

Bacterial Cellulose Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bacterial Cellulose Packaging Market Insights
Asian fermentation capacity is decoupling from legacy cellulose supply chains as dedicated bioreactor facilities scale output for packaging-grade purity. CelluForce leverages its nanocellulose expertise to anchor high-barrier film development for moisture-sensitive goods. Nanollose sustains pilot-scale production in Southeast Asia, competing on feedstock flexibility using agricultural waste streams. Polybion differentiates through molded container geometries that replace expanded polystyrene in protective packaging.
Bacterial cellulose packaging comprises extruded or cast films, sheets, and molded structures derived from Gluconacetobacter xylinus fermentation, typically exhibiting tensile strength of 200-300 MPa and crystallinity exceeding 60% depending on purification protocol, engineered to replace synthetic polymers in oxygen-sensitive and moisture-barrier applications. Films and composite films dominate current output, with composite variants integrating chitosan or alginate layers capturing expanding margin pools in pharmaceutical and electronics protection. Molded containers represent the fastest-growing product type as brand owners seek thermoformed alternatives to petroleum-based rigid packaging for premium cosmetics and luxury goods.
FDA food contact substance notifications and EU REACH compliance frameworks govern migration limits and substance safety for bacterial cellulose materials entering food and cosmetic contact applications, while ISO 17088 biodegradability certification shapes market access for compostable packaging claims. The EU Green Deal's packaging waste reduction targets and emerging state-level extended producer responsibility laws in California and New York will tighten material provenance requirements. Stakeholders must monitor regulatory divergence between jurisdictions on bio-based content verification methods and end-of-life disposal standards.
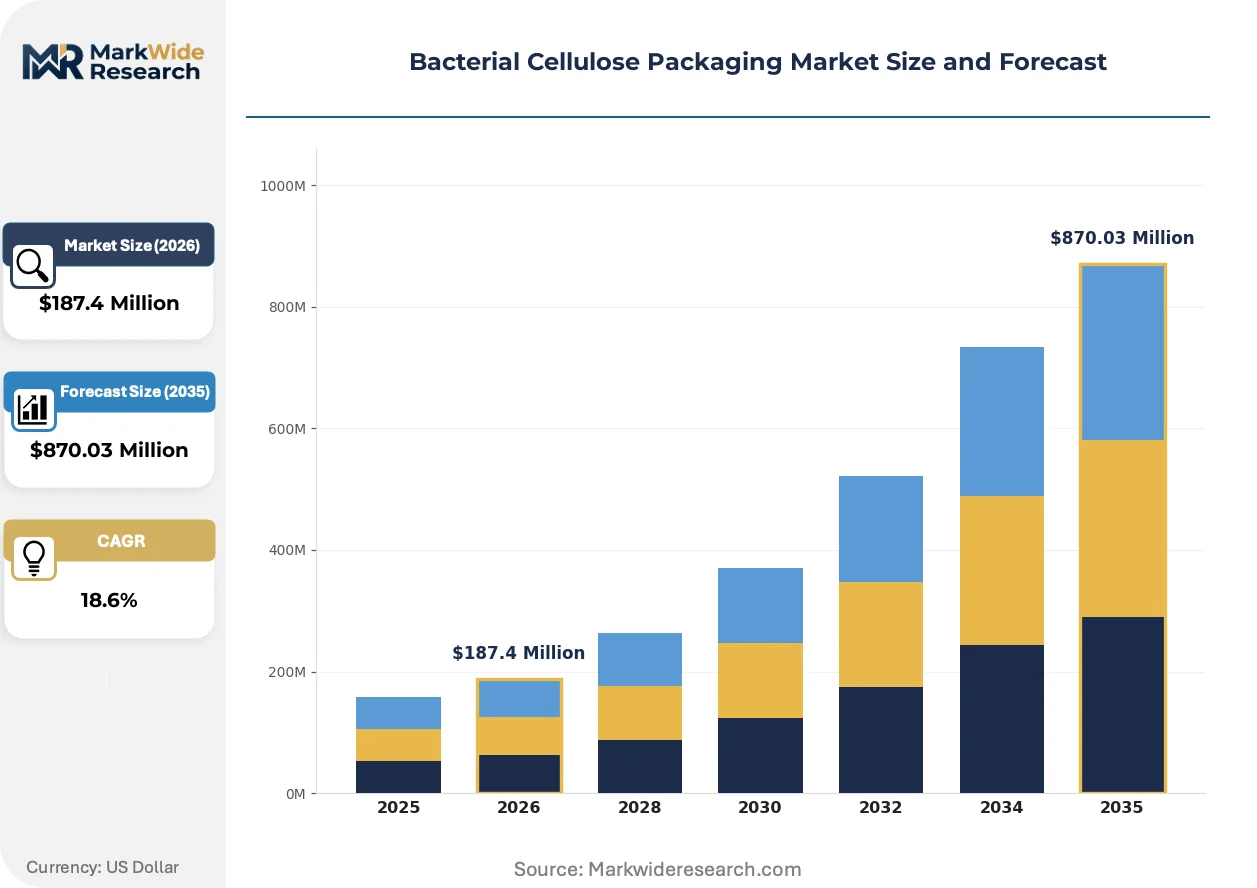
Market Dynamics
Fermentation-to-film manufacturing is compressing lead times for packaging-grade bacterial cellulose, forcing converters to reconfigure supply relationships around continuous-roll bioreactor output rather than batch-processed sheet goods.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Material traceability mandates are accelerating converter migration toward certified bio-based substrates with verifiable chain-of-custody documentation.
- Food & Beverage premium perishables segment:Brand owners in Germany and California are replacing petroleum-derived oxygen barriers with bacterial cellulose films for extended shelf-life applications.
- Continuous-roll fermentation:Bioreactor engineering advances are enabling meter-wide film production that matches thermoplastic throughput rates.
Market Restraints
- Feedstock cost volatility:Agricultural sugar prices swing with climate-induced crop yields, compressing margin predictability for fermentation operators.
- Supply concentration in Southeast Asia:Pilot-scale capacity clusters in Indonesia and Thailand create single-source vulnerability for Western converters.
- Technical limitation in moisture barrier:Unmodified bacterial cellulose exhibits water vapor transmission rates 10-100x higher than synthetic alternatives, requiring costly secondary coating.
Strategic Opportunities
- Underpenetrated US West Coast:California's extended producer responsibility laws and SB 54 implementation timeline create first-mover positioning for compostable packaging certification.
- Technology convergence of bacterial cellulose and nanocellulose:Hybrid barrier films combining fermentation-derived substrates with mechanical fibrillation are opening electronics protection applications.
- Direct-to-brand distribution:Fermentation startups are bypassing traditional converter intermediaries to supply CPG companies with specification-grade rollstock.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial microbiologists with scale-up experience command premium compensation, constraining facility expansion timelines.
- ISO 17088 certification timelines:Compostability validation protocols require 180-day field trials, delaying product launches by 12-18 months.
- Legacy thermoforming equipment incompatibility:Existing toolsets designed for petroleum-based films require retrofitting for bacterial cellulose's distinct rheological properties.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacterial Cellulose Packaging Market Trends and Innovations
Continuous bioreactor engineering is collapsing the cost curve for packaging-grade bacterial cellulose, enabling substitution economics that were structurally impossible under batch fermentation models.
Static culture fermentation with automated harvest systems is decentralizing production geography by eliminating the capital intensity of stirred-tank bioreactors. Mid-sized converters in Poland and Portugal are installing skid-mounted units to serve regional food brands. This distributed model is compressing freight costs and enabling just-in-time inventory for perishable-goods packagers previously dependent on Asian sheet imports.
REACH substance registration requirements for novel bio-based polymers are tightening migration testing protocols for food-contact applications. The European Chemicals Agency's updated guidance demands specific analytical methods for oligomer detection in cellulose-derived films. German and Dutch testing laboratories are expanding capacity to handle pre-submission dossiers, while converters delay product launches pending compliance confirmation.
Brand technical buyers are consolidating supplier relationships around vertically integrated fermentation-to-converter partnerships. Single-source accountability for purity, barrier performance, and compostability documentation is displacing multi-tier procurement. This concentration is most visible in French and Italian cosmetics packaging, where luxury houses specify bacterial cellulose molded containers and reject fragmented supply chains.
Bacterial Cellulose Packaging Market Segmentation
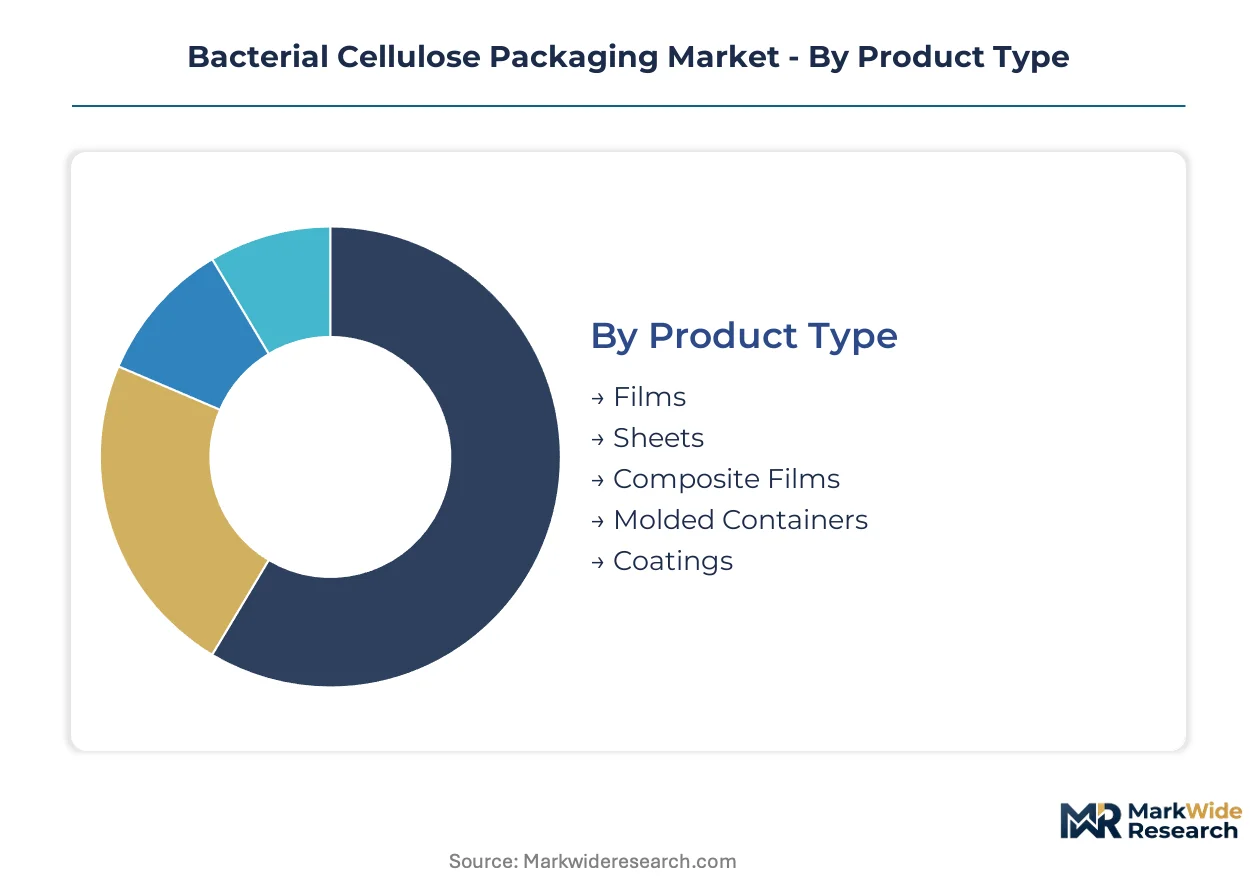
Bacterial cellulose packaging segments diverge sharply on certification burden, with food-contact films requiring FDA notification and EU REACH dossiers while industrial barrier coatings face lighter compliance. Material form and end-use application together determine which regulatory gateways block market entry.
Product Type:
Films and composite variants carry the heaviest certification load, with FDA food contact substance notifications and EU REACH substance registration demanded for migration-compliant barriers. Molded containers and coatings navigate lighter regulatory frameworks but face distinct ISO 17088 compostability validation timelines.
- Films:Cast or extruded bacterial cellulose substrates with tensile strength of 200-300 MPa serve oxygen-sensitive food preservation. German packaging engineers specify these for premium perishables requiring extended shelf-life performance.
- Composite Films:Layered structures integrating chitosan or alginate barriers capture pharmaceutical and electronics protection demand. California's SB 54 implementation timeline accelerates procurement for compostable-certified variants.
- Sheets:Batch-processed substrates for converter thermoforming operations.
- Molded Containers:Rigid geometries replacing expanded polystyrene in protective packaging applications.
- Coatings:Surface-applied bacterial cellulose layers for secondary barrier enhancement.
Leading the category by volume: Films. Growing fastest: Molded Containers.
End Use Industry:
Food & Beverage buyers dominate procurement volumes, yet cosmetics and electronics segments command margin premiums through specialized barrier specifications. Personal care brands in France and Italy consolidate supplier relationships around vertically integrated fermentation-to-converter partnerships.
- Food & Beverages:Oxygen barrier films for premium perishables drive continuous-roll bioreactor investment. California and Germany anchor converter demand for petroleum-derived film substitution.
- Personal Care:Molded container specifications from luxury cosmetics houses in France and Italy demand single-source accountability for purity and compostability documentation.
- Pharmaceuticals:Migration-tested barrier packaging for moisture-sensitive drug products.
- Electronics:Hybrid nanocellulose composite films for component protection.
- Luxury Goods:Rigid molded structures for gift and presentation packaging.
Highest certification intensity: Food & Beverages. Steepest expansion trajectory: Personal Care.
Packaging Type:
Flexible and barrier formats concentrate technical development, with vacuum sealing applications demanding the tightest moisture vapor transmission specifications. Rigid packaging requires thermoforming equipment retrofitting for bacterial cellulose's distinct rheological properties.
- Flexible Packaging:Rollstock and pouch formats for food preservation and cosmetic wrapping. Indonesian and Thai pilot-scale capacity serves Western converter demand despite single-source vulnerability.
- Barrier Packaging:Oxygen and moisture-resistant structures requiring secondary coating to match synthetic alternatives. REACH substance registration protocols for novel bio-based polymers tighten migration testing requirements.
- Rigid Packaging:Thermoformed containers and structural elements.
- Biodegradable Packs:ISO 17088-certified compostable formats.
- Vacuum Sealing:High-performance barrier structures for extended shelf-life.
Technology investment concentrates: Barrier Packaging. Fastest share gain: Biodegradable Packs.
Application:
Food preservation anchors volume demand, while medical device packaging imposes the most stringent purity and migration compliance. Electronic components protection opens through hybrid nanocellulose convergence.
- Food Preservation:Oxygen barrier films for extended shelf-life perishables. EU Packaging and Packaging Waste Regulation traceability mandates accelerate certified bio-based substrate migration.
- Medical Device Packaging:Sterile barrier systems with migration-tested cellulose substrates. ECHA updated guidance demands specific analytical methods for oligomer detection in cellulose-derived films.
- Cosmetic Wrapping:Premium presentation films for beauty and personal care.
- Electronic Components Protection:Moisture and static-resistant packaging for sensitive devices.
- Gift Packaging:Luxury presentation and retail display applications.
Volume leadership: Food Preservation. Climbing the fastest: Electronic Components Protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coconut water and agricultural sugar feedstocks concentrate fermentation capacity in Southeast Asian coastal zones, while European converter demand pulls purified cellulose toward German and French packaging clusters. North American brand procurement is consolidating around California's extended producer responsibility mandates.
Germany
Food & Beverage premium perishables and cosmetics packaging engineers drive bacterial cellulose film specification. EU REACH substance registration protocols tighten migration testing requirements for cellulose-derived barriers. Stuttgart and Hamburg host converter-fermentation startup partnerships on continuous-roll bioreactor engineering.
United States
California's SB 54 implementation timeline accelerates compostable packaging procurement from CPG brands. EPA and state-level extended producer responsibility laws tighten material provenance documentation requirements. Los Angeles and San Francisco Bay Area converters pilot specification-grade rollstock for perishable goods.
Indonesia
Agricultural waste stream availability and coconut plantation proximity anchor pilot-scale fermentation capacity for Western converter supply. National industrial policy supports bio-based material commercialization through investment facilitation. Javanese bioreactor clusters serve European and North American packaging demand despite freight distance.
France
Luxury cosmetics houses specify bacterial cellulose molded containers with single-source accountability demands. EU Packaging and Packaging Waste Regulation traceability mandates push converters toward certified bio-based substrates. Paris-region packaging designers collaborate with fermentation operators on rigid geometry development.
Thailand
Tapioca-derived sugar feedstock abundance supports fermentation scale-up for packaging-grade purity output. National bioplastics promotion programs align with EU import compliance frameworks. Bangkok-centered pilot facilities supply sheet goods to German and US thermoforming converters.
Bacterial Cellulose Packaging Market Competitive Landscape
Global majors compete with regional champions across fermentation capacity and converter relationships, producing a tiered structure where scale-driven bioreactor operators coexist with specialized molded container fabricators. Three archetypes dominate: vertically integrated fermentation-to-film producers, pure-play bioreactor operators supplying converter intermediaries, and application-specific molded geometry specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure feedstock offtake and brand technical buyer relationships.
Within the fermentation-to-film tier, CelluForce and Nanollose occupy distinct positions. CelluForce leverages nanocellulose expertise to anchor high-barrier development for moisture-sensitive applications. Nanollose sustains pilot-scale Southeast Asian production competing on agricultural waste stream flexibility. Polybion represents the molded container archetype, differentiating through rigid geometries that target expanded polystyrene substitution in protective packaging applications.
| Leading Market Players |
|---|
| CelluForce |
| Nanollose |
| Polybion |
| Modern Meadow |
| Ecovative Design |
| Bioweg |
| ScobyTec |
| Fiberlean Technologies |
| Borregaard |
| Others |
Pricing and Supply Chain Analysis
California's SB 54 extended producer responsibility mandate gates qualified supply for converters seeking premium-tier pricing access, as compostability certification becomes a non-negotiable entry ticket for brand technical buyers.
Pricing Analysis
Warranty and compliance documentation bundling separates certified bio-based substrates from commodity-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 17088 certification status, feedstock provenance, and barrier performance specifications. Cost compression in standard-grade sheet goods is intensifying because Indonesian pilot-scale capacity expansion outpaces Western converter demand growth. Small-to-mid-sized food brands exhibit highest price sensitivity, while luxury cosmetics houses in France and Italy demonstrate lowest sensitivity due to single-source accountability requirements.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Thai fermentation clusters serving Western converter demand. Raw material dependencies draw from coconut water, tapioca-derived sugars, and agricultural waste streams. Tariff exposure on purified cellulose imports into the EU and North America creates margin unpredictability for bioreactor operators. Distribution runs through converter intermediaries in Germany and California, though direct-to-brand rollstock supply is displacing traditional channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive fermentation capacity is the defining competitive race, as converters seek upstream control over purity specifications and compostability documentation.
For Market Incumbents: To counter direct-to-brand disintermediation by fermentation startups, secure exclusive offtake agreements with Southeast Asian bioreactor operators and invest in ISO 17088 pre-certification capacity to compress product launch timelines. Channel control through specification-grade rollstock partnerships with California CPG brands provides defensive positioning against emerging converter-less supply models.
For New Entrants and Emerging Players: Launch via skid-mounted static culture bioreactor distribution to serve regional food brands in Poland and Portugal with just-in-time inventory models. The underpenetrated US West Coast personal care segment offers the most penetrable white space, with California's SB 54 implementation timeline accelerating compostable packaging procurement from technical buyers seeking single-source accountability.
For Investors and Strategic Acquirers: FDA food contact substance notification clearance for novel bacterial cellulose composites is the leading indicator that fermentation-to-film operators have crossed the regulatory moat toward scalable revenue. Vertically integrated players with captive bioreactor capacity and converter relationships represent the priority acquisition archetype across the five-to-ten year viability window.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Roll Bioreactor Scale-Up | Meter-wide film output matches thermoplastic throughput rates for California perishables brands. |
| Backward Integration into Feedstock Supply | Captive agricultural waste stream contracts insulate margin predictability from sugar price volatility. |
| ISO 17088 Pre-Certification Investment | Early compostability validation compresses product launch timelines by 12-18 months for German converters. |
| Direct-to-Brand Rollstock Distribution | Bypassing converter intermediaries captures specification-grade relationships with French luxury cosmetics houses. |
| Hybrid Nanocellulose Composite Development | Convergence with mechanical fibrillation opens electronics protection applications for moisture-sensitive components. |
Research Methodology
Multi-period observation of bioreactor capacity announcements, regulatory filing timelines, and brand procurement patterns anchored the trend analysis, supplemented by interviews with fermentation process engineers, packaging converter procurement leads, EU regulatory affairs specialists, and CPG sustainability directors. Secondary validation drew from ECHA guidance documents, FDA food contact substance notification databases, EU Packaging and Packaging Waste Regulation implementation trackers, and trade flow data for purified cellulose imports. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Input-output matrices modeled capacity-expansion trajectories, feedstock cost sensitivities, and certification timeline probabilities across product type, end-use industry, packaging format, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate distributions weighted by named demand concentration in Germany, California, France, and Indonesia. Industry-specific forecast inputs incorporated continuous-roll bioreactor engineering maturity curves and REACH substance registration backlog estimates.
Feedstock price volatility, regulatory divergence on bio-based content verification methods, and bioprocess engineering talent scarcity are the dominant revision risks that could compress or extend projected adoption curves. Forecasts reflect assumptions about certification timeline standardization and converter equipment retrofitting rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.