
 Molded Fiber Wine Packs Market | 2026-2036
Molded Fiber Wine Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Fiber Wine Packs Market Foresight
E-commerce fulfillment is broadening the end-use vertical mix for molded fiber wine packs as direct-to-consumer shipping volumes reshape protective packaging requirements. Huhtamaki Group leverages its European manufacturing footprint to supply major wine exporters with certified compostable formats. Heritage Pioneer Corporate Group anchors North American production capacity through integrated pulp molding operations. Brodrene Hartmann A/S differentiates via thermoformed fiber expertise originally developed for egg packaging.
Molded fiber wine packs are engineered pulp-formed containers produced through vacuum-forming or press-molding processes using recycled paperboard or agricultural residues, typically achieving wall thicknesses of 2-5mm to cushion glass bottles against impact and vibration during transit. Their primary commercial purpose is replacing petroleum-based foam inserts with recyclable, biodegradable alternatives that satisfy retailer sustainability mandates. The material dimension shows recycled paper pulp occupying the dominant share due to established collection infrastructure and lower fiber cost, while straw pulp variants are gaining traction among producers targeting agricultural waste valorization claims. Custom designs command premium positioning as wineries seek branded unboxing experiences, though four-bottle configurations remain the workhorse format for club shipments.
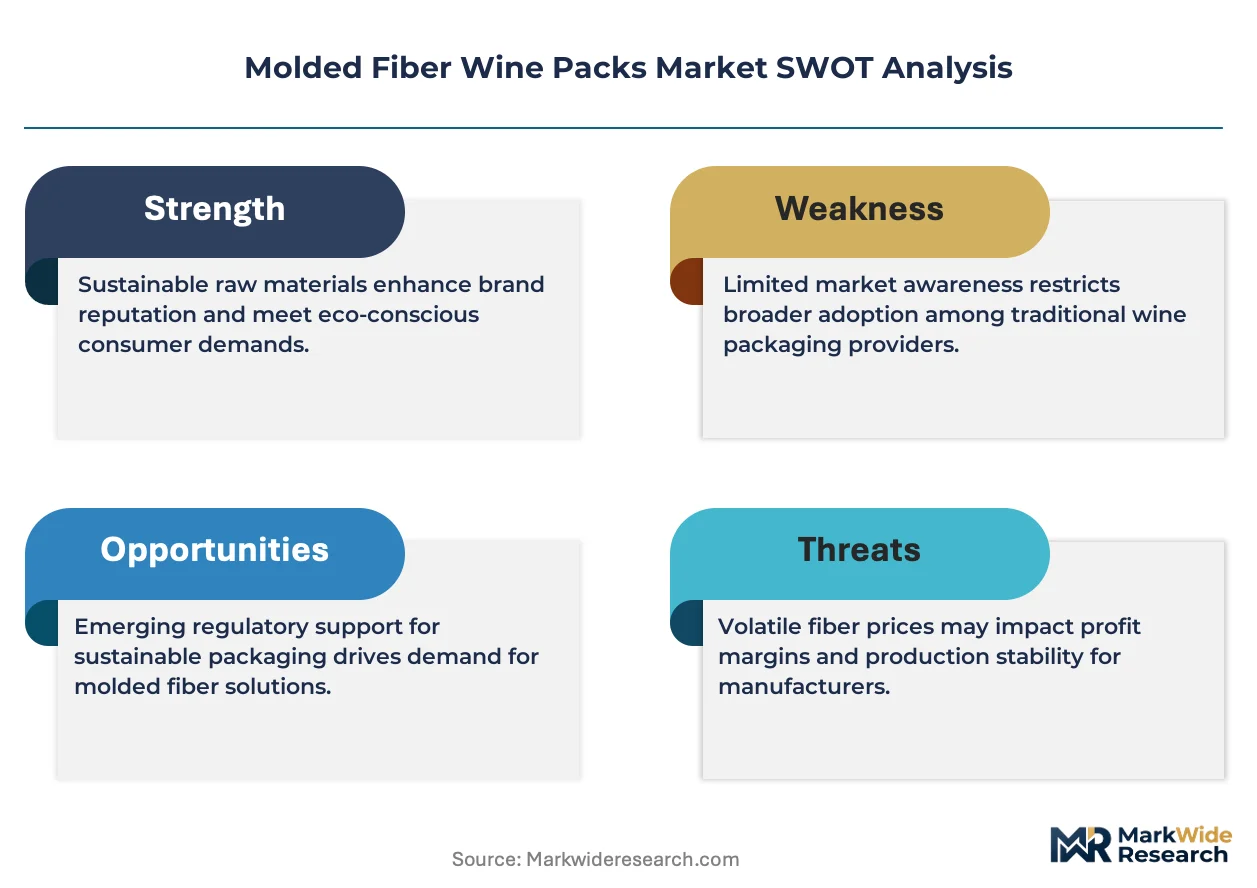
The US EPA guides landfill diversion targets that indirectly shape state-level packaging procurement rules, while EU REACH and F-Gas Regulation frameworks restrict persistent chemical use in competing foam alternatives. California's SB 54 implementation timeline creates compliance-driven replacement demand across West Coast wine distribution. Stakeholders must monitor evolving extended producer responsibility schemes to anticipate which fiber certification standards will become mandatory for market access.
Market Dynamics
Direct-to-consumer wine club fulfillment is compressing order batch sizes and forcing protective packaging converters toward rapid-changeover production lines. California's SB 54 plastic reduction mandates are accelerating substitution timelines for petroleum-based foam alternatives.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds for packaging sold in member states are creating compliance-driven procurement of molded fiber formats among wine exporters targeting European retail channels.
- E-commerce fulfillment expansion:Winery direct-to-consumer shipping volumes are reshaping protective packaging specifications toward lighter, recyclable formats that reduce dimensional weight penalties.
- Agricultural residue valorization:Straw pulp variants are gaining commercial traction among producers seeking circular economy claims and supply chain differentiation in premium market positioning.
Market Restraints
- Recycled paper pulp cost volatility:Fiber feedstock prices fluctuate with municipal collection program economics and export demand from Asian packaging converters.
- Molded fiber equipment concentration:High-capacity thermoforming press manufacturing concentrates among German and Italian machinery suppliers, creating lead time bottlenecks for capacity expansion.
- Performance gap in extreme cold chain:Cellulose fiber moisture absorption limits protective performance in frozen transit conditions, ceding share to engineered foam in certain export corridors.
Strategic Opportunities
- Pacific Northwest craft producer clusters:Oregon and Washington winery consolidation is creating regional scale sufficient to justify dedicated molded fiber production facilities.
- Subscription wine curation services:Curated monthly shipment models are standardizing pack configurations and enabling longer production runs for contract molders.
- California SB 54 implementation timeline:The phased reduction schedule for single-use plastics is generating predictable replacement demand with defined compliance deadlines.
Industry Challenges
- Composting infrastructure geographic mismatch:Industrial composting facility availability lags behind certified packaging supply in key wine-producing counties, creating consumer confusion and brand risk.
- Legacy ERP integration:Winery order management systems require custom API development to synchronize variable pack configurations with automated fulfillment lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Fiber Wine Packs Market |
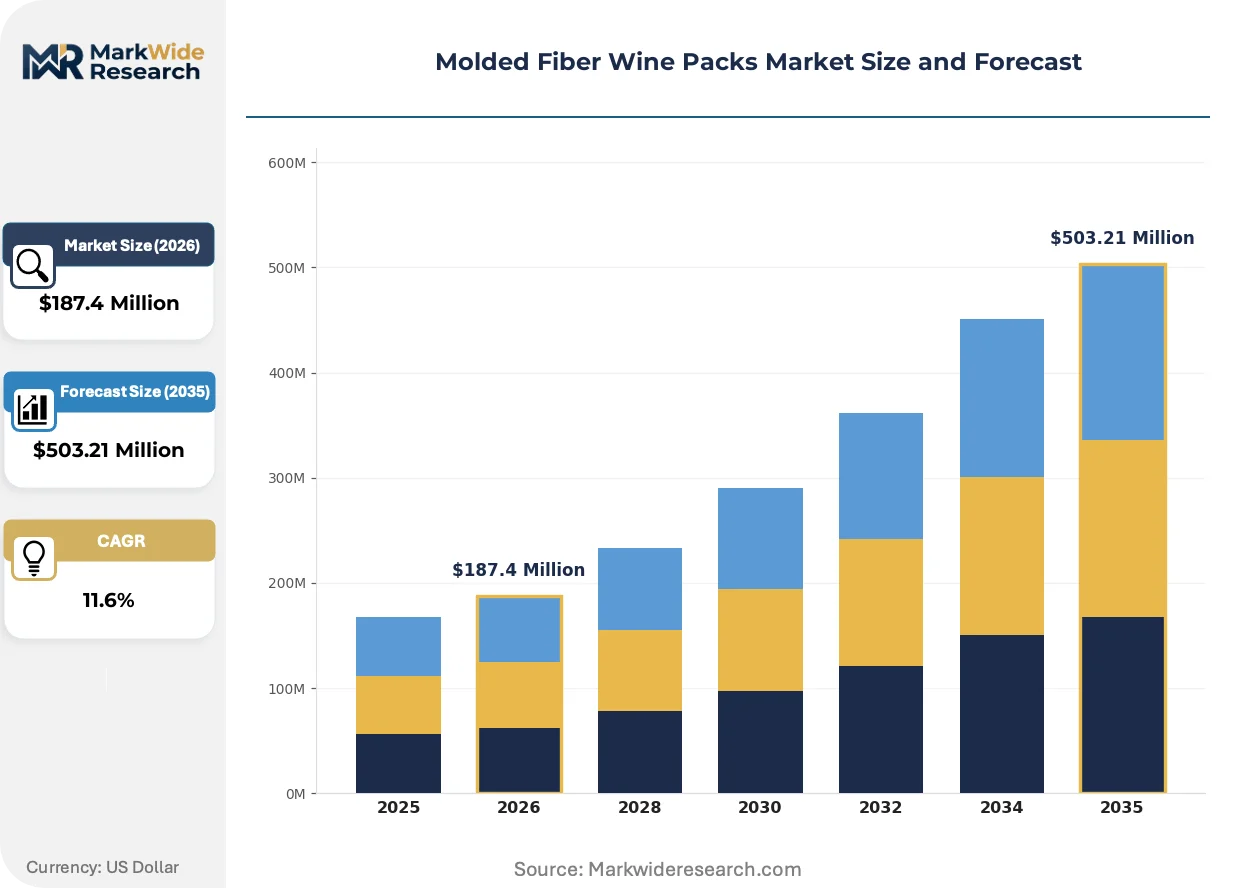
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Bottle, Two Bottle, Four Bottle, Custom Designs Application: Retail, E-commerce, Events, Corporate Gifting Material: Recycled Paper, Wood Pulp, Straw Pulp, Biodegradable Material Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Huhtamaki Group, Heritage Pioneer Corporate Group, UFP Technologies, Inc., ALLPACK Solutions Inc., Western Pulp Products Company, KEYES Packaging Group, Polar Tech Industries, Inc., Sonoco Products Company, Brodrene Hartmann A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Fiber Wine Packs Market Shifts & Advancements
Robotic fiber handling and inline quality inspection are compressing changeover times and enabling economically viable production of short-run custom designs. Regulatory pressure on petroleum-based alternatives is accelerating material science investment in fiber formulations.
Robotic pick-and-place systems integrated with vacuum-forming lines are automating post-mold handling and trimming operations. Mid-sized contract packagers in California's Central Valley are deploying these systems to serve fragmented winery demand with lot sizes below five thousand units. This automation is compressing minimum viable order quantities and enabling economically feasible production of branded, design-variant packs for small-batch producers.
REACH restrictions on persistent organic pollutants in competing expanded polystyrene formulations are tightening material compliance requirements for wine shippers targeting EU retail channels. The F-Gas Regulation's phase-down of hydrofluorocarbon blowing agents is raising production costs for insulated foam alternatives. Premium Bordeaux and Burgundy exporters are responding by specifying molded fiber formats certified under OK Compost INDUSTRIAL standards.
Subscription-based procurement of protective packaging is displacing spot-market purchasing among high-volume wine clubs. Napa Valley and Sonoma County fulfillment operations are consolidating supplier relationships into annual contracts with volume commitments and design refresh schedules. This shift is most visible among direct-to-consumer programs shipping four to six times annually, where predictable pack demand justifies collaborative forecasting with molded fiber converters.
Molded Fiber Wine Packs Market Segmentation
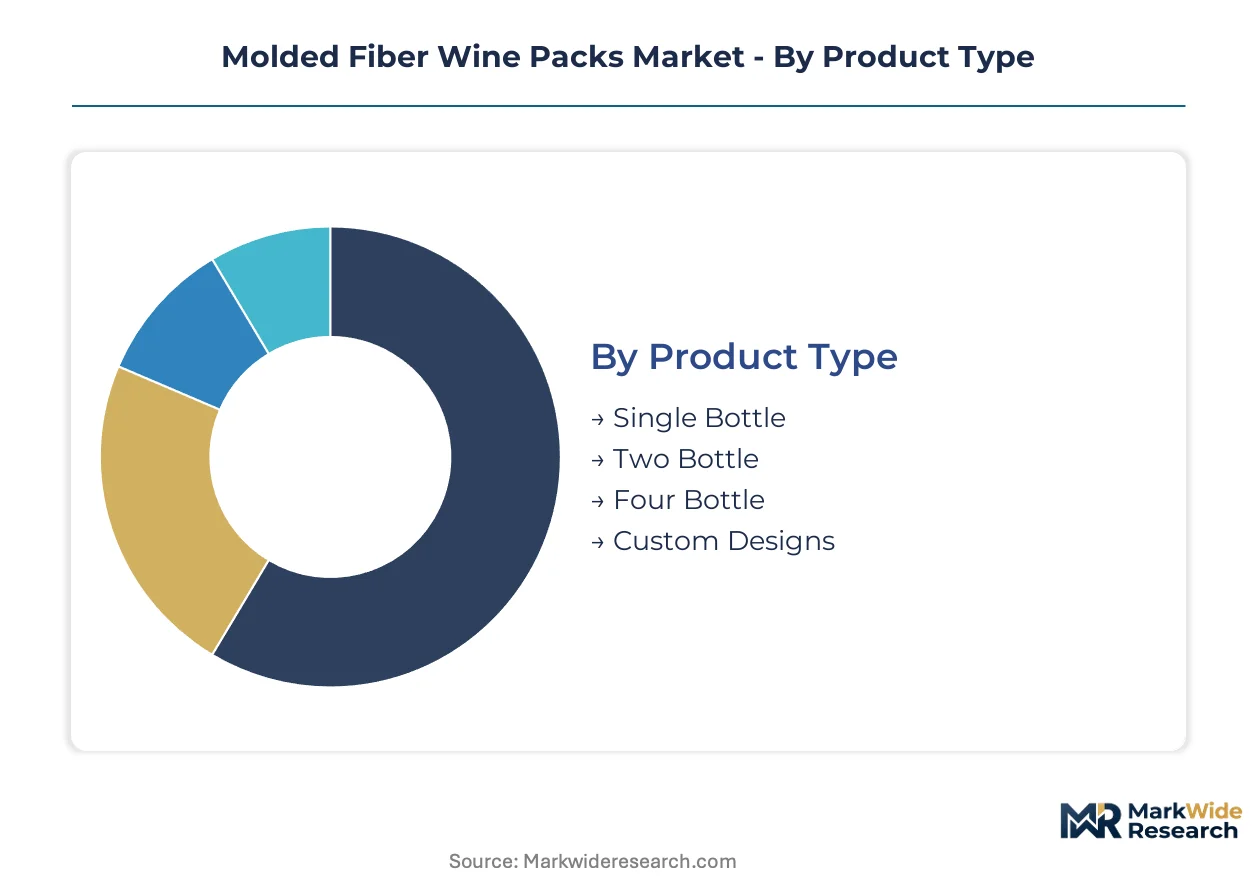
Molded fiber wine pack specifications diverge sharply between club shipment economics and retail shelf presentation. Each segmentation dimension reflects distinct procurement priorities across winery fulfillment operations.
Product Type:
Wineries select pack configurations based on shipment frequency and bottle count economics.
- Four Bottle:Vacuum-formed pulp containers with 3-4mm wall thickness dominate direct-to-consumer subscription programs. California's Napa Valley and Sonoma County fulfillment centers specify this format for quarterly club shipments due to dimensional weight optimization.
- Custom Designs:Press-molded variants with embossed branding and color-dyed fiber serve premium unboxing experiences. Oregon's Willamette Valley craft producers commission short-run designs for limited releases.
- Single Bottle:Compact pulp sleeves protect high-value individual shipments.
- Two Bottle:Paired configurations balance protection density with shipping cube efficiency.
Volume sits with four-bottle formats; growth tilts toward custom designs.
Application:
End-use context determines fiber grade specifications and certification requirements.
- E-commerce:Direct-to-consumer shipping mandates moisture-resistant fiber formulations and drop-test certification. Washington State's Walla Walla AVA producers prioritize this segment for club fulfillment expansion.
- Retail:Shelf-ready packs require printed fiber surfaces and stacking strength for palletized distribution. Supermarket wine buyers specify OK Compost INDUSTRIAL certification for private label programs.
- Events:Temporary protection for tasting and festival distribution.
- Corporate Gifting:Branded presentation packs for B2B wine programs.
Procurement concentrates in e-commerce; retail compliance requirements are stiffening fastest.
Material:
Feedstock selection balances cost position against sustainability claim defensibility.
- Recycled Paper:Post-consumer fiber with established municipal collection infrastructure commands the dominant procurement share. California SB 54 implementation timelines accelerate substitution from petroleum-based alternatives.
- Straw Pulp:Agricultural residue valorization supports circular economy positioning. Pacific Northwest producers leverage regional wheat straw supply chains for differentiation.
- Wood Pulp:Virgin fiber variants for premium moisture resistance.
- Biodegradable Material:Emerging formulations with home composting certification.
Recycled paper anchors current volume; straw pulp is climbing the fastest.
Distribution Channel:
Channel structure dictates order batch sizes and inventory velocity requirements.
- Direct Sales:Winery-controlled fulfillment enables collaborative forecasting with molded fiber converters. Napa Valley operations consolidate annual contracts with volume commitments and design refresh schedules.
- Online Retailers:Third-party wine marketplaces standardize pack specifications across multiple producer inventories.
- Specialty Stores:Independent wine shops require flexible minimum order quantities.
- Supermarkets:Mass retail procurement mandates high-volume production runs.
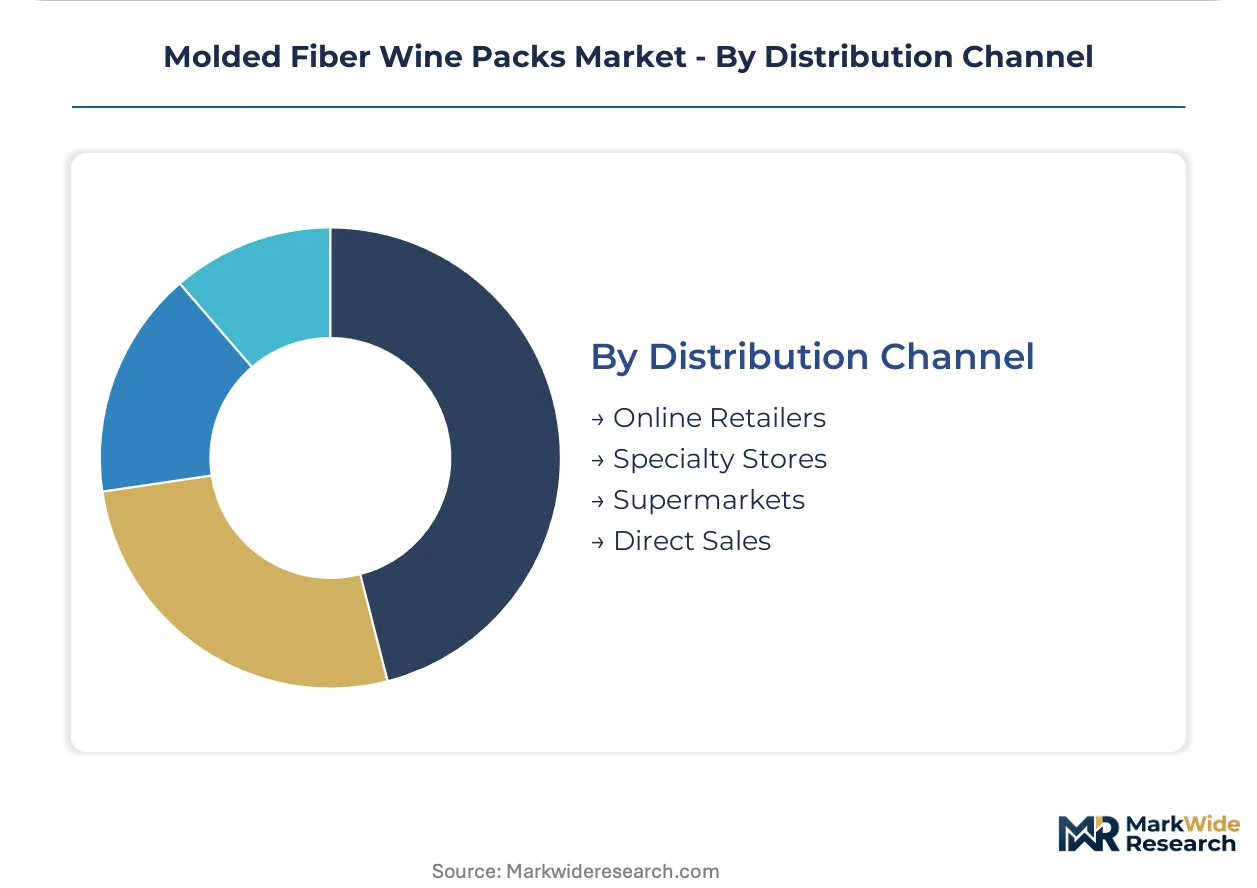
Direct sales capture margin concentration; online retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Enterprise Zone tax credits and Oregon's rural opportunity zones concentrate molded fiber manufacturing capacity along the Pacific Coast wine corridor. These incentive structures offset capital equipment costs for thermoforming press installations serving fragmented winery demand.
United States
California's SB 54 plastic reduction mandates generate compliance-driven procurement from Napa Valley and Sonoma County fulfillment centers. The EPA guides landfill diversion targets that shape state-level packaging procurement rules. Pacific Northwest craft producer clusters in Oregon's Willamette Valley and Washington's Walla Walla AVA justify dedicated regional production facilities.
France
Bordeaux and Burgundy exporters specify OK Compost INDUSTRIAL certified formats for EU retail channel access. The F-Gas Regulation phase-down of hydrofluorocarbon blowing agents raises production costs for competing foam alternatives. Champagne houses commission custom press-molded designs for premium unboxing experiences in direct-to-consumer programs.
Italy
Tuscany and Piedmont wineries adopt straw pulp variants leveraging regional wheat straw supply chains for circular economy positioning. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds for packaging sold in member states. Prosecco producers in Veneto consolidate supplier relationships into annual contracts with volume commitments.
Germany
German machinery suppliers concentrate high-capacity thermoforming press manufacturing, creating lead time bottlenecks for capacity expansion across Europe. REACH restrictions on persistent organic pollutants in expanded polystyrene formulations tighten material compliance requirements. Baden-Württemberg packaging converters serve Rhine Valley wine exporters with certified compostable formats.
Australia
Barossa Valley and Margaret River producers prioritize moisture-resistant fiber formulations for export corridor transit. The country's national environmental regulator guides extended producer responsibility schemes anticipated to mandate fiber certification standards. New South Wales and Victoria winery consolidation creates regional scale sufficient to justify dedicated molded fiber production facilities.
Molded Fiber Wine Packs Market Competitive Landscape
Top-tier vendors anchor European and North American production capacity, while mid-sized contract packagers compress minimum viable order quantities through automation investments. The vendor base spans integrated pulp molding operations, diversified packaging conglomerates, and specialized thermoformed fiber specialists. Three archetypes dominate: European exporters with certified compostable formats, North American integrated producers with captive pulp supply, and machinery-originated specialists leveraging thermoforming expertise. Competitive moves concentrate on rapid-changeover production line deployment and collaborative forecasting partnerships with high-volume wine clubs.
Among diversified packaging conglomerates, Huhtamaki Group and Sonoco Products Company represent scale-driven archetypes with broad protective packaging portfolios. Brodrene Hartmann A/S occupies a specialist position derived from thermoformed fiber expertise. Heritage Pioneer Corporate Group exemplifies North American integrated production through pulp molding operations. These three anchors illustrate the competitive spectrum from global supply chain reach to regional craft producer service models.
| Leading Market Players |
|---|
| Huhtamaki Group |
| Heritage Pioneer Corporate Group |
| UFP Technologies, Inc. |
| ALLPACK Solutions Inc. |
| Western Pulp Products Company |
| KEYES Packaging Group |
| Polar Tech Industries, Inc. |
| Sonoco Products Company |
| Brodrene Hartmann A/S |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters with multi-generational California Central Valley roots anchor regional supply discipline, translating captive pulp sourcing into pricing stability that resists the volatility squeezing spot-market dependent competitors.
Pricing Analysis
Premium pricing attaches to short lead-time orders from German and Italian thermoforming press manufacturers, while spot inventory of standard four-bottle configurations trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels reflects OK Compost INDUSTRIAL certification grade and volume scale commitments. Cost compression in custom design tiers is intensifying because robotic automation investments by mid-sized contract packagers compress minimum viable order quantities. Small-batch Willamette Valley craft producers exhibit highest price sensitivity; Napa Valley wine clubs with annual volume contracts show least.
Supply Chain Analysis
Freight cost exposure concentrates in trans-Pacific container lanes serving Asian recycled fiber export demand and European machinery import corridors. Supply concentrates in Germany, Italy, and the United States for high-capacity thermoforming press manufacturing; recycled paper pulp sourcing draws from established municipal collection infrastructure across North America and Western Europe. Raw material dependencies rest on post-consumer fiber bale availability, agricultural residue collection seasonality, and thermoforming mold steel quality. Single-source vulnerability concentrates in German machinery suppliers creating lead time bottlenecks. Distribution runs through winery direct sales channels and third-party online retailer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race where backward integration into captive pulp molding operations offers the decisive cost-position lever against feedstock volatility.
For Market Incumbents: Lock in multi-year straw pulp supply agreements with Pacific Northwest agricultural cooperatives before regional wheat straw demand intensifies. Add thermoforming capacity in Oregon's rural opportunity zones to defend against emerging craft-producer-focused entrants. Prioritize OK Compost INDUSTRIAL certification investment to maintain EU retail channel access under tightening ECHA frameworks. For New Entrants and Emerging Players: Enter via subscription wine curation services standardizing pack configurations, the most penetrable segment for contract molding relationships. Target Washington State's Walla Walla AVA for regional facility justification as winery consolidation creates sufficient scale. Pursue collaborative forecasting partnerships with high-volume clubs as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized California Central Valley contract packagers with robotic automation deployments already amortized. Long-term viability hinges on five-to-ten year winery direct-to-consumer shipping growth trajectories. Watch California SB 54 implementation compliance deadlines as the inflection signal for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Molding | Captive fiber supply insulates margin position against recycled paper cost volatility. |
| Robotic Automation Deployment | Compresses minimum viable order quantities for fragmented Willamette Valley craft producer demand. |
| OK Compost INDUSTRIAL Certification | Unlocks EU retail channel access for Bordeaux and Burgundy exporter specifications. |
| Collaborative Forecasting Partnerships | Annual volume commitments with Napa Valley wine clubs stabilize production line utilization. |
| Regional Capacity Expansion | Oregon rural opportunity zone installations capture Pacific Northwest craft producer cluster growth. |
Research Methodology
Multi-period observation of winery direct-to-consumer shipping volumes and thermoforming press installation backlogs anchored the trend analysis, supplemented by interviews with packaging procurement managers at California fulfillment centers, Oregon craft producer operations directors, German machinery supplier sales engineers, and EU regulatory compliance officers. Secondary validation drew from EPA landfill diversion reports, EU Packaging and Packaging Waste Regulation implementation timelines, California SB 54 compliance schedules, and trade data on recycled fiber bale pricing. Bottom-up winery shipment modeling and top-down packaging converter capacity estimates were triangulated.
Input-output matrices mapped bottle count configurations against fiber grade specifications and distribution channel structures across the analysis window. Segmentation dimensions modeled include product type, application context, material feedstock, and procurement channel. CAGRs were derived from shipment volume trajectories and replacement demand schedules under regulatory compliance timelines. Industry-specific forecast inputs incorporated California SB 54 phased reduction deadlines and EU REACH restrictions on competing foam alternatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme fiber feedstock price volatility or accelerated composting infrastructure deployment. Forecasts reflect assumptions about regulatory implementation pacing and winery consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
Jumbo Kraft Tubes Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Corrugated Fiberboard Market
Fiber-Based Packaging
North America Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Europe Molded Fiber Packaging Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Global Molded Fiber Bowls Market
Fiber-Based Packaging
Molded Fiber Containers Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Bacterial Cellulose Packaging Market
Fiber-Based Packaging
Fiber Bale Packaging Film Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Fibreglass Trays Market
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Fiberboard Packaging Market