
 Corrugated Fiberboard Market | 2026-2036
Corrugated Fiberboard Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Fiberboard Market Outlook
North American containerboard production is shifting toward recycled-content capacity. International Paper leverages integrated pulp-to-box operations across the southeastern United States. Smurfit Kappa anchors European demand through its pan-regional recycling and mill network. WestRock competes on specialty packaging grades for regulated end uses.
Corrugated fiberboard consists of fluted paperboard sheets laminated between flat linerboards, typically manufactured with basis weights from 125 to 350 grams per square meter and burst strengths exceeding 200 pounds per square inch for industrial grades. Its primary purpose is protective packaging for transport-stressed goods across supply chain nodes. Single wall products dominate volume shipments in consumer-facing e-commerce, while double wall configurations capture margin pools in heavy appliance and electronics logistics. Recycled Kraft material grade sustains cost leadership in price-sensitive Asian markets, and coated grades differentiate output for moisture-sensitive pharmaceutical applications.
The EPA guides recycled content standards in the United States, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility across member states. India's BIS enforces grammage and burst strength specifications for domestic transport packaging. Stakeholders must monitor how fragmented national recycling infrastructure investments reshape regional cost competitiveness and compliance timelines.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery cycles, forcing corrugated converters to locate production capacity within 150 kilometers of metropolitan demand clusters. This geographic reconfiguration is redrawing competitive boundaries around last-mile logistics infrastructure rather than traditional mill-to-market radius economics.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating closed-loop recycling investments across member states. Brand owners now specify minimum recycled content thresholds in procurement contracts.
- Food and beverage cold chain expansion:Temperature-sensitive e-commerce grocery delivery is driving demand for insulated corrugated solutions with integrated thermal liners. Last-mile refrigeration infrastructure gaps create packaging-dependent solutions.
- India's BIS grammage enforcement:Standardized burst strength specifications are displacing informal board suppliers in domestic transport packaging. Formal sector capacity is capturing share from unorganized producers.
Market Restraints
- Old corrugated container (OCC) price volatility:Recycled fiber input costs swing with Chinese import policy fluctuations. Mill margins compress during OCC shortage periods without corresponding box price recovery.
- Containerboard capacity concentration:Southeast United States mill clusters control disproportionate North American linerboard supply. Hurricane corridor exposure creates systemic supply disruption risk.
- Plastic corrugated substitution in reusable applications:Polypropylene twin-wall sheet captures multi-trip logistics loops in automotive component pooling. Fiber-based solutions face durability limitations in closed-loop cycles.
Strategic Opportunities
- Brazil's retail infrastructure modernization:Supermarket and hypermarket expansion in secondary cities is creating corrugated display packaging demand. Point-of-sale ready cases command premium pricing over standard RSC formats.
- Digital printing convergence with short-run corrugating:Direct-to-board inkjet is enabling lot-size-one customization for promotional campaigns. Brand marketing budgets are shifting toward personalized unboxing experiences.
- India's PLI scheme for packaging machinery:Domestic equipment manufacturing incentives are reducing converter capex dependence on European and Japanese suppliers. Local technical service capabilities are improving uptime guarantees.
Industry Challenges
- Skilled corrugator operator scarcity:Automated flute profile changeover systems require mechatronics competencies that vocational training programs have not scaled. Downtime from setup errors erodes short-run profitability.
- FEFCO code standardization delays:Regional variations in box style nomenclature complicate cross-border specification communication. Engineering teams waste cycles reconciling incompatible design conventions.
- Legacy ERP integration with Industry 4.0 sensors:Real-time moisture and bond strength monitoring generates data streams that on-premise systems cannot ingest. Cloud migration timelines extend beyond payback period assumptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Fiberboard Market |
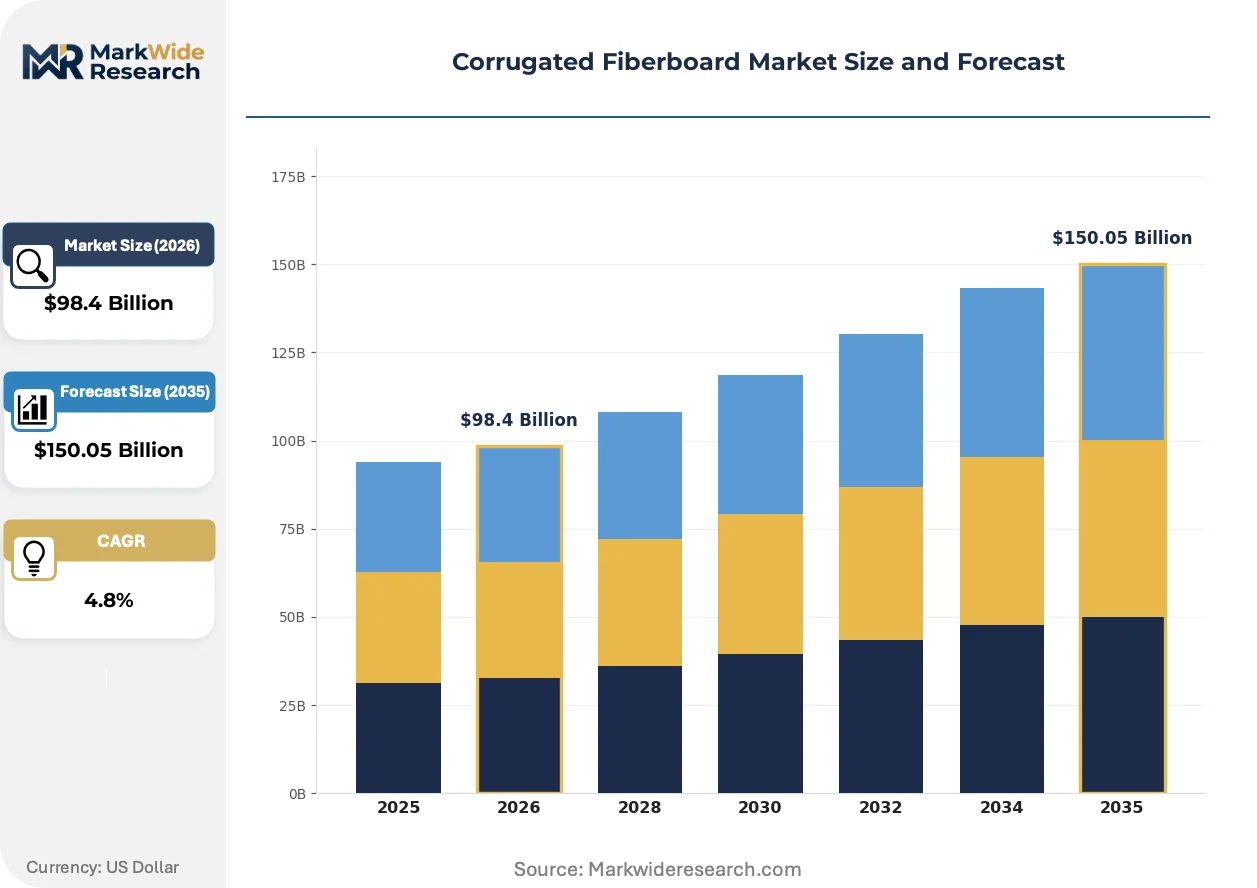
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $150.05 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Heavy Duty, Microflute Material Grade: Virgin Kraft, Recycled Kraft, Semi-Chemical, Testliner, Coated End Use Industry: Consumer Electronics, Pharmaceuticals, Food & Beverages, Personal Care, Home Appliances Distribution Channel: Wholesale Distributors, Direct Sales, E-Commerce Platforms, Retail Outlets |
| Companies Covered | International Paper, Smurfit Kappa, WestRock, DS Smith, Mondi Group, Packaging Corporation of America, Rengo Co., Ltd., Georgia-Pacific, Nine Dragons Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Fiberboard Market Strategic Shifts
Lightweighting through micro-flute geometries is redefining strength-to-weight ratios across e-commerce and retail-ready segments. Material science advances are enabling gram-for-gram performance substitution that protects margins against fiber cost inflation.
Micro-flute E and F profiles are overtaking traditional B-flute in consumer electronics and cosmetics shipping. Amazon and specialty beauty brands specify 1.2mm flute heights for dimensional weight optimization. Corrugated board is displacing folding carton in premium unboxing experiences previously reserved for rigid paperboard.
The EU Green Deal's packaging recyclability targets are mandating mono-material construction and eliminating laminated barrier films. Brand owners are redesigning moisture-sensitive product lines around recyclable corrugated with water-based coatings. Pharmaceutical cold chain applications in Germany and France are piloting bio-based alternatives to polyethylene laminated chill packs.
Direct-to-consumer subscription models are fragmenting order sizes and compressing production runs. Corrugated converters are installing zero-make-ready folder-gluers to handle SKU proliferation. Food and beverage verticals in India and Brazil show the steepest run-length compression as meal-kit services proliferate.
Corrugated Fiberboard Market Segmentation
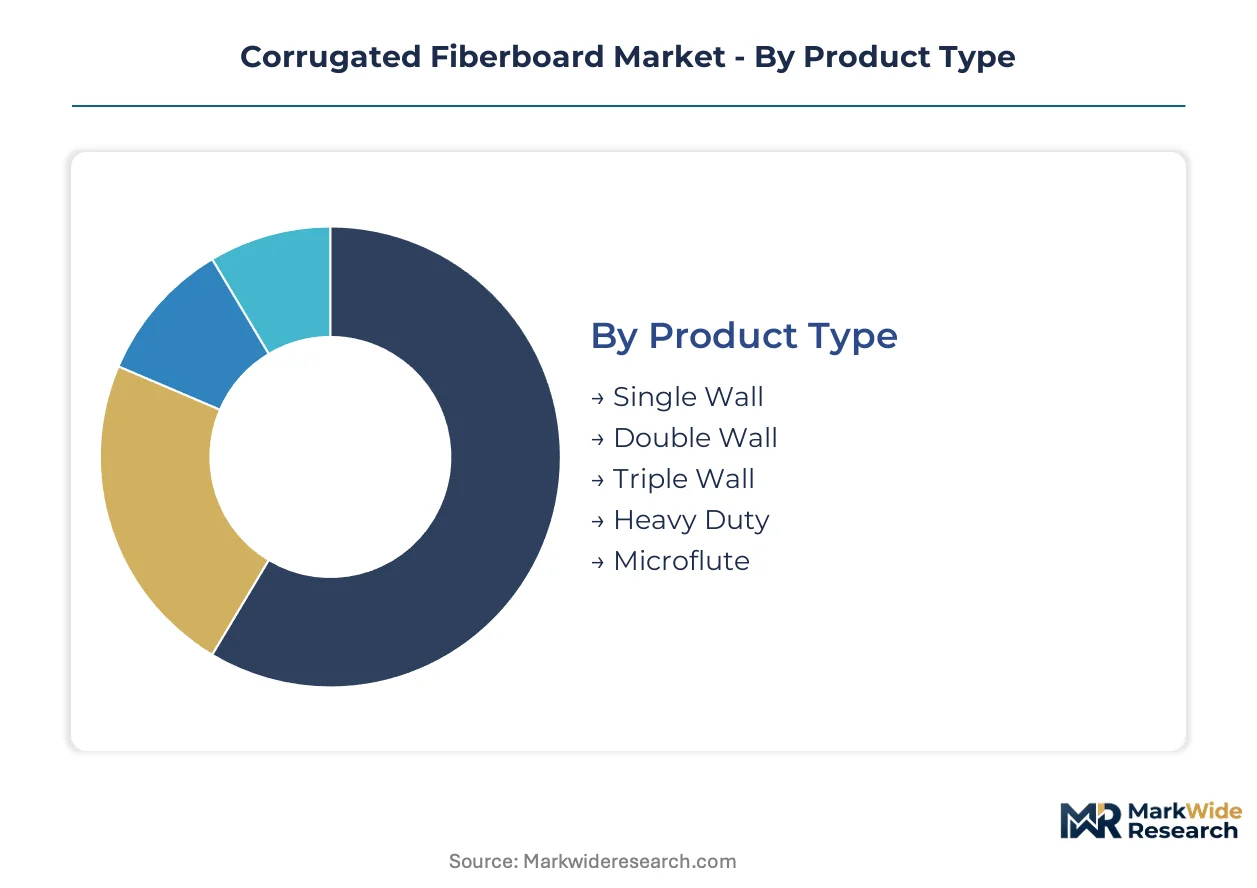
Corrugated fiberboard segmentation reflects divergent technical requirements across protective packaging applications. Product architecture, material specification, end-use performance demands, and channel economics each create distinct competitive arenas with unique margin profiles and capability barriers.
Product Type:
Flute geometry and wall construction define structural performance thresholds for load-bearing and cushioning applications.
- Single Wall:One fluted medium sandwiched between two linerboards, typically 3-4mm flute height. E-commerce parcel volume concentrates demand in Germany and India as fulfillment networks prioritize dimensional weight optimization.
- Double Wall:Two fluted layers with three linerboard facings, delivering burst strengths exceeding 350 psi. Heavy appliance logistics in Brazil and India specify this configuration for refrigerator and washing machine transport.
- Triple Wall:Three fluted mediums with four linerboard layers for extreme load applications. Industrial machinery exports from Germany require this grade for ocean freight containerization.
- Heavy Duty:Reinforced constructions with grammages above 400 gsm for military and aerospace component packaging. Defense procurement in the United States sustains niche volume.
- Microflute:Sub-2mm flute profiles enabling retail-ready display properties. Cosmetics and premium electronics brands in France and Japan specify E and F flutes for shelf presentation.
Mature deployment sits with Single Wall. Newer deployment is concentrated in Microflute as brand owners substitute folding carton for unboxing experiences.
Material Grade:
Raw fiber sourcing and pulping chemistry determine cost position, printability, and moisture resistance in finished board.
- Recycled Kraft:Post-consumer OCC-based linerboard with 90-100% recycled content. Price-sensitive Asian markets in India and cost-optimized e-commerce in Germany drive procurement specifications.
- Virgin Kraft:Fresh softwood pulp linerboard delivering superior tensile strength and print surface quality. Pharmaceutical cold chain applications in France and high-end cosmetics in Japan require virgin fiber for moisture barrier lamination compatibility.
- Semi-Chemical:Neutral sulfite semi-chemical pulp for medium layers combining stiffness with crush resistance. Medium-duty industrial packaging in Brazil favors this grade for palletized agricultural exports.
- Testliner:Multi-ply recycled linerboard with lower burst strength than Kraft equivalents. Secondary packaging for non-fragile goods in India dominates consumption.
- Coated:Clay or polymer surface treatments enabling high-fidelity flexographic and digital printing. Point-of-sale displays in Brazilian retail modernization projects specify coated white top liner.
Cost leadership concentrates in Recycled Kraft. Performance differentiation and regulatory compliance are expanding Coated grade adoption.
End Use Industry:
Application-specific protection requirements dictate flute selection, barrier properties, and certification needs.
- Food & Beverages:Temperature-sensitive and moisture-barrier specifications for cold chain distribution. Meal-kit services in India and grocery e-commerce in Germany are compressing run lengths and accelerating insulated corrugated innovation.
- Consumer Electronics:Anti-static and shock-absorbing requirements for smartphones, laptops, and accessories. Amazon's packaging specifications in the United States and original equipment manufacturer standards in Japan drive microflute adoption.
- Pharmaceuticals:GDP-compliant temperature assurance for vaccines and biologics. German and French regulators mandate recyclable mono-material construction under EU Green Deal packaging rules.
- Home Appliances:Heavy-load protection for refrigerators, washing machines, and air conditioners. Brazil's retail infrastructure expansion and India's appliance manufacturing clusters sustain double-wall and triple-wall demand.
- Personal Care:Premium unboxing aesthetics for cosmetics and skincare subscription boxes. Direct-to-consumer brands in France and Japan specify digitally printed microflute for brand differentiation.
Volume scale favors Food & Beverages. Margin expansion is climbing the fastest in Pharmaceuticals as regulatory compliance creates specification premiums.
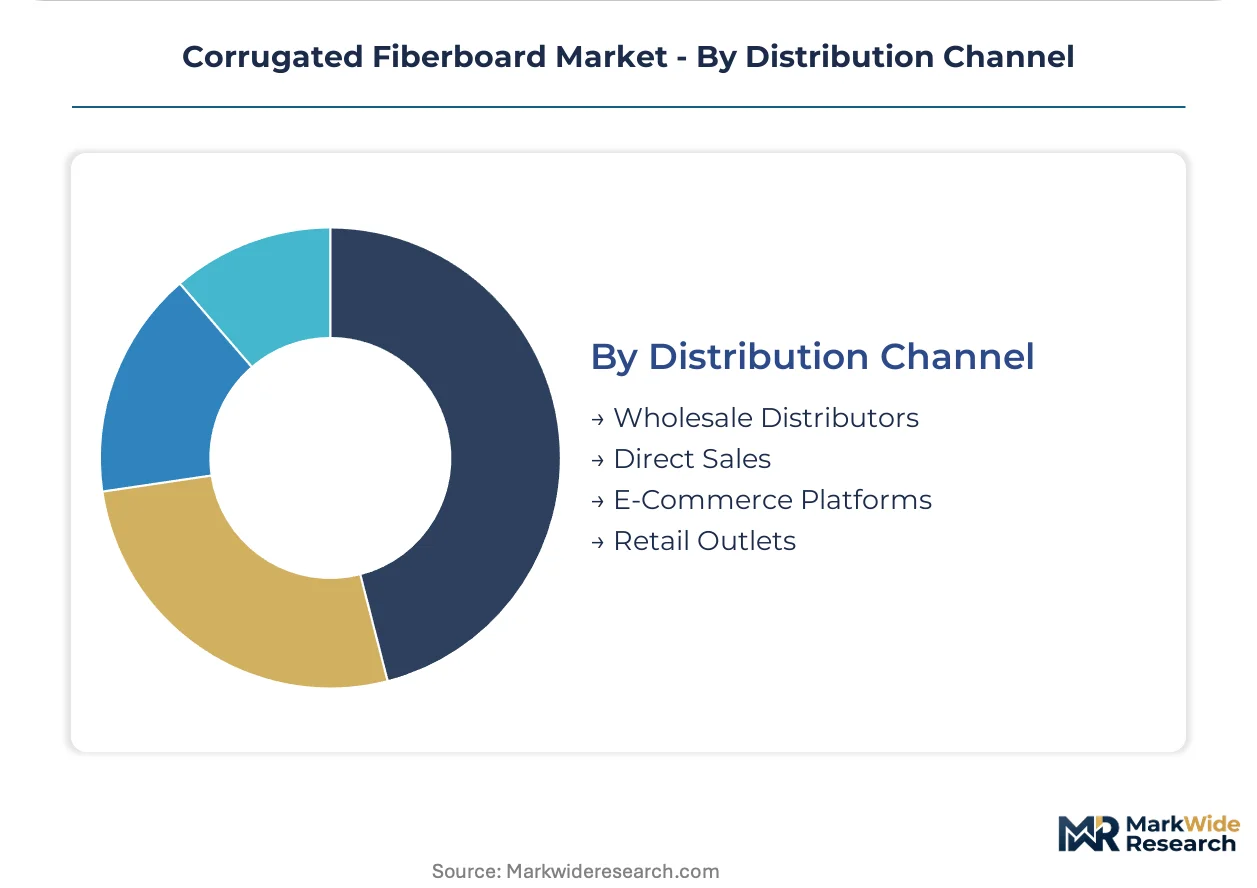
Distribution Channel:
Channel structure determines order fragmentation, technical service intensity, and inventory positioning economics.
- Direct Sales:Converter-to-brand-owner relationships with dedicated account engineering. Large appliance manufacturers in Brazil and pharmaceutical multinationals in Germany negotiate multi-year supply agreements with technical collaboration.
- Wholesale Distributors:Regional inventory pooling for small and mid-sized converters. India's fragmented packaging sector relies on distributor networks for OCC supply security and linerboard spot purchasing.
- E-Commerce Platforms:Digital procurement portals enabling spot purchasing and specification comparison. Mid-tier Indian converters use platforms to reduce dependence on European equipment suppliers under PLI scheme localization.
- Retail Outlets:Point-of-purchase packaging supply for display-ready case requirements. Brazilian supermarket expansion in secondary cities drives corrugated display procurement through retail channel relationships.
Relationship intensity peaks in Direct Sales. Digital transaction volume is expanding most quickly in E-Commerce Platforms as procurement functions modernize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recycled fiber supply clusters in the southeastern United States anchor North American containerboard output. German mill networks dominate European linerboard capacity. Indian informal sector displacement and Brazilian retail modernization are redrawing emerging market competitive boundaries.
United States
E-commerce fulfillment density in Atlanta, Dallas, and Chicago metropolitan corridors drives demand for single-wall parcel-grade board. EPA recycled content guidelines shape procurement specifications for major retail distributors. Integrated pulp-to-box operations across Alabama, Mississippi, and Georgia concentrate North American linerboard supply.
Germany
Pharmaceutical cold chain logistics in Frankfurt-Rhine-Main and Munich corridors sustain premium-grade virgin Kraft demand. EU Green Deal packaging recyclability mandates accelerate mono-material corrugated adoption for temperature-sensitive biologics. The Baden-Württemberg industrial cluster hosts specialized converters serving automotive component exports.
India
Meal-kit subscription proliferation in Mumbai, Delhi-NCR, and Bengaluru compresses production run lengths for food-grade microflute. BIS grammage and burst strength enforcement displaces unorganized board suppliers in domestic transport packaging. Gujarat and Maharashtra formal sector capacity captures share from informal producers.
Brazil
Supermarket and hypermarket expansion in Campinas, Curitiba, and Porto Alegre secondary markets creates display-ready corrugated demand. ANVISA pharmaceutical packaging regulations align with EU traceability standards for export-oriented production. São Paulo state converters command premium pricing for point-of-sale ready cases over standard RSC formats.
Japan
Premium cosmetics unboxing specifications in Tokyo-Osaka corridors drive E and F microflute adoption for brand differentiation. METI circular economy guidelines promote closed-loop OCC collection systems. The Chubu-Nagoya manufacturing belt supplies precision electronics packaging with anti-static and shock-absorbing properties.
Corrugated Fiberboard Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital printing convergence and insulated cold-chain solutions. The market structure consolidates around integrated mill-to-box operators with captive fiber supply and regional converter networks with specialized coating capabilities. Three archetypes dominate: integrated forest products conglomerates with pulp self-sufficiency, regional recycling specialists with pan-European collection networks, and technology-focused converters leveraging short-run digital production. Capacity expansion and strategic partnerships constitute the primary competitive moves, with players securing metropolitan logistics proximity and cross-border raw material sourcing agreements.
Within the integrated multinational tier, International Paper exemplifies southeastern United States fiber integration, while Smurfit Kappa anchors European demand through its recycling and mill network. WestRock occupies a position serving regulated end-use specialties. These three represent distinct strategic postures: North American pulp-to-box verticality, European circular infrastructure dominance, and premium-grade specification focus for compliance-driven segments.
| Leading Market Players |
|---|
| International Paper |
| Smurfit Kappa |
| WestRock |
| DS Smith |
| Mondi Group |
| Packaging Corporation of America |
| Rengo Co., Ltd. |
| Georgia-Pacific |
| Nine Dragons Paper |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap converters across Germany and India anchor regional pricing discipline through generational customer relationships and flexible credit terms that bind buyers through working-capital cycles rather than spot-market competition. This ownership pattern concentrates supply-side bargaining power in OCC procurement while insulating contract pricing from commodity volatility through multi-year volume commitments with major e-commerce platforms.
Pricing Analysis
Warranty and technical service bundling separates premium converters from commodity suppliers, with uptime guarantees and flute-profile engineering support commanding 15-25% contract premiums over unbundled board supply. Pricing stratifies across certified cold-chain grades, standard industrial specifications, and economy testliner for secondary packaging, with EU Green Deal compliance costs widening spreads between virgin Kraft and recycled alternatives. Cost compression in economy grades intensifies as Indian formal-sector capacity scales, while pharmaceutical buyers in Germany show lowest price sensitivity due to GDP-mandated quality assurance requirements.
Supply Chain Analysis
Reverse-logistics flows for used corrugated containers concentrate OCC collection networks in Germany, the United States, and India, where formal sector recovery rates determine regional linerboard cost positions. Virgin pulp supply draws from Scandinavian and southeastern US softwood forests, while recycled fiber feeds from municipal and industrial collection systems. Tariff exposure on Chinese OCC import policies creates systemic input cost volatility. Distribution runs through integrated mill-to-box operators for large accounts and wholesale distributors for fragmented converter demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation erects a compliance moat around closed-loop recycling investments, elevating capital requirements for new entrants while rewarding incumbent integrated operators with established collection infrastructure.
For Market Incumbents: Deepen captive OCC collection network density in metropolitan corridors within 150 kilometers of fulfillment centers to defend against plastic corrugated substitution in automotive pooling applications. Expand micro-flute coating capacity for cosmetics unboxing specifications in France and Japan. Priority investment targets zero-make-ready folder-gluers to capture meal-kit SKU proliferation in India and Brazil. For New Entrants and Emerging Players: The premium-economy price gap in pharmaceutical cold-chain packaging offers white-space entry through bio-based thermal liner development for German and French vaccine distribution. Target India's fragmented secondary cities where BIS enforcement displaces informal suppliers but formal capacity lags retail modernization. Go-to-market through e-commerce procurement platforms reduces equipment capex dependence under PLI localization incentives. For Investors and Strategic Acquirers: Amazon packaging specification shifts toward micro-flute E and F profiles are the leading indicator that lightweighting investments will outpace traditional capacity expansion in valuation multiples. Long-term viability favors converters with digital printing integration and metropolitan logistics proximity over mill-integrated players dependent on hurricane-exposed southeastern US fiber supply. Watch for OCC price volatility spikes signaling margin compression pressure on non-integrated mid-caps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Captive fiber supply insulates margins from Chinese import policy volatility. |
| Micro-Flute Coating Capacity Expansion | E and F flute demand from Amazon and cosmetics brands commands premium pricing. |
| Zero-Make-Ready Folder-Gluer Installation | Short-run capability captures meal-kit SKU fragmentation in India and Brazil. |
| Digital Printing Convergence | Direct-to-board inkjet enables lot-size-one promotional campaigns for DTC brands. |
| Metropolitan Logistics Proximity | 150-kilometer fulfillment radius rewrites competitive boundaries around last-mile infrastructure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this corrugated fiberboard market assessment, combined with primary interviews across corrugator operators, brand-owner packaging engineers, OCC collection network managers, and pharmaceutical supply chain directors. FEFCO design standards, EPA recycled content guidelines, and EU Packaging and Packaging Waste Regulation implementation timelines provided compliance benchmarking. Bottom-up converter capacity surveys triangulated against top-down linerboard production data from mill associations.
Granularity-level modeling deployed product-type flute geometry, material-grade fiber sourcing, end-use industry protection requirements, and distribution-channel relationship intensity as core segmentation dimensions across the projection horizon. CAGRs derived from volume-demand elasticity against e-commerce parcel growth and appliance manufacturing output. Forecast inputs incorporated BIS enforcement timelines in India, Brazilian retail modernization capex cycles, and EU Green Deal packaging redesign mandates.
Inputs from customs records and mill association disclosures were available through the study window; gaps in informal-sector production estimates in India introduce uncertainty bands around emerging market share calculations. Forecasts reflect assumptions on OCC price recovery trajectories and substitution elasticity for plastic corrugated in closed-loop automotive applications. Material deviation in Chinese OCC import policy or hurricane disruption frequency in the southeastern United States warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fiber-Based Packaging
North America Molded Fiber Packaging Market
Fiber-Based Packaging
Crystalline Polyethylene Terephthalate Market
Fiber-Based Packaging
Molded Fiber Cup Market
Fiber-Based Packaging
USA and Canada Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Wine Packs Market
Fiber-Based Packaging
Molded Pulp Inserts Market
Fiber-Based Packaging
Jumbo Kraft Tubes Market
Fiber-Based Packaging
Bio-Based PSA for Paper and Fiber-Based Flexible Packaging Market
Fiber-Based Packaging
Molded Pulp Basket Market
Fiber-Based Packaging
Fiberboard Packaging Market
Fiber-Based Packaging
Europe Molded Fiber Pulp Packaging Market
Fiber-Based Packaging
Global Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Packaging Market
Fiber-Based Packaging
Composite Cardboard Tubes Market
Fiber-Based Packaging
Europe Molded Pulp Packaging Market
Fiber-Based Packaging
Molded Fiber Containers Market