
 Die Grinders Market | 2026-2036
Die Grinders Market Size, Share, and Industry Trends Forecast 2026-2036
Die Grinders Market Outlook
East Asian pneumatic component manufacturing is shifting toward higher-precision collet assemblies for die grinder integration. Makita Corporation leverages its cordless battery platform to extend product reach across construction and metalworking channels. Ingersoll Rand Inc. anchors its position through industrial-grade pneumatic systems for heavy-duty grinding operations. Bosch Group differentiates via connected tool ecosystems that integrate torque feedback and runtime monitoring for professional users.
Die grinders are rotary power tools utilizing high-speed spindles typically rated between 15,000 and 35,000 RPM to perform grinding, polishing, and material removal on metal, plastic, and composite surfaces. Electric die grinders dominate volume shipments across manufacturing facilities requiring consistent power delivery for extended duty cycles, while cordless variants represent the fastest-expanding category as lithium-ion cell energy density improves runtime thresholds for field applications. Pneumatic die grinders retain entrenched positions in aerospace metalworking shops where compressed air infrastructure eliminates battery swap downtime and reduces spark hazards near flammable compounds.
OSHA enforces permissible exposure limits on occupational noise from pneumatic grinding equipment, compelling manufacturers to engineer muffled exhaust pathways and vibration-dampened housings. The EU Machinery Directive through CE marking mandates ergonomic design validation and residual risk disclosure for handheld rotary tools sold across member states. Stakeholders must monitor evolving battery safety standards from IEC and regional adaptations of ISO 28927 vibration test protocols as cordless platforms displace pneumatic alternatives in noise-sensitive environments.
Market Dynamics
OSHA's tightening permissible exposure limits on occupational noise from pneumatic grinding equipment are forcing manufacturers to reengineer exhaust pathways and housing designs, compressing margins for legacy product lines while accelerating cordless platform development.
Growth Catalysts
- Compressed air infrastructure in aerospace metalworking:Aerospace facilities in Germany and the United States maintain entrenched pneumatic fleets where spark hazards near flammable compounds make battery alternatives impractical.
- OSHA noise exposure mandates:Tighter OSHA enforcement in automotive repair workshops is expanding pneumatic tool fleet upgrades with muffled exhaust systems and vibration-dampened housings.
- Lithium-ion energy density improvements:Advances in cell chemistry are extending runtime thresholds for cordless die grinders in field applications across Japan's precision manufacturing corridors.
Market Restraints
- Cobalt and lithium supply concentration:Battery raw material sourcing concentrates in politically unstable regions, creating input cost volatility for cordless platform manufacturers.
- CE marking compliance burden:The EU Machinery Directive mandates extensive ergonomic design validation and residual risk disclosure, extending product launch timelines for handheld rotary tools.
- Pneumatic infrastructure lock-in:Heavy industrial facilities face high switching costs from established compressed air systems to electric alternatives, preserving incumbent technology positions.
Strategic Opportunities
- Connected tool ecosystems:Integration of torque feedback and runtime monitoring creates premium positioning for professional users seeking operational data.
- Precision manufacturing corridors in Japan:Nagoya and Osaka industrial clusters show concentrated demand for cordless variants in tight-access finishing operations.
- IEC battery safety standard harmonization:Emerging unified standards across cordless platforms reduce regional certification duplication and accelerate cross-border product launches.
Industry Challenges
- ISO 28927 vibration test protocol adaptation:Regional variations in vibration measurement standards create compliance complexity for manufacturers serving multiple markets simultaneously.
- Collet assembly precision scaling:East Asian component suppliers struggle to maintain tolerances during volume ramp-up for higher-precision die grinder integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Grinders Market |
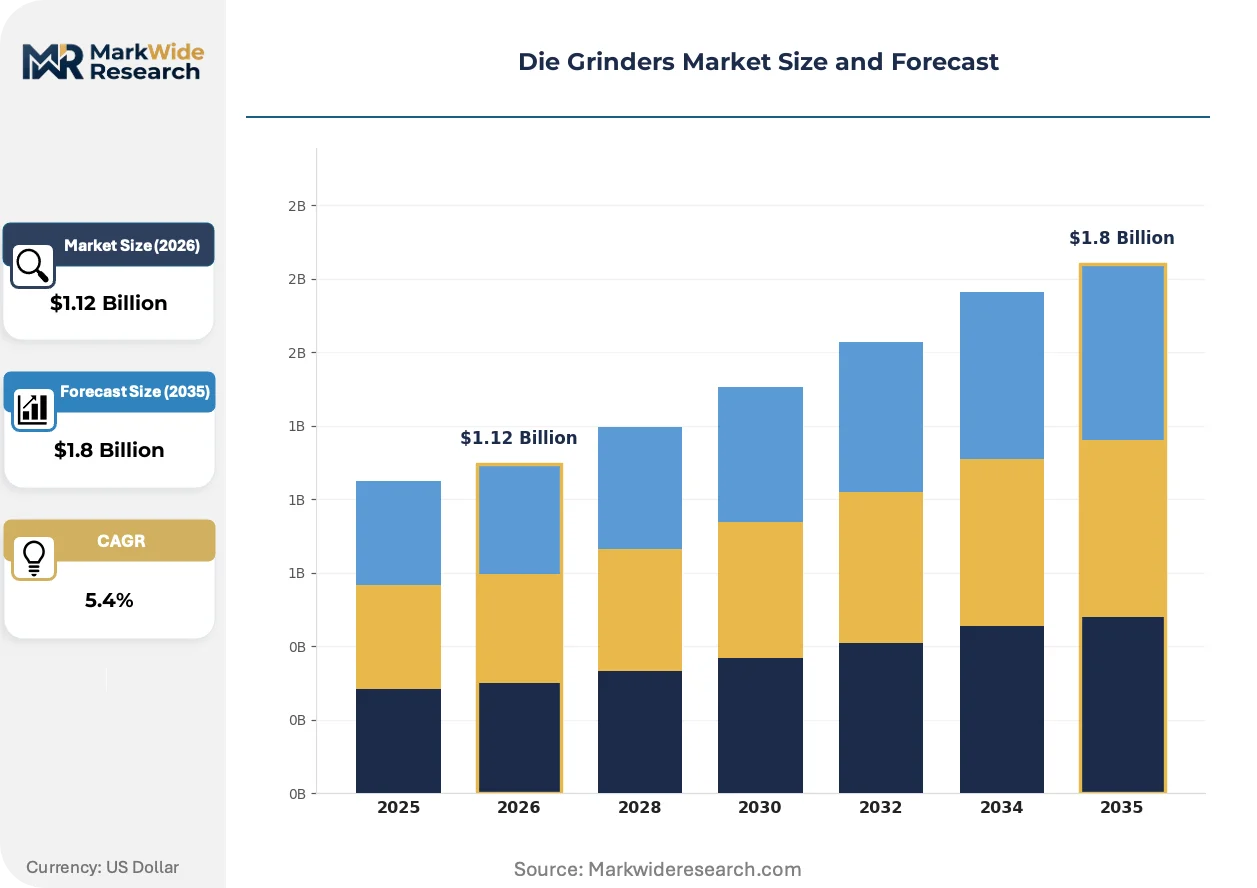
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $1.8 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Die Grinders, Pneumatic Die Grinders, Cordless Die Grinders, Bench Die Grinders End User: Manufacturing, Automotive, Aerospace, Metalworking Power Rating: Less than 100 Watts, 100-500 Watts, 500-1000 Watts, Above 1000 Watts Size: Compact, Standard, Heavy-Duty, Mini |
| Companies Covered | Nitto Kohki U.S.A., Inc., DEPRAG USA, Dynabrade, Inc., Snap-on Incorporated, Ingersoll Rand Inc., Atlas Copco AB, Makita Corporation, Stanley Black & Decker, Inc., Bosch Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Grinders Market Strategic Shifts
Brushless motor architectures and smart torque management systems are actively displacing conventional brushed designs across professional-grade die grinder portfolios, compressing the performance gap between cordless and pneumatic alternatives.
Brushless DC motor technology with integrated Hall-effect sensors is rewriting the power-to-weight benchmarks for cordless die grinders. Metal fabrication shops in the United States are adopting these platforms at accelerating rates for extended duty cycle applications. The technology is rewriting competitive positioning by enabling runtime parity with pneumatic systems in noise-sensitive environments.
REACH restrictions on hexavalent chromium in surface finishing processes are compelling manufacturers to validate alternative abrasive chemistries for collet-mounted accessories. The regulation is forcing reformulation of grinding wheels and polishing compounds sold across EU member states. German automotive suppliers are responding fastest, locking in certified abrasive supply chains ahead of enforcement deadlines.
Buying committees at industrial distributors are consolidating supplier relationships around platforms offering unified battery ecosystems across multiple tool categories. The traditional standalone die grinder procurement model is giving way to fleet-standardization decisions driven by battery compatibility. This pattern concentrates most visibly in Japanese construction and metalworking channels where multi-tool platform loyalty drives vendor selection.
Die Grinders Market Segmentation
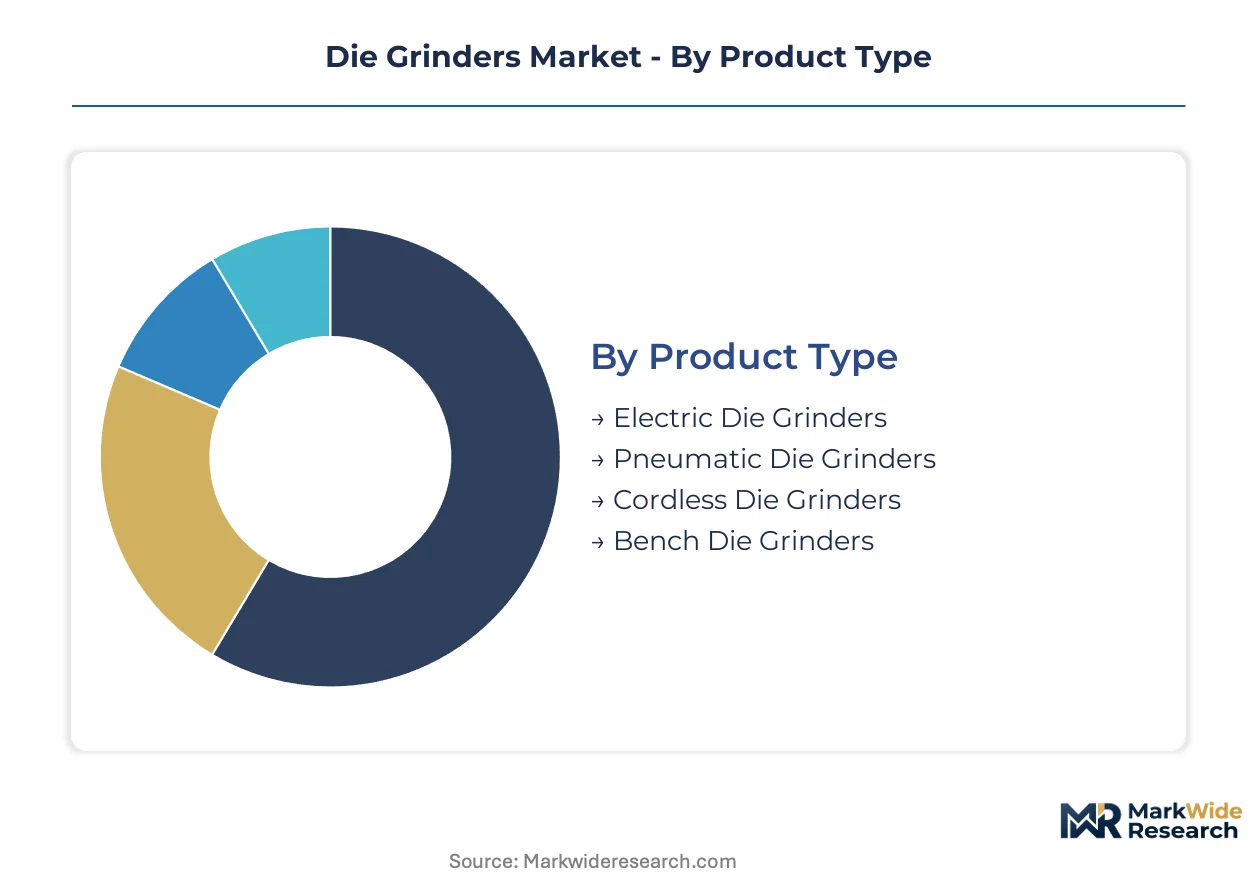
Die grinder procurement patterns diverge sharply across power sources and duty cycles. Capital deployment, maintenance infrastructure, and regulatory exposure vary substantially by segment, reshaping vendor priorities and distributor stocking strategies.
Product Type:
Pneumatic die grinders demand the heaviest upfront capital commitment through compressor infrastructure and distribution line installation, while cordless platforms require sustained battery ecosystem investment.
- Electric Die Grinders:Corded AC-motor designs deliver continuous torque for extended grinding operations in metal fabrication facilities. Manufacturing plants in Germany and the United States favor these units for production line integration where power consistency outweighs mobility requirements. OSHA electrical safety standards govern installation protocols in industrial settings.
- Pneumatic Die Grinders:Compressed-air systems utilizing rotary vane motors achieve higher power-to-weight ratios than electric alternatives. Aerospace metalworking shops in Germany maintain entrenched pneumatic fleets where spark hazards near flammable compounds render battery alternatives impractical. Muffled exhaust pathways address tightening OSHA noise exposure limits.
- Cordless Die Grinders:Lithium-ion battery platforms with brushless DC motors are gaining traction in field applications across Japan's precision manufacturing corridors around Nagoya and Osaka.
- Bench Die Grinders:Stationary units with pedestal mounting serve dedicated grinding stations in small machine shops and vocational training facilities.
Electric die grinders absorb the bulk of installed capacity in heavy manufacturing; cordless die grinders are expanding most quickly as battery energy density improves runtime thresholds.
End User:
Application environments dictate specification requirements from collet precision to vibration damping, with aerospace and automotive sectors driving premium product development.
- Manufacturing:High-volume production facilities require die grinders rated for continuous duty cycles with standardized collet interfaces for rapid accessory changeover.
- Automotive:Repair workshops and OEM stamping plants utilize die grinders for weld seam grinding and surface preparation. German automotive suppliers are consolidating procurement around unified battery ecosystems ahead of REACH enforcement deadlines for hexavalent chromium alternatives.
- Aerospace:Precision metalworking operations demand vibration-dampened housings and certified abrasive compatibility. Facilities in Germany and the United States maintain pneumatic infrastructure to eliminate spark hazards near flammable compounds while meeting FAA-adjacent material handling protocols.
- Metalworking:Job shops and fabrication contractors prioritize runtime flexibility and multi-tool battery compatibility across grinding, cutting, and finishing operations.
Metalworking channels represent the broadest addressable base; aerospace applications command the steepest specification premiums and supplier qualification barriers.
Power Rating:
Motor wattage directly correlates with material removal rates and thermal management requirements, segmenting procurement between light finishing and heavy stock removal.
- Less than 100 Watts:Compact units for detail work and precision finishing in electronics manufacturing and jewelry production.
- 100-500 Watts:Mid-range motors balance portability with adequate torque for general metalworking tasks. Japanese construction channels show concentrated demand for cordless variants in this bracket as multi-tool platform loyalty drives vendor selection.
- 500-1000 Watts:Heavy-duty applications in automotive repair and metal fabrication require sustained power delivery. German automotive workshops are upgrading pneumatic fleets in this range with vibration-dampened housings to comply with OSHA noise exposure mandates.
- Above 1000 Watts:Industrial-grade units for aggressive material removal in foundries and heavy equipment maintenance.
The 100-500 Watt bracket captures the highest shipment volumes; above-1000 Watt systems face the steepest cordless displacement pressure from improving battery chemistry.
Size:
Physical dimensions determine access constraints in tight workspaces and influence operator fatigue over extended duty cycles.
- Compact:Reduced head diameter and shortened body length enable operation in confined spaces. Precision manufacturing corridors in Japan around Nagoya and Osaka show concentrated demand for compact cordless variants in tight-access finishing operations.
- Standard:Balanced ergonomics for general-purpose grinding across automotive and metalworking applications.
- Heavy-Duty:Reinforced housings and larger collet capacities for aggressive material removal in industrial maintenance.
- Mini:Ultra-small form factors for intricate detail work in electronics and medical device manufacturing.
Standard sizes maintain the broadest installed base; compact variants are climbing the fastest as precision manufacturing tolerances tighten and access constraints multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate deposits in Chile's Atacama Desert and cobalt mining in the Democratic Republic of Congo supply critical raw materials for cordless die grinder battery packs. These upstream concentrations ripple through manufacturing footprints and pricing dynamics across consuming markets.
United States
Automotive repair workshops in Detroit and the broader Midwest are retrofitting pneumatic fleets with vibration-dampened housings to meet OSHA's permissible exposure limits on occupational noise. The Department of Labor enforces these standards through regional compliance audits. Metal fabrication shops in Texas and the Southeast are adopting brushless cordless platforms for extended duty cycle applications.
Germany
Aerospace metalworking facilities in Bavaria and Baden-Württemberg maintain entrenched compressed air infrastructure to eliminate spark hazards near flammable compounds. CE marking under the EU Machinery Directive mandates ergonomic design validation for handheld rotary tools sold across member states. Stuttgart's automotive supplier cluster is consolidating procurement around unified battery ecosystems ahead of REACH enforcement deadlines.
Japan
Precision manufacturing corridors around Nagoya and Osaka show concentrated demand for compact cordless variants in tight-access finishing operations. METI promotes domestic battery technology development through industrial competitiveness programs. Chubu region tool distributors report accelerating fleet standardization decisions driven by multi-tool platform loyalty.
China
East Asian pneumatic component manufacturing is shifting toward higher-precision collet assemblies for die grinder integration. GB standards and MIIT regulations govern power tool safety certification for domestic and export markets. Yangtze River Delta fabrication clusters are scaling volume production of brushless motor subassemblies for cordless platform OEMs.
India
Metalworking job shops in Maharashtra and Gujarat prioritize runtime flexibility and multi-tool battery compatibility across grinding and finishing operations. BIS certification requirements extend product launch timelines for handheld rotary tools entering the domestic market. Tamil Nadu's automotive component manufacturing belt is upgrading pneumatic tool fleets to meet evolving factory safety protocols.
Die Grinders Market Competitive Environment
Global majors compete with regional champions across pneumatic and cordless technology vectors, creating a tiered structure where scale-driven conglomerates anchor premium positioning while specialized fabricators capture niche applications. The vendor landscape segments into three strategic archetypes: diversified industrial conglomerates with cross-category battery ecosystems, pneumatic specialists leveraging compressed air expertise, and precision component manufacturers supplying collet and motor subassemblies. Competitive moves center on portfolio diversification into connected tool ecosystems and backward integration into battery cell supply chains.
Among Japan-based manufacturers, Makita Corporation and Nitto Kohki U.S.A., Inc. exemplify divergent strategic positioning within the cordless and pneumatic archetypes respectively. Makita anchors the multi-tool platform loyalty dynamic visible across Nagoya-Osaka industrial channels, while Nitto Kohki occupies a specialized position in precision pneumatic systems. Bosch Group represents the diversified conglomerate tier with integrated torque feedback capabilities, and Ingersoll Rand Inc. sits within the industrial-grade pneumatic specialist category serving aerospace metalworking facilities.
| Leading Market Players |
|---|
| Nitto Kohki U.S.A., Inc. |
| DEPRAG USA |
| Dynabrade, Inc. |
| Snap-on Incorporated |
| Ingersoll Rand Inc. |
| Atlas Copco AB |
| Makita Corporation |
| Stanley Black & Decker, Inc. |
| Bosch Group |
| Others |
Value Chain & Pricing Dynamics
REACH restrictions on hexavalent chromium in surface finishing processes gate qualified abrasive supply chains and premium-tier pricing access for die grinder accessories across EU member states. German automotive suppliers are locking in certified abrasive partnerships ahead of enforcement deadlines, compressing margin structures for uncertified competitors while concentrating pricing power among validated suppliers.
Pricing Analysis
Warranty and service bundling separates premium die grinder offerings from unbundled economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service inclusion. Pricing pressure stems from cobalt and lithium input cost volatility in cordless platforms. Metalworking job shops exhibit highest price sensitivity; aerospace facilities show lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Container freight rates from East Asian manufacturing hubs to European and North American distribution centers influence landed cost structures for die grinder assemblies. China, Japan, and Germany anchor component supply for collet assemblies, brushless motors, and precision pneumatics. Battery cell chemistry draws from Chilean lithium and DRC cobalt concentrations. Single-source vulnerability in rare earth magnet supply creates structural exposure. Distribution runs through industrial distributor networks and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around multi-tool battery platform loyalty, with weaker pneumatic specialists facing displacement as cordless runtime thresholds improve.
For Market Incumbents: Deepen backward integration into battery cell supply chains to secure cobalt and lithium offtake against raw material volatility. Expand certification investment in REACH-compliant abrasive ecosystems to defend premium positioning against emerging cordless entrants. Anchor channel control through unified battery platform lock-in across construction and metalworking distributor networks. For New Entrants and Emerging Players: E-commerce industrial procurement portals offer lower customer acquisition costs than established distributor relationships. Target precision manufacturing corridors in Japan's Chubu region where compact cordless variants face supply gaps. Pursue white-label partnerships with East Asian component manufacturers to bypass collet assembly precision barriers. For Investors and Strategic Acquirers: Fleet standardization decisions at Japanese construction channels are the leading indicator that multi-tool platform loyalty is hardening into durable competitive moats. The five-to-ten-year viability window favors diversified conglomerates with captive battery ecosystems over standalone pneumatic specialists. Watch for IEC battery safety standard harmonization as the inflection signal reducing regional certification duplication costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captive lithium and cobalt sourcing insulates margins from DRC and Chile supply volatility. |
| Connected Tool Ecosystem Launch | Torque feedback integration with runtime monitoring captures premium positioning among professional users. |
| REACH-Compliant Abrasive Certification | Hexavalent chromium alternative validation secures German automotive supplier procurement decisions. |
| Multi-Tool Platform Standardization | Battery compatibility across grinding, cutting, and finishing categories locks in distributor shelf space. |
| Precision Collet Assembly Scale-Up | Higher-tolerance East Asian component manufacturing enables cordless die grinder performance parity. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this die grinder market analysis. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combined with OSHA enforcement databases, EU Machinery Directive compliance registries, and lithium carbonate trade flow statistics. Bottom-up shipment modeling and top-down industrial equipment expenditure triangulation validated volume estimates.
Segment-level granularity modeled power source, end-use industry, and power rating across the projection horizon. CAGRs derived from trend extrapolation of pneumatic fleet replacement cycles and cordless adoption curves in precision manufacturing corridors. Brushless motor cost reduction trajectories and battery energy density improvement curves informed platform substitution assumptions.
The model holds under steady OSHA noise enforcement and REACH implementation timelines; deviation in battery raw material export restrictions or pneumatic infrastructure retrofit subsidy programs would shift cordless displacement velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Micro Welders Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Height Gauge Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Tool Holder Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Digital Tool Presetter Market
Industrial Tools
Deburring Machine Market