
 Saudi Arabia Power Tools Market | 2026-2036
Saudi Arabia Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Power Tools Market Analytics
Multi-source procurement among large construction conglomerates is recalibrating vendor relationships across the Kingdom. Robert Bosch GmbH leverages its cordless battery platform to anchor premium positioning in commercial segments. Makita Corporation specializes in compact brushless motor designs that sustain contractor loyalty on tight-deadline sites. Stanley Black & Decker, Inc. competes through broad SKU coverage that spans entry-level DIY to heavy-duty industrial grades.
Saudi Arabia power tools encompass electrically, pneumatically, or hydraulically actuated handheld and stationary devices engineered for material cutting, fastening, grinding, or surface preparation, typically operating at voltages from 12V to 240V AC or 18V–54V DC battery platforms with torque ratings exceeding 50 Nm in professional-grade units. Cordless lithium-ion configurations now dominate new procurement in construction and manufacturing applications where site mobility outweighs sustained duty-cycle demands. Drills retain the largest volume share across contractor fleets, while cordless power source adoption outpaces corded alternatives as battery energy density improves and SASO import standards tighten on electrical safety compliance. Grinders command higher per-unit margins in metalworking and infrastructure fabrication, where abrasive disc compatibility and overload protection differentiate professional from consumer tiers.
SASO technical regulations mandate conformity assessment for electromagnetic compatibility and mechanical safety on all imported power tools, effectively filtering low-cost uncertified suppliers from Saudi distribution channels. The Saudi Building Code and Ministry of Municipal and Rural Affairs specifications further steer procurement toward vibration-reduced and dust-extraction-ready equipment on public works. Stakeholders must monitor battery platform standardization battles and local assembly incentive structures as the Kingdom deepens industrial content requirements under Vision 2030 localization mandates.
Market Dynamics
Cordless lithium-ion platforms are compressing corded equipment procurement cycles across Saudi construction sites, while SASO electromagnetic compatibility mandates filter uncertified imports from distribution channels.
Growth Catalysts
- Vision 2030 Infrastructure Pipeline:Megaprojects in Riyadh and Jeddah generate sustained fleet replacement demand among tier-one contractors.
- SASO Safety Certification:Mandatory conformity assessment for mechanical safety and electrical compliance elevates professional-grade equipment preference over consumer-tier alternatives.
- Battery Energy Density Gains:54V platform endurance improvements enable cordless tools to displace pneumatic systems in metal fabrication and infrastructure welding.
Market Restraints
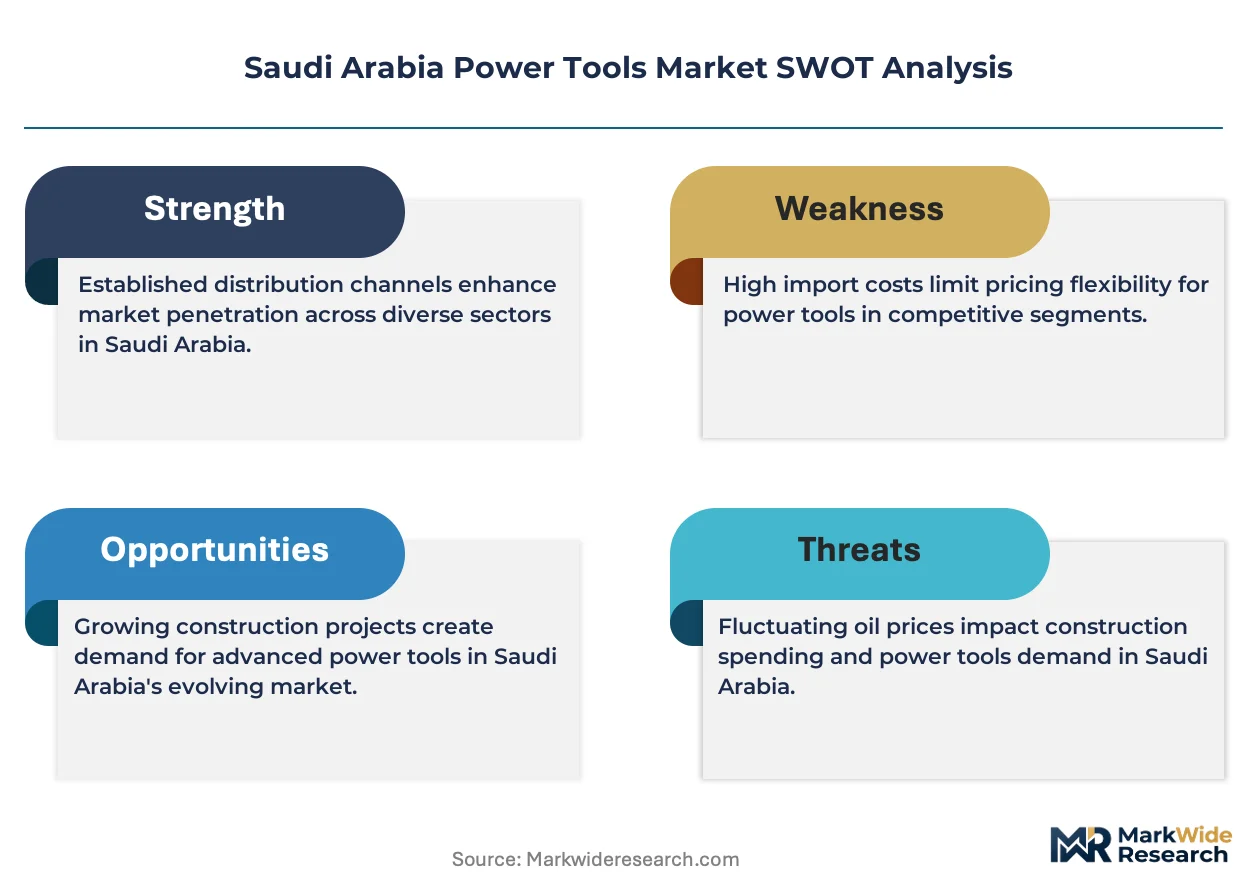
- Lithium-Ion Cell Cost Volatility:Raw material price swings for cobalt and nickel concentrate squeeze margin structures on battery pack assemblies.
- Import Dependency Concentration:East Asian manufacturing clusters control 80-plus percent of brushless motor and power electronics supply, exposing distributors to shipping lane disruptions.
- Duty-Cycle Limitations:Sustained high-torque applications in steel erection still favor corded or engine-driven alternatives over cordless platforms.
Strategic Opportunities
- Neom and Red Sea Project Corridors:Remote site deployment creates demand for solar-compatible charging infrastructure and ruggedized tool storage systems.
- Local Assembly Incentives:Vision 2030 industrial content requirements reward domestic kit assembly with preferential procurement access on government contracts.
- Brushless-Pneumatic Hybrid Convergence:Dual-power tools bridge cordless mobility with pneumatic torque density for heavy-duty infrastructure fabrication.
Industry Challenges
- Certification Timeline Compression:SASO conformity assessment backlogs delay product launches by four to eight months, forcing distributors to pre-position inventory ahead of seasonal demand spikes.
- Technician Training Deficits:Battery diagnostics and brushless motor repair skills lag equipment complexity, straining aftermarket service networks in secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Power Tools Market |
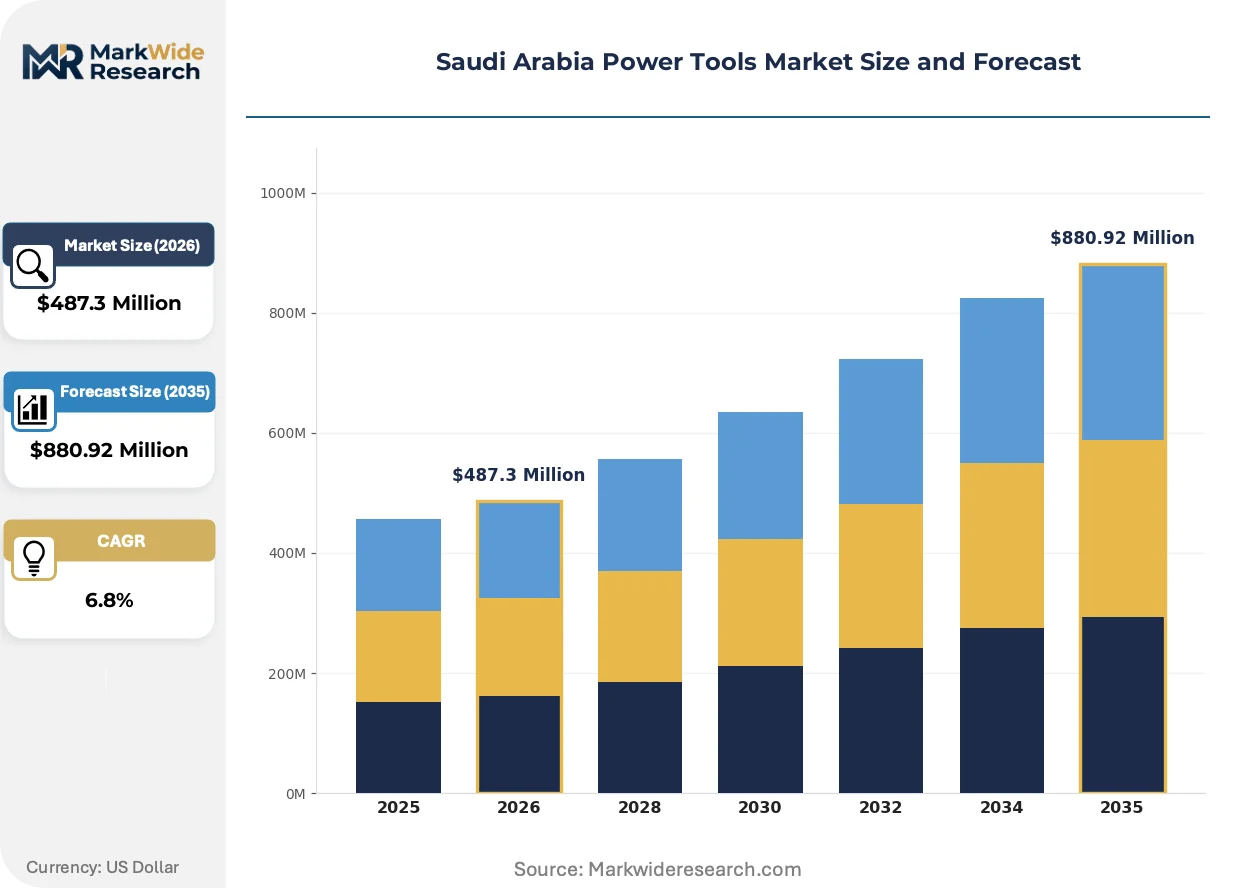
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Saws, Grinders, Sanders Power Source: Corded, Cordless, Pneumatic, Hydraulic Application: Construction, Manufacturing, Automotive, Woodworking End User: Contractors, Homeowners, Industrial, DIY Enthusiasts |
| Companies Covered | Hilti Corporation, Robert Bosch GmbH, Bosch Limited, Snap-On, Inc., Atlas Copco AB, Stanley Black & Decker, Inc., Milwaukee Tool (Techtronic Industries), Emerson Electric Co., Makita Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Power Tools Market Evolving Landscape
Three forces are restructuring Saudi Arabia power tools procurement: battery platform consolidation, regulatory tightening on electrical safety, and contractor fleet standardization around interoperable ecosystems.
Brushless motor architectures are expanding into high-torque fastening and concrete cutting applications previously dominated by corded or engine-driven equipment. Tier-one construction conglomerates are mandating 18V-to-54V platform standardization across multi-site operations to reduce charger redundancy and spare parts complexity. This convergence is compressing supplier margins on entry-tier SKUs while anchoring premium pricing for ecosystem-compatible professional lines.
SASO technical regulations on electromagnetic compatibility and mechanical safety now require third-party laboratory testing for all imported power tools. The Saudi Building Code amendments steer public works procurement toward vibration-reduced and dust-extraction-ready equipment. Commercial contractors are pre-qualifying suppliers based on certification documentation completeness, filtering uncertified Asian manufacturers from Riyadh and Jeddah distribution channels.
Multi-year fleet leasing arrangements are displacing spot purchasing among large construction conglomerates. Equipment-as-a-service providers bundle tool access with maintenance and battery swap programs, capturing contractor loyalty through uptime guarantees rather than unit sales. This model concentrates most visibly in Vision 2030 megaproject corridors where capital efficiency priorities override ownership preferences.
Saudi Arabia Power Tools Market Segmentation
SASO certification requirements vary sharply across power tool categories, with battery-powered equipment facing stricter electromagnetic compatibility testing than corded alternatives. Construction contractors in Riyadh and Jeddah prioritize segments that minimize site downtime through rapid battery swap protocols.
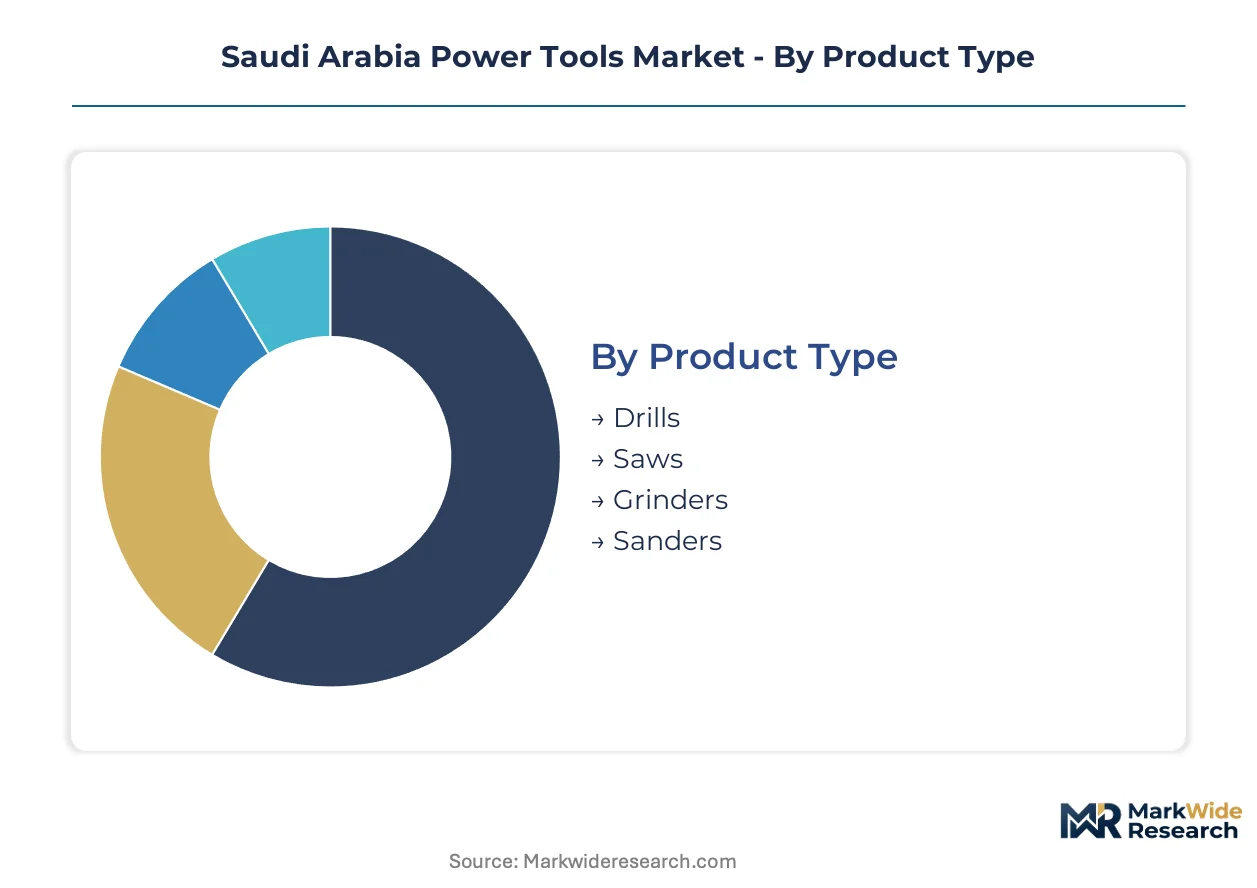
Product Type:
Drills and saws carry the heaviest SASO conformity assessment burden due to electrical safety and vibration exposure standards, while grinders face additional abrasive disc compatibility mandates.
- Drills:Rotary and hammer configurations dominate contractor fleet procurement, with brushless motor variants displacing brushed units in Riyadh megaproject sites where SASO energy efficiency regulations tighten. Tier-one construction conglomerates standardize around 18V-to-54V battery platforms to reduce charger redundancy across multi-site operations.
- Saws:Circular and reciprocating designs sustain the steepest demand trajectory in Jeddah commercial buildouts, where fast-track deadlines favor cordless mobility over corded sustained duty cycles. Blade standardization around TPI ratings and arbor compatibility anchors vendor selection criteria.
- Grinders:Angle and die grinder configurations command premium positioning in metal fabrication workshops, with overload protection and dust-extraction readiness differentiating professional from consumer tiers under Saudi Building Code amendments.
- Sanders:Orbital and belt designs concentrate in woodworking and finishing applications where vibration-reduced specifications align with Ministry of Municipal and Rural Affairs procurement guidelines for public works.
Leading the category by volume: Drills. Growing fastest: Saws.
Power Source:
Cordless lithium-ion platforms now absorb the majority of new procurement spend, though pneumatic systems retain cost advantages in fixed-facility metalworking where compressed air infrastructure exists.
- Corded:Sustained high-torque applications in steel erection and concrete cutting still favor AC-powered equipment, particularly where site electrical infrastructure eliminates battery logistics. SASO electrical safety testing focuses on grounding integrity and thermal cutoff reliability.
- Cordless:Lithium-ion configurations from 12V to 54V dominate Vision 2030 infrastructure corridors, with battery energy density improvements enabling displacement of pneumatic systems in infrastructure welding. Rapid charger deployment and solar-compatible charging infrastructure support remote site operations at Neom and Red Sea Project locations.
- Pneumatic:Compressed air systems maintain cost efficiency in established manufacturing facilities across Dammam industrial zones, where existing compressor infrastructure amortizes capital investment. Torque density advantages persist in heavy-duty fastening applications.
- Hydraulic:Specialized demolition and underwater cutting applications in marine infrastructure projects utilize hydraulic actuation where electrical ignition risks prohibit battery or corded alternatives.
Cordless platforms capture the largest procurement share. Hydraulic systems expand most quickly from a small base in specialized marine applications.
Application:
Construction applications generate the densest certification documentation requirements, with manufacturing and automotive segments prioritizing precision tolerances over ruggedization specifications.
- Construction:Commercial and residential buildouts across Riyadh, Jeddah, and emerging giga-project corridors drive fleet standardization mandates among tier-one contractors. Dust-extraction-ready equipment and vibration-reduced specifications align with Saudi Building Code procurement steering.
- Manufacturing:Metal fabrication and assembly line operations in Jubail Industrial City favor pneumatic and corded systems where fixed infrastructure supports continuous duty cycles. Precision torque control differentiates professional-grade equipment.
- Automotive:Collision repair and assembly applications concentrate in Eastern Province service clusters, with cordless impact wrenches and polishers gaining share through battery platform interoperability.
- Woodworking:Furniture manufacturing and finish carpentry in smaller urban centers prioritize compact cordless designs where site mobility outweighs sustained power demands.
Construction commands the dominant revenue share. Automotive applications climb fastest as dealership service bay modernization accelerates.
End User:
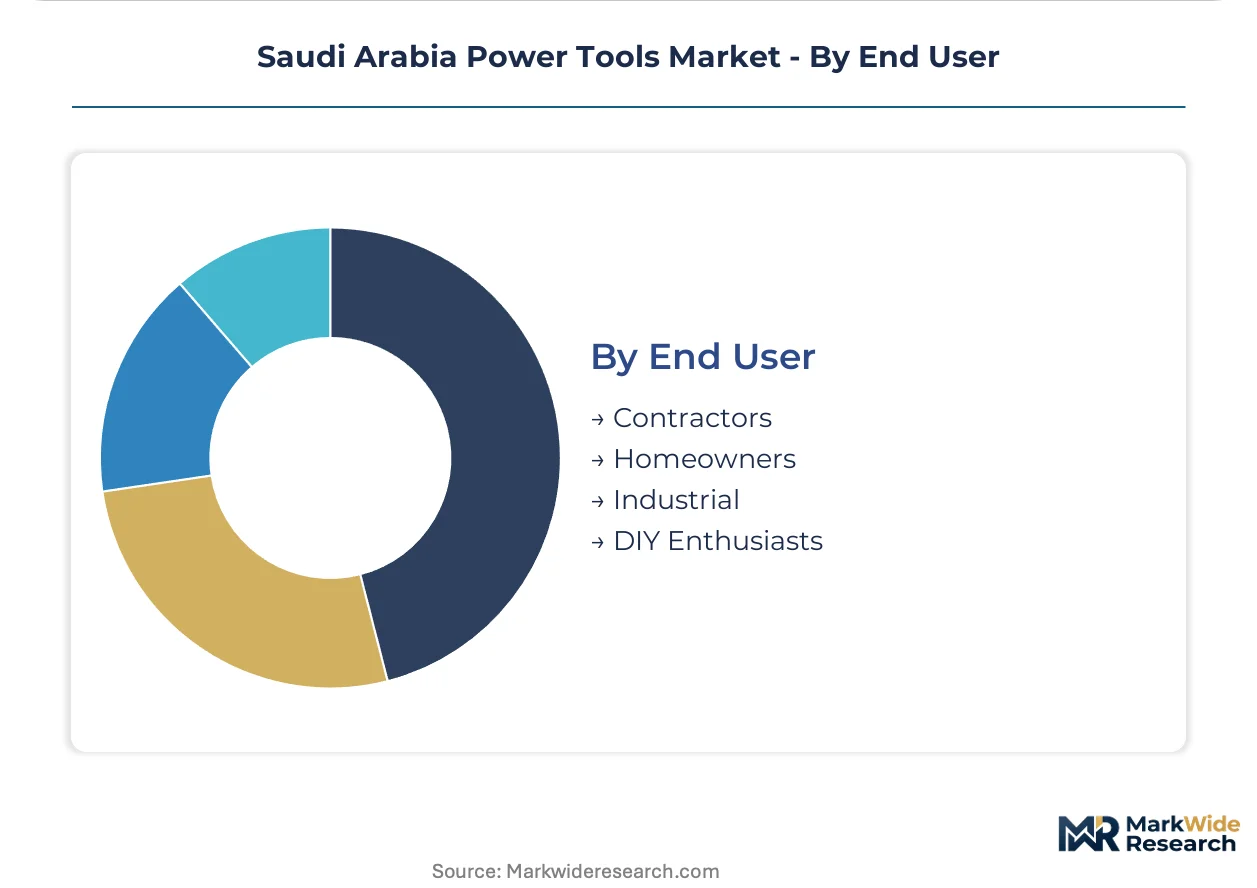
Contractor procurement concentrates around equipment-as-a-service leasing models, while homeowner and DIY segments remain exposed to uncertified import channels that SASO regulations increasingly filter.
- Contractors:Tier-one construction conglomerates mandate multi-year fleet leasing arrangements with bundled maintenance and battery swap programs, capturing uptime guarantees through vendor loyalty rather than unit ownership. Standardization around interoperable 18V-to-54V ecosystems reduces spare parts complexity.
- Homeowners:Residential maintenance and renovation demand concentrates in entry-level cordless platforms, with retail distribution through Jeddah and Riyadh home improvement centers. SASO certification completeness increasingly influences purchase decisions as enforcement tightens.
- Industrial:Manufacturing facility maintenance departments prioritize durability specifications and aftermarket service network density, with procurement decisions centralized in Dammam and Jubail industrial zone headquarters.
- DIY Enthusiasts:Hobbyist and maker segment demand fragments across online channels and specialty retailers, with price sensitivity exposing this cohort to non-compliant import risks that SASO border controls progressively interdict.
Contractor segment leads absolute volume. Industrial end users gain share fastest as manufacturing localization incentives deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Riyadh megaproject corridors and Jeddah commercial buildouts, with secondary clusters emerging in Eastern Province industrial zones and NEOM development sites. The Saudi Standards, Metrology and Quality Organization steers procurement toward certified equipment through mandatory conformity assessment protocols.
Riyadh
Vision 2030 giga-projects including Diriyah Gate and King Salman Park generate fleet replacement cycles among tier-one contractors. SASO electromagnetic compatibility testing requirements filter uncertified imports from distribution channels. The Riyadh Metro extension and Qiddiya entertainment city anchor equipment procurement at density levels unmatched elsewhere in the Kingdom.
Eastern Province
Jubail Industrial City and Dammam manufacturing facilities sustain pneumatic system demand where compressed air infrastructure already exists. The Saudi Building Code amendments steer public works toward vibration-reduced equipment specifications. Aramco-backed supplier development programs incentivize local assembly partnerships for maintenance tool provisioning.
Jeddah
Red Sea Project tourism infrastructure and Jeddah Economic City commercial towers favor cordless mobility on fast-track construction schedules. Ministry of Municipal and Rural Affairs procurement guidelines mandate dust-extraction-ready equipment on municipal contracts. The King Abdullah Port logistics corridor enables rapid battery platform distribution to western region sites.
NEOM Northwest
Remote site deployment at The Line and Oxagon creates demand for solar-compatible charging infrastructure and ruggedized tool storage systems. Vision 2030 localization mandates reward domestic kit assembly with preferential government contract access. Trojena mountain resort and Sindalah island developments require specialized underwater and demolition tooling for marine infrastructure phases.
Saudi Arabia Power Tools Market Competitive Landscape
Platform standardization battles dominate the current landscape as tier-one contractors mandate interoperable 18V-to-54V ecosystems across multi-site operations. The vendor base organizes around three strategic archetypes: German-engineered premium battery platforms, Japanese precision motor specialists, and diversified industrial conglomerates with broad SKU coverage. M&A activity concentrates on battery technology acquisitions and regional distribution rights consolidation. Vertical integration into lithium-ion cell supply and local assembly partnerships represent parallel competitive thrusts.
Within the premium battery platform tier, Robert Bosch GmbH and Makita Corporation exemplify divergent technical anchoring strategies. Stanley Black & Decker, Inc. occupies a position spanning entry-level DIY through heavy-duty industrial grades through portfolio breadth rather than ecosystem depth. Milwaukee Tool represents the battery platform consolidation vector through its parent Techtronic Industries' manufacturing scale. These three anchors illustrate how vendor selection increasingly hinges on charger interoperability and spare parts network density rather than per-unit specifications alone.
| Leading Market Players |
|---|
| Hilti Corporation |
| Robert Bosch GmbH |
| Bosch Limited |
| Snap-On, Inc. |
| Atlas Copco AB |
| Stanley Black & Decker, Inc. |
| Milwaukee Tool (Techtronic Industries) |
| Emerson Electric Co. |
| Makita Corporation |
| Others |
Value Network & Pricing Analysis
Captive battery pack assembly by tier-one distributors anchors both supply security and margin control across Saudi Arabia's certified power tools channel. This backward integration into lithium-ion cell sourcing insulates vendors from cobalt and nickel volatility while commanding premium positioning against uncertified competitors filtered by SASO electromagnetic compliance mandates.
Pricing Analysis
Warranty bundling separates professional-grade procurement from consumer-tier transactions, with tier-one contractors demanding multi-year uptime guarantees that embed service costs into per-unit pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by SASO certification completeness and battery platform interoperability. Pricing pressure stems from raw material cost compression in battery cells, squeezing margin structures on mid-tier SKUs. DIY enthusiasts exhibit highest price sensitivity, while construction conglomerates prioritize total cost of ownership over per-unit outlay.
Supply Chain Analysis
SASO conformity assessment gating filters distribution access, with third-party laboratory documentation requirements eliminating uncertified East Asian manufacturers from Riyadh and Jeddah procurement channels. Manufacturing concentrates in China, South Korea, and Japan for brushless motors, power electronics, and lithium-ion cells. Supply chains draw from cobalt and nickel mining operations, copper winding materials, and rare-earth magnet feeds. Single-source vulnerability in 54V battery platform controllers exposes distributors to semiconductor allocation disruptions. Distribution runs through authorized dealer networks with SASO pre-qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning, with battery platform standardization emerging as the decisive upstream lever for capturing contractor fleet loyalty across Vision 2030 megaprojects.
For Market Incumbents: Hedge against platform fragmentation by deepening charger interoperability investments and locking multi-year fleet leasing arrangements with tier-one construction conglomerates. Defensive consolidation through local assembly partnerships secures preferential government contract access under industrial content mandates. Certification timeline compression at SASO threatens product launch windows, necessitating pre-positioned inventory buffers. For New Entrants and Emerging Players: Equipment-as-a-service providers represent the most penetrable channel archetype, with maintenance and battery swap bundling displacing spot purchasing in Neom and Red Sea Project corridors. White-space concentrates in solar-compatible charging infrastructure for remote site deployment. Go-to-market execution should target aftermarket service network gaps in secondary cities where technician training deficits strain incumbent response times. For Investors and Strategic Acquirers: Exit pathways concentrate in battery technology acquisitions and regional distribution rights consolidation, with platform standardization battles determining long-term viability across the analysis window. Acquisition targets with captive lithium-ion cell supply or SASO-certified local assembly partnerships command premium positioning. Watch for SASO regulatory expansion into carbon footprint disclosure as an inflection indicator for ESG-linked procurement steering.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Interoperable 18V-to-54V ecosystems reduce charger redundancy across multi-site contractor operations. |
| Local Assembly Partnership | Vision 2030 industrial content requirements reward domestic kit assembly with preferential government contract access. |
| Equipment-as-a-Service Launch | Multi-year fleet leasing with bundled maintenance captures contractor loyalty through uptime guarantees. |
| Solar-Compatible Charging Infrastructure | Remote site deployment at Neom and Red Sea Project locations demands off-grid power solutions. |
| Aftermarket Service Network Expansion | Brushless motor repair and battery diagnostics capabilities address technician training deficits in secondary cities. |
Research Methodology
Multi-period observation of battery platform adoption rates, SASO certification timelines, and contractor fleet replacement cycles anchored the trend analysis, supplemented by interviews with construction procurement directors, power tools distribution channel managers, aftermarket service technicians, and Ministry of Municipal and Rural Affairs specification engineers. Secondary validation drew from SASO technical regulation filings, Saudi Building Code amendments, customs import data, and Vision 2030 project development disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrix modeling connected power source technology shifts, application demand trajectories, and end-user procurement pattern evolution across the projection horizon. Segmentation dimensions spanned product type, power source architecture, application vertical, and end-user category with regional demand clustering. CAGRs derived from regression analysis of historical replacement cycles projected against megaproject pipeline commitments. Forecast inputs incorporated lithium-ion energy density improvement curves and SASO regulatory expansion scenarios.
Caveats apply where lithium raw material price volatility, shipping lane disruptions, or SASO conformity assessment backlog extensions could materially shift the outlook. Forecasts reflect documented assumptions on battery platform consolidation velocity and contractor standardization mandate adoption. A model refresh is warranted upon material change in Vision 2030 megaproject execution timelines or SASO certification scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Electric Tools Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Tool Holder Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Tool Holder Collets Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Micro Welders Market
Industrial Tools
India Power Tool Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Jigs and Other Tools Market