
 Precision Components and Tooling Systems Market | 2026-2036
Precision Components and Tooling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Components and Tooling Systems Market Analytics
Additive manufacturing integration with traditional CNC workflows is reshaping how aerospace and medical device producers source complex geometries. Robert Bosch Tool Corporation leverages its European manufacturing footprint to sustain high-volume carbide insert production. ARCH Cutting Tools differentiates through specialized geometries for hardened steel applications. Ensinger Precision Components anchors its position in high-performance polymer tooling for semiconductor packaging equipment.
Precision components and tooling systems encompass dimensionally critical parts and cutting or forming tools manufactured to tolerances often below five micrometers, serving as the foundational layer for repeatable industrial production. These systems rely on material grades such as powdered-metal high-speed steel and tungsten carbide substrates to achieve hardness exceeding 65 HRC while maintaining thermal stability during sustained cutting operations. Machined components and die-cast parts represent mature volume categories where margin pools have compressed, while additive manufacturing and 3D printing segments attract premium pricing for low-volume, high-complexity aerospace and medical device applications. CNC machining retains dominant share across automotive manufacturing and electronics assembly, though hybrid workflows combining subtractive and additive steps are gaining traction in titanium-intensive medical implant production.
ISO 9001 and AS9100 quality frameworks govern supplier qualification across aerospace and defense channels, while FDA 21 CFR Part 820 imposes design-control and validation requirements on medical device tooling vendors seeking US market access. REACH substance restrictions and EU Green Deal carbon-border adjustments are forcing European producers to document supply-chain emissions and eliminate hexavalent chromium surface treatments. Stakeholders must monitor how evolving MDR requirements in Europe and potential SEC climate-disclosure rules in the United States reshape capital allocation toward certifiable, traceable production systems.
Market Dynamics
Hybrid manufacturing workflows are compressing traditional supplier tiers as aerospace and medical device producers merge additive and subtractive capabilities under single-source contracts. REACH substance restrictions and FDA device-quality mandates are simultaneously tightening material-traceability requirements, forcing tooling vendors to reconfigure quality systems.
Growth Catalysts
- AS9100 certification requirements:Aerospace primes in Germany and the United States are consolidating supplier bases around dual-certified machine shops capable of titanium-grade fastener production.
- Tungsten carbide substrate demand:Automotive powertrain manufacturers are specifying ultra-hard cutting inserts for electric motor shaft machining, extending tool life in high-volume lines.
- Stuttgart-Aachen corridor concentration:Precision engineering clusters in southwestern Germany are attracting tier-two tooling vendors seeking proximity to OEM technical centers.
Market Restraints
- Cobalt supply concentration:Binding agents in cemented carbide rely on DRC-sourced cobalt, exposing producers to price volatility and ethical sourcing audits.
- Hexavalent chromium elimination:REACH Annex XIV restrictions on hard chrome plating force European vendors to qualify PVD alternatives, extending lead times.
- Five-micron tolerance limits:Conventional grinding cannot achieve geometries required for next-generation semiconductor packaging equipment.
Strategic Opportunities
- India PLI scheme for precision manufacturing:Domestic content requirements in aerospace and defense are creating demand for locally tooled CNC machining centers.
- Hybrid workflow convergence:Medical implant producers are integrating directed energy deposition with five-axis milling to reduce titanium waste.
- EU Green Deal carbon-border adjustments:Documented low-emission production processes will qualify European tooling vendors for premium positioning in regulated markets.
Industry Challenges
- Multi-axis programming expertise:Complex geometries require CAM specialists fluent in simultaneous five-axis toolpath optimization.
- AS9100D transition timelines:Smaller machine shops face eighteen-month certification cycles that delay aerospace contract qualification.
- Legacy ERP integration:Real-time traceability systems for FDA 21 CFR Part 820 compliance must interface with decades-old shop-floor control software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Components and Tooling Systems Market |
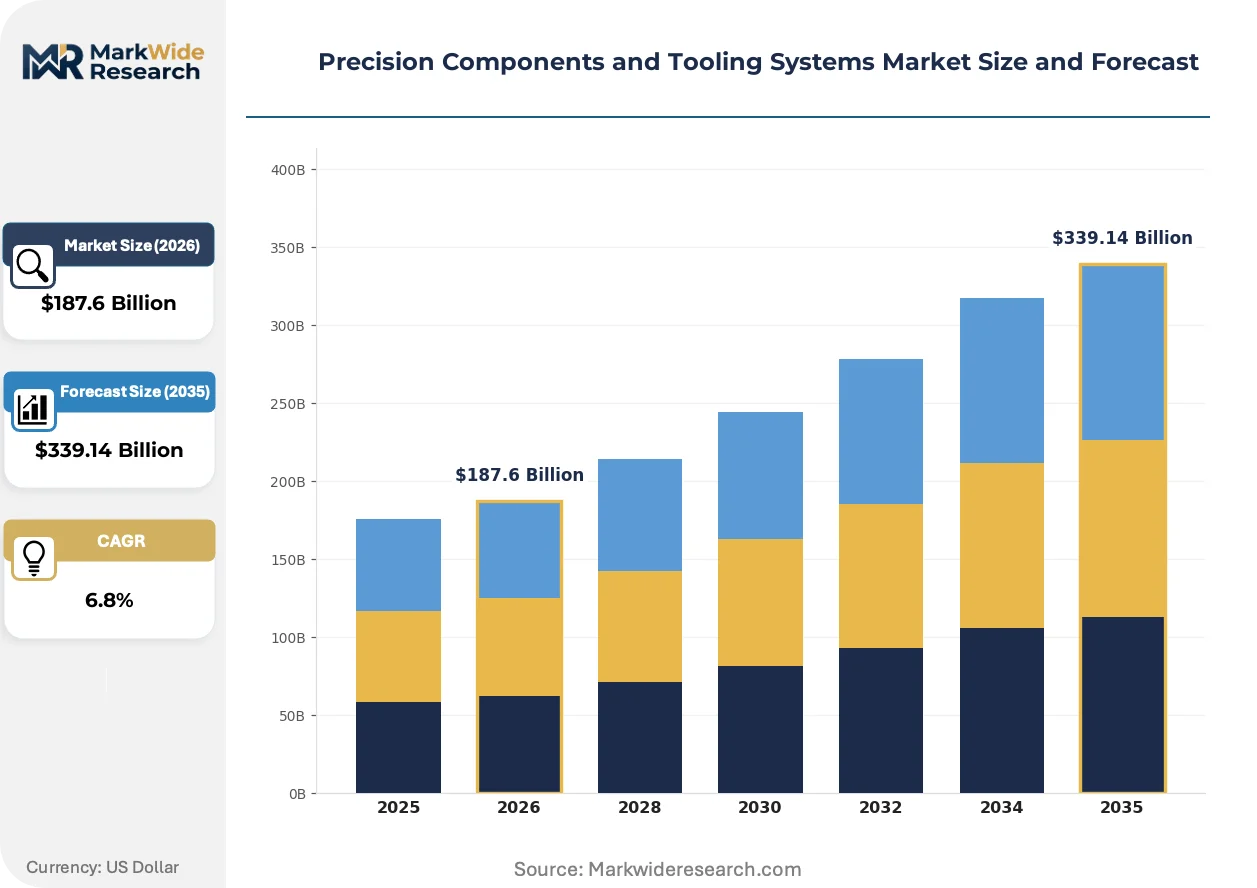
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Machined Components, Die-cast Parts, Injection Molding, Fasteners Application: Aerospace, Automotive Manufacturing, Electronics Assembly, Medical Devices Material: Aluminum Alloys, Steel, Plastics, Titanium Technology: CNC Machining, 3D Printing, Additive Manufacturing, Stamping |
| Companies Covered | botek Präzisionsbohrtechnik GmbH, ARCH Cutting Tools, Robert Bosch Tool Corporation, FRAISA SA, Ensinger Precision Components, Agathon AG, Makino, Nepean, BENZ GmbH Werkzeugsysteme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Components and Tooling Systems Market Evolving Landscape
Digital thread integration is collapsing the boundary between design and production, enabling real-time toolpath adjustments based on in-process metrology feedback loops.
Directed energy deposition is migrating from prototype repair to production-scale aerospace structural component manufacturing. Tier-one suppliers in France and Italy are adopting laser-based titanium deposition for rib and spar geometries. This technology is migrating from niche aftermarket applications to primary production contracts, compressing lead times for low-volume, high-complexity parts.
EU MDR device traceability mandates are forcing medical tooling vendors to implement serialized component tracking. The regulation requires lot-level genealogy records for cutting tools used in implant production. German and Swiss precision component manufacturers are investing in blockchain-anchored documentation systems to satisfy notified body audits.
After-sales service unbundling is fragmenting traditional distributor relationships. Large automotive OEMs in Japan and South Korea are procuring cutting tools directly from manufacturers while outsourcing regrind services to specialized regional providers. This pattern is most visible in powertrain machining lines where tool life data drives predictive replenishment contracts.
Precision Components and Tooling Systems Market Segmentation
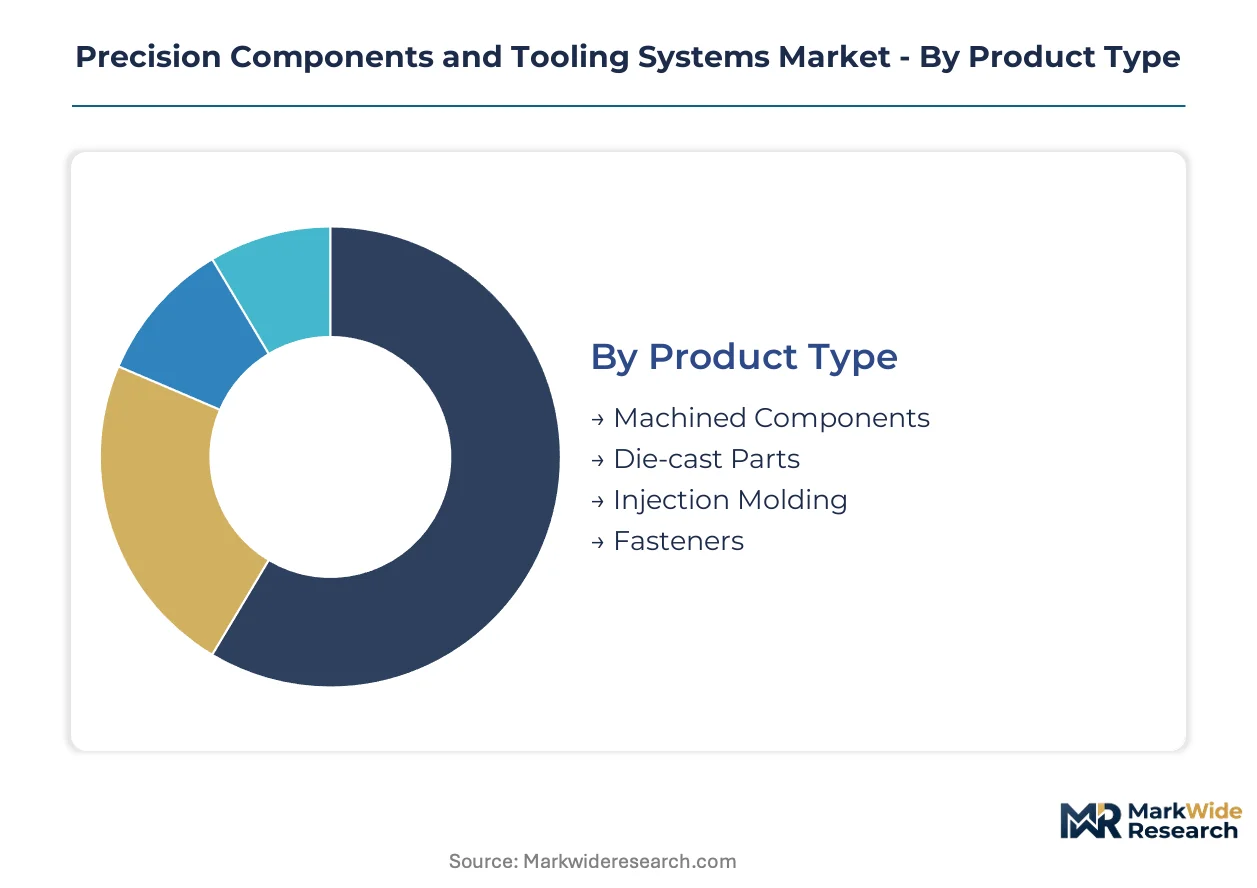
Precision components and tooling systems fragment across four intersecting dimensions that determine sourcing strategy and margin structure. Product type dictates capital intensity and batch economics. Material selection governs regulatory qualification pathways for aerospace and medical channels.
Product Type:
End-use requirements span from high-volume automotive stampings to single-piece aerospace structural components.
- Machined Components:Subtractive manufacturing of dimensionally critical parts from bar stock or forgings, achieving tolerances below five micrometers through multi-axis CNC workflows. Demand concentrates in Germany's Stuttgart-Aachen corridor for automotive powertrain and aerospace fastener applications, where AS9100D certification filters supplier qualification.
- Die-cast Parts:High-pressure aluminum and zinc injection into hardened steel molds for complex geometries with thin-wall sections. Automotive manufacturers in Japan and South Korea specify these for electric motor housings and transmission cases, prioritizing cycle time reduction over absolute precision.
- Injection Molding:Thermoplastic and thermoset forming for semiconductor packaging equipment and medical device housings.
- Fasteners:Threaded and non-threaded joining elements including titanium-grade aerospace bolts and automotive powertrain fasteners.
The dominant share belongs to Machined Components, while Injection Molding is closing the gap fastest.
Application:
Customer industries impose divergent quality frameworks and volume profiles.
- Aerospace:Structural airframe components, engine hardware, and landing gear assemblies governed by AS9100 and FAA airworthiness directives. OEMs in France and Italy are consolidating supplier bases around dual-certified machine shops capable of titanium-grade fastener production, compressing traditional tier structures.
- Automotive Manufacturing:Powertrain machining, chassis components, and electric motor housings where tool life data drives predictive replenishment contracts. Japanese and South Korean OEMs are procuring cutting tools directly from manufacturers while outsourcing regrind services regionally.
- Electronics Assembly:Connector housings, heat sinks, and semiconductor packaging equipment requiring sub-micron positioning accuracy.
- Medical Devices:Implant-grade components and surgical instruments subject to FDA 21 CFR Part 820 and EU MDR traceability mandates.
Automotive Manufacturing retains volume leadership, though Medical Devices is expanding most quickly.
Material:
Substrate selection determines thermal stability, machinability, and regulatory compliance burden.
- Aluminum Alloys:Lightweight structural grades with excellent thermal conductivity for electronics heat dissipation and automotive body panels. German and Swiss precision component manufacturers favor these for semiconductor packaging equipment where weight reduction intersects with thermal management requirements.
- Steel:High-speed and powdered-metal tool steels exceeding 65 HRC for cutting inserts and die-cast tooling. REACH Annex XIV restrictions on hexavalent chromium surface treatments are forcing European vendors to qualify PVD alternatives.
- Plastics:High-performance polymers including PEEK and PTFE for medical implants and chemical-resistant semiconductor components.
- Titanium:Biocompatible and aerospace-grade alloys with exceptional strength-to-weight ratios for structural applications.
Steel commands the largest share by tonnage, while Titanium is climbing the fastest on aerospace and medical demand.
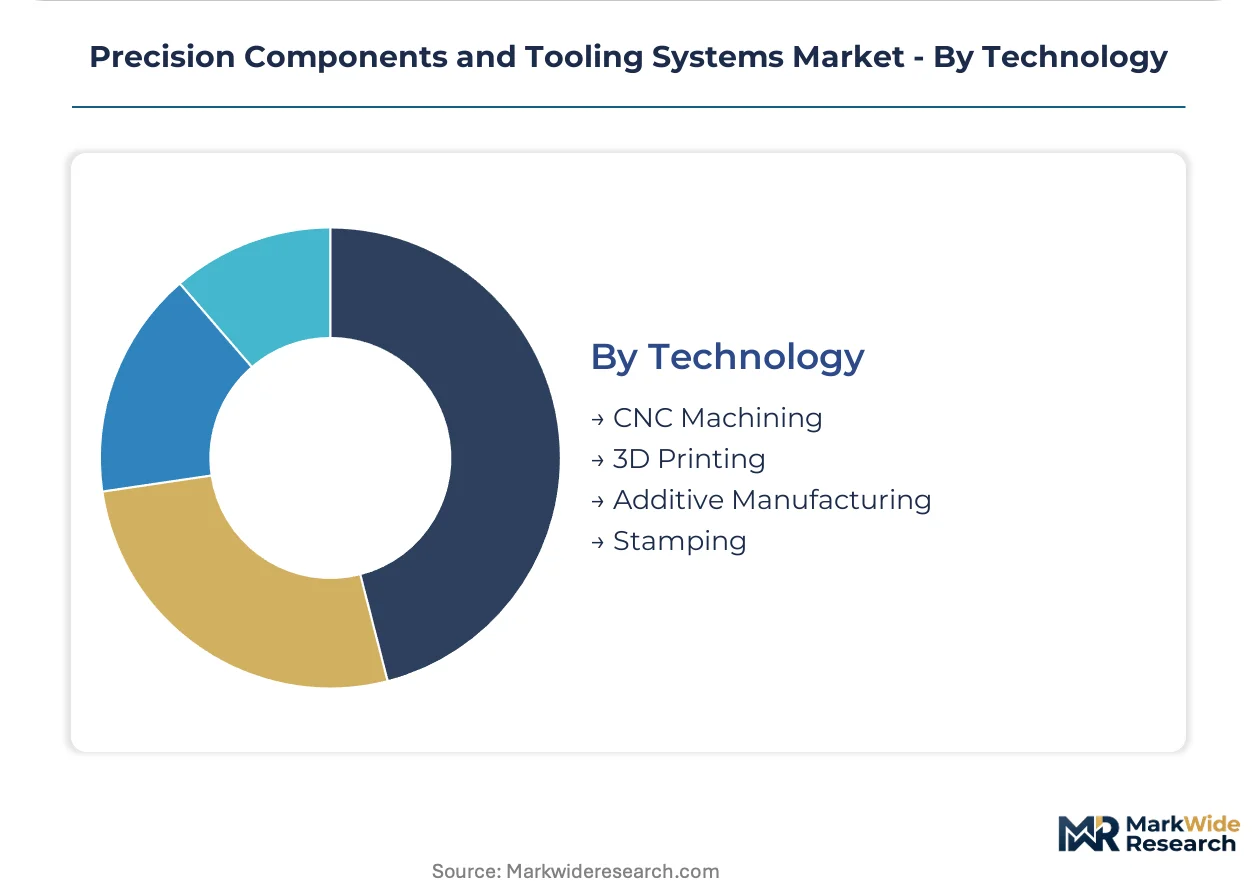
Technology:
Process selection governs geometric complexity, lead time, and unit economics.
- CNC Machining:Computer-numerical-control subtractive workflows dominant across automotive and electronics manufacturing, retaining share through hybrid integration with additive steps. Tier-one suppliers face eighteen-month AS9100D certification cycles that delay aerospace contract qualification.
- 3D Printing:Powder-bed fusion and material extrusion for prototyping and low-volume production of complex geometries.
- Additive Manufacturing:Directed energy deposition migrating from prototype repair to production-scale aerospace structural component manufacturing in France and Italy, compressing lead times for titanium rib and spar geometries.
- Stamping:Mechanical and hydraulic press forming for high-volume sheet metal components.
CNC Machining anchors current output, though Additive Manufacturing is gaining share fastest on hybrid workflow adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision component exports flow predominantly into French and Italian aerospace assembly lines, while Japanese cutting tool shipments serve South Korean automotive powertrain manufacturers. This trade architecture concentrates advanced manufacturing capability in specific industrial corridors.
Germany
Stuttgart and Aachen host dense clusters of AS9100D-certified machine shops supplying titanium-grade aerospace fasteners. REACH Annex XIV restrictions on hexavalent chromium plating force vendors to qualify PVD surface treatments, extending qualification cycles. The Baden-Württemberg precision engineering corridor attracts tier-two tooling vendors seeking proximity to OEM technical centers.
United States
FDA 21 CFR Part 820 mandates drive medical device tooling vendors toward serialized component tracking systems. The SEC's proposed climate-disclosure rules pressure suppliers to document supply-chain emissions. Greater Boston and the Pacific Northwest concentrate semiconductor packaging equipment manufacturers demanding sub-micron positioning accuracy.
Japan
METI industrial policy supports domestic content requirements in precision manufacturing equipment. Automotive OEMs in Nagoya and Osaka procure cutting tools directly from manufacturers while outsourcing regrind services regionally. The Chubu region around Nagoya anchors high-volume carbide insert production for electric motor shaft machining.
France
ANSM and EU MDR device traceability requirements force medical tooling vendors into blockchain-anchored documentation systems. Tier-one aerospace suppliers in Toulouse and Nantes adopt laser-based titanium deposition for rib and spar geometries. The Île-de-France region concentrates R&D investment in hybrid additive-subtractive workflows.
India
The PLI scheme for precision manufacturing creates demand for locally tooled CNC machining centers in aerospace and defense. CDSCO and BIS quality frameworks govern supplier qualification for medical device exports. Maharashtra and Gujarat host emerging clusters of domestic component fabricators serving European automotive OEMs.
Precision Components and Tooling Systems Market Competitive Landscape
On the supply side, the industry is bifurcated between scale-driven carbide producers and specialized geometry shops serving hardened steel applications. The vendor base stratifies across three tiers: multinational tool corporations with integrated manufacturing footprints, mid-cap specialists in polymer or ceramic substrates, and regional job shops competing on proximity. Dominant competitive moves include strategic partnerships for additive manufacturing capability licensing and geographic expansion through distributor acquisition.
Among European-based fabricators, botek Präzisionsbohrtechnik GmbH and FRAISA SA occupy positions within the precision drilling and milling specialist tier, while Robert Bosch Tool Corporation anchors the scale-driven multinational segment. ARCH Cutting Tools and Ensinger Precision Components exemplify the mid-cap specialist archetype, with the former representing hardened steel geometry expertise and the latter high-performance polymer tooling for semiconductor applications. Agathon AG and BENZ GmbH Werkzeugsysteme sit within the German-speaking precision component cluster, reflecting the Stuttgart-Aachen corridor's concentration of family-owned engineering enterprises. Makino represents Japanese machine tool integration into precision workflow systems.
| Leading Market Players |
|---|
| botek Präzisionsbohrtechnik GmbH |
| ARCH Cutting Tools |
| Robert Bosch Tool Corporation |
| FRAISA SA |
| Ensinger Precision Components |
| Agathon AG |
| Makino |
| Nepean |
| BENZ GmbH Werkzeugsysteme |
| Others |
Value Network & Pricing Analysis
Stuttgart's precision engineering corridor concentrates high-volume carbide insert capacity, granting German vendors pricing leverage over automotive OEMs in Japan and South Korea. REACH compliance costs and cobalt price volatility feed directly into contract negotiations, compressing margins for non-integrated suppliers.
Pricing Analysis
Current-generation hybrid additive-subtractive workflows command premium positioning against conventional CNC machining, while prior-generation stamping and die-casting face sustained cost compression. Three-tier pricing structure across AS9100D-certified aerospace grades, ISO 9001 industrial standards, and uncertified job-shop economy segments separates qualified from commodity supply. Pricing pressure stems from Indian PLI scheme incentives accelerating domestic CNC capacity buildout. Automotive powertrain manufacturers exhibit highest price sensitivity through predictive replenishment contracts, whereas medical device OEMs prioritize traceability over unit cost.
Supply Chain Analysis
Upstream feedstock flows from DRC-sourced cobalt for cemented carbide binders, tungsten concentrates from Vietnam and Russia, and high-performance polymer resins from Germany and Switzerland. Raw material dependencies center on rare earth stabilized substrates, powdered-metal high-speed steel, and injection-molding grade PEEK. Single-source vulnerability in cobalt supply exposes producers to ethical sourcing audits and price spikes. Distribution runs through tier-one aerospace primes consolidating supplier bases, direct procurement by Japanese automotive OEMs, and regional regrind specialists fragmenting aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against additive manufacturing displacing conventional machining in titanium-intensive aerospace and medical applications. Incumbents must fortify positioning before hybrid workflows consolidate supplier tiers.
For Market Incumbents: Pre-empt additive-native competitors by acquiring directed energy deposition capability in France and Italy, where laser-based titanium deposition is migrating to primary production contracts. Deepen backward integration into cobalt recycling and tungsten powder processing to neutralize DRC supply risk. AS9100D certification moats defend aerospace pricing power against Indian PLI-subsidized entrants. For New Entrants and Emerging Players: Maharashtra and Gujarat offer underpenetrated white-space for European automotive OEMs seeking India-based component fabricators with REACH-aligned emissions documentation. Target medical device tooling segments where FDA 21 CFR Part 820 compliance gaps delay incumbent qualification cycles. Go-to-market leverage rests on blockchain-anchored traceability systems satisfying EU MDR serialized component mandates. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with precision components stranded outside core semiconductor or aerospace platforms. Five-to-ten year viability hinges on hybrid workflow integration depth and carbon-border adjustment readiness. Monitor EU Green Deal implementation pace as inflection signal for premium positioning of documented low-emission European vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Workflow Integration | Combining directed energy deposition with five-axis milling reduces titanium waste in medical implant production. |
| Backward Integration into Feedstock | Captive tungsten carbide powder processing insulates margins from DRC cobalt price volatility. |
| Blockchain-Anchored Traceability | Serialized component tracking satisfies EU MDR lot-level genealogy requirements for cutting tools. |
| AS9100D Certification Investment | Eighteen-month qualification cycles create defensive moats against uncertified job-shop competition. |
| Carbon-Border Adjustment Readiness | Documented low-emission production qualifies European vendors for premium positioning under EU Green Deal. |
Research Methodology
A spread of perspectives from CNC machining center operators, aerospace procurement directors, medical device quality managers, and carbide insert distributors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, REACH substance restriction databases, and customs trade records for tungsten and cobalt flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply-balance framing anchored the forecast framework, modeling machined components, die-cast parts, injection molding, and fasteners against aerospace, automotive, electronics, and medical device end-use demand. Technology generation, material substrate, and regional regulatory cluster dimensions segmented volume and value outputs. CAGRs derived from historical trajectory analysis adjusted for AS9100D certification adoption curves and hybrid workflow penetration rates in titanium structural applications.
Practitioners should monitor cobalt supply disruption events, EU MDR enforcement intensity, and Indian PLI scheme capacity commissioning for early signals of forecast revision. Cross-checking against IHS Markit aerospace production data and VDMA machine tool order indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Machine Tool Touch Probe Market
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Soldering Iron Pen Market
Industrial Tools
Electric Tools Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Handheld DC Torque Tools Market
Industrial Tools
Centerless Grinding Market
Industrial Tools
Drill Drivers Market
Industrial Tools
Micro Welders Market
Industrial Tools
Plasma Arc Cutting Market
Industrial Tools
Air Screwdrivers Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Saudi Arabia Power Tools Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Tool Wire Cutters Market