
 P2P Payment Market | 2026-2036
P2P Payment Market Size, Share, and Industry Trends Forecast 2026-2036
P2P Payment Market Analysis
The premium super-app ecosystem is consolidating around bundled financial services while commodity peer-to-peer rails fragment into single-purpose utilities. PayPal sustains its cross-border merchant network through currency hedging infrastructure. Alipay dominates Asia-Pacific merchant acquisition with embedded credit scoring. Venmo competes on social transaction feeds that lock in younger demographics.
A peer-to-peer payment system denotes a decentralized funds transfer architecture enabling direct value exchange between individuals without intermediary banking correspondence, typically operating through mobile-optimized APIs with sub-second settlement latency and tokenized credential vaulting. Its primary commercial purpose replaces cash handling and check clearing for retail, gig, and informal economy transactions. Mobile wallets capture the dominant transaction volume pool as consumers abandon card-present habits, while QR code methods lead growth in emerging markets where NFC terminal penetration remains shallow. Payment apps targeting freelancers now sit at the highest margin tier due to invoice financing attachments and tax automation upsells.
The US Consumer Financial Protection Bureau scrutinizes earned-wage access products under Truth in Lending Act extensions, while the EU Payment Services Directive 2 mandates open-banking API standards that force platform interoperability. India's RBI enforces transaction caps and data localization for wallet operators, directly constraining foreign platform architecture choices. Stakeholders must weigh biometric KYC investment against the operational cost of fragmented national compliance regimes.
Market Dynamics
Instant settlement infrastructure is compressing transaction latency from days to seconds, forcing incumbent platforms to rebuild core architecture around real-time clearing rails rather than batch processing systems.
Growth Catalysts
- UPI Interoperability Mandates:India's RBI-mandated protocol standardization forces wallet operators to open APIs, expanding merchant acceptance networks for domestic and foreign platforms.
- Biometric Authentication Standards:Fingerprint and facial recognition vaulting is displacing password-based credentialing, reducing fraud rates and onboarding friction for unbanked users.
- Micro-Merchant QR Adoption:Indonesia's urban corridor demand from unbanked street vendors is pulling low-cost acceptance hardware into mass deployment.
Market Restraints
- Data Localization Requirements:India's RBI transaction caps and server domicile rules fragment platform architecture, raising compliance costs for cross-border operators.
- Interchange Compression:Regulatory pressure on merchant discount rates squeezes revenue per transaction, forcing volume-dependent monetization models.
- NFC Terminal Scarcity:Emerging market POS infrastructure gaps limit contactless penetration, constraining premium wallet feature rollout.
Strategic Opportunities
- Earned-Wage Access Integration:The US CFPB's Truth in Lending Act extension scrutiny creates compliant product white space for payroll-linked advance platforms.
- Freelancer Invoice Financing:Gig worker payment apps can attach working capital products and tax automation, capturing the highest margin tier in the ecosystem.
- EU Open Banking Convergence:PSD2-mandated API standards enable account-to-account payment bypass of card networks, reducing interchange exposure.
Industry Challenges
- Fragmented National Compliance Regimes:Biometric KYC investment requirements vary by jurisdiction, complicating platform standardization.
- Legacy Core System Integration:Real-time settlement rails must interface with batch-oriented banking infrastructure, creating middleware complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | P2P Payment Market |
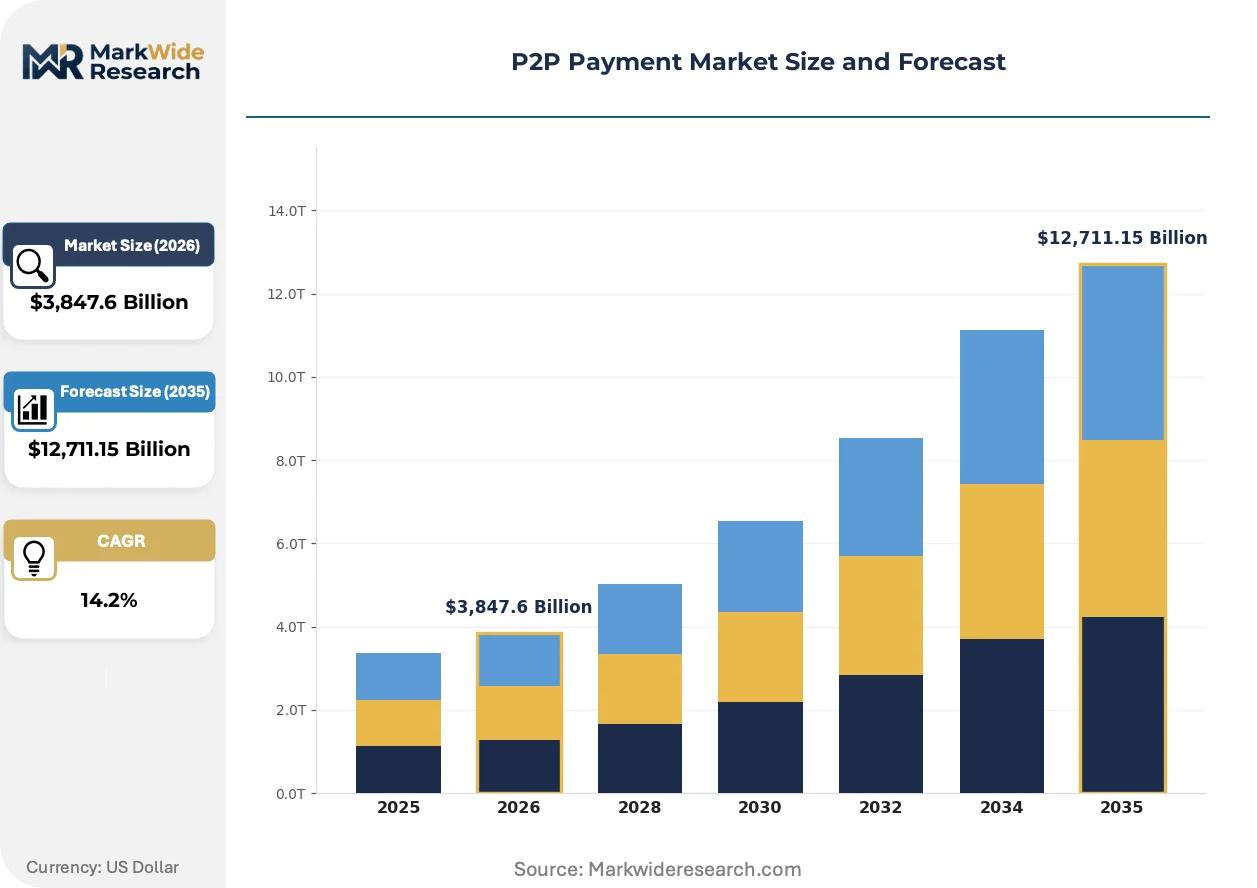
| Market Size in 2026 | $3,847.6 Billion |
| Market Size in 2035 | $12,711.15 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Wallets, Digital Bank Transfers, Payment Apps, Social Media Payments End User: Millennials, Small Businesses, Freelancers, Elderly Users Transaction Method: QR Code, NFC, Direct Bank Transfer, SMS Payment Payment Platform: iOS, Android, Web-Based, Desktop Applications |
| Companies Covered | PhonePe, Paytm, PayPal, Alipay, Revolut, Cash App, Google Pay, WeChat Pay, Venmo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
P2P Payment Market Emerging Trajectories
Tokenized credential vaulting and embedded finance modules are dissolving boundaries between payment rails and adjacent banking services, compressing the traditional value chain into unified super-app architectures.
AI-powered transaction monitoring is rewriting fraud detection economics. Machine learning models score risk in sub-100 millisecond windows, enabling instant approval for high-velocity P2P transfers. Southeast Asian platforms deploy these systems to serve thin-file customers lacking traditional credit histories, expanding addressable markets beyond legacy scoring boundaries.
The EU Payment Services Directive 2 mandates open-banking API standards that force platform interoperability. Banks must grant licensed third parties access to account data and initiation rights, dismantling proprietary payment silos. Fintech challengers leverage this regulatory tailwind to bypass card network rails entirely, shifting volume toward account-to-account settlement.
Social transaction feeds now function as customer acquisition channels rather than mere engagement features. Younger demographics in North American markets select payment apps based on feed visibility and group payment aesthetics, not fee structures. This behavioral pivot forces commodity P2P utilities to invest in content-layer differentiation or retreat to B2B infrastructure roles.
P2P Payment Market Segmentation
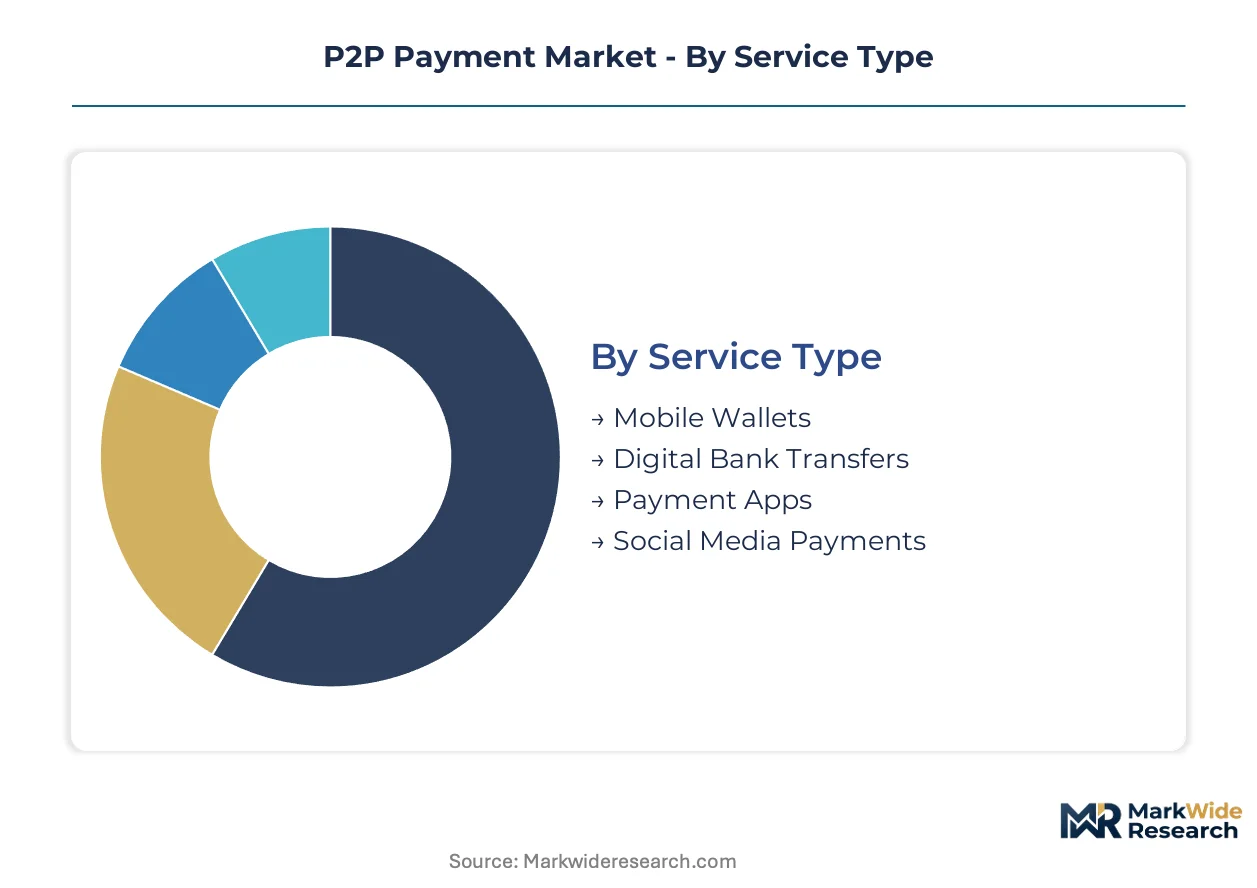
P2P payment architectures fragment across service interfaces, user demographics, and technical protocols. Each segmentation axis reveals distinct margin pools and regulatory exposure profiles that reshape platform investment priorities.
Service Type:
Supply concentration clusters around mobile-native architectures with embedded financial services, while legacy bank-linked rails fragment into commodity utilities.
- Mobile Wallets:Tokenized credential vaulting with sub-second settlement latency dominates transaction volume pools. Demand concentrates in India's urban corridors where RBI-mandated UPI interoperability forces API standardization across competing platforms.
- Payment Apps:Invoice financing attachments and tax automation modules capture the highest margin tier in the ecosystem. Freelancer-focused platforms in Southeast Asia deploy these features to monetize gig worker cash flow management needs.
- Digital Bank Transfers:Batch-oriented clearing infrastructure faces compression from real-time rails. The EU's PSD2 open-banking mandates enable account-to-account bypass of card networks for this segment.
- Social Media Payments:Transaction feeds function as customer acquisition channels through visibility and group payment aesthetics. Younger demographics in North American markets select platforms based on content-layer differentiation rather than fee structures.
Today's leader: Mobile Wallets. Tomorrow's challenger: Payment Apps.
End User:
Cost tier stratification separates high-margin freelancer tools from subsidized consumer utilities, with small business adoption accelerating fastest across emerging market corridors.
- Freelancers:Working capital products and automated tax compliance create the steepest expansion trajectory in user monetization. Platforms serving this segment attach invoice financing to payment flows, capturing premium yields unavailable in consumer P2P.
- Small Businesses:Instant settlement tools address working capital constraints for micro-merchants. Indonesia's unbanked street vendors pull low-cost QR acceptance hardware into mass deployment across urban corridors.
- Millennials:Social transaction visibility drives platform selection over functional fee comparison. Feed-based engagement features lock in this demographic through network effects rather than price competition.
- Elderly Users:Biometric authentication vaulting reduces onboarding friction for thin-file customers lacking traditional credit histories. Fingerprint and facial recognition displace password-based credentialing for this risk-averse segment.
Freelancer tools command premium pricing. Small business adoption scales fastest.
Transaction Method:
Volume distribution favors QR-based methods where NFC terminal penetration remains shallow, while direct bank transfer architectures gain share through regulatory tailwinds.
- QR Code:Low-cost acceptance hardware enables mass deployment among unbanked micro-merchants. Indonesia's urban corridor demand pulls this method into dominant position across Southeast Asian emerging markets.
- NFC:Contactless protocols face infrastructure gaps in emerging market POS environments. Terminal scarcity constrains premium wallet feature rollout where merchant acquisition costs exceed unit economics.
- Direct Bank Transfer:Account-to-account settlement bypasses card network interchange through open-banking API standards. The EU's PSD2 mandates force bank data access that dismantles proprietary payment silos for this rail.
- SMS Payment:Feature-phone compatibility extends reach beyond smartphone penetration boundaries. This method retains relevance in rural corridors where device upgrade cycles lag urban adoption patterns.
QR methods scale through hardware cost advantage. Direct bank transfers gain through regulatory interoperability mandates.
Payment Platform:
Customer type stratification separates mobile-native super-apps from desktop-anchored B2B infrastructure, with iOS and Android ecosystems competing on embedded finance integration depth.
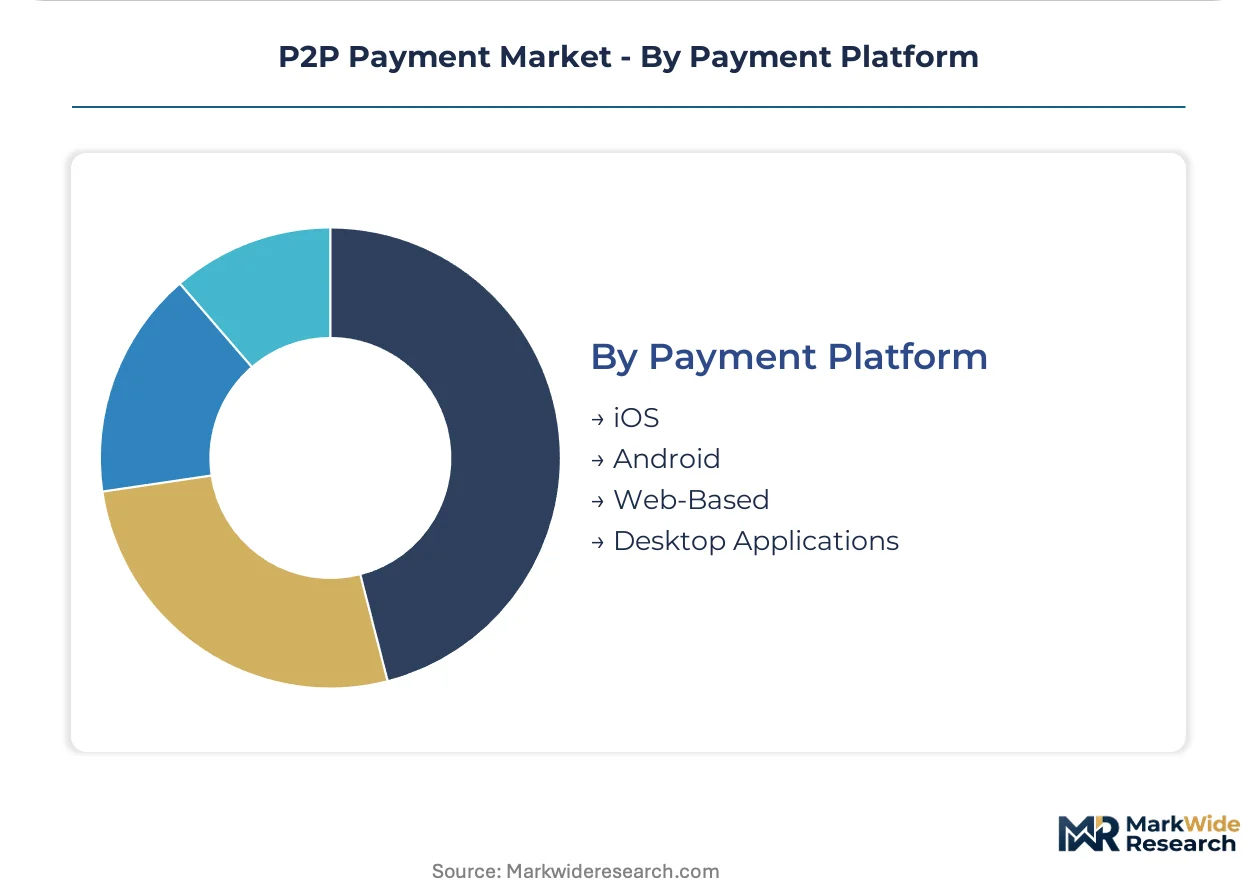
- Android:Open architecture enables deep OS-level integration for biometric authentication and tokenized credential vaulting. Market share concentration in emerging economies drives platform prioritization for QR-based merchant acceptance.
- iOS:Closed ecosystem enforces standardized security protocols that reduce fraud detection costs. Premium demographic concentration supports higher transaction value thresholds for instant settlement features.
- Web-Based:Cross-platform accessibility serves thin-file users without dedicated app installation. This interface captures residual volume from desktop-anchored B2B workflows and occasional-use consumer segments.
- Desktop Applications:Batch processing interfaces persist in enterprise treasury and accounting integrations. Real-time rail migration forces middleware complexity as legacy core systems adapt to sub-second settlement demands.
Android dominates emerging market volume. iOS captures premium transaction value density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's UPI developer concentration anchors Asia-Pacific innovation density, while Indonesia's QR merchant acquisition teams and the EU's open-banking compliance specialists distribute talent across complementary growth corridors.
India
RBI-mandated UPI interoperability and biometric authentication standards drive platform architecture decisions. The central bank's transaction caps and data localization rules force foreign operators to rebuild domestic server infrastructure. Bengaluru's fintech cluster concentrates engineering talent for real-time settlement rail development.
Indonesia
Unbanked micro-merchants across Jakarta and Surabaya urban corridors pull low-cost QR acceptance hardware into mass deployment. Bank Indonesia's merchant discount rate regulations compress interchange revenue per transaction. The Greater Jakarta area hosts the densest concentration of street vendor digital onboarding programs.
United States
Freelancer payment apps attach invoice financing and tax automation modules to capture premium yields. The CFPB scrutinizes earned-wage access products under Truth in Lending Act extensions. San Francisco and New York metro areas anchor venture funding for payroll-linked advance platforms.
Germany
PSD2-mandated open-banking API standards enable account-to-account payment bypass of card networks. BaFin supervision enforces strong customer authentication for P2P transaction initiation. Frankfurt's banking infrastructure cluster supports middleware development for real-time rail integration.
Singapore
Cross-border remittance corridors connecting Southeast Asian labor markets demand sub-second settlement latency. The Monetary Authority of Singapore's licensing framework for digital payment token operators attracts regional headquarters. The city-state's financial district concentrates compliance expertise for multi-jurisdiction platform deployment.
P2P Payment Market Vendor Landscape
Top-tier vendors anchor super-app ecosystems with embedded financial services, while commodity peer-to-peer rails fragment into single-purpose utilities. Market structure stratifies across three archetypes: cross-border merchant networks sustaining currency hedging infrastructure, Asia-Pacific merchant acquirers deploying embedded credit scoring, and social transaction platforms competing on feed-based engagement features. Dominant competitive moves include strategic partnerships for real-time clearing rail access and portfolio diversification into earned-wage advance products.
Within the Asia-Pacific acquisition tier, PhonePe and Paytm exemplify mobile-native platforms navigating RBI-mandated interoperability requirements. PayPal occupies a position representing cross-border merchant network archetypes with currency infrastructure investments. These three anchors illustrate how regulatory compliance capabilities and settlement architecture choices differentiate competitive positioning across fragmented national regimes.
| Leading Market Players |
|---|
| PhonePe |
| Paytm |
| PayPal |
| Alipay |
| Revolut |
| Cash App |
| Google Pay |
| WeChat Pay |
| Venmo |
| Others |
Supply Flow & Price Mechanics
Freelancer payment platforms anchor premium pricing power through invoice financing attachments, while QR-based merchant utilities compete on transaction volume economics across Southeast Asian urban corridors.
Pricing Analysis
Bundled super-app ecosystems command subscription and interchange-based revenue models, while unbundled P2P rails fragment into per-transaction fee structures. Three-tier pricing structure across premium, standard, and economy levels differentiates by settlement speed and embedded credit access. Pricing pressure stems from India's RBI-mandated merchant discount rate caps and Indonesia's interchange compression regulations. Micro-merchants in emerging markets exhibit highest price sensitivity, while freelancer tools in North America demonstrate lowest elasticity due to working capital product stickiness.
Supply Chain Analysis
Cross-border settlement infrastructure draws heavily from Singapore's financial district licensing hubs and India's Bengaluru engineering clusters, with middleware development concentrated in Germany's Frankfurt banking corridor. Critical inputs include biometric authentication modules, tokenized credential vaulting software, and real-time clearing rail APIs. Single-source vulnerability concentrates in India's UPI protocol stack, where RBI-mandated interoperability creates dependency on domestic server infrastructure. Distribution runs through mobile-native app stores and embedded banking partnerships rather than traditional hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The P2P payment market functions as a stable compounder, with regulatory interoperability mandates across India, the EU, and Southeast Asia generating sustained infrastructure replacement cycles.
For Market Incumbents: To counter fintech challengers exploiting open-banking API standards, incumbent platforms should deepen backward integration into real-time clearing rail access and fortify certification investment for biometric KYC compliance across fragmented national regimes. For New Entrants and Emerging Players: Enter via earned-wage access product white space in the US market under CFPB Truth in Lending Act extensions, targeting payroll-linked advance platforms with compliant architecture and tax automation module attachments as the primary go-to-market angle. For Investors and Strategic Acquirers: Payment infrastructure specialists are the most active acquirer in this space, consolidating middleware capabilities for real-time settlement integration. The long-term viability window favors platforms with multi-jurisdiction compliance architecture. Watch RBI transaction cap adjustments as the key inflection signal for India market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Clearing Rail Access Partnership | Sub-second settlement latency enables competitive positioning against India's UPI-native platforms. |
| Biometric KYC Certification Investment | Fingerprint and facial recognition vaulting satisfies RBI, EU PSD2, and Indonesia's authentication mandates. |
| Freelancer Invoice Financing Module Launch | Working capital attachments capture premium yields unavailable in commodity P2P transaction flows. |
| Earned-Wage Access Product Development | CFPB-compliant payroll-linked advances address regulatory scrutiny while opening white-space revenue. |
| QR Merchant Acquisition Hardware Deployment | Low-cost acceptance devices penetrate Indonesia's unbanked street vendor corridors at scale. |
Methodological Framework
Bottom-up freelancer and micro-merchant demand modeling reconciled against top-down payment rail infrastructure tracking forms the analytical core of this study. Primary interviews with platform engineering leads, regulatory compliance officers at RBI and BaFin, merchant acquisition managers, and treasury product directors combined with secondary validation from SEC filings, central bank policy circulars, and app store download analytics. Triangulation across these sources ensures segmentation integrity for mobile wallet, payment app, and social media payment architectures.
Historical trendline analysis of settlement latency compression and interchange rate trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include service interface type, end-user archetype, transaction protocol, and platform ecosystem, with CAGRs derived from regression against real-time rail penetration curves and biometric authentication adoption rates. Forecast inputs incorporate UPI transaction volume trajectories and PSD2 open-banking API deployment timelines.
The model holds under sustained regulatory interoperability mandates and stable central bank digital payment policies; deviation in data localization enforcement intensity or merchant discount rate cap adjustments would shift volume projections. Stakeholders should weight assumptions against their own operating context and jurisdiction-specific compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Israel Credit Cards Market
Payments
Sweden Mobile Payments Market
Payments
North America Mobile Payments Market
Payments
Canada Payment Gateway Market
Payments
Online Payment Gateway Market
Payments
Japan Payment Gateway Market
Payments
Credit Card Issuance Services Market
Payments
Payment Security Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Wireless POS Terminals Market
Payments
Hong Kong Payments Market
Payments
Latin America Subscription and Billing Management Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Cyprus POS Terminals Market
Payments
GCC Payment Gateway Market
Payments
Payment Card Market