
 B2C Payment Market | 2026-2036
B2C Payment Market Size, Share, and Industry Trends Forecast 2026-2036
B2C Payment Market Analysis
Real-time payment rails and embedded finance APIs is rewriting how consumer transactions clear and settle across merchant ecosystems. Visa leverages its tokenization infrastructure to anchor security standards for card-not-present commerce. Stripe competes through developer-first tooling that extends checkout customization to mid-market platforms. Adyen differentiates via a single-platform architecture that unifies online, in-store, and mobile payment acceptance.
B2C payment denotes electronic value transfer mechanisms enabling consumers to purchase goods and services from businesses, encompassing authorization protocols, settlement networks, and fraud detection algorithms operating within sub-second latency thresholds. Digital wallet and contactless technology segments are capturing disproportionate growth as NFC-enabled point-of-sale terminals reach saturation in developed markets and QR-code-based solutions proliferate in emerging economies. Credit card infrastructure sustains dominant transaction value globally, though mobile payment volumes are expanding fastest where banking penetration lags smartphone adoption.
The US Federal Reserve's FedNow service, the EU's PSD2 open-banking mandates, and India's RBI-operated UPI framework are collectively mandating interoperable, low-cost settlement infrastructure that reduces merchant acquirer concentration. GDPR in Europe and state-level privacy statutes in the US impose data-localization requirements that complicate cross-border payment routing. Stakeholders must monitor how central bank digital currency pilots in Brazil, India, and the European Union reshape consumer payment preferences and merchant fee structures.
Market Dynamics
Real-time payment rails and embedded finance APIs are compressing settlement latency from days to sub-second intervals, forcing merchant acquirers to abandon legacy batch-processing architectures or cede volume to API-native platforms.
Growth Catalysts
- UPI protocol expansion:India's RBI-operated framework enables instant peer-to-merchant transfers without card network intermediation, accelerating financial inclusion among smartphone-first consumers.
- PSD2 open banking mandates:The EU's regulatory framework forces incumbent banks to expose account data via standardized APIs, enabling third-party payment initiation services.
- Contactless terminal saturation:NFC-enabled point-of-sale infrastructure in developed markets is displacing magnetic-stripe and chip-and-signature workflows at physical retail locations.
Market Restraints
- Data-localization compliance costs:GDPR in Europe and state-level privacy statutes in the US impose jurisdictional storage requirements that fragment cloud infrastructure and inflate operational overhead.
- Merchant acquirer concentration:Dominant processors control interchange fee schedules, limiting margin compression for smaller payment service providers.
- QR-code interoperability gaps:Proprietary closed-loop wallet protocols in emerging markets prevent seamless cross-platform transactions.
Strategic Opportunities
- Central bank digital currency pilots:Brazil's Drex initiative and India's digital rupee experiments create new settlement rails that could disintermediate traditional card networks.
- Embedded finance convergence:Buy-now-pay-later APIs and insurance micro-products are integrating directly into e-commerce checkout flows.
- Unbanked urban corridors:Digital wallet penetration among cash-dependent consumers in Southeast Asian metropolitan clusters offers first-mover acquisition potential.
Industry Challenges
- Legacy core banking integration:Real-time settlement protocols require expensive middleware development to connect with decades-old mainframe systems.
- Fraud model recalibration:Sub-second authorization windows compress the latency budget for machine-learning risk scoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B2C Payment Market |
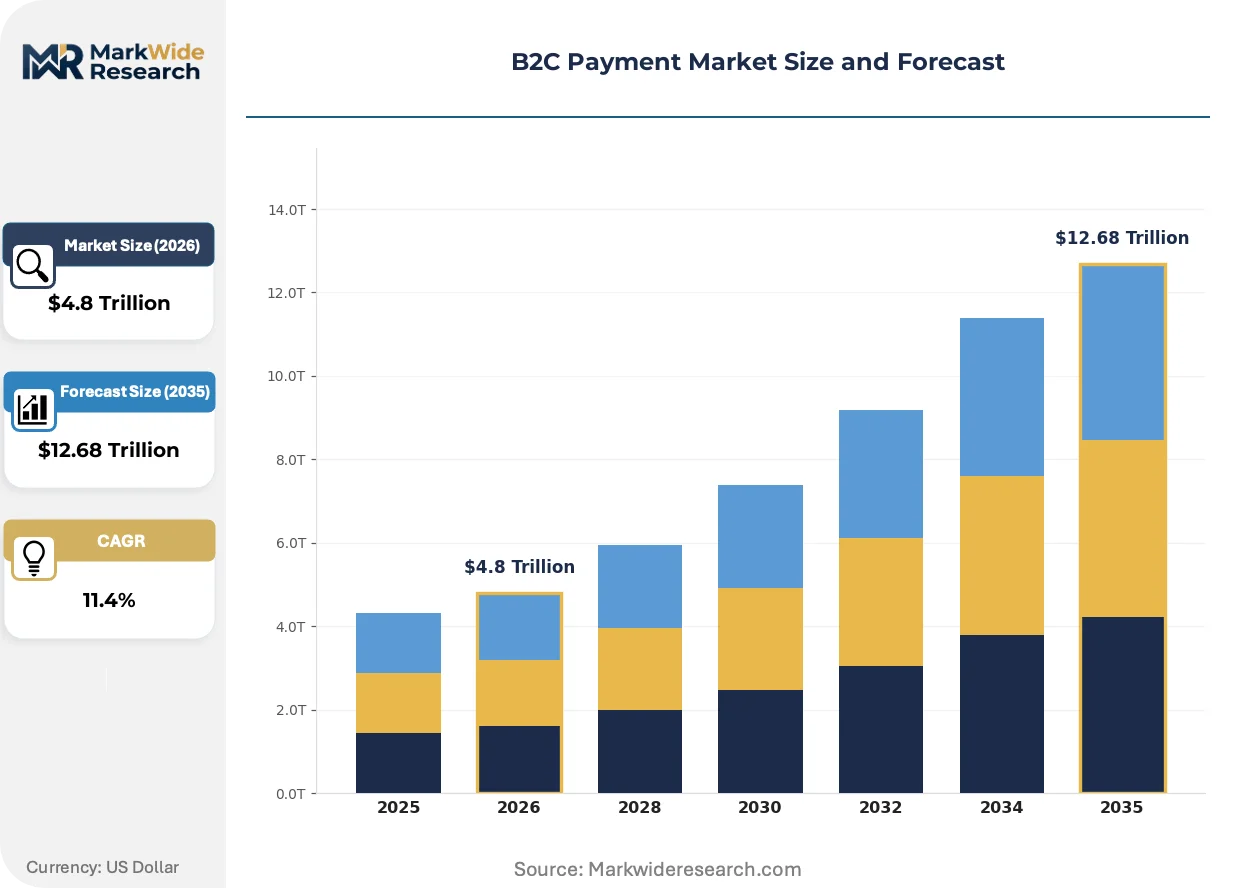
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $12.68 Trillion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer Transaction Type: Mobile Payment, Online Payment, In-Store Payment, Recurring Payment Customer Type: Individual Customer, Small Business, Freelancers, E-commerce Platforms Technology: Contactless, QR Code, NFC, Blockchain |
| Companies Covered | Visa, Block, PayPal, BlueSnap, Rapyd, Stripe, Mastercard, Revolut, Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B2C Payment Market Emerging Trajectories
Payment infrastructure is fragmenting across competing settlement protocols while merchant-facing interfaces consolidate toward unified commerce platforms. Three forces are compressing competitive timelines.
Tokenization technology is virtualizing cardholder data into cryptographically secure substitutes that render raw primary account numbers obsolete. E-commerce merchants and mobile wallet providers are adopting network tokens at accelerating velocity. This virtualization is collapsing the fraud liability exposure that previously justified high interchange fees.
The EU's Digital Operational Resilience Act imposes strict uptime and incident-reporting requirements on payment service providers. Financial institutions must rearchitect cloud deployments to meet continuity thresholds. European neobanks and payment institutions are responding by diversifying across multiple infrastructure regions.
Consumer checkout preferences are rotating toward invisible payment experiences where authentication occurs through biometrics or device-bound credentials. Ride-hailing and food-delivery apps are eliminating explicit payment confirmation steps. This pattern is most pronounced in South Korean and Chinese super-app ecosystems where embedded wallets dominate.
B2C Payment Market Segmentation
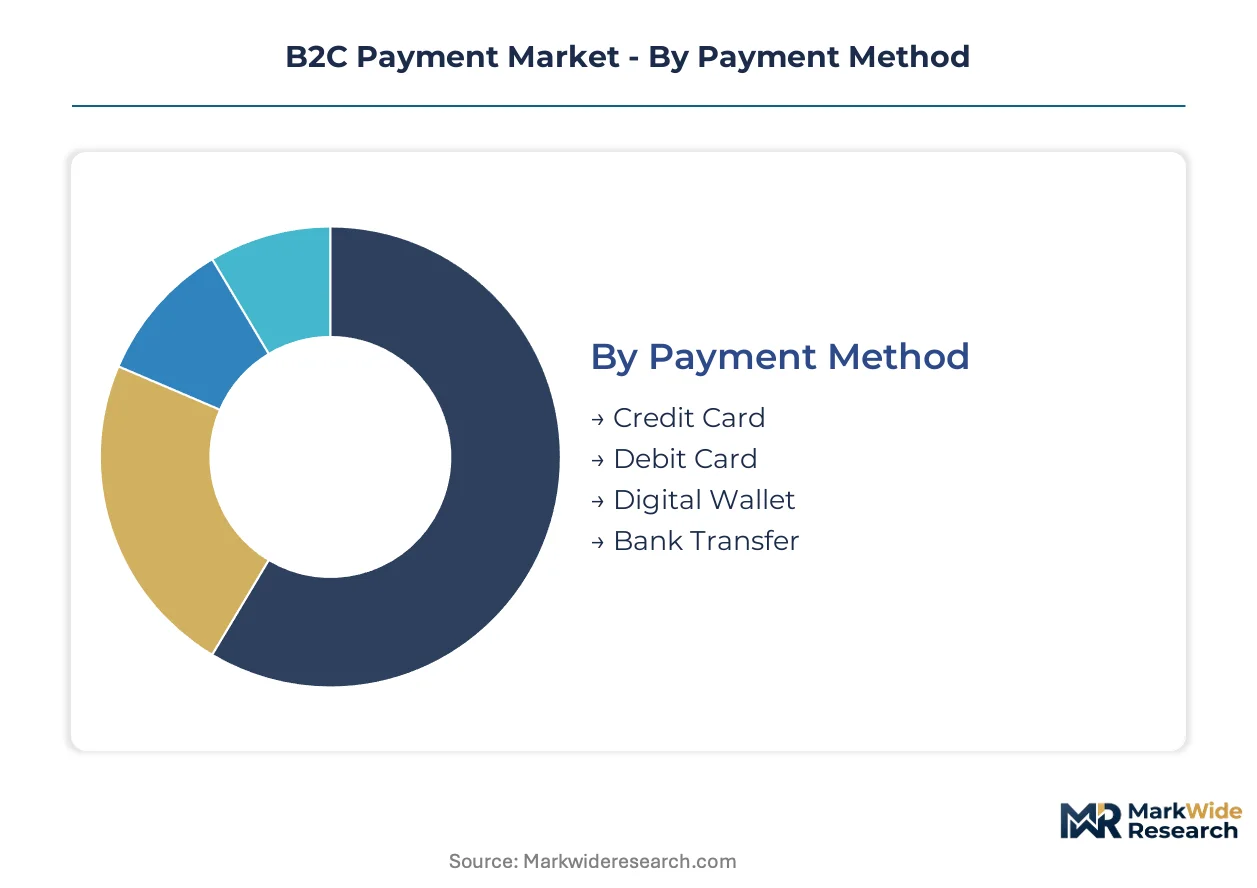
Payment infrastructure fragmentation demands granular segmentation to identify where transaction volumes concentrate and which rails are displacing legacy settlement. Methodology distinctions reveal divergent growth trajectories across consumer touchpoints and underlying technical protocols.
Payment Method:
Mature card networks coexist with emerging real-time account-to-account transfers as regulatory mandates reshape cost structures.
- Credit Card:Revolving credit lines issued by banking networks carry interchange fees that fund reward programs and fraud protection. US merchants absorb these costs while Brazilian regulators cap rates to expand acceptance among small retailers.
- Debit Card:Direct account deduction instruments process through PIN or signature verification, dominating US grocery and fuel purchases where consumers avoid credit utilization. India's RuPay network displaces international schemes on domestic transactions.
- Digital Wallet:Tokenized credential storage enables smartphone-based checkout across e-commerce and physical terminals.
- Bank Transfer:ACH and wire protocols settle directly between depositories, bypassing card network intermediation.
Credit cards handle the majority of throughput; digital wallets are climbing the fastest on share.
Transaction Type:
Volume distribution tracks device penetration patterns and merchant integration depth across physical and virtual commerce.
- Mobile Payment:Smartphone-originated transactions leverage device-bound biometrics and token vaults, commanding Southeast Asian urban corridors where super-apps embed financial services. South Korea's transportation and retail ecosystems run almost exclusively on Samsung Pay and KakaoPay rails.
- Online Payment:Browser or app-based checkout flows integrate hosted fields, redirect authentication, and embedded finance APIs. German consumers favor Sofortüberweisung bank redirects over card entry at e-commerce checkouts.
- In-Store Payment:Physical terminal acceptance spans chip, contactless tap, and magnetic stripe fallback.
- Recurring Payment:Credential-on-file billing supports subscription services and utility auto-debit arrangements.
Online payments sustain the largest absolute flow; mobile payments are expanding most quickly where smartphone penetration outpaces legacy point-of-sale replacement cycles.
Customer Type:
Entity scale determines fraud tolerance, integration complexity, and negotiating leverage with acquirers.
- Individual Customer:Single-user accounts drive peer-to-merchant volume through personal banking credentials and stored wallet balances. India's UPI protocol processes billions of monthly person-to-merchant transfers at zero direct cost to users.
- Small Business:Sole proprietorships and micro-enterprises aggregate personal and commercial transaction flows through simplified onboarding platforms. Brazil's PIX instant payment system enables street vendors to receive QR-code settlements without merchant accounts.
- Freelancers:Independent contractors require cross-border receipt capabilities and multi-currency settlement.
- E-commerce Platforms:Marketplace operators aggregate thousands of sub-merchant transactions through unified master merchant agreements.
E-commerce platforms concentrate transaction value density; freelancers represent the steepest expansion trajectory as gig economy participation scales.
Technology:
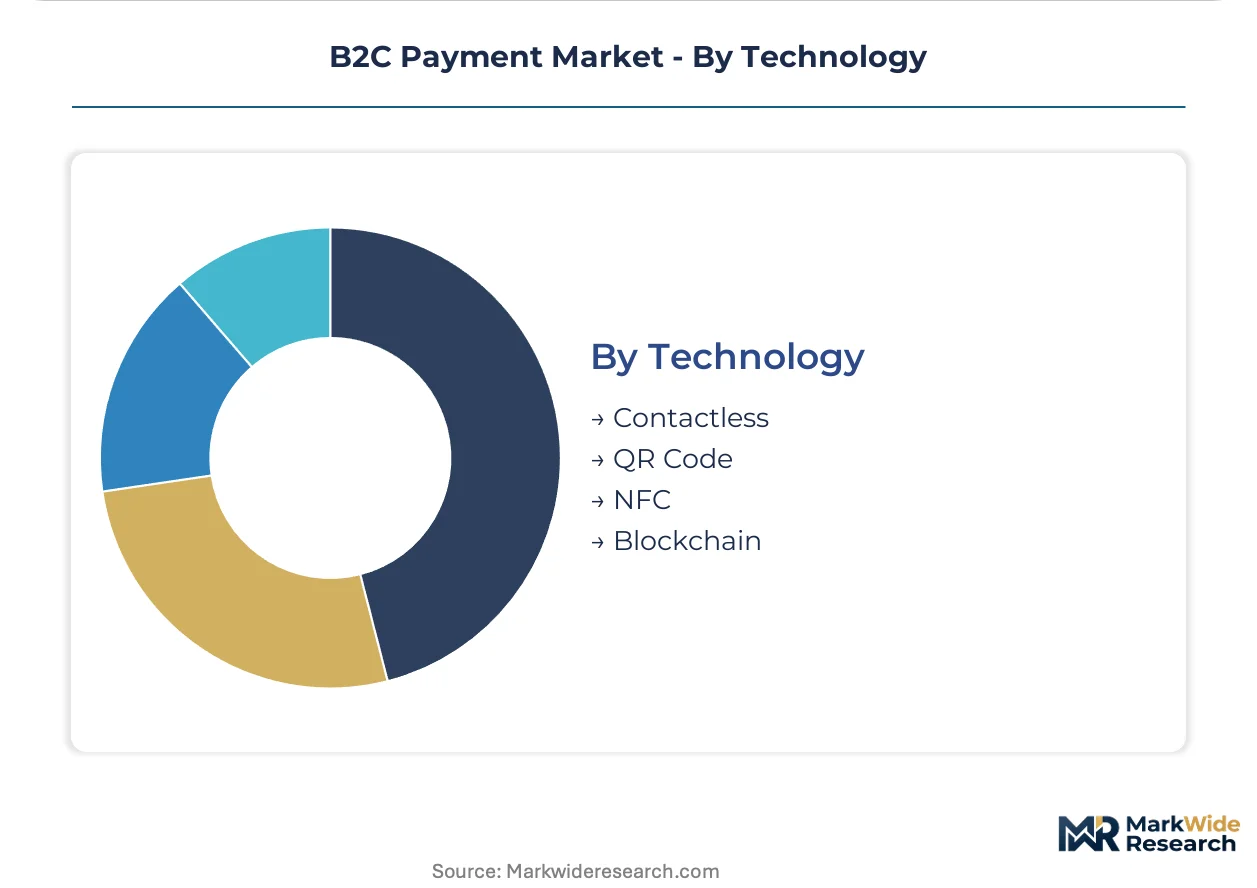
Physical interface standards and distributed ledger architectures compete for authentication and settlement roles.
- Contactless:Near-field electromagnetic coupling enables tap-to-pay at distances under four centimeters, saturating London and Tokyo transit gates where throughput speed determines modal choice. Visa and Mastercard mandate terminal compliance deadlines that accelerate merchant hardware refresh.
- QR Code:Optical machine-readable patterns encode payment instructions for camera-based capture, dominating Indonesian and Vietnamese street commerce where smartphone prevalence exceeds terminal infrastructure investment.
- NFC:Short-range radio frequency protocols support card emulation and peer-to-peer transfer modes.
- Blockchain:Distributed consensus mechanisms enable cryptocurrency settlement and programmable money contracts.
Contactless terminals process the highest transaction frequency; QR codes are gaining share fastest in emerging market corridors with infrastructure gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's UPI protocol exports real-time settlement architecture to Singapore and the UAE, reshaping cross-border remittance corridors across South and Southeast Asia. Brazil's PIX instant payment system influences Latin American interoperability standards. European open banking frameworks attract Middle Eastern regulatory attention.
United States
FedNow real-time settlement rails and contactless terminal saturation drive transaction volume growth. The Federal Reserve mandates instant payment availability for depository institutions. New York and San Francisco fintech clusters concentrate API-native payment platform development.
India
Smartphone-first consumers and zero-merchant-fee UPI person-to-merchant transfers accelerate financial inclusion. The Reserve Bank of India operates the UPI protocol and pilots the digital rupee. Mumbai and Bengaluru urban corridors process billions of monthly QR-code transactions.
Brazil
Digital wallet penetration among unbanked urban consumers and PIX instant settlement displace cash-dependent street commerce. The Central Bank of Brazil manages the Drex CBDC pilot and PIX infrastructure. São Paulo metropolitan vendors adopt QR-code acceptance without traditional merchant accounts.
Germany
Sofortüberweisung bank redirects and PSD2 open banking APIs reshape e-commerce checkout preferences. The Federal Financial Supervisory Authority enforces PSD2 compliance and strong customer authentication. Berlin and Frankfurt payment institutions diversify cloud deployments under Digital Operational Resilience Act requirements.
Singapore
Cross-border payment linkages with India and Thailand expand real-time settlement networks. The Monetary Authority of Singapore licenses digital payment token providers and regulates stablecoin issuance. The city-state's fintech hub anchors Southeast Asian embedded finance API development.
B2C Payment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across acquiring, issuing, and network layers. Card network incumbents anchor security standards through tokenization infrastructure while API-native platforms capture mid-market merchant volume. Two strategic archetypes dominate: developer-first checkout toolkits and unified commerce platforms spanning online, in-store, and mobile acceptance. Competitive moves concentrate on embedded finance partnerships and real-time settlement protocol integration.
Within the network infrastructure tier, Visa and Mastercard anchor global tokenization and fraud protection standards. Among developer-first platforms, Stripe exemplifies API-native checkout customization. Adyen occupies a position as a unified commerce architecture provider. These three represent distinct competitive vectors: incumbent network security, developer tooling depth, and omnichannel platform consolidation.
| Leading Market Players |
|---|
| Visa |
| Block |
| PayPal |
| BlueSnap |
| Rapyd |
| Stripe |
| Mastercard |
| Revolut |
| Adyen |
| Others |
Supply Flow & Price Mechanics
Mumbai's fintech corridor anchors payment processing capacity for South Asian transaction volumes, concentrating merchant acquirer infrastructure that translates into downstream pricing leverage for network tokenization services. This geographic concentration shapes how interchange fee compression propagates through issuer-processor relationships.
Pricing Analysis
Legacy card-present infrastructure commands premium pricing against API-native real-time rails and next-generation CBDC settlement protocols. Three-tier pricing structure across premium tokenization, standard gateway services, and economy QR-code processing dominates merchant fee schedules. Price differentiation rests on fraud liability allocation and settlement speed guarantees. Small retailers in Brazil exhibit highest price sensitivity, while multinational e-commerce platforms absorb premium tiers for unified commerce coverage.
Supply Chain Analysis
TSMC and Samsung Foundry hold concentrated capacity for secure element chip fabrication powering NFC terminals and hardware security modules. Taiwan, South Korea, and Vietnam anchor semiconductor supply for payment terminal manufacturing. Raw material dependencies include silicon wafers, rare earth magnets for contactless antennas, and cobalt for battery-powered portable terminals. Single-source vulnerability in advanced node chip production threatens terminal refresh cycles. Distribution runs through OEM terminal manufacturers, merchant acquirer provisioning networks, and direct-to-merchant API integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
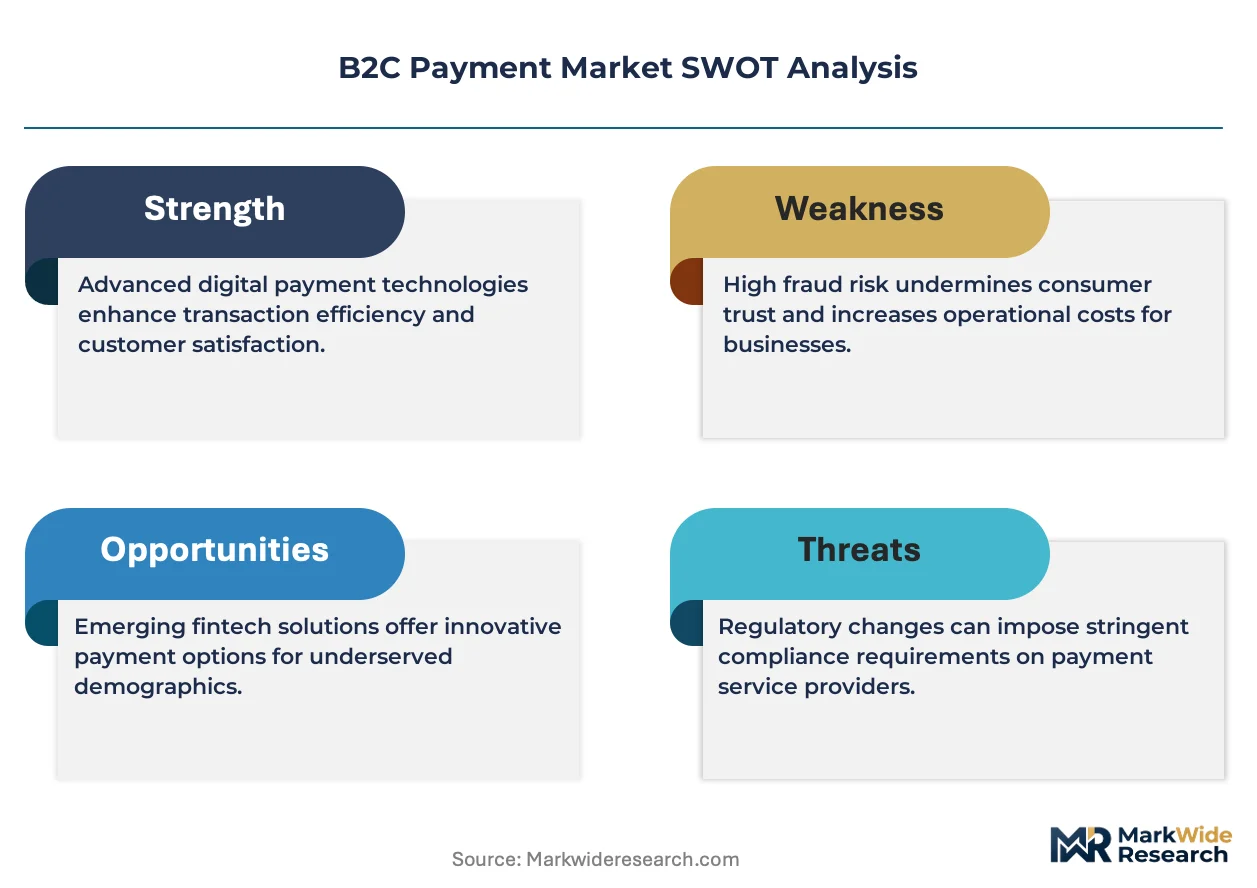
This market functions as a defensive-moat story where network effects in tokenization infrastructure create regulatory entrenchment that new entrants cannot easily replicate.
For Market Incumbents: Pre-empt API-native platform encroachment by embedding real-time settlement protocols into legacy core banking middleware before FedNow and UPI-style architectures disintermediate card networks. Consolidate fraud scoring capabilities through strategic certification investments in biometric authentication standards. Vertical integration into cloud infrastructure regions mitigates GDPR localization compliance costs. For New Entrants and Emerging Players: Pursue unbanked urban corridors in Southeast Asian metropolitan clusters where smartphone penetration outpaces terminal infrastructure investment. Target freelance and gig-economy payment receipt as the most penetrable segment, exploiting incumbent blind spots in cross-border multi-currency settlement. Developer-first checkout toolkits offer the strongest go-to-market angle against unified commerce incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because real-time settlement rails exhibit natural monopoly characteristics once regulatory mandates cement interoperability standards. Acquisition targets should concentrate on API-native platforms with embedded finance integration depth. Monitor central bank digital currency pilot expansion as the critical inflection signal for network disintermediation risk.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Rail Integration | FedNow and UPI protocol adoption forces legacy batch-processing abandonment. |
| Tokenization Infrastructure Expansion | Network token vaults reduce fraud liability exposure that justifies interchange premiums. |
| Embedded Finance Partnership | Buy-now-pay-later APIs integrate directly into e-commerce checkout flows. |
| Biometric Authentication Investment | Device-bound credentials enable invisible payment experiences in super-app ecosystems. |
| Cloud Infrastructure Diversification | EU Digital Operational Resilience Act mandates multi-region deployment for continuity. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, central bank payment system reports, and hyperscaler capex disclosures with structured interviews across payment network executives, merchant acquirer operations leads, fintech platform engineers, and regulatory policy specialists. Bottom-up transaction volume modeling triangulates against top-down macroeconomic consumption indicators.
Forecast inputs span payment method migration curves, terminal infrastructure replacement cycles, and regulatory mandate implementation timelines across the projection horizon. Segmentation dimensions include payment instrument type, transaction channel, merchant scale tier, and settlement protocol architecture. CAGRs derive from S-curve adoption modeling applied to real-time payment penetration rates and digital wallet user growth trajectories.
Sensitivities concentrate around central bank digital currency issuance timelines, interchange fee regulatory caps, and data-localization mandate expansion. Quarterly review of UPI transaction volume trends, PIX merchant adoption rates, and FedNow depository institution participation metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Convergent Billing Market
Payments
Transaction Monitoring Market
Payments
Uganda Mobile Money Market
Payments
Denmark Mobile Payments Market
Payments
Spain Payments Market
Payments
Fingerprint Payment Market
Payments
Argentina Payments Market
Payments
Middle East and Africa Payments Market
Payments
Global Financial Cards and Payments Market
Payments
Germany Mobile Payments Market
Payments
Middle East and Africa Prepaid Card Market
Payments
NFC Payments Market
Payments
Europe POS Terminal Market
Payments
Money Transfer Agencies Market
Payments
Italy Gift Cards Market
Payments
Asia Pacific POS Terminal Market