
 Global Virtual Cards Market | 2026-2036
Global Virtual Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Cards Market Foresight
Singapore is tilting toward virtual card infrastructure expansion as regional banks and fintechs establish Asia-Pacific processing hubs. Mastercard Inc. leverages its tokenization network to secure digital-first card credentials across merchant categories. Visa Inc. sustains programmable spending controls that appeal to corporate treasury departments seeking granular budget enforcement. Marqeta, Inc. specializes in API-native card issuance that lets platforms embed virtual cards within hours rather than months.
A virtual card is a digitally generated payment credential bearing a unique card number, expiration date, and security code, issued without physical plastic and typically provisioned through tokenized mobile wallets or browser extensions. The credential draws from a pre-funded balance or existing credit line and routes transactions through standard card networks while masking the underlying funding source. Single-use credentials dominate fraud-sensitive applications such as vendor onboarding and one-time procurement, while multi-use reloadable formats anchor recurring subscription management and employee spend programs. Corporate enterprises represent the deepest margin pool due to interchange revenue from high transaction volumes and SaaS-based expense management attach rates.
The European Banking Authority enforces PSD2 Strong Customer Authentication requirements that mandate multi-factor verification for virtual card transactions above threshold limits, elevating compliance costs for issuers while reducing unauthorized chargebacks. India's Reserve Bank India governs prepaid payment instrument licensing through the PPI framework, restricting cross-border virtual card flows without explicit authorization and channeling domestic fintech innovation toward rupee-denominated closed-loop products. The US Federal Reserve's FedNow instant payment network creates interoperability pressure on card networks to demonstrate speed advantages over account-to-account transfers. Stakeholders must weigh tokenization patent positions against open banking account-linking models as the primary interface for B2B payment initiation.
Market Dynamics
Tokenization infrastructure and real-time payment rails are compressing issuance timelines from months to hours, forcing card networks and fintech platforms to compete on API latency and programmable control granularity rather than brand recognition alone.
Growth Catalysts
- PSD2 Strong Customer Authentication:European mandates for multi-factor verification have normalized secure credential provisioning, reducing fraud friction and accelerating corporate treasury adoption of virtual card programs for vendor payments.
- Employee expense management digitization:Corporate enterprises are consolidating travel, procurement, and subscription spend onto single platforms that embed virtual credentials with granular budget controls and real-time reconciliation.
- API-native issuance infrastructure:Open banking standards enable platforms to provision tokenized credentials through REST endpoints, collapsing integration cycles and expanding addressable markets to mid-market SaaS providers.
Market Restraints
- Cross-border licensing fragmentation:India's RBI prepaid payment instrument framework restricts rupee-denominated virtual cards from international routing without explicit authorization, forcing issuers to maintain separate domestic and offshore credential stacks.
- Interchange compression risk:The US Federal Reserve's FedNow instant payment network creates price pressure on card networks to demonstrate value-add beyond raw transaction speed, threatening revenue per transaction in B2B corridors.
- Tokenization patent thickets:Proprietary vaulting and credential generation IP held by incumbent networks creates licensing friction for new entrants seeking network-agnostic issuance capabilities.
Strategic Opportunities
- Underpenetrated SMB segments in India:Digital payment maturity gaps among small and medium businesses present white space for rupee-denominated closed-loop products with embedded working capital features.
- Convergence of virtual cards and embedded finance:Platforms integrating tokenized credentials with accounting software and ERP systems can capture interchange revenue and SaaS attach rates simultaneously.
- Singapore hub infrastructure:Regional banks and fintechs establishing Asia-Pacific processing centers can leverage the city-state's regulatory clarity to serve cross-border B2B payment corridors with unified compliance frameworks.
Industry Challenges
- Legacy core banking integration:Traditional issuers face months-long reconfiguration cycles to connect virtual card APIs to decades-old ledger systems, delaying product launches and ceding ground to cloud-native competitors.
- Compliance talent scarcity:Shortages of professionals versed in PSD2 technical standards, RBI PPI licensing, and multi-jurisdiction AML frameworks are extending time-to-market for new credential programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Cards Market |
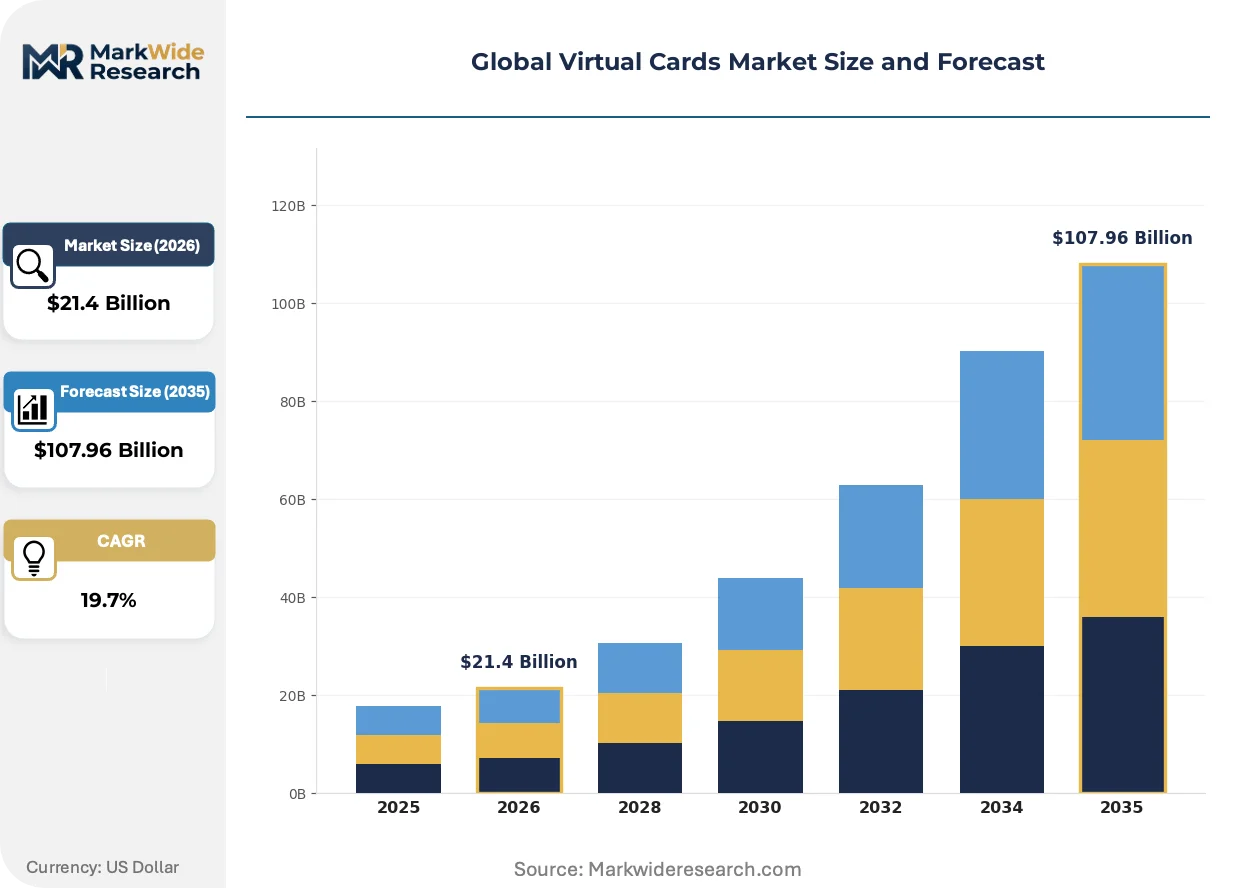
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $107.96 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Single-Use, Multi-Use, Reloadable, Disposable End User: Corporate Enterprises, Freelancers, Payment Service Providers, Financial Institutions Deployment Mode: Cloud-Based, On-Premise, Hybrid, API Integration Application: Expense Management, E-Commerce Payments, Vendor Payments, Travel & Entertainment |
| Companies Covered | Mastercard Inc., Visa Inc., American Express Company, JPMorgan Chase & Co., Marqeta, Inc., Stripe, Inc., Adyen, Revolut Ltd., Airwallex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Cards Market Shifts & Advancements
Programmable spending controls and network tokenization are converging to create credentials that enforce policy at the transaction level, shifting competitive differentiation from issuance volume to real-time authorization intelligence.
Network tokenization is hybridizing static primary account numbers with dynamic cryptograms that rotate per transaction. Corporate treasury departments are adopting these credentials for high-risk vendor onboarding and one-time procurement scenarios. The technology is compressing fraud liability exposure while enabling issuers to command premium interchange on credential types with embedded policy enforcement.
The European Banking Authority's PSD2 Strong Customer Authentication mandates are elevating baseline security requirements for all card-not-present transactions above threshold limits. Issuers must now maintain multi-factor verification flows that add latency to authorization paths. Corporate virtual card programs in the European Union are responding by pre-authenticating credential holders through biometric mobile wallets, reducing checkout friction while maintaining compliance.
Subscription management procurement patterns are displacing traditional corporate card programs that rely on post-hoc expense reporting. Finance teams are unbundling vendor payments from employee reimbursements, routing recurring software spend through dedicated virtual credentials with hard-coded merchant locks and spend ceilings. This shift is most visible in United States technology sector procurement, where SaaS vendor proliferation has overwhelmed legacy expense management workflows.
Global Virtual Cards Market Segmentation
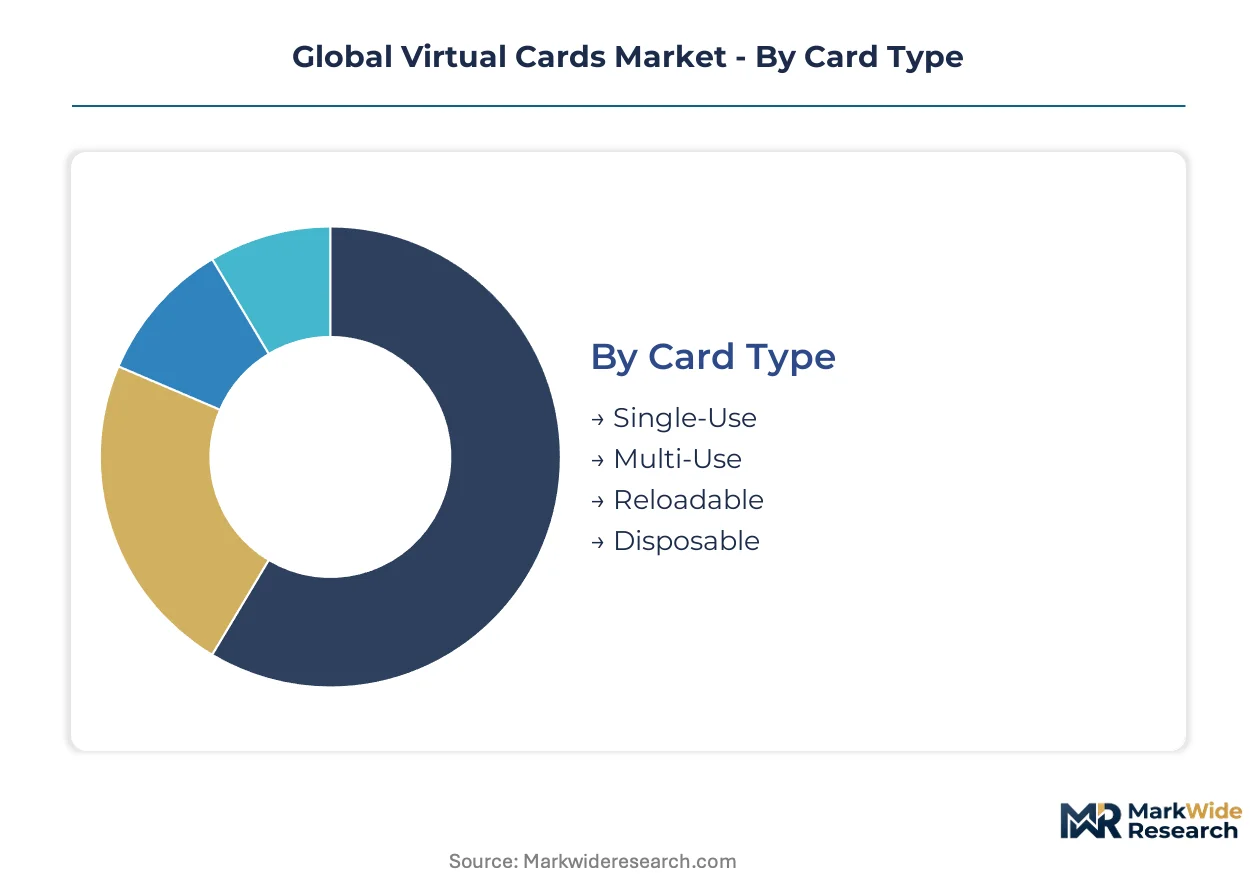
Virtual card market segmentation reveals divergent velocity profiles across credential types and deployment architectures. Issuers optimize working capital cycles differently for single-use fraud-sensitive credentials versus multi-use recurring instruments. Understanding these turnover dynamics enables platform architects to align tokenization infrastructure with specific revenue and risk models.
Card Type:
Single-use credentials clear authorization queues within seconds of generation, while reloadable products sustain multi-year account relationships with periodic funding events.
- Single-Use:Dynamically generated credentials with cryptograms valid for one transaction only. Corporate procurement teams in the United States deploy these for vendor onboarding where fraud exposure peaks during initial credential exchange.
- Multi-Use:Persistent digital credentials supporting predetermined transaction counts or merchant categories. European treasury departments under PSD2 mandates favor these for subscription management with embedded spending ceilings.
- Reloadable:Accounts accepting repeated funding through linked bank rails or card loads. India's PPI-licensed fintechs concentrate here for SMB working capital products restricted to domestic rupee corridors.
- Disposable:Time-bound credentials expiring after fixed windows regardless of use status. Travel platforms issue these for per-diem allowances with automatic deactivation post-trip.
Multi-use credentials anchor the volume base while single-use formats gain share at the steepest rate.
End User:
Cost tier stratification separates high-interchange corporate programs from thin-margin freelancer solutions with minimal SaaS attach potential.
- Corporate Enterprises:Organizations consolidating travel, procurement, and software spend onto unified platforms. These customers command premium interchange rates and drive API-native issuance volume in the United Kingdom and United States.
- Freelancers:Independent professionals requiring segregated business credentials without formal entity structures. European neobanks target this segment with instant-provisioned credentials linked to personal current accounts.
- Payment Service Providers:Intermediaries embedding virtual cards as white-label infrastructure for downstream clients. Singapore-based regional hubs serve these entities across Asia-Pacific corridors.
- Financial Institutions:Traditional banks retrofitting legacy core systems with tokenized credential programs. India's public sector banks face extended integration timelines due to decades-old ledger architectures.
Corporate enterprises dominate revenue concentration while payment service providers expand most quickly as embedded finance penetration deepens.
Deployment Mode:
Application maturity varies from hours-long API integrations to months-long on-premise core banking reconfigurations.
- Cloud-Based:Fully managed issuance infrastructure with network tokenization handled by platform operators. Marqeta and similar providers enable provisioning within hours through REST endpoints.
- On-Premise:Self-hosted vaulting and credential generation within bank data centers. Traditional issuers in Europe maintain these for PSD2 audit trail requirements despite higher operational overhead.
- Hybrid:Split architectures with sensitive operations on-premise and scale functions cloud-resident. United States regional banks adopt this to balance FedNow interoperability pressure with compliance control.
- API Integration:Direct embedding of virtual card capabilities into accounting software and ERP systems. SaaS platforms in India leverage this for SMB market penetration without standalone banking licenses.
Cloud-based deployment anchors the volume base while API integration gains share at the steepest rate.
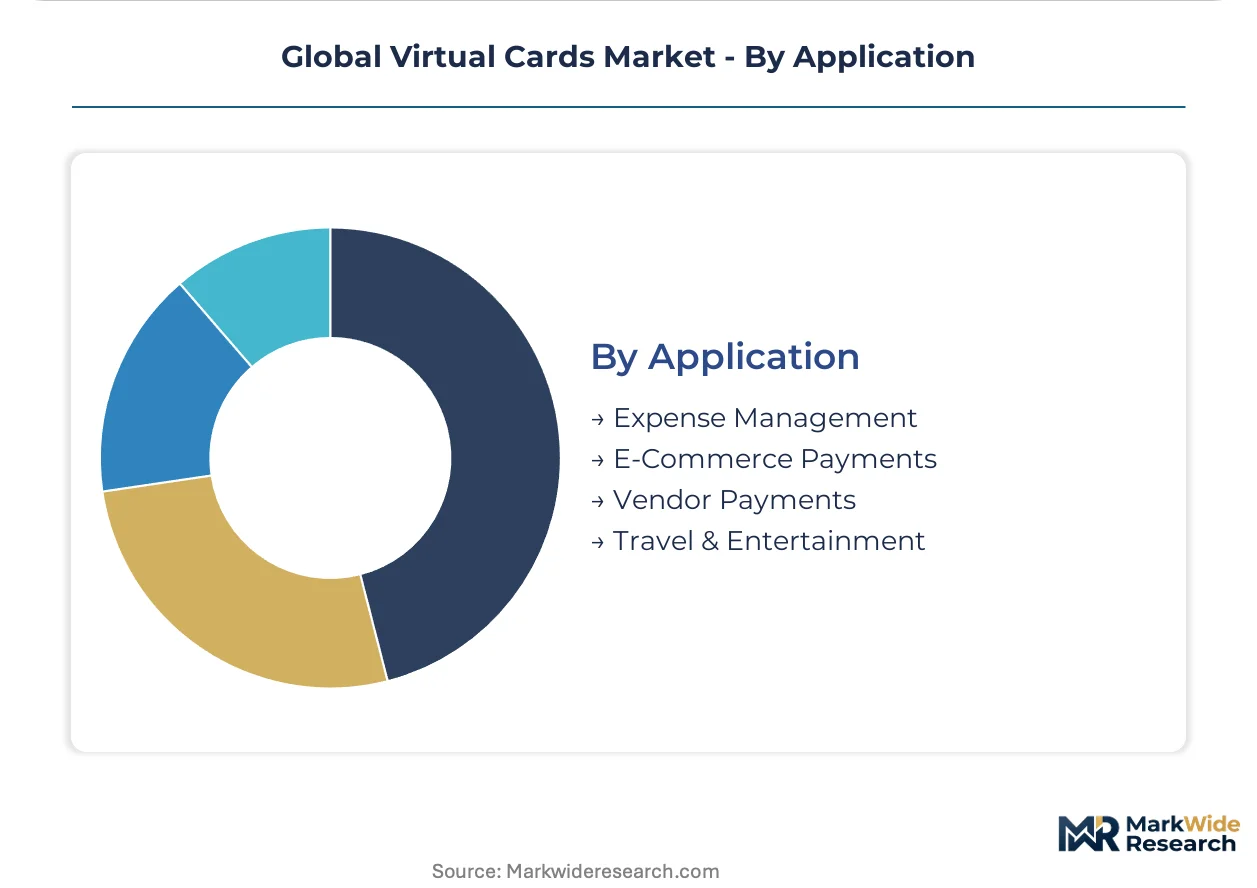
Application:
Geography shapes adoption intensity, with expense management concentration in mature digital payment markets and vendor payment growth in B2B automation corridors.
- Expense Management:Employee spend programs with real-time receipt capture and policy enforcement. United States technology sector procurement teams displace traditional corporate cards here.
- E-Commerce Payments:Consumer-facing checkout credentials masking primary funding sources. European PSD2 SCA compliance has normalized biometric pre-authentication for this use case.
- Vendor Payments:B2B procurement credentials with merchant-locked controls and automated reconciliation. Singapore's regional bank hubs process significant volume for cross-border trade finance.
- Travel & Entertainment:Per-diem and corporate travel credentials with geographic and category restrictions. India's closed-loop PPI products concentrate domestically due to RBI cross-border licensing constraints.
Expense management anchors the volume base while vendor payments gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Reserve anchors the dominant geography through FedNow instant payment rails that pressure card networks to demonstrate speed advantages over account-to-account transfers. Tokenization infrastructure and real-time payment rails are compressing issuance timelines from months to hours across major financial centers. Corporate treasury departments and fintech platforms are driving adoption intensity in markets with mature digital payment ecosystems and open banking frameworks.
United States
Corporate enterprises consolidate travel, procurement, and software spend onto unified platforms with granular budget controls. The Federal Reserve's FedNow network creates interoperability pressure on card networks to demonstrate value-add beyond raw transaction speed. Silicon Valley and New York fintech clusters host API-native issuance platforms that provision credentials within hours through REST endpoints.
United Kingdom
Open banking APIs and real-time payment rails reshape issuance infrastructure for corporate expense management programs. The Financial Conduct Authority enforces PSD2 Strong Customer Authentication requirements that mandate multi-factor verification for transactions above threshold limits. London's fintech corridor anchors European virtual card processing volume with regulatory clarity attracting regional headquarters.
India
Small and medium businesses present white space for rupee-denominated closed-loop products with embedded working capital features. The Reserve Bank of India governs prepaid payment instrument licensing through the PPI framework, restricting cross-border virtual card flows without explicit authorization. Mumbai and Bangalore fintech clusters channel domestic innovation toward rupee-denominated products while maintaining separate offshore credential stacks.
Singapore
Regional banks and fintechs establish Asia-Pacific processing hubs to serve cross-border B2B payment corridors with unified compliance frameworks. The Monetary Authority of Singapore provides regulatory clarity that attracts regional headquarters for credential issuance platforms. The city-state's financial district concentrates tokenization infrastructure serving trade finance corridors across Southeast Asian markets.
Germany
Corporate treasury departments under PSD2 mandates favor multi-use credentials for subscription management with embedded spending ceilings. The Federal Financial Supervisory Authority enforces technical standards for multi-factor verification flows that add latency to authorization paths. Frankfurt's banking cluster maintains on-premise vaulting architectures for audit trail requirements despite higher operational overhead.
Global Virtual Cards Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structure fragments across network operators with tokenization patent positions, API-native issuance platforms, and embedded finance intermediaries. Three archetypes dominate: incumbent card networks with vaulting infrastructure, cloud-native issuance specialists, and banking-as-a-service platforms. Competitive moves center on API latency reduction and programmable control granularity rather than brand recognition alone.
Within the network operator tier, Mastercard Inc. and Visa Inc. anchor tokenization infrastructure for digital-first credentials. Among API-native specialists, Marqeta, Inc. exemplifies platform architectures that collapse integration cycles for mid-market SaaS providers. These entities occupy positions that bridge legacy network rails and modern REST-based provisioning, representing the convergence point where issuance timelines compress from months to hours.
| Leading Market Players |
|---|
| Mastercard Inc. |
| Visa Inc. |
| American Express Company |
| JPMorgan Chase & Co. |
| Marqeta, Inc. |
| Stripe, Inc. |
| Adyen |
| Revolut Ltd. |
| Airwallex |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud-based tokenization infrastructure across Singapore and the United States is compressing API provisioning margins while forcing issuers to differentiate through programmable control granularity rather than raw issuance speed. This utilization dynamic rewards platforms with embedded finance attach rates and penalizes pure-play credential generators.
Pricing Analysis
Geographic price spreads separate premium-interchange corporate programs in the United States and United Kingdom from thin-margin rupee-denominated PPI products in India. SaaS-tiered subscription models dominate, with price differentiation resting on API latency tiers and embedded policy enforcement depth. Pricing pressure stems from FedNow interoperability demands forcing card networks to justify value-add beyond transaction speed. Freelancers exhibit highest price sensitivity; corporate treasury departments show lowest sensitivity due to reconciliation efficiency premiums.
Supply Chain Analysis
Upstream feedstock for virtual card infrastructure concentrates in United States cloud hyperscalers, Singapore regional processing hubs, and European tokenization vault operators. The supply chain draws from network tokenization patents, open banking API standards, and real-time payment rail connectivity. Single-source vulnerability in proprietary vaulting IP held by incumbent networks creates licensing friction for new entrants. Distribution runs through API-native issuance platforms embedding credentials into accounting software and ERP systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-native issuance infrastructure is compressing product launch timelines from months to hours, creating a high-growth disruption window as PSD2 and FedNow regulatory frameworks reshape competitive requirements.
For Market Incumbents: Harden tokenization patent positions against open banking account-linking models by deepening vaulting infrastructure investments in Singapore and London regulatory corridors. Defend interchange revenue pools through embedded policy enforcement features that demonstrate value-add beyond raw transaction speed against FedNow displacement threats. For New Entrants and Emerging Players: Mid-market SaaS providers in India seeking unified expense management platforms represent the most penetrable entry point, with rupee-denominated closed-loop PPI products offering regulatory-compliant white space. Target API integration partnerships with accounting software vendors to bypass standalone banking license requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native issuance platforms as infrastructure-as-a-service models displace on-premise vaulting investments. Long-term viability over the projection horizon favors platforms with embedded finance convergence capabilities. Watch for RBI authorization expansions permitting cross-border credential flows as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| API Latency Optimization | Marqeta and similar platforms compress provisioning timelines to hours through REST endpoint architectures. |
| Network Tokenization Patent Licensing | Mastercard and Visa vault infrastructure creates moats against open banking account-linking substitutes. |
| Embedded Finance Convergence | Platforms integrating credentials with ERP systems capture interchange revenue and SaaS attach rates simultaneously. |
| Regional Hub Establishment | Singapore processing centers leverage MAS regulatory clarity for cross-border B2B payment corridors. |
| PSD2 Compliance Automation | Biometric pre-authentication through mobile wallets reduces checkout friction while satisfying EBA multi-factor mandates. |
Research Methodology
Operator-level perspectives from corporate treasury directors, fintech platform architects, regulatory compliance officers, and network tokenization engineers anchored the qualitative base. Primary interviews combined with secondary validation through SEC filings of listed payment networks, RBI circulars on PPI frameworks, EBA technical standards documentation, and FedNow service guides. Bottom-up credential volume modeling triangulated against top-down interchange revenue estimates across the analysis window.
Scenario-bracketing around FedNow adoption velocity and RBI cross-border authorization timelines framed the forecast sensitivity. Segmentation dimensions modeled include card type, end user archetype, deployment architecture, and application corridor, with geographic regulatory cluster as cross-cutting variable. CAGRs derived from credential issuance velocity projections and interchange rate compression assumptions, with API integration penetration and embedded finance attach rates as industry-specific inputs.
Practitioners should monitor PSD2 technical standard revisions, RBI PPI framework amendments, and FedNow transaction volume trajectories for early signals requiring forecast reassessment. Cross-checking against published network operator tokenization disclosure filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Payments Market
Payments
Remote Mobile Payment Market
Payments
Payment Orchestration Platform Market
Payments
Digital Transfer Services Market
Payments
China Virtual Cards Market
Payments
3D Secure Pay Authentication Market
Payments
Online Charging System (OCS) Market
Payments
Global Accounts Payable Software Market
Payments
In-Vehicle Payment Services Market
Payments
Canada Gift Card and Incentive Card Market
Payments
EMV Card Market
Payments
Digital Transaction Management Market
Payments
United Kingdom Mobile Payments Market
Payments
Croatia POS Terminals Market
Payments
China Prepaid Cards Market
Payments
Japan Payments Market