
 Saudi Arabia Payments Market | 2026-2036
Saudi Arabia Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Payments Market Outlook
A capital-intensity divergence between legacy bank-owned networks and agile fintech platforms is bifurcating competitive dynamics in Saudi Arabia's payments landscape. Saudi Payments Company anchors the national mada debit infrastructure across point-of-sale terminals nationwide. STC Bank leverages its telecom parentage to sustain wallet penetration among younger demographics unburdened by traditional banking relationships. Geidea Technology Company competes aggressively on merchant acquiring hardware, controlling terminal deployment in mid-tier retail segments outside the Riyadh-Jeddah axis.
Payments systems in Saudi Arabia encompass the technological infrastructure, regulatory protocols, and institutional networks enabling value transfer between consumers, merchants, and government entities, operating through real-time gross settlement engines with sub-second clearing windows and ISO 20022 messaging standards. The primary commercial purpose centers on reducing friction in economic exchange while generating transaction data for credit risk assessment and monetary policy transmission. Digital wallets are capturing disproportionate growth momentum as NFC-enabled contactless payments displace card-present volume in grocery and quick-service restaurant channels. Bank transfers retain structural dominance in corporate treasury operations and government disbursement flows where SAMR's regulatory audit trails mandate traceable settlement rails. Cash transactions persist in micro-transaction segments serving informal labor markets and rural municipalities with limited digital infrastructure.
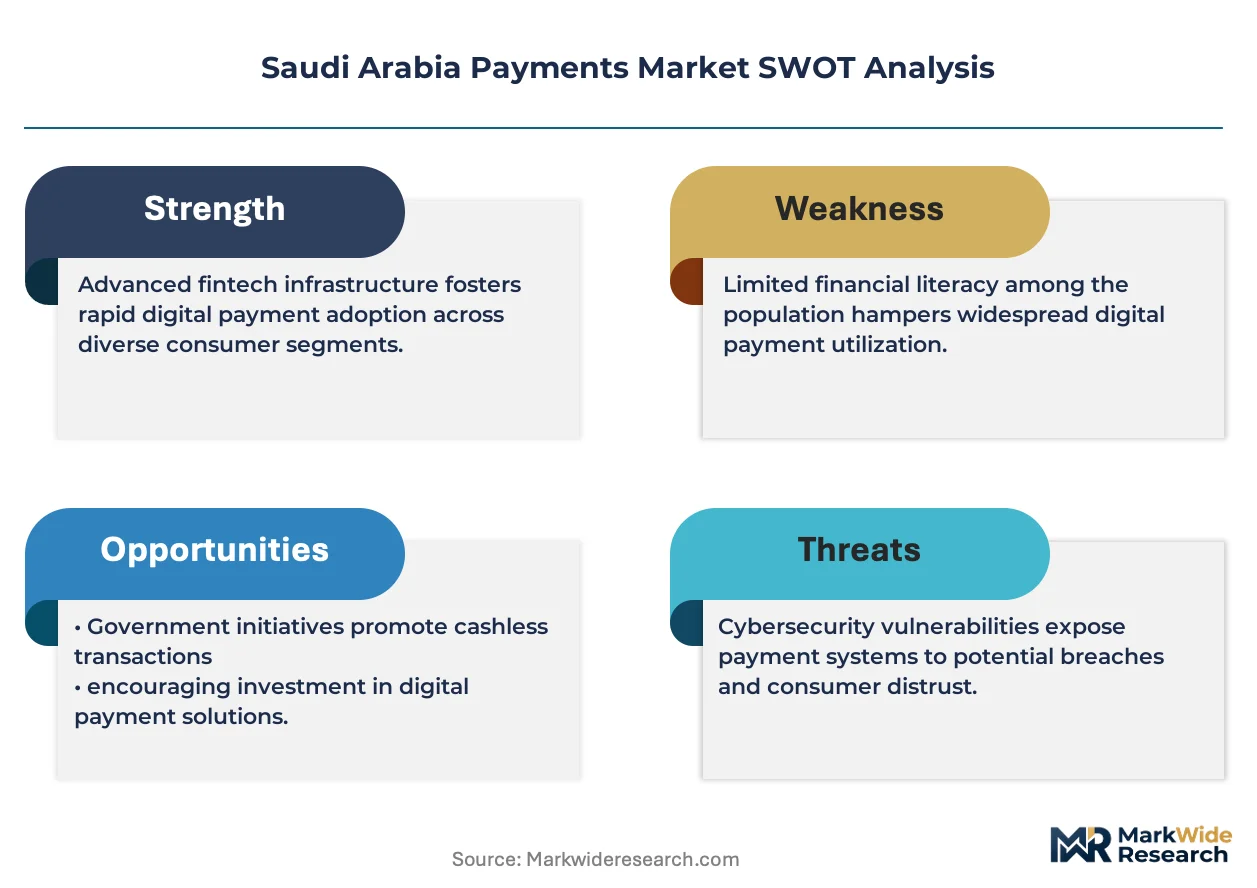
SAMA's licensing regime for payment service providers and the Saudi Central Bank's operational oversight of the SARI instant payment system create dual compliance thresholds that filter market participation. The Personal Data Protection Law, enforced by the National Data Management Office, imposes localization requirements on transaction data storage that elevate infrastructure costs for foreign platform operators. Stakeholders must monitor how SAMA's forthcoming open banking API standards redistribute data access advantages between incumbent banks and licensed fintech challengers.
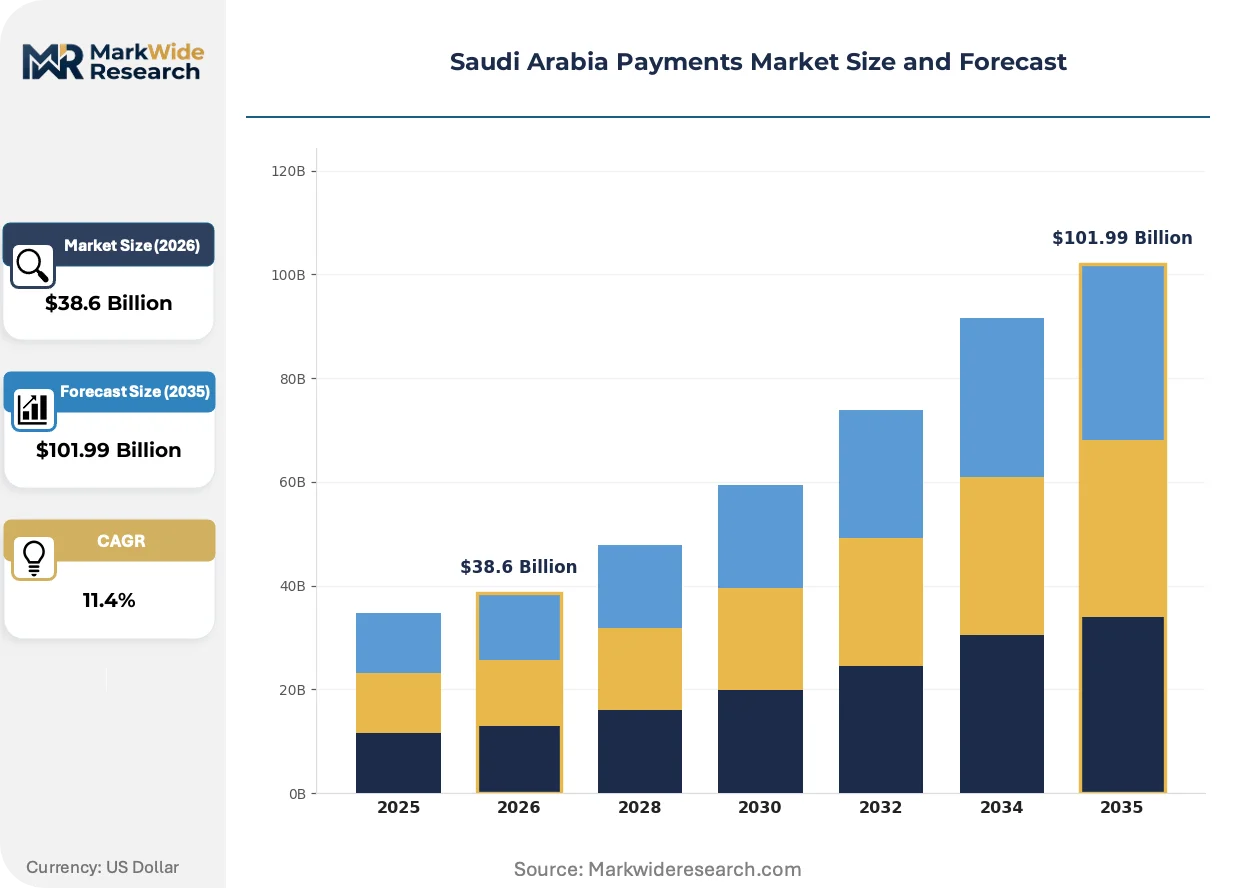
Market Dynamics
The Saudi Arabia Payments Market is undergoing a structural transformation as SAMA's open banking framework and the Saudi Central Bank's instant payment infrastructure mandate force incumbent banks to expose customer data APIs to licensed fintech challengers. This regulatory architecture is redistributing competitive advantages away from legacy branch networks toward platform-based aggregators that can orchestrate multi-bank services through unified interfaces.
Growth Catalysts
- SAMA's Open Banking Framework:Mandatory API standards are unlocking transaction data portability, enabling third-party providers to build personalized financial management tools that accelerate wallet adoption among digitally native consumers.
- E-commerce platform integration:Major online marketplaces are embedding native checkout experiences that bypass traditional card rails, creating direct incentives for merchants to adopt instant payment settlement through the SARI system.
- Riyadh merchant acquiring clusters:Concentrated retail development in the capital's commercial districts is generating network effects that reduce per-terminal deployment costs for payment service providers.
Market Restraints
- Data localization mandates:The National Data Management Office's Personal Data Protection Law requires domestic storage of transaction records, elevating infrastructure capex for foreign platform operators seeking market entry.
- Rural digital infrastructure gaps:Limited broadband penetration in municipalities outside the Riyadh-Jeddah corridor constrains contactless payment acceptance in micro-merchant segments dependent on cash settlement.
- Legacy core banking dependencies:Incumbent institutions' mainframe architectures create integration friction with ISO 20022 messaging standards, delaying real-time clearing capabilities for smaller banks.
Strategic Opportunities
- Jeddah cross-border remittance corridors:Labor migration flows between the Kingdom and South Asian markets present white space for blockchain-based settlement rails that compress correspondent banking fees.
- Government disbursement digitization:SAMA's mandate for traceable settlement rails in social welfare and salary payments creates captive demand for bank transfer infrastructure with embedded compliance reporting.
- NFC-contactless convergence:Integration of biometric authentication with tap-to-pay functionality at quick-service restaurant channels is displacing card-present volume among time-sensitive consumer segments.
Industry Challenges
- API standardization timelines:SAMA's phased rollout of open banking technical specifications creates uncertainty for fintech product roadmaps, forcing parallel development tracks against draft and finalized protocols.
- Legacy system integration complexity:Payment service providers must maintain dual connectivity to both the SARI instant payment engine and traditional batch settlement systems, doubling operational overhead during the transition window.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Payments Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Card Payments, Digital Wallets, Bank Transfers, Cash Transactions End User Type: Retail Consumers, Corporates, E-commerce Platforms, Government Agencies Transaction Size: Micro Transactions, Small Transactions, Medium Transactions, Large Transactions Technology: Contactless Payments, NFC, Mobile Payment Solutions, Online Payment Gateways |
| Companies Covered | Saudi Payments Company (mada network), STC Bank (STC Pay Wallet), Al Rajhi Bank, Visa Inc., Mastercard Inc., Hyperpay Inc., Geidea Technology Company, PayTabs Group, Saudi National Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Payments Market Strategic Shifts
Digital wallet architectures are fragmenting the Saudi Arabia Payments Market as platform operators compete to own the consumer interface layer while commoditizing underlying banking infrastructure. Three convergent developments are compressing margins in traditional acquiring while opening new value pools in data services and embedded finance.
Biometric authentication protocols are fragmenting trust architectures across the Kingdom's payment ecosystem. Fingerprint and facial recognition systems are replacing PIN entry at grocery and quick-service restaurant terminals, with younger demographics adopting these methods at rates that outpace card-present volume decline. This technology is fragmenting liability models between merchants, issuers, and biometric service providers as transaction dispute frameworks adapt to non-repudiable identity verification.
SAMA's licensing regime for payment service providers is tightening operational oversight while expanding the permitted scope of non-bank financial activities. The central bank's capital adequacy requirements and consumer protection mandates are filtering market participation toward well-funded platform operators capable of absorbing compliance costs. Small and mid-tier retail segments outside Riyadh's core districts are responding by consolidating merchant relationships around fewer acquiring partners with proven regulatory track records.
Merchant procurement of payment acceptance infrastructure is rotating toward subscription-based hardware provisioning rather than capital purchase models. Mid-tier retailers in Jeddah's commercial corridors are demanding terminal-as-a-service arrangements that bundle software updates, compliance certification, and dynamic currency conversion into per-transaction fees. This shift is most visible in the quick-service restaurant vertical, where franchise operators prioritize cash-flow predictability over equipment ownership.
Saudi Arabia Payments Market Segmentation
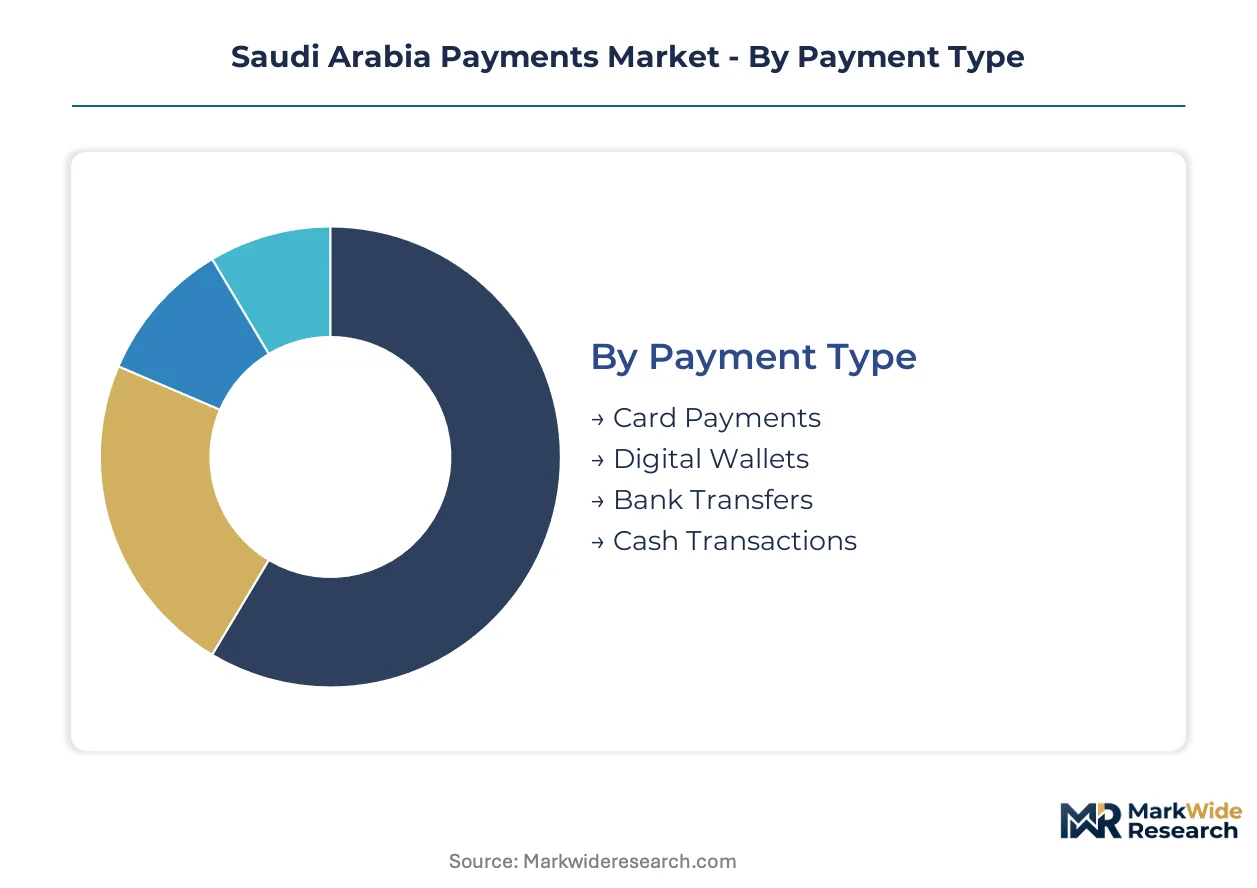
Segmentation in Saudi Arabia's payments landscape reveals how SAMA's regulatory architecture and infrastructure mandates differentially shape competitive entry across transaction modalities and user profiles. Channel-mix dynamics determine which payment rails capture volume in Riyadh's concentrated merchant clusters versus Jeddah's fragmented retail corridors.
Payment Type:
Channel-mix patterns show card payments and digital wallets flowing through POS terminals in urban retail districts, while bank transfers dominate B2B corridors and government disbursement channels.
- Card Payments:Debit infrastructure anchored by the national mada network processes settlement through ISO 20022 messaging rails. Demand concentrates in Riyadh's grocery and quick-service restaurant terminals where contactless tap limits have risen to accommodate inflation-adjusted basket sizes.
- Digital Wallets:Platform-agnostic mobile applications integrate biometric authentication with NFC-enabled point-of-sale acceptance. STC Bank and competing telecom-affiliated providers are capturing younger demographics in Jeddah's commercial districts through merchant-funded cashback incentives.
- Bank Transfers:Real-time gross settlement through the SARI instant payment engine serves corporate treasury operations with sub-second clearing windows.
- Cash Transactions:Physical currency persists in rural municipalities outside broadband coverage and informal labor markets requiring anonymous settlement.
By volume, Card Payments leads. By growth pace, Digital Wallets is expanding most quickly.
End User Type:
Cost tier differentiation separates high-frequency low-margin retail processing from compliance-heavy government disbursement systems with embedded audit trail requirements.
- Retail Consumers:Individual payment behavior bifurcates between urban NFC adoption and rural cash dependence. Riyadh's concentrated retail development generates network effects that reduce per-transaction processing costs for acquirers serving this segment.
- Corporates:Enterprise treasury operations demand batch payment scheduling with foreign exchange hedging and multi-bank reconciliation. SAMA's open banking API standards are redistributing data access advantages between incumbent banks and licensed fintech challengers serving this tier.
- E-commerce Platforms:Online marketplaces embed native checkout experiences that bypass traditional card rails through SARI instant settlement integration.
- Government Agencies:Public sector disbursement mandates require traceable settlement rails with automated compliance reporting for social welfare and salary payments.
Retail Consumers generates the highest transaction count. E-commerce Platforms shows the steepest expansion trajectory as platform integration accelerates.
Transaction Size:
Application context determines infrastructure requirements, with micro-merchant segments demanding low-cost acceptance hardware and large corporate flows requiring real-time FX and liquidity management tools.
- Micro Transactions:Sub-ten-riyal payments for transit fares and vending machines drive demand for tap-to-pay functionality without signature or PIN verification. Geidea Technology Company targets this tier with stripped-down terminal hardware deployed outside the Riyadh-Jeddah axis.
- Small Transactions:Everyday retail purchases in grocery and quick-service channels are displacing card-present volume as biometric authentication replaces PIN entry.
- Medium Transactions:Mid-market B2B procurement and professional services payments flow through bank transfer rails with value-date certainty.
- Large Transactions:Cross-border remittance corridors and corporate M&A settlement require correspondent banking relationships with compressed fees.
Small Transactions dominates daily volume. Micro Transactions is gaining share fastest as contactless limits rise and merchant acquisition costs fall.
Technology:
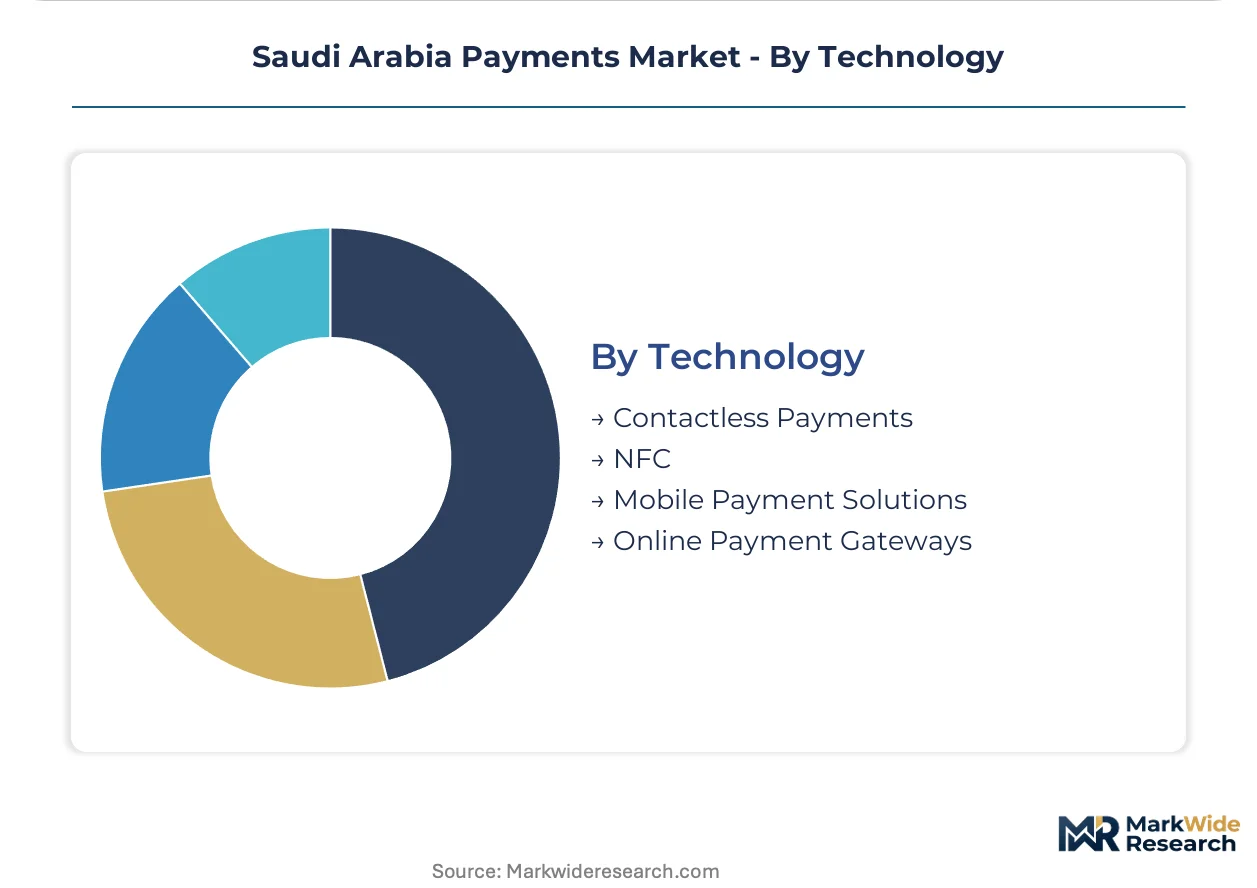
Customer type segmentation separates consumer-facing biometric authentication from merchant-facing gateway infrastructure with diverging margin profiles and regulatory burdens.
- Contactless Payments:Tap-to-accept terminals with EMV certification process NFC-enabled cards and wearable devices. Riyadh's merchant acquiring clusters generate sufficient density to amortize deployment costs across high-throughput locations.
- NFC:Near-field communication protocols enable sub-second handshake between mobile devices and POS terminals. Jeddah's quick-service restaurant verticals are adopting this technology to reduce queue abandonment during peak hours.
- Mobile Payment Solutions:Smartphone-native applications integrate loyalty programs with payment execution through embedded wallets.
- Online Payment Gateways:E-commerce checkout infrastructure routes transactions through multiple acquiring banks for redundancy and cost optimization.
Contactless Payments leads by installed terminal base. Mobile Payment Solutions is climbing the fastest as smartphone penetration saturates urban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Riyadh's merchant acquiring clusters while Jeddah's cross-border corridors operate on compressed margins. Eastern Province industrial zones generate B2B payment flows with distinct infrastructure requirements. Regional divergence reflects SAMA's phased regulatory rollout and uneven digital infrastructure deployment.
Riyadh
Riyadh's concentrated retail development generates network effects that reduce per-terminal deployment costs for payment service providers. SAMA's open banking API standards are redistributing data access advantages between incumbent banks and licensed fintech challengers in the capital. King Abdullah Financial District anchors merchant acquiring density, with contactless tap limits rising to accommodate inflation-adjusted basket sizes.
Jeddah
Jeddah's commercial corridors drive demand for terminal-as-a-service arrangements that bundle software updates and compliance certification into per-transaction fees. The Saudi Central Bank's SARI instant payment infrastructure mandate is accelerating settlement speed in cross-border remittance channels serving South Asian labor migration flows. Quick-service restaurant verticals in the city are adopting NFC technology to reduce queue abandonment during peak hours.
Eastern Province
Eastern Province industrial zones generate corporate treasury operations demanding batch payment scheduling with foreign exchange hedging and multi-bank reconciliation. SAMA's licensing regime for payment service providers is filtering market participation toward well-funded platform operators capable of absorbing compliance costs. Dhahran's energy sector clusters create captive demand for bank transfer infrastructure with embedded compliance reporting.
Western Region
Western Region pilgrimage corridors create seasonal payment volume spikes requiring elastic processing capacity. The National Data Management Office's Personal Data Protection Law imposes localization requirements on transaction data storage that elevate infrastructure costs for foreign platform operators. Makkah's religious tourism clusters are consolidating merchant relationships around fewer acquiring partners with proven regulatory track records.
NEOM Northwest
NEOM's greenfield development is testing biometric authentication protocols that fragment trust architectures across the Kingdom's payment ecosystem. SAMA's forthcoming open banking API standards are creating uncertainty for fintech product roadmaps in the megacity project. The zone's digital-native infrastructure is bypassing legacy core banking dependencies that delay real-time clearing capabilities elsewhere.
Saudi Arabia Payments Market Competitive Environment
Concentration sits with bank-owned payment networks and telecom-affiliated digital wallet operators that control national infrastructure rails. The market structure reflects a capital-intensity divergence between legacy institutions with branch networks and agile fintech platforms unburdened by traditional banking relationships. Three strategic archetypes dominate: national payment infrastructure operators, telecom-originated wallet providers, and merchant acquiring hardware specialists. Competitive moves center on API standardization compliance and subscription-based hardware provisioning models that displace capital purchase arrangements.
Within the national infrastructure tier, Saudi Payments Company anchors the mada debit network across point-of-sale terminals nationwide. STC Bank exemplifies telecom-originated wallet penetration among younger demographics through merchant-funded incentive structures. Geidea Technology Company occupies a position among merchant acquiring specialists controlling terminal deployment in mid-tier retail segments outside core urban corridors.
| Leading Market Players |
|---|
| Saudi Payments Company (mada network) |
| STC Bank (STC Pay Wallet) |
| Al Rajhi Bank |
| Visa Inc. |
| Mastercard Inc. |
| Hyperpay Inc. |
| Geidea Technology Company |
| PayTabs Group |
| Saudi National Bank |
| Others |
Value Chain & Pricing Dynamics
Terminal deployment density in Riyadh's merchant clusters generates procurement scale economies that compress hardware unit costs while elevating price floors for sparse rural coverage. SAMA's data localization mandates under the Personal Data Protection Law further concentrate infrastructure investment around domestic server farms, reinforcing supply-side consolidation that limits price competition in compliant payment processing tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order terminal provisioning from standard hardware bundles in Saudi Arabia's payments landscape. Subscription-based terminal-as-a-service models dominate mid-tier retail, embedding software updates and compliance certification into per-transaction fees rather than capital purchase arrangements. Price differentiation hinges on biometric authentication integration and SAMA licensing tier, with unlicensed foreign platforms facing elevated localization costs that widen their premium spread over domestic operators. Cost compression in standard acquiring hardware is intensifying as Geidea Technology Company and competing specialists saturate Riyadh-Jeddah deployment corridors. Government agencies and corporate treasury operations exhibit lowest price sensitivity due to embedded compliance reporting requirements, while micro-merchants in rural municipalities remain most price-sensitive and cash-dependent.
Supply Chain Analysis
Just-in-time inventory strategies dominate terminal hardware procurement for urban merchant clusters, while strategic stockpiling of biometric authentication components buffers against semiconductor supply volatility. Manufacturing concentration rests on China for POS terminal assembly, Taiwan for NFC chip fabrication, and South Korea for secure element production. Raw material dependencies include rare earth elements for magnetic stripe readers, lithium-ion cells for portable terminal power, and specialized polymers for EMV card durability. Single-source vulnerability in NFC controller chips creates supply chain risk given limited qualified alternative suppliers. Distribution runs through Saudi Payments Company for mada network infrastructure, with independent hardware specialists managing last-mile deployment to mid-tier retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's payments market is positioned for cyclical recovery as SAMA's open banking framework mandates force incumbent infrastructure refresh cycles and create replacement demand for legacy core banking integrations.
For Market Incumbents: Fortify API standardization compliance ahead of SAMA's phased rollout timelines to defend merchant relationships against fintech challengers exploiting data portability advantages. Prioritize backward integration into biometric authentication service provisioning to capture margin pools shifting from hardware toward identity verification layers, while consolidating terminal deployment partnerships in Eastern Province industrial zones where corporate treasury operations demand batch payment infrastructure with embedded FX hedging. For New Entrants and Emerging Players: Anchor in Jeddah's cross-border remittance corridors serving South Asian labor migration flows, where correspondent banking fee compression creates white space for blockchain-based settlement rails. Target Western Region pilgrimage clusters around Makkah and Madinah with seasonal elastic capacity solutions, deploying terminal-as-a-service arrangements that bundle dynamic currency conversion for religious tourism merchants. Lead go-to-market through merchant-funded cashback incentive structures proven effective with younger demographics in STC Bank's telecom-originated wallet model. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-based aggregators orchestrating multi-bank services through unified interfaces over legacy branch-dependent institutions. Long-term viability across the projection horizon rests on regulatory track record depth and open banking API compliance maturity rather than pure transaction volume scale. Acquisition targets should demonstrate proven SAMA licensing history and ISO 20022 messaging integration. The signal to watch as inflection indicator is merchant consolidation behavior around fewer acquiring partners with demonstrated compliance certification, particularly in quick-service restaurant verticals adopting NFC-biometric convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Compliance Investment | SAMA's mandatory standards unlock data portability advantages for licensed fintech challengers against incumbent banks. |
| Biometric Authentication Integration | Fingerprint and facial recognition systems displace PIN entry in grocery and quick-service restaurant channels nationwide. |
| Terminal-as-a-Service Model Expansion | Subscription hardware provisioning bundles compliance certification into per-transaction fees for mid-tier Jeddah retailers. |
| Cross-Border Remittance Rail Development | Blockchain settlement compression targets correspondent banking fees in South Asian labor migration corridors. |
| Government Disbursement Digitization Partnership | SAMA's traceable settlement mandates create captive demand for bank transfer infrastructure with automated compliance reporting. |
Study Parameters
Initial hypotheses were tested against primary input from payment service provider executives, SAMA regulatory affairs specialists, merchant acquiring operations managers, and fintech platform engineers, then refined through secondary validation. Primary fieldwork encompassed structured interviews with terminal deployment specialists at Geidea Technology Company, treasury operations leads at Eastern Province energy sector clusters, and quick-service restaurant franchise operators in Jeddah commercial corridors. Secondary sources included SAMA licensing disclosure records, Saudi Central Bank SARI system operational bulletins, National Data Management Office Personal Data Protection Law implementation guidance, and ISO 20022 migration status reports. Bottom-up terminal deployment counts and top-down transaction value estimates were triangulated against merchant density mapping in Riyadh and Jeddah corridors.
Variance decomposition across the modeling period isolated volume drivers from price-mix effects, with segmentation dimensions spanning payment type, end user category, transaction size tier, and technology modality. CAGRs were derived from fitted growth curves against historical adoption benchmarks, incorporating biometric authentication penetration rates and NFC terminal installation trajectories as industry-specific forecast inputs. The analytical framework weighted open banking API standardization timelines and SARI instant payment infrastructure rollout phases as structural breakpoints.
Material uncertainties — SAMA regulatory revision schedules, biometric liability framework evolution, and rural broadband deployment pace — sit outside the modeled envelope. Forecasts reflect assumptions regarding phased compliance adoption and merchant consolidation behavior around proven regulatory track records. Revision becomes warranted when SAMA open banking API finalization delays exceed current draft-to-final protocol parallel development windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United Kingdom Mobile Payments Market
Payments
Canada Buy Now Pay Later Market
Payments
Vietnam Payments Market
Payments
Global Prepaid Cards Market
Payments
Epayment System Market
Payments
Cross-Border Payment Platform Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
Mobile Wallet Market
Payments
Canada POS Terminal Market
Payments
Australia Mobile Payment Market
Payments
Nigeria Mobile Money Market
Payments
Transit Cards Market
Payments
Accelerator Card Market
Payments
France Mobile Payment Market
Payments
US Gift Card and Incentive Card Market
Payments
UAE Buy Now Pay Later Services Market