
 Global Real-Time Payments Market | 2026-2036
Global Real-Time Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Real-Time Payments Market Foresight
Enterprise buyer concentration around large e-commerce platforms and multinational retailers is realigning procurement priorities for payment infrastructure providers. Mastercard Inc. leverages its network scale to dominate high-volume clearing corridors between North America and Asia. Visa Inc. competes through API-first developer tools that embed real-time capabilities directly into merchant checkout flows. Fiserv Inc. anchors its position through backward integration into core banking systems that feed instant payment rails.
Real-time payments denote electronic fund transfers that settle funds between bank accounts within seconds, operating on ISO 20022 messaging standards that carry richer remittance data than legacy batch systems. The primary commercial purpose is elimination of settlement risk and liquidity float for businesses managing high-velocity receivables. Person-to-Person transfers occupy the highest transaction frequency tier, though Business-to-Business flows capture disproportionate value per transaction due to larger average ticket sizes. Cloud-Based Platforms represent the fastest-growing deployment architecture, displacing on-premises installations as banks prioritize elastic capacity for volume spikes.
The European Banking Authority enforces instant payment availability rules under the EU's revised Payment Services Directive, compelling banks to offer 24/7 euro clearing at negligible cost. India's NPCI operates the Unified Payments Interface under Reserve Bank of India oversight, creating the world's most penetrated real-time retail payment ecosystem. The US Federal Reserve launched the FedNow Service to close the gap with private real-time networks operated by The Clearing House. Stakeholders must monitor how divergent regulatory timelines for interoperability mandates reshape competitive positioning across corridors.
Market Dynamics
ISO 20022 messaging standards are compressing clearing timelines from batch cycles to sub-second settlement, forcing banks to retire legacy mainframe architectures that cannot process continuous transaction streams.
Growth Catalysts
- E-commerce settlement velocity:Online marketplaces now mandate instant fund availability for merchant payouts, converting payment rails from cost centers to competitive differentiators.
- India's UPI network effects:The Unified Payments Interface has crossed critical mass density, creating self-reinforcing adoption loops among banks, merchants, and consumers.
- EU Payment Services Directive mandates:The European Banking Authority's instant payment availability rules require 24/7 euro clearing at near-zero cost, eliminating bank discretion to delay modernization.
Market Restraints
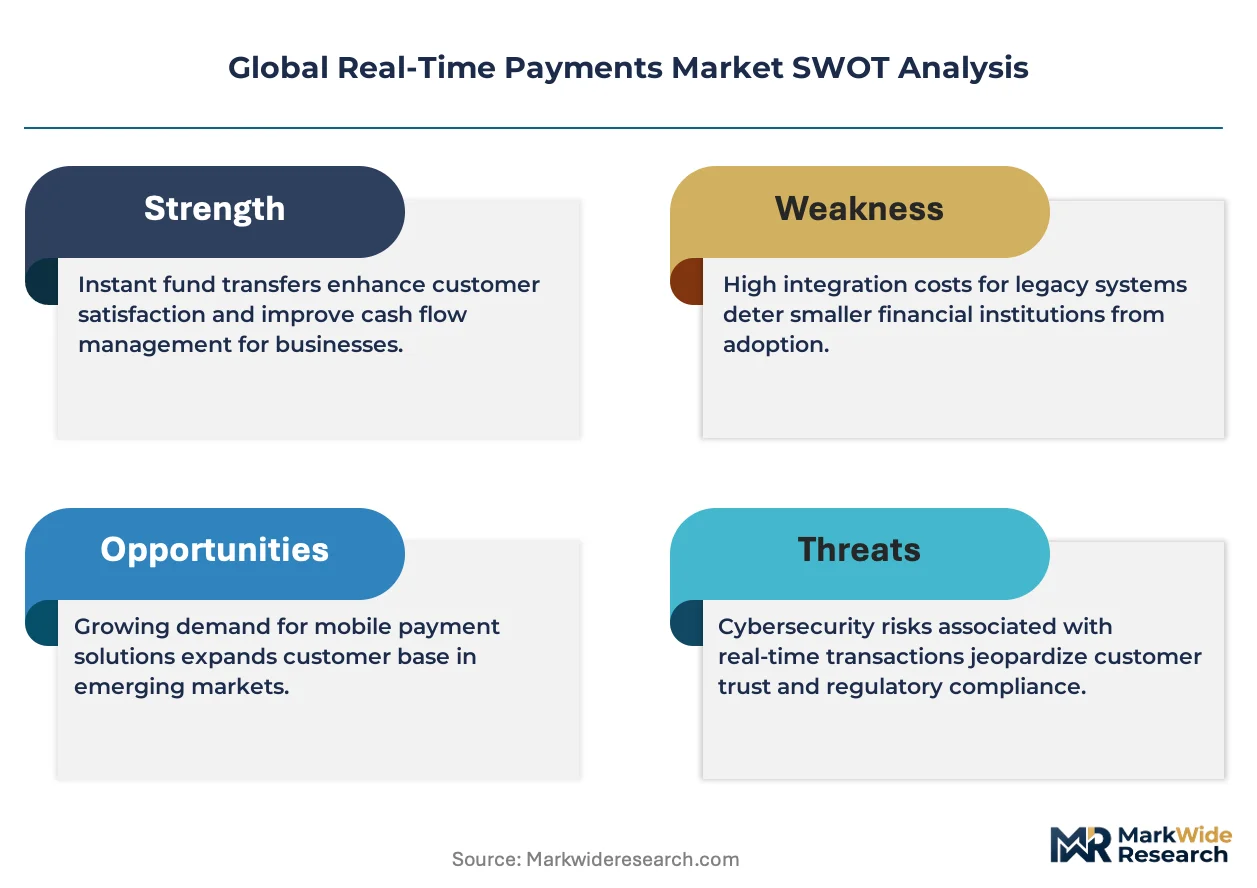
- Core banking replacement costs:Legacy batch-oriented mainframes at tier-one banks require billion-dollar modernization programs to support continuous processing.
- Interoperability fragmentation:The US maintains three competing real-time networks (FedNow, The Clearing House RTP, Zelle) with divergent technical specifications.
- Fraud exposure amplification:Irreversible settlement eliminates the recall window that protected banks against authorized push payment scams.
Strategic Opportunities
- Brazil's Pix ecosystem expansion:The Central Bank of Brazil's instant payment system is penetrating underbanked segments previously served only by cash.
- Request-to-Pay messaging:ISO 20022's structured invoice data field enables straight-through reconciliation for accounts payable automation.
- Embedded finance convergence:Real-time rails combined with banking-as-a-service APIs allow non-financial platforms to originate payments.
Industry Challenges
- ISO 20022 migration complexity:Banks must remap decades of unstructured remittance data into standardized XML schemas without disrupting live operations.
- 24/7 operational resilience:Continuous availability requirements expose banks to nighttime system failures when technical staffing is minimal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Real-Time Payments Market |
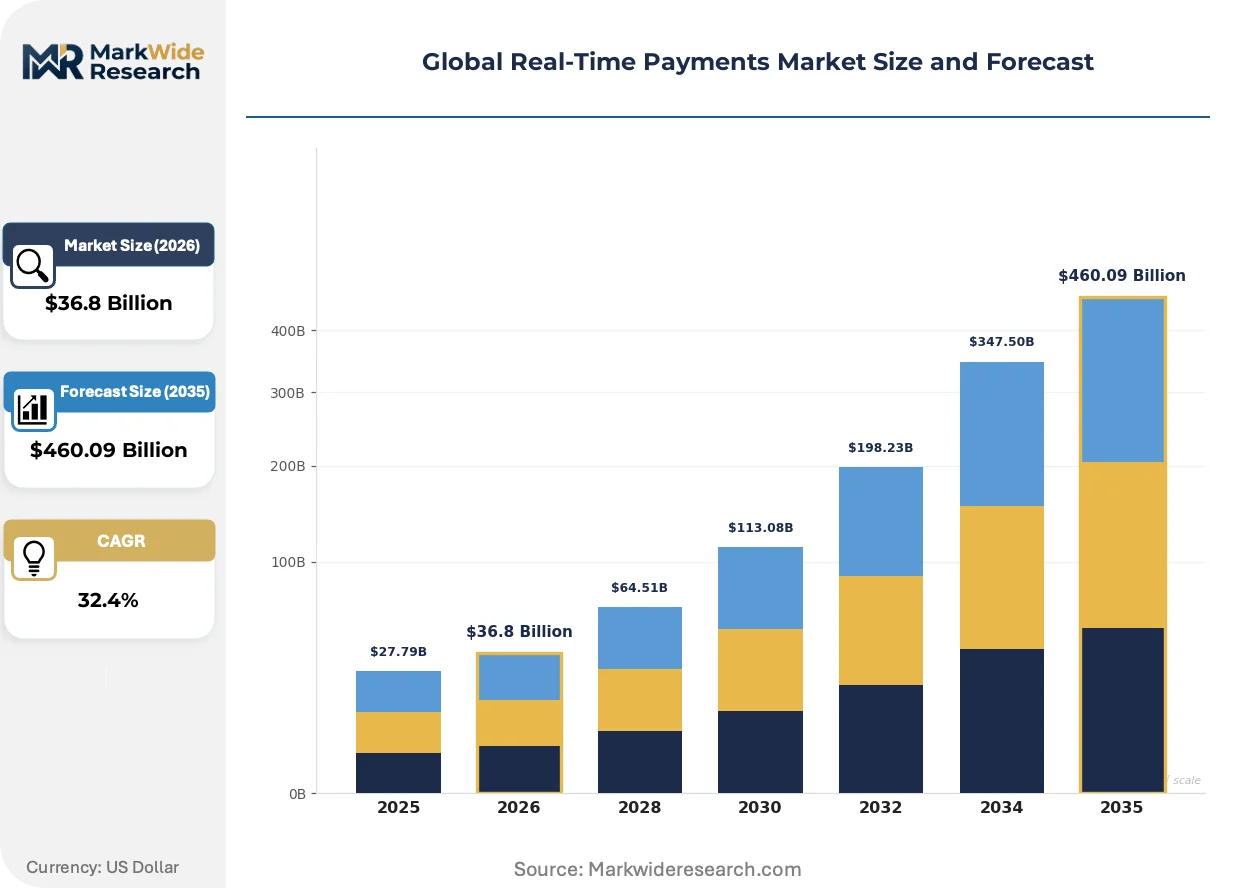
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $460.09 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Person-to-Person, Business-to-Consumer, Business-to-Business, Consumer-to-Business, Government Payments Technology: Mobile Wallets, APIs, Cloud-Based Platforms, Blockchain, Near Field Communication End User: FinTech Companies, E-Commerce Platforms, Brick-and-Mortar Stores, Utility Providers, Financial Institutions Deployment Model: On-Premises, Cloud, Hybrid, Hosted, Managed Services |
| Companies Covered | ACI Worldwide Inc., Fiserv Inc., Mastercard Inc., Visa Inc., PayPal Holdings Inc., Temenos AG, Finastra, Ripple Labs Inc., Adyen N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Real-Time Payments Market Shifts & Advancements
Cloud-native processing architectures are displacing on-premise mainframes as volume volatility demands elastic capacity. Three developments are compressing competitive timelines.
ISO 20022 messaging is unifying payment, securities, and trade finance communication onto a single data standard. Major correspondent banks are migrating cross-border flows to the enriched format. This unifying standard is collapsing the fragmentation that previously required multiple translation layers between domestic and international clearing.
The EU's revised Payment Services Directive compels instant payment availability at negligible cost. Banks must offer 24/7 euro clearing regardless of counterparty size. Small and medium enterprises are the most affected segment, as they gain access to settlement speeds previously reserved for large corporates with premium banking relationships.
Merchant procurement of payment infrastructure now prioritizes API response latency over per-transaction pricing. E-commerce platforms are selecting providers based on 99.99% availability guarantees and sub-100 millisecond authorization speeds. This behavioral shift is most visible in India, where checkout abandonment rates directly correlate with payment confirmation delays.
Global Real-Time Payments Market Segmentation
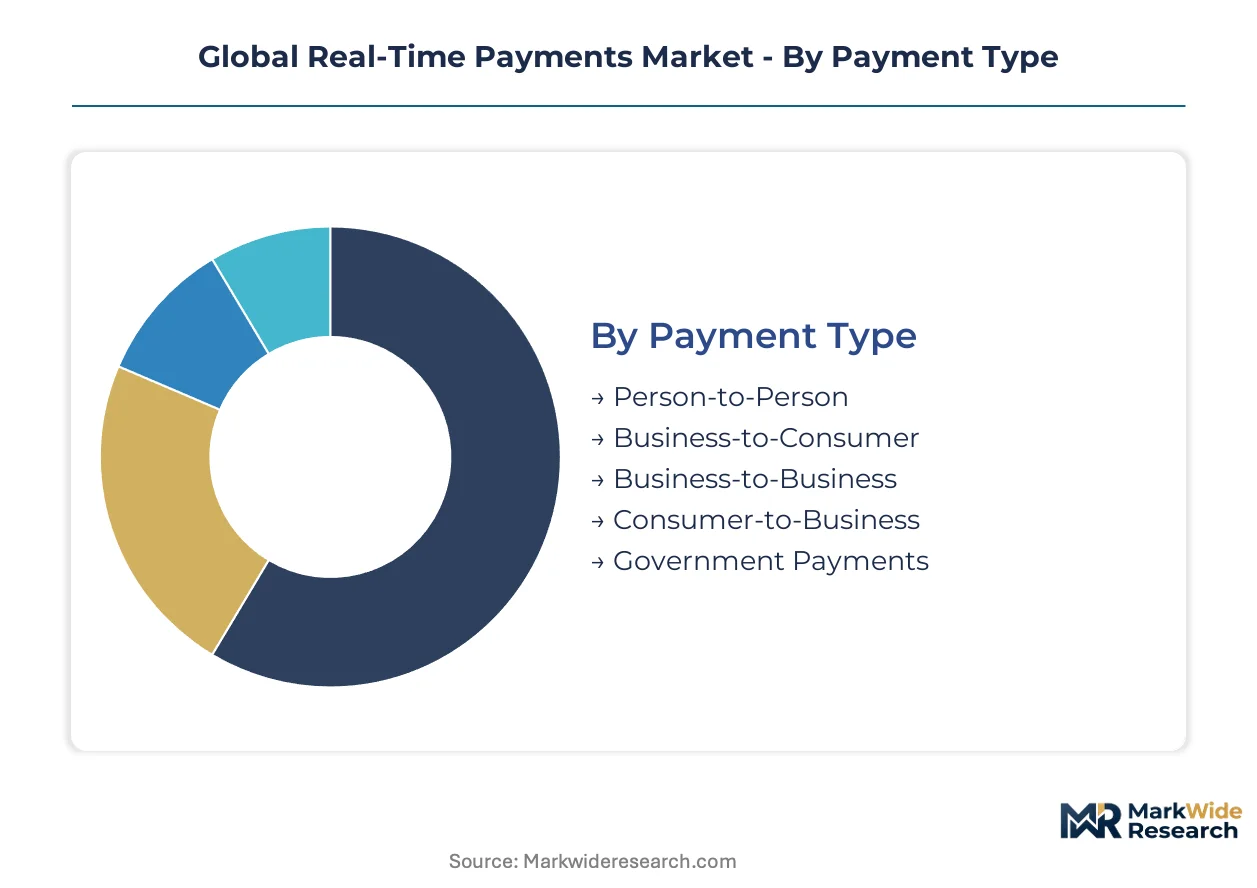
Segmentation reveals where infrastructure investment concentrates and which user profiles generate transaction density. Capital deployment patterns diverge sharply across payment types and deployment architectures.
Payment Type:
Capital intensity peaks where settlement velocity requirements strain legacy core banking systems.
- Person-to-Person:Low-value, high-frequency transfers between individual accounts dominate transaction volume. India's UPI network processes billions of monthly P2P flows, driven by mobile-first consumer behavior and zero-merchant-fee economics.
- Business-to-Business:Large-ticket commercial settlements carry the highest infrastructure demands per transaction. ISO 20022's structured remittance data enables straight-through processing for accounts payable automation, though legacy ERP integration absorbs disproportionate implementation spend.
- Business-to-Consumer:Payroll disbursements and insurance payouts require instant availability guarantees. Brazil's Pix mandates 24/7 settlement for government benefits, forcing banks to maintain continuous operational capacity.
- Consumer-to-Business:Bill payments and retail checkouts prioritize sub-second authorization speeds. E-commerce platforms in Southeast Asia select rails based on checkout abandonment correlation with confirmation latency.
- Government Payments:Tax refunds and social transfers demand audit-grade traceability. The EU's instant payment availability rules compel public sector disbursement modernization.
Person-to-Person absorbs the bulk of installed capacity; Business-to-Business is expanding most quickly.
Technology:
Cloud-native architectures now attract the majority of new platform investment, displacing on-premise deployments.
- Cloud-Based Platforms:Elastic capacity provisioning enables banks to absorb volume spikes without permanent infrastructure overbuild. India's major private banks have migrated UPI processing to cloud stacks, driven by festival-season transaction surges that overwhelm fixed-capacity mainframes.
- APIs:Developer-first interfaces embed payment origination directly into merchant applications. Singapore's banking-as-a-service ecosystem leverages open API standards to let non-financial platforms initiate instant settlements.
- Mobile Wallets:Smartphone-native interfaces dominate consumer-facing origination layers. Kenya's M-Pesa demonstrates wallet-based real-time clearing without traditional bank account dependency.
- Blockchain:Distributed ledger trials focus on cross-border corridor settlement. Thailand's central bank pilots blockchain rails for regional remittance corridors with reduced correspondent banking friction.
- Near Field Communication:Contactless point-of-sale integration accelerates physical retail checkout velocity. South Korea's transit-integrated NFC payments create daily-use habituation that drives broader adoption.
Cloud-Based Platforms command the largest share of new capital deployment; APIs are climbing the fastest.
End User:
Procurement authority concentrates where transaction volume intersects with technical sophistication to mandate infrastructure modernization.
- E-Commerce Platforms:Online marketplaces now require instant merchant settlement as a competitive baseline. Amazon India and Flipkart negotiate sub-24-hour payout guarantees, converting payment rail selection into a vendor retention tool.
- Financial Institutions:Banks face regulatory compulsion to upgrade clearing architectures. The European Banking Authority's instant euro availability rules eliminate discretion to defer core system replacement.
- FinTech Companies:Neobanks and payment specialists build entirely on real-time-native stacks without legacy migration burden. Brazil's Nubank and India's Paytm originate from cloud-first infrastructure.
- Brick-and-Mortar Stores:Physical retail adoption lags due to POS terminal replacement costs. India's QR-code-based acceptance networks reduce hardware barriers for small merchants.
- Utility Providers:Bill collection infrastructure prioritizes reconciliation automation over settlement speed. Electricity and water distributors in developed markets maintain batch-oriented systems for consumer billing.
E-Commerce Platforms absorb the bulk of installed capacity; FinTech Companies are expanding most quickly.
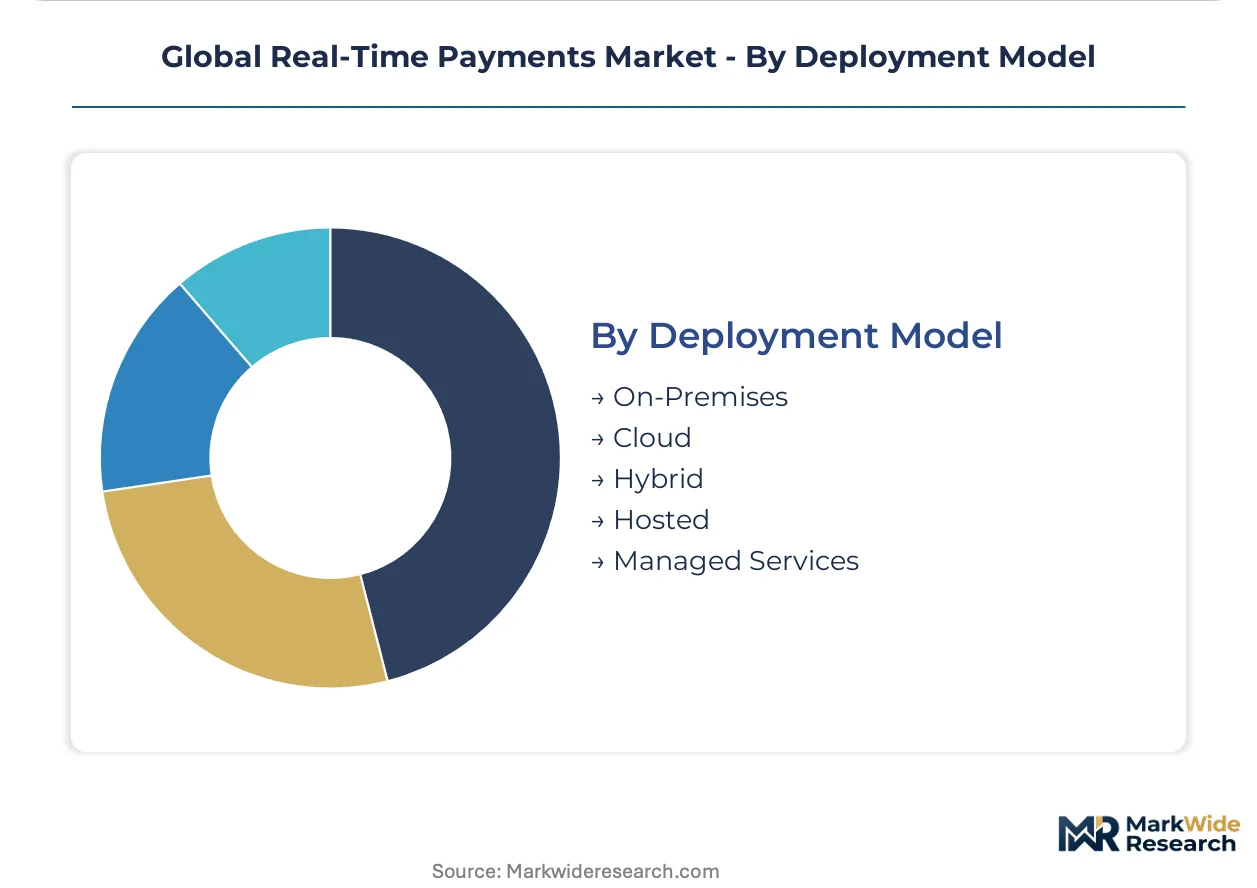
Deployment Model:
Operational model selection reflects risk tolerance for data sovereignty versus elasticity requirements.
- Cloud:Third-party infrastructure eliminates capital expenditure for capacity expansion. Australia's major banks deploy cloud-based real-time stacks to meet regulatory availability mandates without mainframe dependency.
- Hybrid:Sensitive transaction data remains on-premise while processing bursts shift to cloud. German banks favor hybrid architectures to satisfy Bundesbank data localization expectations.
- On-Premises:Legacy installations persist where regulatory scrutiny restricts external data handling. Swiss private banks maintain on-premise clearing for wealth management clients with confidentiality requirements.
- Hosted:Single-tenant dedicated infrastructure splits control and operational burden. Mid-tier banks in Canada select hosted models to access modern stacks without internal platform engineering.
- Managed Services:Outsourced operations transfer 24/7 staffing responsibility to specialists. UK building societies deploy managed real-time services to avoid nighttime operational coverage costs.
Cloud absorbs the bulk of installed capacity; Hybrid is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the heaviest transaction density, processing billions of monthly instant settlements through its national interface. Brazil and the European Union follow with regulatory-mandated network buildouts. The United States lags in interoperability despite multiple private clearing systems.
India
Mobile-first consumers and zero-merchant-fee economics drive volume through the national interface. The Reserve Bank of India mandates universal bank participation under strict oversight protocols. Mumbai's financial district anchors processing infrastructure scaling for festival-season transaction surges.
Brazil
Underbanked populations previously dependent on cash now access instant settlement through mandatory bank participation. The Central Bank of Brazil enforces 24/7 availability for government benefit disbursements. São Paulo's fintech cluster incubates wallet-native platforms bypassing traditional account dependencies.
United States
Enterprise treasury operations demand instant receivables visibility for working capital optimization. The Federal Reserve operates a public clearing service competing with private networks. New York's correspondent banking hub migrates cross-border flows to enriched messaging formats.
Germany
Industrial exporters require straight-through reconciliation for accounts payable automation. The European Banking Authority compels euro-denominated instant availability at negligible cost. Frankfurt's banking quarter modernizes core systems for continuous processing without batch windows.
Singapore
Regional headquarters procurement prioritizes API response latency for treasury aggregation. The Monetary Authority of Singapore licenses banking-as-a-service frameworks for non-financial payment origination. The city-state's technology corridor hosts cloud-native stacks serving Southeast Asian e-commerce platforms.
Global Real-Time Payments Market Competitive Landscape
Established network operators occupy the standard tier; emerging entrants pursue embedded finance integration and blockchain corridor settlement. The market structures around three archetypes: global card networks with clearing scale, core banking software providers with backward integration into payment rails, and API-native specialists embedding instant capabilities into merchant workflows. Consolidation pressure intensifies as volume concentrates among platforms processing festival-season spikes. Dominant competitive moves include strategic partnerships for cross-border interoperability and portfolio diversification into adjacent treasury services.
Within the network-scale tier, Mastercard Inc. and Visa Inc. anchor competitive positioning through corridor density and developer tooling respectively. Fiserv Inc. exemplifies the core-software-integrated archetype through its backward integration into banking systems feeding instant rails. Among specialists in merchant-facing APIs, Adyen N.V. occupies a position representing the checkout-embedded instant settlement model.
| Leading Market Players |
|---|
| ACI Worldwide Inc. |
| Fiserv Inc. |
| Mastercard Inc. |
| Visa Inc. |
| PayPal Holdings Inc. |
| Temenos AG |
| Finastra |
| Ripple Labs Inc. |
| Adyen N.V. |
| Others |
Supply & Pricing Matrix
Platform engineering talent clusters in Bangalore and Singapore create labor-cost differentials that widen pricing-tier spreads between premium cloud-native stacks and economy-tier hosted alternatives. The Reserve Bank of India's interoperability mandates compress margins for domestic providers while EU Payment Services Directive compliance costs inflate European pricing bands.
Pricing Analysis
Volume-versus-margin splits sharply across deployment architectures. Cloud-based platforms command subscription-tiered pricing with elasticity premiums, while on-premise installations trade at project-based licensing with customization uplifts. ISO 20022 certification tier and transaction volume scale drive price differentiation between correspondent banks and regional processors. Pricing pressure stems from India's zero-merchant-fee UPI economics forcing competitive compression elsewhere. Small and medium enterprises exhibit highest price sensitivity; multinational retailers with treasury aggregation demands show least.
Supply Chain Analysis
Dual-sourcing requirements from tier-one banks mandate multi-cloud qualification across AWS, Azure, and Google Cloud platforms alongside regional providers. Core infrastructure draws from India, Ireland, and Singapore for data center concentration; specialized fraud detection components source from Israel and the United Kingdom. Supply chain risk centers on single-source vulnerability for ISO 20022 messaging gateways. Distribution runs through direct enterprise sales teams for large financial institutions and API marketplaces for developer-centric adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as festival-season volume spikes force subscale processors into distressed exits. Regulatory interoperability mandates eliminate technical moats that previously sustained regional specialists.
For Market Incumbents: Acquire cloud-native processing stacks to absorb elasticity demands that overwhelm legacy mainframe architectures. Integrate backward into core banking software to lock clearing relationships before open banking APIs commoditize rail access. Defend against neobank-native challengers by embedding instant settlement into merchant checkout flows as a retention tool. For New Entrants and Emerging Players: Underbanked merchant segments in Southeast Asia offer the most penetrable white-space target, bypassing saturated India and Brazil corridors. Brazil's Pix ecosystem expansion into micro-entailment presents a second entry vector. Pursue banking-as-a-service licensing to originate payments from non-financial platforms without direct bank charter requirements. For Investors and Strategic Acquirers: Re-rating potential sits with API-native specialists given embedded finance convergence accelerating revenue multiple expansion. Long-term viability favors platforms with demonstrated festival-season resilience and cross-border corridor density. Watch for FedNow-The Clearing House interoperability breakthroughs as the inflection signal for US market consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Migration Completion | Enables straight-through processing for B2B accounts payable automation across EU and Asian corridors. |
| Cloud-Native Stack Acquisition | Absorbs volume spikes without permanent infrastructure overbuild during India's festival seasons. |
| Cross-Border Interoperability Partnership | Links India's UPI with Singapore's PayNow to capture remittance corridor density. |
| Banking-as-a-Service API Licensing | Allows e-commerce platforms to originate payments under Monetary Authority of Singapore frameworks. |
| Request-to-Pay Messaging Deployment | Automates invoice reconciliation for German industrial exporters using structured remittance data fields. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with payment network executives, core banking software architects, and merchant platform CTOs validated demand assumptions. Central bank annual reports, SEC 10-K disclosures from listed processors, and NPCI transaction bulletins supplied volume benchmarks. Bottom-up transaction flow modeling triangulated against top-down market sizing from banking association aggregates.
Granularity-level modeling deployed payment-type, deployment architecture, and end-user vertical dimensions at country-level resolution. Cloud versus on-premise splits were projected across the analysis window using elasticity demand curves derived from India's festival-season patterns. CAGRs emerged from logistic adoption curves fitted to UPI and Pix penetration trajectories. ISO 20022 migration timelines and open banking mandate enforcement dates shaped regional divergence assumptions.
Revisions become necessary when central bank interoperability mandates accelerate or delay, when cloud provider regional availability shifts, or when fraud loss ratios breach operational thresholds. Deviation in FedNow network adoption velocity would shift the North American outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
US Virtual Cards Market
Payments
E-Commerce Payments Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Digital Payment in Healthcare Market
Payments
Europe Payment Analytics Software Market
Payments
Global Prepaid Cards Market
Payments
Mobile Money Market
Payments
United Arab Emirates Payment Market
Payments
Crypto Payment Gateway Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Electronic Cash Register Market
Payments
France Buy Now Pay Later Services Market
Payments
Canada Payment Gateway Market
Payments
Slovakia POS Terminal Market
Payments
Russia Payments Market
Payments
Buy Now Pay Later Platform Market