
 Epayment System Market | 2026-2036
Epayment System Market Size, Share, and Industry Trends Forecast 2026-2036
Epayment System Market Analysis
The EU Green Deal is realigning data center energy standards for payment infrastructure operators, forcing cloud migration timelines. Stripe Inc. leverages developer-centric API architectures to sustain merchant acquisition in high-growth corridors. Adyen N.V. anchors unified commerce platforms across omnichannel retail environments. Visa Inc. dominates tokenization standards that secure card-not-present transactions.
An epayment system comprises hardware, software, and network protocols that authorize, clear, and settle monetary transactions without physical currency exchange, typically processing within sub-second latency through encrypted communication channels. These systems serve commercial purpose by reducing friction in consumer-to-business and peer-to-peer transfers while generating transaction fee revenue for platform operators. Digital wallet deployment leads transaction volume growth among payment method segments, reflecting consumer preference for credential vaulting and one-tap checkout. Cloud-based infrastructure expands fastest within deployment type categories as processors abandon on-premises hardware maintenance. NFC technology occupies mature retail point-of-sale environments while QR code adoption accelerates in emerging market merchant segments.
The European Banking Authority enforces Strong Customer Authentication under PSD2, compelling multi-factor verification for transaction values exceeding thresholds. The RBI mandates tokenization of card data for domestic Indian transactions, reshaping issuer-processor relationships and vaulting economics. The PCI Security Standards Council governs global data protection benchmarks that determine market access for platform providers. Stakeholders must monitor central bank digital currency pilots that threaten to disintermediate traditional card networks.
Market Dynamics
Real-time payment rails and tokenization mandates are compressing settlement windows while fragmenting processor economics across merchant tiers.
Growth Catalysts
- UPI Infrastructure Expansion:India's unified payments interface mandates from the RBI are onboarding merchants at scale through interoperable QR codes and zero-MDR incentives for small-value transactions.
- PSD2 Strong Customer Authentication:The European Banking Authority's multi-factor verification requirements for transactions above thresholds are driving credential vaulting adoption among European issuers.
- Cloud-Native Processing Architectures:Payment service providers are abandoning on-premises hardware maintenance for elastic compute capacity that scales with transaction volume volatility.
Market Restraints
- Tokenization Compliance Costs:The RBI's domestic card data vaulting mandate forces issuers to rebuild processor relationships and absorb vaulting economics previously externalized.
- Data Center Energy Standards:The EU Green Deal is realigning infrastructure requirements for payment operators, compressing cloud migration timelines and stranding legacy hardware investments.
- Central Bank Digital Currency Disintermediation:Pilot programs from monetary authorities threaten to bypass traditional card networks by enabling direct liability transfers between consumers and central banks.
Strategic Opportunities
- Embedded Finance Convergence:Non-financial platforms in ride-hailing and e-commerce are integrating checkout infrastructure through API-first architectures that capture transaction flow.
- QR Code Merchant Penetration:Emerging market street vendors and micro-merchants remain underpenetrated by NFC terminals, creating white space for camera-based payment acceptance.
- EU AI Act Authentication Protocols:Biometric verification requirements for high-risk financial applications are opening procurement windows for behavioral analytics and liveness detection vendors.
Industry Challenges
- Legacy Core System Integration:Tier-2 banks face multi-year re-platforming cycles to connect real-time payment rails with batch-oriented settlement infrastructure.
- PCI-DSS Certification Velocity:The PCI Security Standards Council's evolving data protection benchmarks extend compliance timelines for new market entrants seeking processor licenses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epayment System Market |
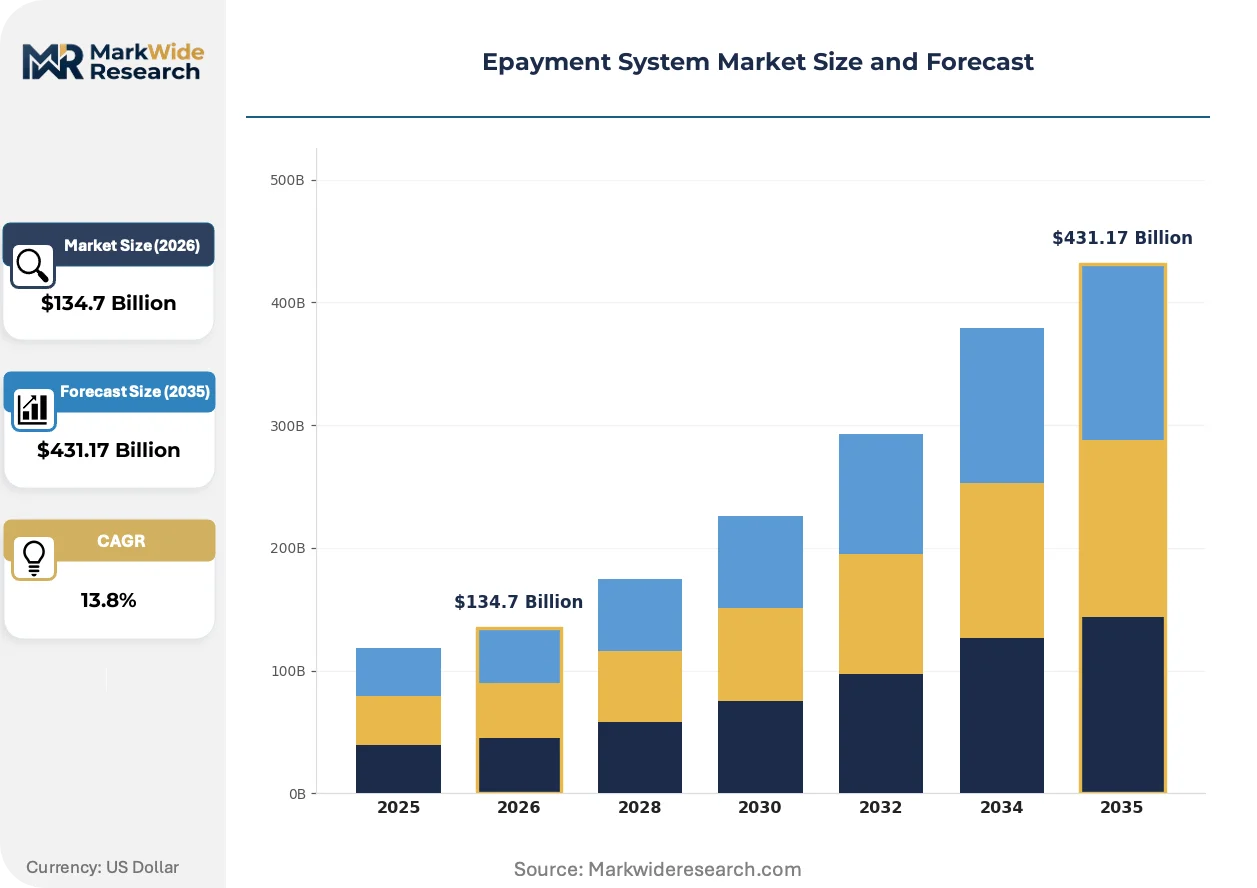
| Market Size in 2026 | $134.7 Billion |
| Market Size in 2035 | $431.17 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer End User: Retailers, Merchants, Service Providers, Consumers Technology: NFC, QR Code, Tokenization, Blockchain Deployment Type: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | PayPal Holdings Inc., Stripe Inc., Adyen N.V., ACI Worldwide Inc., Fiserv Inc., Global Payments Inc., Visa Inc., Mastercard Incorporated, Alipay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epayment System Market Emerging Trajectories
Authentication protocols and settlement infrastructure are converging around sub-second latency requirements that reshape hardware procurement and software architecture decisions.
Biometric payment verification is electrifying point-of-sale transaction flows. Fingerprint and facial recognition systems authenticate users without credential entry. Large-format retailers in Asia-Pacific are deploying these terminals at self-checkout lanes. This compression of authentication steps is electrifying throughput metrics while reducing cart abandonment at high-traffic merchant locations.
The EU AI Act is reshaping risk classification for automated payment decisions. High-risk algorithmic systems must maintain human oversight and audit trails. European payment service providers are rebuilding decision engines to comply with transparency requirements. Affected segments include real-time fraud scoring and dynamic transaction routing where explainability mandates are forcing architecture redesigns.
Merchant acquisition models are unbundling from bundled hardware-software contracts. Small and mid-size retailers now procure payment acceptance as a service with per-transaction pricing rather than terminal purchase commitments. This shift is most visible in India and Southeast Asia where platform-native sellers demand API-first onboarding without physical device logistics. Channel disruption favors cloud-native processors over legacy terminal distributors.
Epayment System Market Segmentation
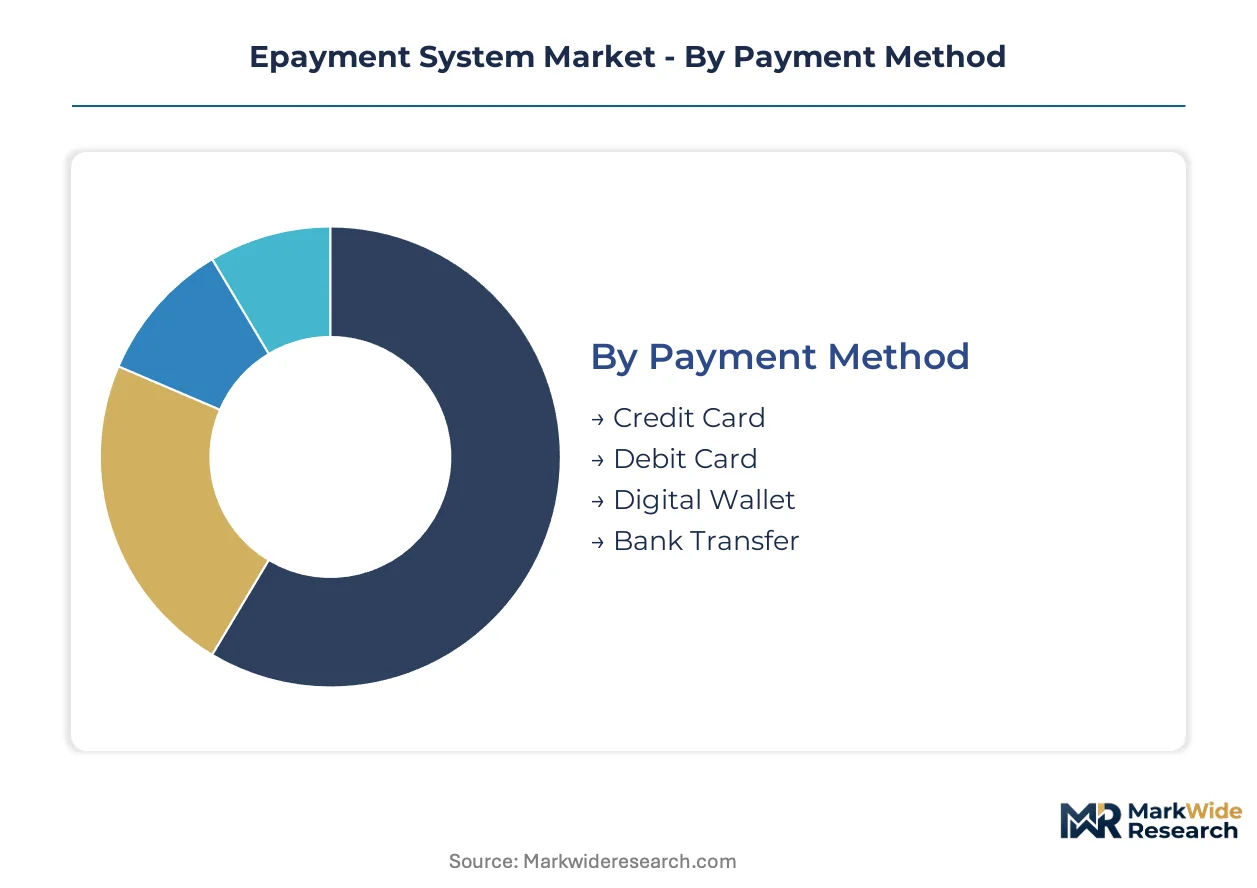
Epayment system segmentation reveals divergent capital requirements across infrastructure layers. Payment processors allocate resources differently between credential vaulting, terminal hardware, and cloud compute depending on target merchant tiers and regulatory jurisdictions.
Payment Method:
Capital intensity peaks in segments requiring issuer-processor coordination and compliance infrastructure, while lighter-weight methods bypass traditional banking rails.
- Digital Wallet:Credential vaulting architectures demand substantial upfront investment in tokenization infrastructure and PCI-DSS certification. Demand concentrates among mobile-first consumers in India, where RBI mandates for domestic card tokenization are forcing wallet providers to rebuild vaulting relationships with issuers.
- Credit Card:Interchange economics and fraud liability frameworks require sustained capital deployment in risk scoring engines and chargeback management systems. European issuers are absorbing compliance costs under PSD2 Strong Customer Authentication mandates for transactions above regulatory thresholds.
- Debit Card:Direct liability to deposit accounts necessitates real-time balance verification infrastructure.
- Bank Transfer:ACH and real-time payment rail integration carries lower per-transaction margins but reduced fraud exposure.
Credit card infrastructure absorbs the bulk of installed processing capacity; digital wallet deployment is expanding most quickly across emerging market corridors.
End User:
Merchant scale determines procurement patterns, with enterprise retailers demanding unified commerce platforms while micro-merchants prioritize zero-hardware onboarding.
- Retailers:Omnichannel checkout integration requires substantial investment in POS-terminal-cloud synchronization and inventory-linked payment flows. Large-format merchants in Asia-Pacific are deploying biometric verification terminals at self-checkout lanes to compress authentication latency.
- Merchants:Street vendors and micro-enterprises drive volume through QR-code acceptance with minimal capital outlay. India's UPI infrastructure mandates from the RBI are onboarding these merchants at scale through interoperable QR codes and zero-MDR incentives for small-value transactions.
- Service Providers:Subscription billing and recurring payment architectures require vaulting and dunning management capabilities.
- Consumers:Peer-to-peer transfer demand centers on mobile-native interfaces with social feature integration.
Retailers command the highest per-site infrastructure spend; merchant segments are climbing the fastest as QR-code penetration accelerates in underbanked corridors.
Technology:
Authentication mechanisms split between mature NFC terminal estates and emerging camera-based protocols with diverging hardware economics.
- NFC:Contactless terminal deployment requires certified hardware with embedded secure elements and antenna arrays. Mature retail environments in developed markets have saturated POS infrastructure, though replacement cycles accelerate as biometric terminals enter the refresh window.
- QR Code:Camera-based acceptance eliminates dedicated terminal procurement, shifting investment to software-based code generation and dynamic URL routing. Emerging market merchant segments in Southeast Asia favor API-first onboarding without physical device logistics.
- Tokenization:Vaulting infrastructure demands cryptographic key management and HSM deployment for card-not-present security.
- Blockchain:Distributed ledger settlement carries regulatory uncertainty and energy consumption constraints under EU Green Deal standards.
NFC retains the largest installed terminal base; QR code adoption is gaining share fastest among platform-native sellers.
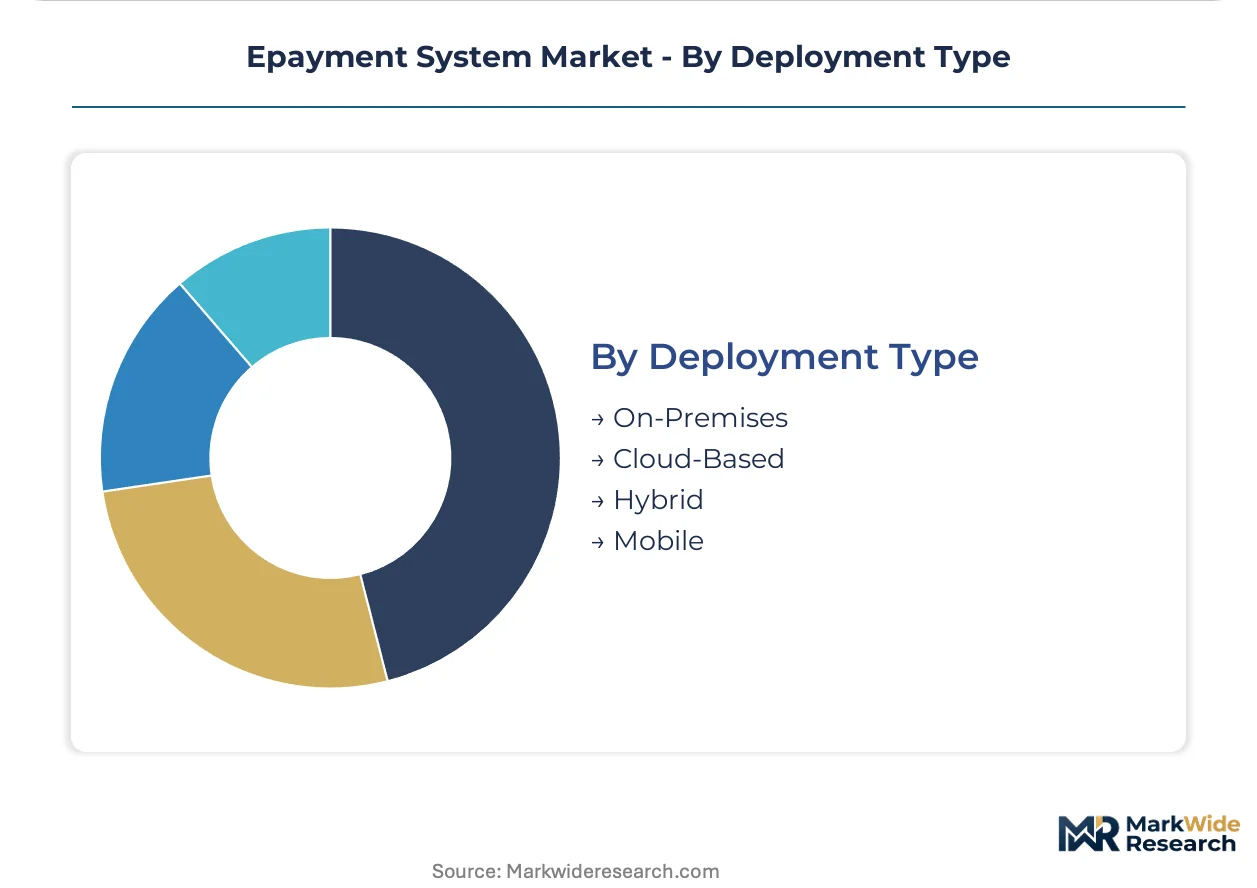
Deployment Type:
Infrastructure location decisions hinge on transaction volume volatility, data residency mandates, and stranded asset risk from shifting energy standards.
- Cloud-Based:Elastic compute capacity eliminates stranded hardware risk while scaling with volume spikes. The EU Green Deal is compressing migration timelines as data center energy standards realign, forcing payment operators to abandon on-premises maintenance contracts.
- On-Premises:Dedicated hardware retains regulatory appeal in jurisdictions with strict data localization mandates. Legacy core system integration challenges confront Tier-2 banks facing multi-year re-platforming cycles to connect real-time rails with batch settlement infrastructure.
- Hybrid:Sensitive authentication data remains local while transaction routing leverages cloud elasticity.
- Mobile:SDK-based deployment minimizes merchant IT involvement but increases platform dependency risk.
On-premises infrastructure carries the largest legacy installed base; cloud-native architectures are expanding most quickly as processors abandon hardware maintenance obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bengaluru's fintech corridor anchors the highest concentration of payment infrastructure development activity, with the city hosting the densest cluster of API-first processors and regulatory technology vendors serving emerging market corridors.
United States
Real-time payment rail adoption and merchant demand for unified commerce platforms drive infrastructure investment. The Federal Reserve's FedNow service mandates are compelling financial institutions to modernize legacy settlement systems. Silicon Valley and New York Metro house the dominant clusters of cloud-native processors and card network operators expanding tokenization standards.
India
UPI transaction volume expansion and QR-code merchant onboarding at scale reshape domestic payment economics. The RBI's zero-MDR mandate for small-value transactions and tokenization requirements for card data are forcing processor relationship rebuilds. Mumbai and Bengaluru concentrate the API-first infrastructure vendors capturing platform-native seller demand.
Germany
PSD2 Strong Customer Authentication compliance and open banking API integration drive credential vaulting investment. The EU AI Act's biometric verification requirements for high-risk financial applications are opening procurement windows for behavioral analytics vendors. Frankfurt and Berlin anchor the core clusters of payment service providers rebuilding decision engines for explainability mandates.
United Kingdom
Open banking payment initiation and real-time account-to-account transfers displace card volume in e-commerce checkout. The Financial Conduct Authority's operational resilience requirements are compressing cloud migration timelines for Tier-2 institutions. London's Square Mile hosts the densest concentration of fintech infrastructure vendors serving European merchant corridors.
Singapore
Cross-border remittance corridor demand and ASEAN merchant acquisition drive platform expansion. The Monetary Authority of Singapore's digital payment licensing framework is consolidating vendor participation in the city-state. The Marina Bay financial district concentrates regional headquarters for processors targeting Southeast Asia's underpenetrated QR-code merchant segments.
Epayment System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across API sophistication and developer ecosystem depth, with the market consolidating around three tiers: global card networks with tokenization standards dominance, unified commerce platforms with omnichannel integration capabilities, and API-first processors with embedded finance penetration. Strategic moves concentrate on M&A for regulatory technology capabilities and geographic expansion through local licensing partnerships.
Within the unified commerce tier, Adyen N.V. and Stripe Inc. exemplify platform architectures that capture merchant flow across online and in-store environments. Among network operators, Visa Inc. anchors tokenization standard-setting for card-not-present security. These three occupy positions that reflect divergent bets on developer-centric onboarding versus enterprise sales velocity.
| Leading Market Players |
|---|
| PayPal Holdings Inc. |
| Stripe Inc. |
| Adyen N.V. |
| ACI Worldwide Inc. |
| Fiserv Inc. |
| Global Payments Inc. |
| Visa Inc. |
| Mastercard Incorporated |
| Alipay |
| Others |
Supply Flow & Price Mechanics
Cloud compute costs cascade through payment processor pricing tiers, with elastic infrastructure expenses from AWS and Azure regions compressing margins for mid-tier SaaS providers serving small merchants in India and Southeast Asia.
Pricing Analysis
Transaction throughput anchors value-based pricing for enterprise payment orchestration platforms. Three-tier pricing structure across premium API suites, standard gateway services, and economy QR-code acceptance separates tiered merchant commitments. Pricing pressure stems from zero-MDR mandates in India's UPI corridor forcing processor margin compression. Micro-merchants exhibit highest price sensitivity, while omnichannel retailers absorb premium tiers for unified commerce integration.
Supply Chain Analysis
Cross-border data center provisioning and subsea cable latency costs concentrate supply chain risk for real-time payment infrastructure. Hardware secure element manufacturing draws from Taiwan, South Korea, and Germany. Cloud-native processors source cryptographic key management modules and HSM appliances from these hubs. Single-source vulnerability in semiconductor foundry capacity threatens terminal refresh cycles. Distribution runs through direct API partnerships and channel reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payment infrastructure is becoming a vertical-integration race, with processors pursuing upstream control over tokenization vaults and downstream capture of merchant checkout real estate.
For Market Incumbents: Lock in issuer relationships through exclusive tokenization vaulting contracts before RBI and PSD2 mandates fully reshape processor economics. Acquire regulatory technology capabilities for EU AI Act compliance to defend against biometric authentication entrants. Prioritize cloud-native architecture migration to avoid stranded hardware risk from EU Green Deal energy standards.
For New Entrants and Emerging Players: Begin with QR-code merchant acquisition in underpenetrated Southeast Asian street vendor segments where NFC terminal density remains low. Target platform-native sellers in India's UPI ecosystem through zero-hardware API onboarding. Pursue embedded finance partnerships with ride-hailing and e-commerce platforms to capture transaction flow without direct merchant sales cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor API-first processors with Indian payment system operator licenses and established issuer-processor relationships. Long-term viability hinges on regulatory technology differentiation and cloud-native cost structures. Watch central bank digital currency pilot announcements as disintermediation inflection signals for traditional card network exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Tokenization Vault Acquisition | Captures RBI-mandated domestic card data vaulting economics ahead of compliance deadlines. |
| Biometric Terminal Deployment | Compresses authentication latency for Asia-Pacific large-format retail self-checkout lanes. |
| Cloud-Native Architecture Migration | Eliminates stranded hardware risk under EU Green Deal data center energy standards. |
| Embedded Finance API Integration | Captures transaction flow from non-financial platforms in ride-hailing and e-commerce. |
| QR-Code Merchant Onboarding | Penetrates underbanked Southeast Asian street vendor segments without terminal logistics. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for payment infrastructure trade flows and hardware component sourcing. Primary interviews with payment platform CTOs, merchant acquisition heads, issuer processor relationship managers, and regulatory compliance officers combined with secondary validation from RBI circulars, EU AI Act documentation, PCI Security Standards Council publications, and SEC 10-K disclosures from listed processors. Bottom-up transaction volume modeling and top-down market sizing triangulated segment estimates.
Granularity-level modeling deployed payment method, end user, technology, and deployment type dimensions at country-level resolution across the projection horizon. Cloud infrastructure spend, merchant onboarding velocity, and real-time payment rail adoption curves fed analytical frameworks. CAGRs derived from segment-level volume trajectories and value-per-transaction compression trends.
Underlying measurement precision varies by segment; digital wallet and QR-code adoption carry tighter precision than blockchain settlement projections. Forecasts reflect assumptions on regulatory timeline adherence and central bank digital currency pilot scope. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Israel Credit Cards Market
Payments
France Buy Now Pay Later Services Market
Payments
Wireless POS Terminals Market
Payments
Retail Cash Management Market
Payments
China Real Time Payments Market
Payments
Cryptocurrency Payment Apps Market
Payments
Netherlands POS Terminal Market
Payments
South Korea POS Terminals Market
Payments
Payment Analytics Software Market
Payments
Payment Security Market
Payments
Contactless Payment Market
Payments
Payment Security Software Market
Payments
China POS Terminals Market
Payments
Denmark POS Terminals Market
Payments
Mobile Point of Sale (POS) Market
Payments
Mobile Payment Transaction Market