
 Mobile Card Reader Market | 2026-2036
Mobile Card Reader Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Card Reader Market Intelligence
The traditional direct sales channel from payment processors to merchants is fragmenting under pressure from new distribution players. Square leverages its integrated hardware and software ecosystem to capture micro-retailers. PayPal extends its vast online payment user base into physical point-of-sale environments. SumUp specializes in providing low-cost, simple devices specifically for European and Latin American small businesses.
A mobile card reader is a compact hardware peripheral that connects to a mobile device like a smartphone or tablet via Bluetooth or a physical port. These devices are engineered to read payment card data through magnetic stripe, EMV chip, or NFC for contactless transactions. Within technology segments, NFC-enabled readers represent the fastest-growing category due to consumer preference for tap-to-pay. While multi-function readers that combine all technologies are becoming standard, dedicated chip card readers still hold a significant base in markets transitioning from magnetic stripe.
Hardware design and data handling are governed by the global PCI DSS framework, which mandates security protocols for payment processing. In parallel, regulations like Europe's GDPR and certifications from bodies such as the US FCC for wireless emissions impose strict compliance hurdles for market entry. Vendor success depends on navigating the complex interplay between evolving security standards, hardware cost-down pressures, and the integration of alternative payment methods.
Market Dynamics
The market's structure is defined by the tension between rapid hardware commoditization and the escalating costs of security compliance. Mandatory adherence to the Payment Card Industry Data Security Standard (PCI DSS) establishes a high barrier to entry, favoring established vendors.
Growth Catalysts
- Government Digitalization Initiatives:Policies promoting cashless economies, such as India's Digital India program and Brazil's PIX system, are accelerating the adoption of mobile payment devices among small merchants and service providers.
- Consumer Preference for Contactless:A strong consumer shift toward NFC-enabled tap-to-pay transactions for speed and hygiene compels merchants to upgrade their hardware, driving a replacement cycle for older, non-NFC readers.
- Growth of Micro-Merchants:The expansion of the gig economy, market stalls, and pop-up retail creates a substantial customer base requiring low-cost, portable, and easy-to-use payment acceptance solutions.
Market Restraints
- Network Infrastructure Gaps:Device functionality relies on stable cellular or Wi-Fi connectivity, rendering them less effective in rural or remote areas with poor network coverage and limiting market penetration.
- Security Certification Costs:The significant financial investment and technical expertise required to achieve and maintain mandatory PCI DSS and EMVCo certifications act as a major structural barrier for new hardware startups.
- QR Code Payment Substitution:In many Asian markets, the widespread adoption of QR code-based mobile payments provides a low-cost software alternative that can bypass the need for a dedicated card reader peripheral.
Strategic Opportunities
- Integrated Software Services:Bundling value-added services like inventory management, customer analytics, and loyalty programs into the reader's companion app creates opportunities for recurring software-as-a-service (SaaS) revenue.
- Biometric Security Integration:Incorporating fingerprint or other biometric sensors directly into reader hardware presents a future pathway to enhance transaction security beyond PINs, creating a new premium product tier.
- Expansion in African Markets:Countries such as Nigeria, Kenya, and South Africa are experiencing rapid growth in mobile money and digital banking, representing underpenetrated markets for affordable mobile card readers.
Industry Challenges
- Secure Firmware Deployment:A significant operational challenge involves managing secure over-the-air firmware updates across a vast and diverse fleet of deployed devices to patch critical vulnerabilities without disrupting merchant operations.
- Interoperability with POS Systems:Ensuring seamless plug-and-play compatibility with a highly fragmented global ecosystem of third-party point-of-sale software and business applications remains a persistent engineering hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Card Reader Market |
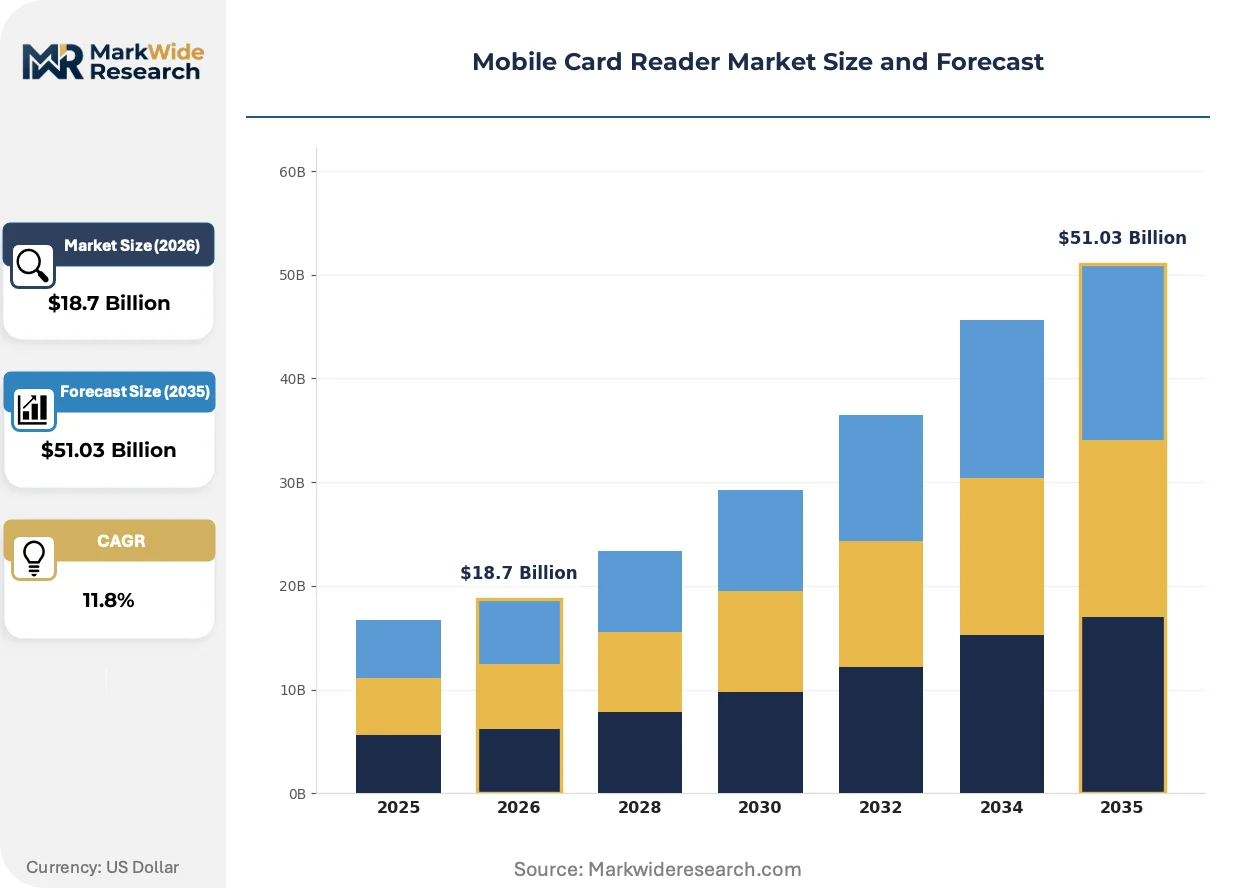
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $51.03 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tap Card Readers, Chip Card Readers, Contactless Readers, Multi-Function Readers End User: Retailers, Restaurants, eCommerce Merchants, Market Stall Owners Technology: Bluetooth, USB, Wi-Fi, NFC Distribution Channel: Online Retailers, Direct Sales, Value-Added Resellers, Third-Party Distributors |
| Companies Covered | PayPal, Worldpay, Square, Checkout.com, Global Payments, Stripe, Fiserv, SumUp, Adyen NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Card Reader Market Strategic Shifts & Innovations
The evolution from single-purpose payment hardware to integrated commerce enablement tools is the central theme. This shift is driven by software, connectivity, and the demand for business insights directly from the point of sale.
Multi-function readers that combine magnetic stripe, EMV chip, and NFC in one unit are the current product standard. Small businesses and micro-retailers are the primary adopters, seeking to maximize payment acceptance and avoid lost sales. The market's hardware focus is migrating from single-function readers toward these versatile, all-in-one peripherals that offer universal card compatibility.
Europe's General Data Protection Regulation (GDPR) places stringent requirements on the collection and processing of personal data. This forces manufacturers to embed privacy-by-design principles into their hardware and software, ensuring robust data encryption and transparent consent management. The fintech segment targeting European merchants is most affected, investing heavily in compliance to build trust and gain market access.
Merchants increasingly prefer self-service onboarding and direct online purchasing of hardware. This model disrupts the traditional distribution channel, which relied on sales agents from banks or payment processors. The shift is most pronounced among sole proprietors and new businesses in North America who prioritize speed, transparent pricing, and autonomy over managed installation.
Mobile Card Reader Market Segmentation
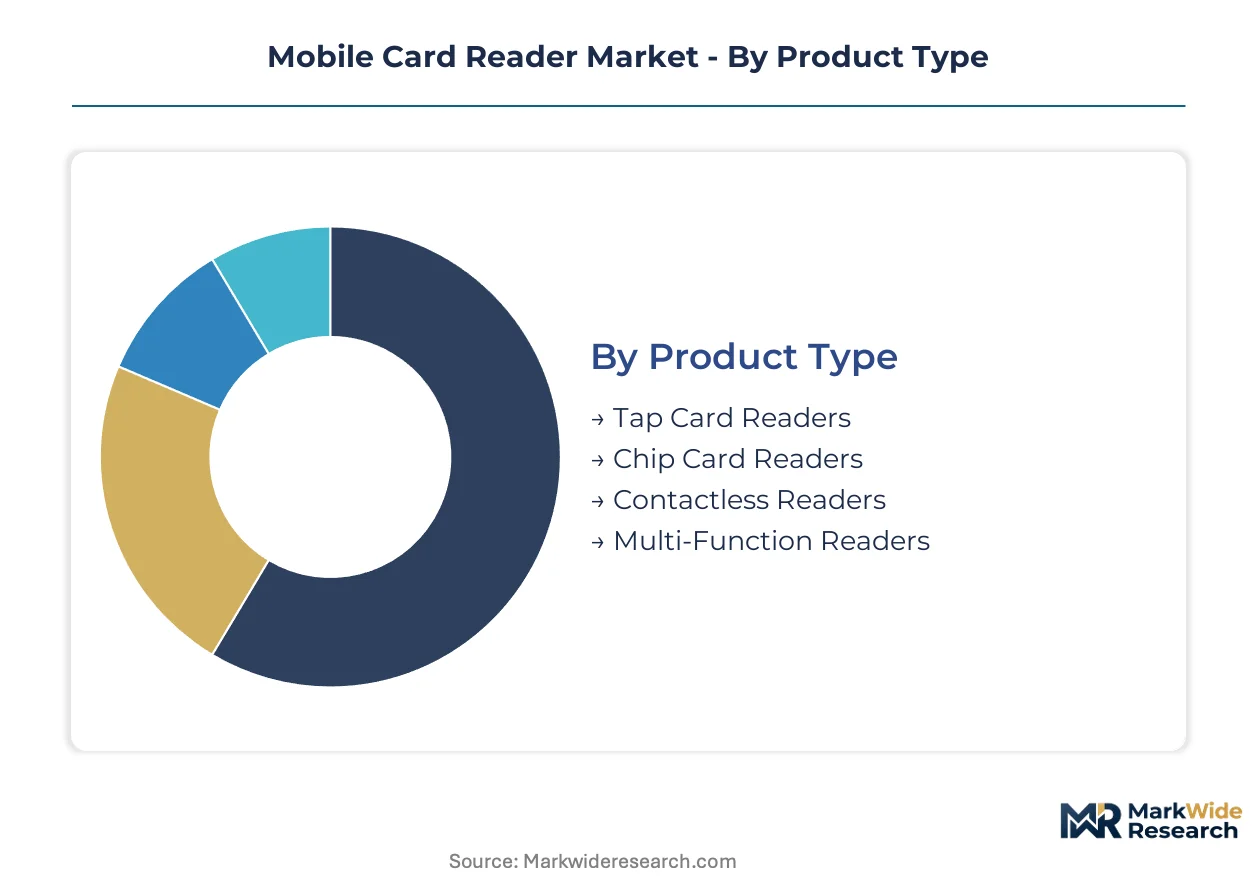
The mobile card reader market's segmentation provides a detailed lens into technology adoption patterns, end-user preferences, and evolving distribution strategies. Understanding these distinct segments helps manufacturers and service providers tailor offerings to specific merchant needs, from micro-businesses to established retailers. Each category reflects unique compliance requirements and operational demands across different payment ecosystems.
Product Type:
The product type spectrum shows a clear shift towards versatile, all-encompassing devices, yet specialized readers retain importance in specific transition markets.
- Multi-Function Readers:These devices integrate magnetic stripe, EMV chip, and NFC capabilities into a single unit, providing universal payment acceptance. Demand concentrates among small businesses and market stall owners in India and Brazil, who seek to maximize transaction options and reduce hardware complexity.
- Contactless Readers:Designed for NFC-enabled tap-to-pay transactions, these readers cater to consumer preferences for speed and hygiene. The strong consumer shift towards NFC payment methods in Europe compels merchants to upgrade hardware, driving a significant replacement cycle.
- Tap Card Readers:These devices primarily facilitate NFC-based transactions, gaining traction where contactless payments are prevalent.
- Chip Card Readers:Dedicated hardware for EMV chip card processing, these readers remain essential in markets still transitioning from magnetic stripe technology.
Multi-Function Readers handles the majority of throughput; Contactless Readers is the fastest mover on share.
End User:
The end-user segmentation highlights the diverse operational contexts and scale requirements for mobile payment acceptance solutions.
- Market Stall Owners:This segment includes micro-merchants, gig economy workers, and pop-up retailers requiring highly portable, low-cost, and easy-to-use payment acceptance solutions. The expansion of the gig economy in countries like Nigeria and Kenya drives demand for these affordable devices.
- Retailers:Traditional brick-and-mortar stores, ranging from small boutiques to larger chains, utilize mobile card readers for queue busting, mobile sales, and enhanced customer service. Retailers in North America leverage integrated software services for inventory management alongside payment processing.
- Restaurants:Food service establishments employ mobile readers for tableside payments, improving efficiency and customer experience.
- eCommerce Merchants:While primarily online, these businesses use mobile card readers for pop-up events, in-person pickups, and returns, extending their digital presence into physical touchpoints.
The growth of Micro-Merchants continues to expand the customer base for mobile card readers, while traditional Retailers represent a consistent, established demand.
Technology:
Connectivity technology defines the operational flexibility and integration capabilities of mobile card readers within various merchant environments.
- Bluetooth:This wireless technology enables seamless connection between the card reader and a mobile device (smartphone or tablet), offering portability and ease of setup. Small businesses in European markets favor Bluetooth readers for their simplicity and low power consumption.
- NFC:Near Field Communication technology facilitates contactless payments, allowing consumers to tap their cards or mobile wallets for transactions. Consumer preference for tap-to-pay in countries like Australia and Canada accelerates the adoption of NFC-enabled readers.
- USB:Wired connections via USB provide reliable data transfer and power, often used in stationary or semi-mobile setups.
- Wi-Fi:Readers with Wi-Fi connectivity offer greater range and can operate independently of a specific mobile device, integrating into existing network infrastructures.
Bluetooth connectivity provides widespread accessibility for mobile devices, while NFC technology experiences the steepest expansion trajectory due to consumer demand.
Distribution Channel:
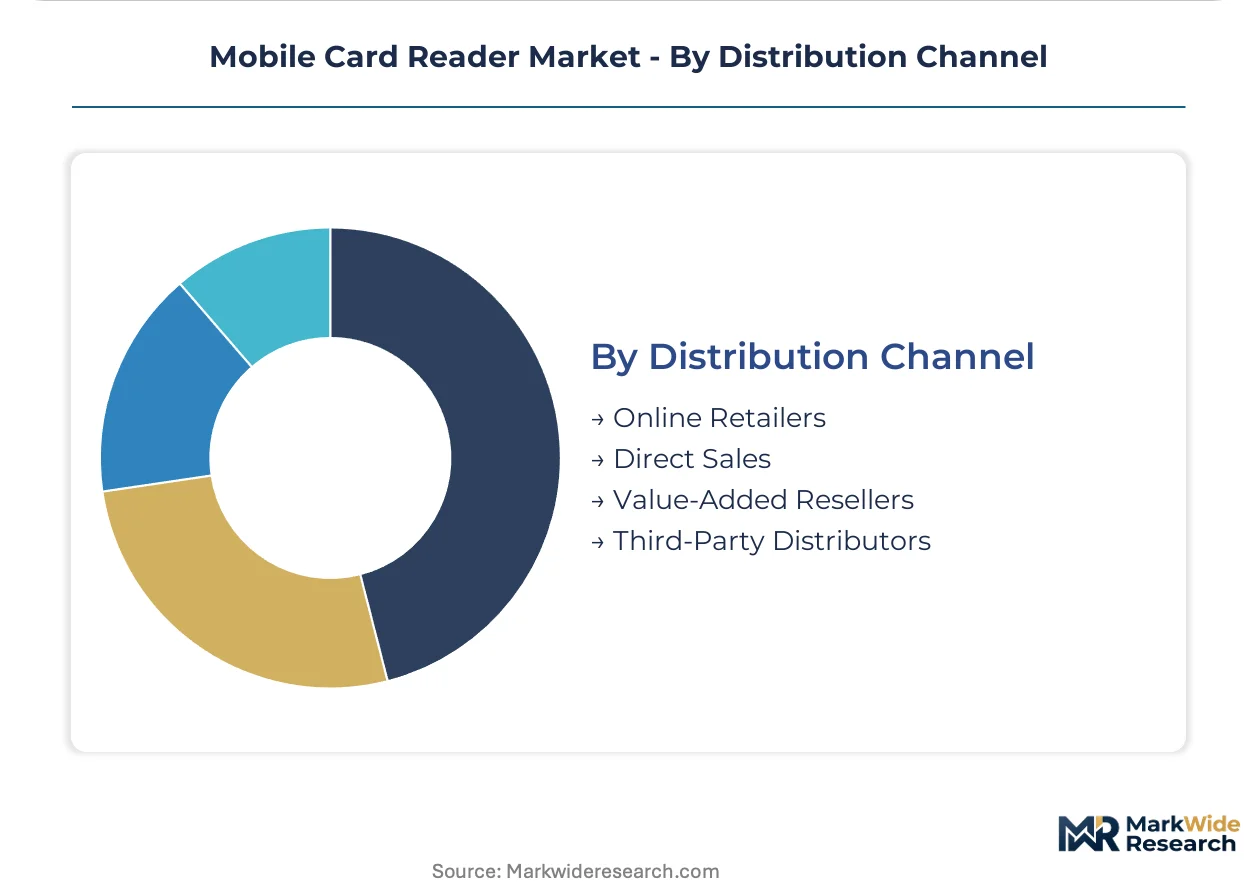
The distribution landscape for mobile card readers is evolving, with new channels challenging traditional sales models and reaching diverse merchant types.
- Online Retailers:E-commerce platforms and dedicated online stores provide merchants with direct access to a wide range of mobile card reader hardware, often with transparent pricing and self-service onboarding. Sole proprietors and new businesses in North America prioritize direct online purchasing for its speed and autonomy.
- Direct Sales:Payment processors and financial institutions historically sold card readers directly to their merchant clients, offering bundled services and support. This channel remains significant for established businesses seeking comprehensive payment solutions from their primary banking partners.
- Value-Added Resellers:These partners combine card reader hardware with complementary software, services, or specialized POS systems for niche markets.
- Third-Party Distributors:Broad distribution networks supply mobile card readers to various retail outlets, electronics stores, and business-to-business channels.
Online Retailers are rapidly gaining market share through direct-to-merchant models, while Direct Sales channels maintain a foundational position with integrated service offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between developed and emerging markets, with hardware commoditization more advanced in Asia and Latin America. North American and European markets often support higher price points for integrated software ecosystems. This divergence shapes vendor strategies for market entry and product localization.
India
Demand for mobile card readers in India stems from its vast micro-merchant base and rapid digital payment adoption. The government's Digital India program actively promotes cashless transactions across the country. Cities like Bangalore and Mumbai show high concentrations of small businesses upgrading their payment infrastructure.
Brazil
Brazil exhibits strong demand due to the widespread success of its PIX instant payment system, driving digital transaction volumes. ANVISA regulations for electronic devices ensure compliance with local standards for market entry. The São Paulo metropolitan area, a major economic hub, sees significant deployment among small and medium-sized enterprises.
Germany
German merchants increasingly adopt mobile card readers, driven by consumer preference for secure contactless payments. Europe's GDPR mandates stringent data protection, influencing hardware and software design for privacy-by-design. Berlin and Munich, with their thriving startup and small business scenes, represent key adoption centers.
United States
The United States market benefits from a strong gig economy and the expansion of pop-up retail, necessitating portable payment solutions. FCC certifications for wireless emissions are mandatory for all devices sold in the country. Major urban centers like New York City and Los Angeles show high usage among diverse service providers.
Nigeria
Nigeria presents an underpenetrated market with significant growth potential, fueled by the rapid expansion of mobile money and digital banking. The Central Bank of Nigeria (CBN) actively promotes financial inclusion through various digital payment initiatives. Lagos, as a major commercial hub, leads in the deployment of affordable mobile card readers.
Mobile Card Reader Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the mobile card reader ecosystem. The market exhibits a tiered structure, with established payment processors and fintech innovators competing for merchant mindshare. Strategic archetypes include integrated hardware-software providers, low-cost hardware specialists, and payment network extenders. Dominant competitive moves involve both strategic partnerships to expand reach and continuous portfolio diversification into value-added services.
Specialists in integrated ecosystems like Square and PayPal exemplify the trend towards bundling payment hardware with comprehensive software solutions. These US-based companies target micro-merchants and small businesses with seamless onboarding and transparent pricing. SumUp, a European-based provider, occupies a distinct position by focusing on low-cost, simple devices tailored for small businesses, particularly in European and Latin American markets.
| Leading Market Players |
|---|
| PayPal |
| Worldpay |
| Square |
| Checkout.com |
| Global Payments |
| Stripe |
| Fiserv |
| SumUp |
| Adyen NV |
| Others |
Cost & Logistics Intelligence
Upstream component manufacturing in Asia, particularly China for electronic components and assembly, dictates hardware cost structures. This concentration influences the margin distribution across the value chain, favoring software-centric platform integrators downstream.
Pricing Analysis
Configured-to-order pricing for integrated mobile card reader solutions contrasts with standard, off-the-shelf hardware unit pricing. The dominant pricing model combines per-unit hardware sales with SaaS-tiered subscriptions for value-added software services. Price differentiation stems from PCI DSS certification levels and advanced biometric security integration. Hardware commoditization, particularly from Asian manufacturers, drives pricing softness across basic device tiers. Micro-merchants and gig economy workers exhibit the highest price sensitivity, while established retailers prioritize feature sets and system integration.
Supply Chain Analysis
Geopolitical tensions affecting electronics trade between major manufacturing hubs and consumer markets pose a significant supply chain risk. The supply chain for mobile card readers predominantly sources from China and Vietnam for assembly and component fabrication. Manufacturing relies heavily on semiconductor chips and secure element modules. Single-source vulnerability for specialized EMVCo-certified components creates fragility. Downstream distribution primarily occurs through online retailers and direct sales channels from payment processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
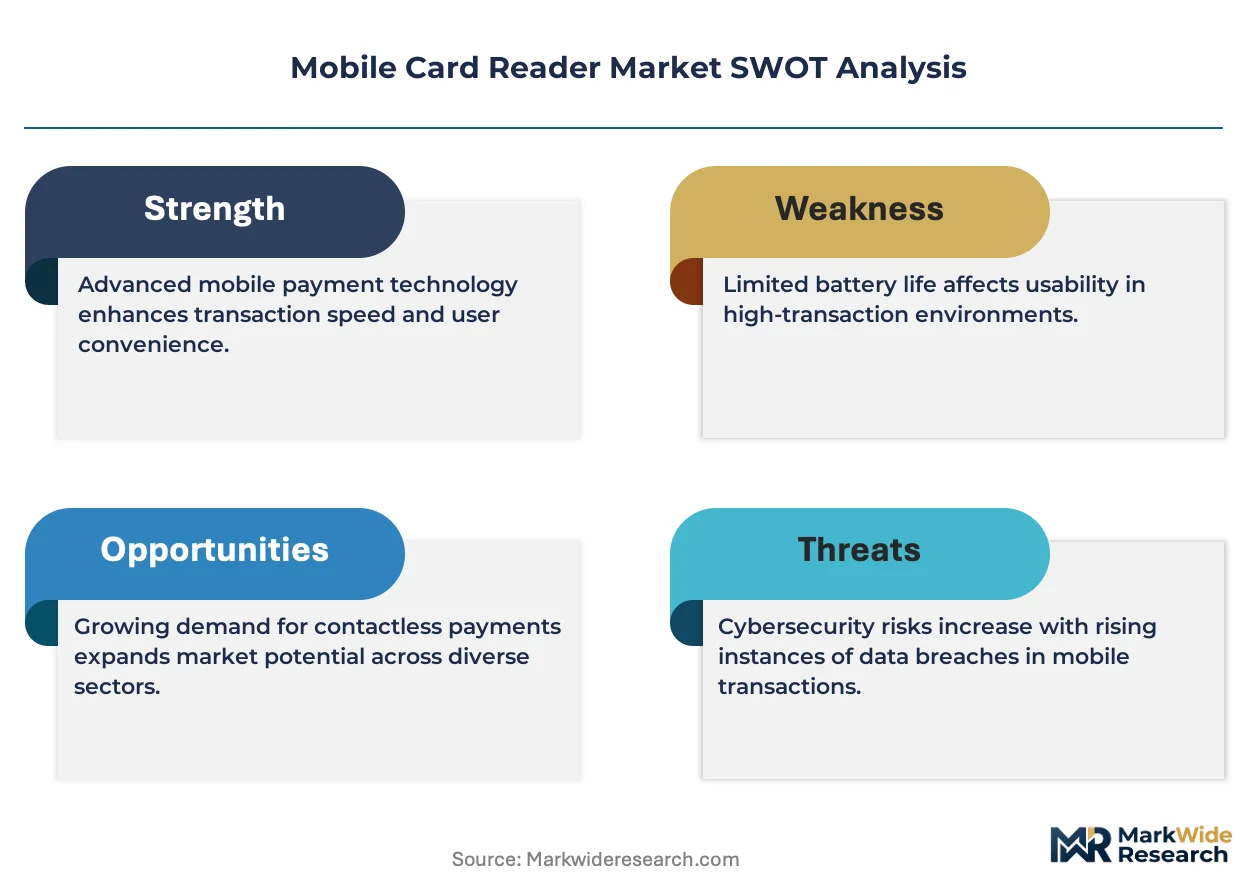
The mobile card reader market is at a platform-economics inflection point, driven by the shift towards integrated hardware-software ecosystems. This transformation focuses on seamless interoperability with broader POS and business management systems.
For Market Incumbents: Harden existing merchant relationships through deeper integration of value-added software services, such as inventory management and customer analytics. Invest significantly in ongoing PCI DSS and EMVCo certification to maintain a high barrier against less compliant hardware. This strategy mitigates the threat from low-cost QR code payment alternatives and hardware commoditization. Leverage R&D into biometric security to differentiate premium offerings.
For New Entrants and Emerging Players: Build out distribution networks in underpenetrated African markets like Nigeria and Kenya, focusing on affordable, robust devices. Target the expanding gig economy and market stall owners with simple, low-cost solutions that offer quick onboarding. A direct-to-merchant online sales model, combined with localized customer support, represents an effective go-to-market angle. Focus on basic payment acceptance initially, with future software upgrade paths.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated hardware-software providers demonstrating strong recurring SaaS revenue streams and robust compliance infrastructure. The market's long-term viability, spanning the next decade, hinges on the ability to bundle payment acceptance with comprehensive business management tools. Target acquisition archetypes include fintech innovators specializing in secure firmware deployment and seamless POS integration. A key signal to watch is the expansion of value-added service adoption beyond core payment processing.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Integrated Software Ecosystems | Enhances merchant stickiness and creates new recurring revenue streams beyond transactional fees. |
| Invest in Biometric Security R&D | Establishes a premium product tier and strengthens transaction security, building consumer trust. |
| Localize for Emerging Markets | Captures underpenetrated micro-merchant segments in high-growth regions with tailored solutions. |
| Secure Firmware Update Protocols | Mitigates security vulnerabilities and ensures device compliance across a diverse installed base. |
| Pursue EMVCo/PCI DSS Certifications | Maintains market access by meeting mandatory global security and interoperability standards. |
Research Approach
Initial hypotheses were tested against primary input from payment processor executives, hardware engineers, small business owners, and regulatory compliance officers, then refined through iterative processes. This approach combined in-depth interviews with extensive secondary validation. Data sources included government digitalization reports, FCC and ANVISA regulatory documents, and financial filings from key market players. A rigorous bottom-up and top-down triangulation process ensured data accuracy and consistency across all market segments.
Demand-supply balance formed the core of the analytical framework, projecting market evolution over the projection horizon. The modeling integrated segmentation across product type, end user, technology, distribution channel, and regional outlook. Compound annual growth rates were derived from historical trends, competitive landscape analysis, and future growth catalysts. Key forecast inputs included evolving consumer preference for contactless payments and sustained government digitalization initiative funding.
Stress conditions across geopolitical trade policies and rapid technological obsolescence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and sustained economic growth in key emerging markets. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India Real Time Payments Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Hong Kong Payments Market
Payments
Wireless POS Terminals Market
Payments
Telecom Cloud Billing Market
Payments
Payment Orchestration Platform Market
Payments
India POS Terminals Market
Payments
US Gift Card and Incentive Card Market
Payments
Buy Now Pay Later Market
Payments
China Virtual Cards Market
Payments
B2C Payment Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
China Payments Market
Payments
Remote Deposit Capture Market
Payments
Proximity Payment Market
Payments
Medical Payment Fraud Detection Market