
 United Arab Emirates Mobile Payments Market | 2026-2036
United Arab Emirates Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Mobile Payments Market Analytics
The UAE Central Bank's open banking regulations is realigning how financial institutions and fintech platforms architect their payment rails. Emirates NBD leverages its established retail banking footprint to anchor merchant acquisition networks across the Emirates. NymCard competes as a banking-as-a-service provider enabling white-label card and wallet issuance for non-bank brands. Tabby specializes in buy-now-pay-later integration at checkout, extending consumer purchasing flexibility within merchant ecosystems.
Mobile payments encompass digital fund transfers executed through smartphone applications using near-field communication, tokenized credentials, and encrypted host card emulation to complete commercial transactions without physical card presentment. NFC technology dominates in-store proximity payments due to sub-second transaction latency and embedded hardware security elements across Android and iOS devices. Cloud-based processing architectures are displacing on-device storage for credential management, while QR code payments capture small merchant segments where terminal deployment costs prove prohibitive.
MOHAP and the UAE Central Bank jointly supervise financial technology licensing, anti-money laundering protocols, and consumer data protection standards that govern mobile payment provider operations. SAMA-aligned instant payment specifications and the domestic Aani real-time platform shape interoperability mandates and settlement velocity requirements for licensed operators. Stakeholders must monitor evolving central bank digital currency pilots and open API standardization to anticipate infrastructure investment priorities and partnership model disruptions.
Market Dynamics
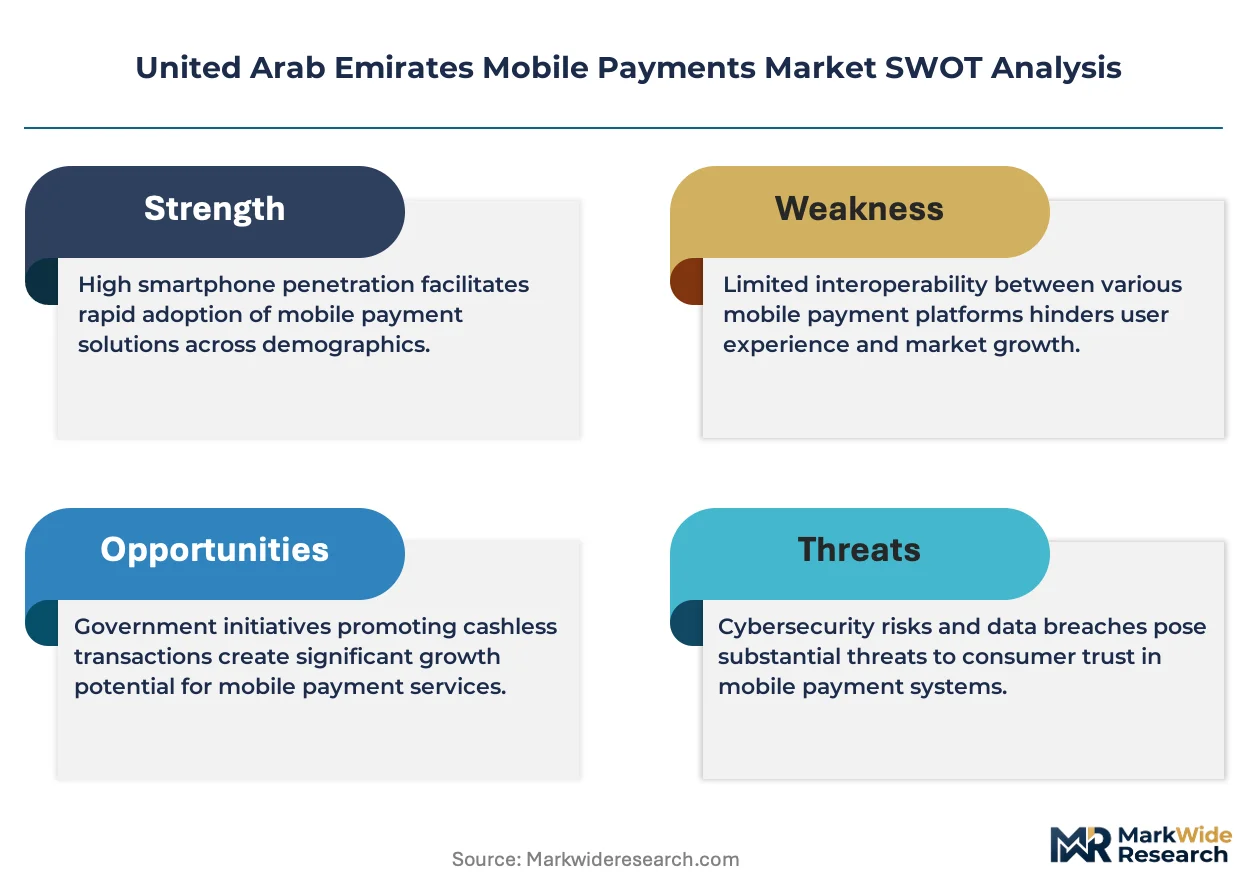
The UAE Central Bank's open banking framework is compressing settlement timelines and forcing interoperability between legacy bank rails and fintech platforms. This regulatory architecture is reshaping how payment providers build merchant networks and consumer acquisition channels across the Emirates.
Growth Catalysts
- Aani Instant Payment Platform:The UAE's real-time settlement infrastructure reduces transaction friction for peer-to-peer transfers and merchant payouts. Licensed operators gain competitive velocity through sub-second clearing.
- Contactless Terminal Deployment:Small merchants across Dubai's retail corridors are installing NFC-enabled point-of-sale hardware. Hardware cost curves and bank subsidy programs accelerate physical infrastructure rollout.
- Digital Native Cohort Expansion:Expatriate professionals and younger Emirati consumers demonstrate minimal cash dependency. Demographic composition favors wallet-first payment behavior in high-frequency retail categories.
Market Restraints
- Banking License Concentration:The UAE Central Bank maintains strict licensing thresholds for payment service providers. Capital requirements and compliance overhead limit new entrant formation.
- Merchant Acquisition Cost Inflation:Competing platforms drive up customer acquisition spending for small business onboarding. Unit economics compress as multiple providers target identical merchant segments.
- Interoperability Fragmentation:Proprietary wallet ecosystems resist seamless fund portability. Consumer friction persists when transferring between non-affiliated payment applications.
Strategic Opportunities
- Abu Dhabi SME Corridor Penetration:Merchant payment digitization lags Dubai's saturation levels. Targeted acquisition programs capture underpenetrated commercial zones in the capital emirate.
- Embedded Finance Convergence:Buy-now-pay-later functionality integrates with ride-hailing and food delivery super-apps. Technology convergence creates sticky consumer financial relationships within vertical ecosystems.
- Central Bank Digital Currency Pilots:The UAE Central Bank's experimental wholesale CBDC programs signal future settlement infrastructure. Early platform alignment with digital dirham specifications positions operators for protocol adoption.
Industry Challenges
- Certification Timeline Compression:MOHAP and Central Bank joint licensing procedures extend operational readiness periods. Anti-money laundering protocol verification creates bottlenecks for product launch schedules.
- Legacy Core Banking Integration:Established financial institutions maintain outdated transaction processing architectures. API standardization gaps force costly middleware development for fintech partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Mobile Payments Market |
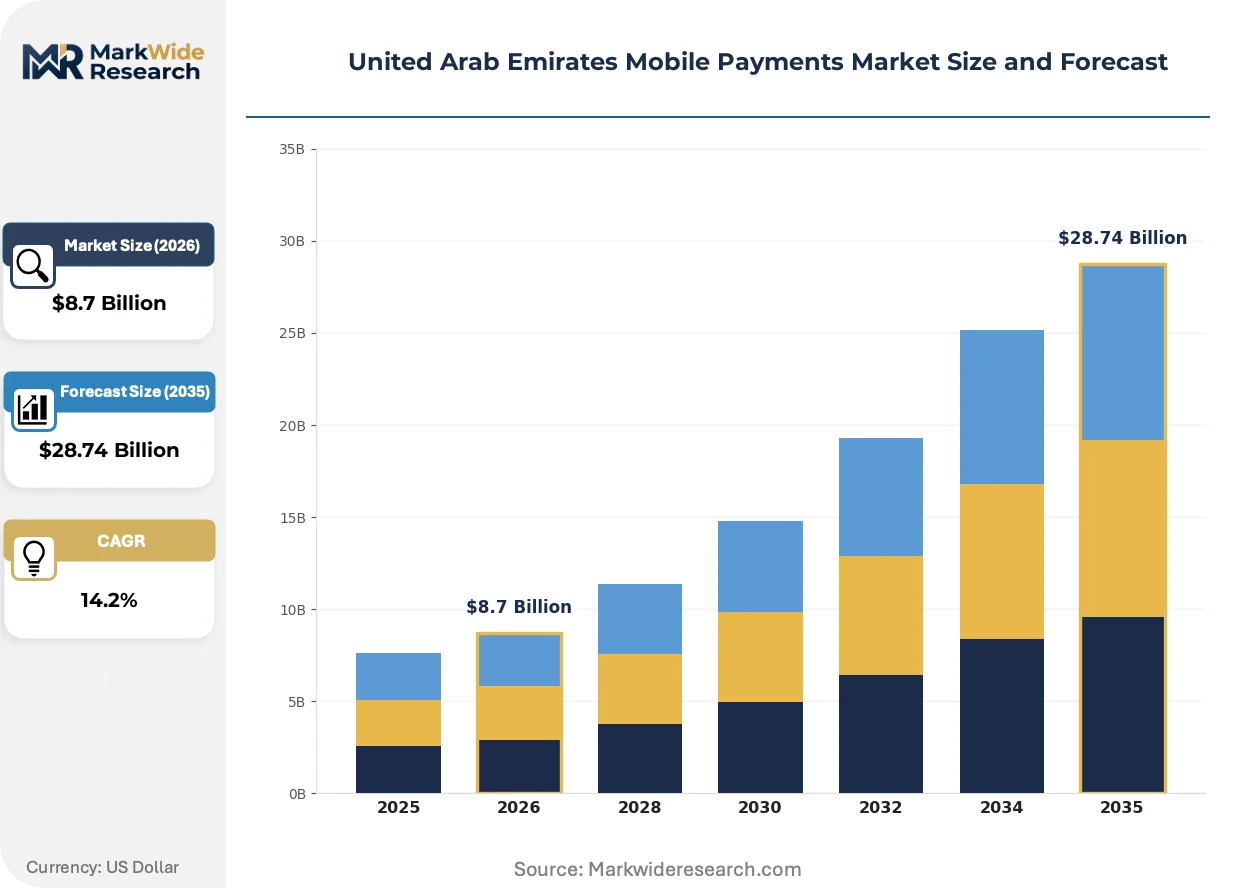
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Contactless Payments, Mobile Wallets, QR Code Payments, Peer-to-Peer Transfers Consumer Segment: Millennials, Gen Z, Small Businesses, Large Enterprises Technology: NFC, Bluetooth, Cloud-Based, Blockchain Usage Scenario: Retail Transactions, Online Purchases, Bill Payments, In-App Payments |
| Companies Covered | Apple Pay, Samsung Pay, Emirates NBD, NymCard, Tabby, e& (Etisalat), Google Pay, NOW Money, First Abu Dhabi Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Mobile Payments Market Evolving Landscape
Cloud-based credential management architectures are displacing on-device secure element storage across UAE payment platforms. This infrastructure shift enables faster feature deployment while introducing new vendor dependency structures.
Host card emulation technology is electrifying in-store proximity payment execution. Retail merchants across Dubai Mall and Mall of the Emirates deploy sub-second NFC transaction processing. Android and iOS hardware security modules enable tokenized credential rotation without physical card presentment. Settlement compression and queue abandonment reduction follow from latency elimination.
MOHAP's financial technology licensing protocols align with SAMA instant payment specifications. The regulatory convergence creates cross-border interoperability standards for Gulf Cooperation Council payment corridors. Licensed UAE operators gain operational passporting advantages into Saudi and Bahraini markets. Compliance architecture investments yield multi-jurisdiction operational leverage.
Consumer purchasing flexibility expectations are reshaping checkout integration priorities. Buy-now-pay-later functionality displaces traditional credit card installment options at e-commerce and physical retail touchpoints. Fashion and electronics verticals demonstrate highest attachment rates for deferred payment instruments. Merchant platforms compete on financing option breadth rather than transaction fee minimization alone.
United Arab Emirates Mobile Payments Market Segmentation
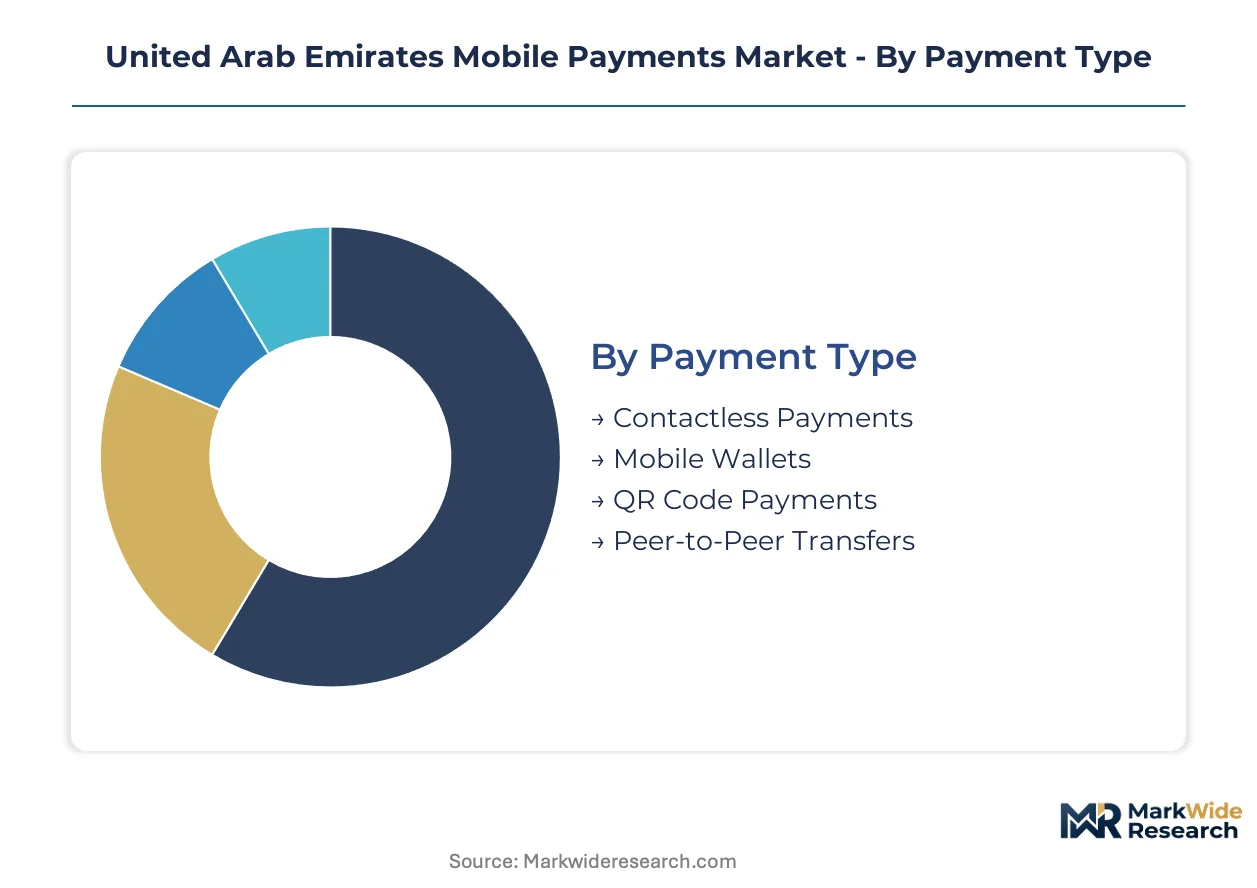
Payment type distinctions determine infrastructure investment priorities for UAE operators. Consumer segment stratification reveals divergent acquisition cost structures and lifetime value profiles. Technology choices impose specific certification timelines and vendor dependency patterns.
Payment Type:
Volume concentrates in proximity-enabled transactions while premium service margins attach to deferred payment instruments.
- Contactless Payments:NFC-enabled tap-to-pay functionality dominates high-frequency retail corridors across Dubai Mall and Mall of the Emirates. Merchant subsidy programs from Emirates NBD and competing acquirers accelerate terminal deployment in food service and convenience retail.
- Mobile Wallets:Tokenized credential storage within native applications enables closed-loop fund management and loyalty program integration. Expatriate professionals in Abu Dhabi's financial district demonstrate highest daily active usage intensity.
- QR Code Payments:Low-cost merchant onboarding suits small traders in Deira's traditional souks where hardware deployment proves uneconomical.
- Peer-to-Peer Transfers:Real-time settlement via the Aani platform displaces cash-based remittance corridors for South Asian labor populations.
Mature deployment sits with contactless infrastructure. Newer deployment is concentrated in QR code merchant acquisition.
Consumer Segment:
Demographic composition shapes feature prioritization and interface design requirements.
- Millennials:Digitally fluent professionals aged 28-43 drive subscription billing and recurring payment automation. Salary-credited wallet usage concentrates in retail and food delivery verticals.
- Gen Z:Native mobile-first behavior extends to social commerce and gaming microtransactions. Buy-now-pay-later attachment rates peak within fashion and electronics purchase occasions.
- Small Businesses:Merchant acquisition targets prioritize integrated accounting and inventory management functionality alongside payment acceptance.
- Large Enterprises:Treasury management and bulk disbursement capabilities dominate procurement specifications.
Revenue concentration aligns with millennial transaction frequency. Steepest expansion trajectory attaches to Gen Z cohort penetration.
Technology:
Hardware dependency versus cloud-native architectures creates divergent capital intensity profiles.
- NFC:Sub-second transaction latency and embedded secure element authentication anchor in-store proximity payment dominance. Android and iOS hardware security modules enable tokenized credential rotation without physical card presentment.
- Bluetooth:Low-energy beacon protocols enable proximity-aware checkout experiences in experiential retail environments.
- Cloud-Based:Credential management displacement from on-device storage enables faster feature deployment cycles and reduces manufacturer dependency.
- Blockchain:Experimental settlement layer pilots target cross-border remittance cost compression for South Asian corridor flows.
Operational maturity clusters around NFC infrastructure. Experimental deployment concentrates in blockchain settlement pilots.
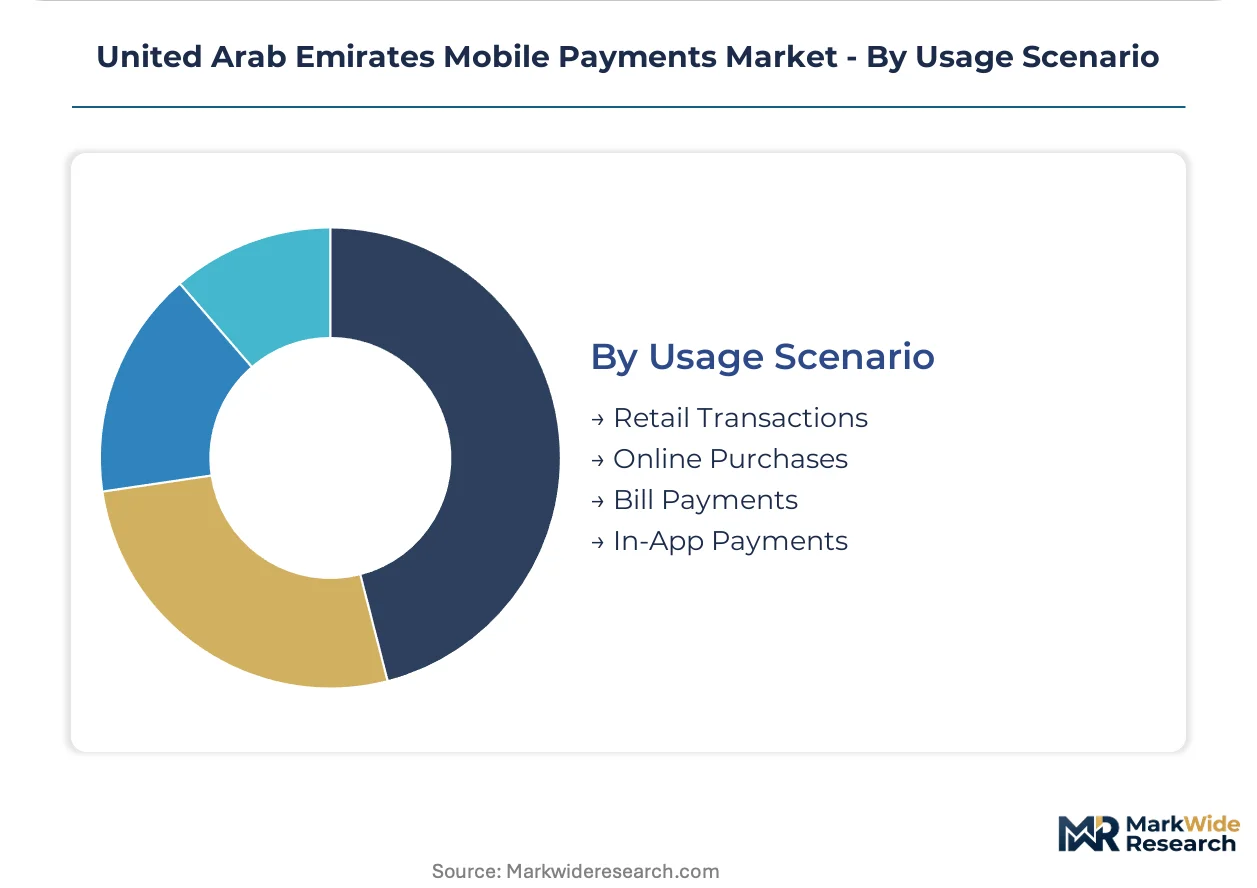
Usage Scenario:
Transaction context determines authentication rigor and value-added service attachment potential.
- Retail Transactions:Physical point-of-sale acceptance spans NFC tap, QR scan, and biometric verification modalities. Dubai's luxury retail segment drives highest average transaction values.
- Online Purchases:E-commerce checkout integration demands seamless redirection and tokenized credential storage. Fashion and electronics verticals demonstrate highest buy-now-pay-later attachment.
- Bill Payments:Utility and telecommunications settlement automation favors scheduled recurring transfers over manual initiation.
- In-App Payments:Super-app ecosystems embed financial services within ride-hailing and food delivery workflows.
Established penetration sits with retail transaction acceptance. Emerging concentration clusters in super-app embedded finance convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's financial district anchors UAE mobile payment infrastructure deployment. The emirate's merchant density and expatriate professional concentration create concentrated transaction velocity. Abu Dhabi follows with institutional banking corridors and government digitization mandates.
Dubai
Retail merchant networks and hospitality verticals drive contactless terminal saturation across Dubai Mall and Mall of the Emirates corridors. The Dubai Department of Economic Development mandates electronic payment acceptance for commercial licensing renewal. Fintech clusters concentrate in Dubai International Financial Centre where banking-as-a-service providers enable white-label wallet issuance for non-bank brands.
Abu Dhabi
Government disbursement digitization and sovereign wealth fund portfolio companies accelerate B2B payment platform adoption. The Abu Dhabi Global Market financial free zone issues specialized fintech licenses with streamlined regulatory pathways. Yas Island's entertainment and retail precincts deploy integrated loyalty-wallet systems for tourist-facing merchants.
Sharjah
Manufacturing SME corridors and industrial free zones create merchant acquisition opportunities for QR-code payment solutions. The Sharjah Economic Development Department promotes cashless transition programs for traditional trading families. Industrial zones in Hamriyah and Sharjah Airport International Free Zone concentrate payroll digitization demand among South Asian labor populations.
Northern Emirates
Ras Al Khaimah's tourism development and Fujairah's port logistics generate specialized payment acceptance requirements. Federal inclusion mandates from the UAE Central Bank extend instant payment infrastructure to underserved emirates. Ajman's retail souks and residential communities present merchant education challenges for contactless hardware deployment.
United Arab Emirates Mobile Payments Market Competitive Landscape
The competitive structure tilts toward bank-affiliated platform dominance with fintech specialization at the edges. Established retail banks leverage merchant acquisition networks and regulatory licensing advantages. Three archetypes populate the field: legacy banking institutions with payment subsidiaries, banking-as-a-service infrastructure providers, and vertical-focused checkout integrators. Consolidation pressure manifests through strategic partnerships between banks and technology platforms rather than outright acquisition activity.
Among the bank-affiliated tier, Emirates NBD and First Abu Dhabi Bank anchor merchant network scale with established retail footprints. NymCard occupies a position within the banking-as-a-service archetype, enabling non-bank brands to issue tokenized payment credentials. Tabby exemplifies the vertical specialization approach, embedding deferred payment functionality directly within merchant checkout flows.
| Leading Market Players |
|---|
| Apple Pay |
| Samsung Pay |
| Emirates NBD |
| NymCard |
| Tabby |
| e& (Etisalat) |
| Google Pay |
| NOW Money |
| First Abu Dhabi Bank |
| Others |
Value Network & Pricing Analysis
Merchant acquisition hardware subsidies from Emirates NBD and First Abu Dhabi Bank cascade through three-tier pricing structures across premium, standard, and economy service levels. Cloud-based credential management infrastructure compresses platform operating costs while NFC terminal deployment subsidies reshape merchant onboarding economics across Dubai and Abu Dhabi retail corridors.
Pricing Analysis
Transaction throughput volume anchors pricing tiers for UAE mobile payment operators. Premium pricing attaches to buy-now-pay-later functionality and embedded loyalty program integration, while standard tiers cover basic contactless acceptance. Price differentiation stems from merchant size segmentation and value-added service bundling. Cost compression in QR-code merchant acquisition is intensifying because competing platforms target identical small trader segments in Deira's traditional souks. Small businesses demonstrate highest price sensitivity; luxury retail merchants in Dubai Mall corridors exhibit lowest.
Supply Chain Analysis
MOHAP financial technology licensing and UAE Central Bank compliance certification gate operational readiness for payment service providers. Hardware supply concentrates in China, Taiwan, and South Korea for NFC-enabled terminal manufacturing. Cloud infrastructure draws from hyperscaler data centers in Singapore, Ireland, and the United Arab Emirates. Single-source vulnerability sits with secure element chip fabrication for tokenized credential storage. Distribution runs through banking-as-a-service platform partnerships and direct merchant acquisition teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE mobile payments sector sits in a technology-transition phase as cloud-based credential management displaces on-device secure element storage. Host card emulation and tokenized credential rotation are replacing legacy physical card presentment architectures.
For Market Incumbents: Anchor merchant network scale through accelerated NFC terminal deployment subsidies in Abu Dhabi's underpenetrated SME corridors. Deepen API standardization investments to reduce middleware development costs from legacy core banking integration friction. Threat from banking-as-a-service providers like NymCard demands defensive certification alignment with SAMA instant payment specifications. For New Entrants and Emerging Players: Begin with Sharjah's manufacturing SME corridors and industrial free zones where QR-code payment solutions address hardware deployment cost barriers. Target payroll digitization demand among South Asian labor populations in Hamriyah and Sharjah Airport International Free Zone. Go-to-market angle: integrated accounting and inventory management functionality alongside payment acceptance. For Investors and Strategic Acquirers: UAE Central Bank digital dirham pilot announcements are the leading indicator that settlement infrastructure investments will yield multi-jurisdiction operational leverage. Long-term viability favors platforms with early alignment to open API standardization and cross-border interoperability protocols. Acquisition target archetype: vertical-focused checkout integrators with proven buy-now-pay-later attachment rates. Signal to watch: CBDC protocol adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Migration | Displaces on-device storage and enables faster feature deployment cycles for UAE operators. |
| Merchant Acquisition Partnership | Banking-as-a-service platforms like NymCard expand white-label wallet issuance reach. |
| Regulatory Certification Investment | MOHAP and Central Bank licensing alignment opens Saudi and Bahraini market passporting. |
| Embedded Finance Integration | Buy-now-pay-later functionality from Tabby creates sticky consumer relationships within super-apps. |
| Cross-Border Interoperability | SAMA-aligned instant payment specifications enable Gulf Cooperation Council corridor expansion. |
Research Methodology
Central Bank regulatory filings, UAE banking sector disclosures, and fintech licensing databases formed the secondary backbone of this analysis. Primary interviews with payment platform executives, merchant acquisition leads, and cloud infrastructure specialists triangulated against Emirates NBD annual reports and Aani platform specifications. Bottom-up transaction volume modeling and top-down macroeconomic trend analysis validated segmentation outputs.
Historical trendline analysis across the projection horizon informed CAGR derivation through regression-based trajectory fitting. Segmentation dimensions modeled include payment type, consumer demographic cohort, technology architecture, and usage scenario. Forecast inputs incorporated Aani real-time settlement velocity metrics and contactless terminal deployment curves from Dubai Department of Economic Development mandates.
Underlying measurement precision varies by segment; contactless payment volumes carry tighter precision than experimental blockchain settlement pilots. Forecasts reflect assumptions regarding regulatory timeline compression and merchant education program effectiveness. A model refresh is warranted upon material change in CBDC pilot specifications or open banking framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Medical Payment Fraud Detection Market
Payments
Epayment System Market
Payments
Finland Payments Market
Payments
Vietnam Payments Market
Payments
Mobile Money Market
Payments
Europe Payment Gateways Market
Payments
United States Mobile Payment Market
Payments
Norway Mobile Payments Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Southeast Asia POS Terminal Market
Payments
Mexico POS Terminals Market
Payments
Crypto Payment Gateway Market
Payments
Global Payment Gateways Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
United States Electronic Toll Collection Market
Payments
GCC Mobile Payment Market