
 Contactless Payment Market | 2026-2036
Contactless Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless Payment Market Intelligence
PCI DSS Level 1 certification is bifurcating the vendor landscape into compliant infrastructure providers and second-tier operators locked out of enterprise accounts. Square leverages its integrated hardware-software stack to dominate small-business terminals in North America. Adyen sustains a single-platform architecture that processes card-present and card-not-present flows across unified APIs. Stripe differentiates through developer-first tooling that accelerates embedded finance deployments for platforms.
Contactless payment denotes transaction settlement initiated through proximity communication between a consumer device and a merchant terminal, typically operating at 13.56 MHz with transaction completion under 500 milliseconds for transit-grade speed requirements. The technology serves commercial purpose by eliminating authentication friction, reducing queue abandonment, and lowering cash-handling costs for high-frequency, low-value purchases. NFC-enabled smartphones and payment terminals capture the dominant value share, as merchant terminal refresh cycles and consumer handset penetration align. QR code deployments represent the fastest-expanding segment in emerging markets where smartphone density outpaces dedicated terminal infrastructure. Cloud-based deployment models concentrate margin pools through recurring SaaS revenues and reduced on-site maintenance overhead.
FDA oversight does not apply to this sector; instead, PCI DSS governs data security, EMVCo sets chip specification standards, and GDPR in Europe constrains transaction data retention and cross-border processing protocols. EMVCo certification requirements compel terminal manufacturers to upgrade firmware and hardware designs, while GDPR limits the granularity of purchase analytics available to merchants and payment networks. Stakeholders must monitor central bank digital currency pilots and real-time payment network interoperability mandates that could reroute transaction volumes away from traditional card rails.
Market Dynamics
Transit-grade tap-to-ride infrastructure is compressing transaction latency requirements below 500 milliseconds, forcing terminal manufacturers and payment networks to re-architect authentication flows around speed rather than layered security alone.
Growth Catalysts
- UPI QR penetration:India's real-time payment rails enable smartphone-based contactless acceptance without dedicated terminal hardware, accelerating merchant onboarding in tier-2 and tier-3 cities.
- EMVCo certification mandates:Upgraded chip specification standards compel issuing banks and acquirers to refresh terminal fleets, creating replacement demand across mature payment corridors.
- Transit authority modernization:Metropolitan transport networks in London, São Paulo, and Singapore are deploying open-loop contactless acceptance, embedding payment credentials into daily commute patterns.
Market Restraints
- Semiconductor supply concentration:NFC controller and secure element fabrication concentrates among Taiwanese and South Korean foundries, exposing terminal production to geopolitical disruption.
- PCI DSS compliance costs:Level 1 certification requirements impose six-figure audit expenditures and 12-18 month implementation timelines, excluding smaller terminal vendors from enterprise procurement pools.
- Biometric authentication substitution:Facial recognition and palm-vein payment systems in Chinese retail environments threaten to bypass card-present infrastructure entirely.
Strategic Opportunities
- Central bank digital currency integration:Pilot programs by the European Central Bank and Bank of England create white space for wallet providers to bridge CBDC rails with existing contactless terminals.
- SoftPOS expansion:NFC-enabled smartphones functioning as acceptance devices unlock merchant categories previously excluded by dedicated terminal economics, particularly in mobile retail and gig-economy services.
- GDPR-compliant analytics:Privacy-preserving transaction data architectures that satisfy European data retention constraints enable differentiated merchant services without regulatory exposure.
Industry Challenges
- EMVCo certification backlog:Terminal manufacturers face 8-14 month queue times for firmware and hardware validation, compressing product launch windows against competitor cycles.
- Legacy core banking integration:Issuers maintaining 1980s-era mainframe architectures encounter API friction when connecting real-time contactless authorization to batch-oriented settlement systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless Payment Market |
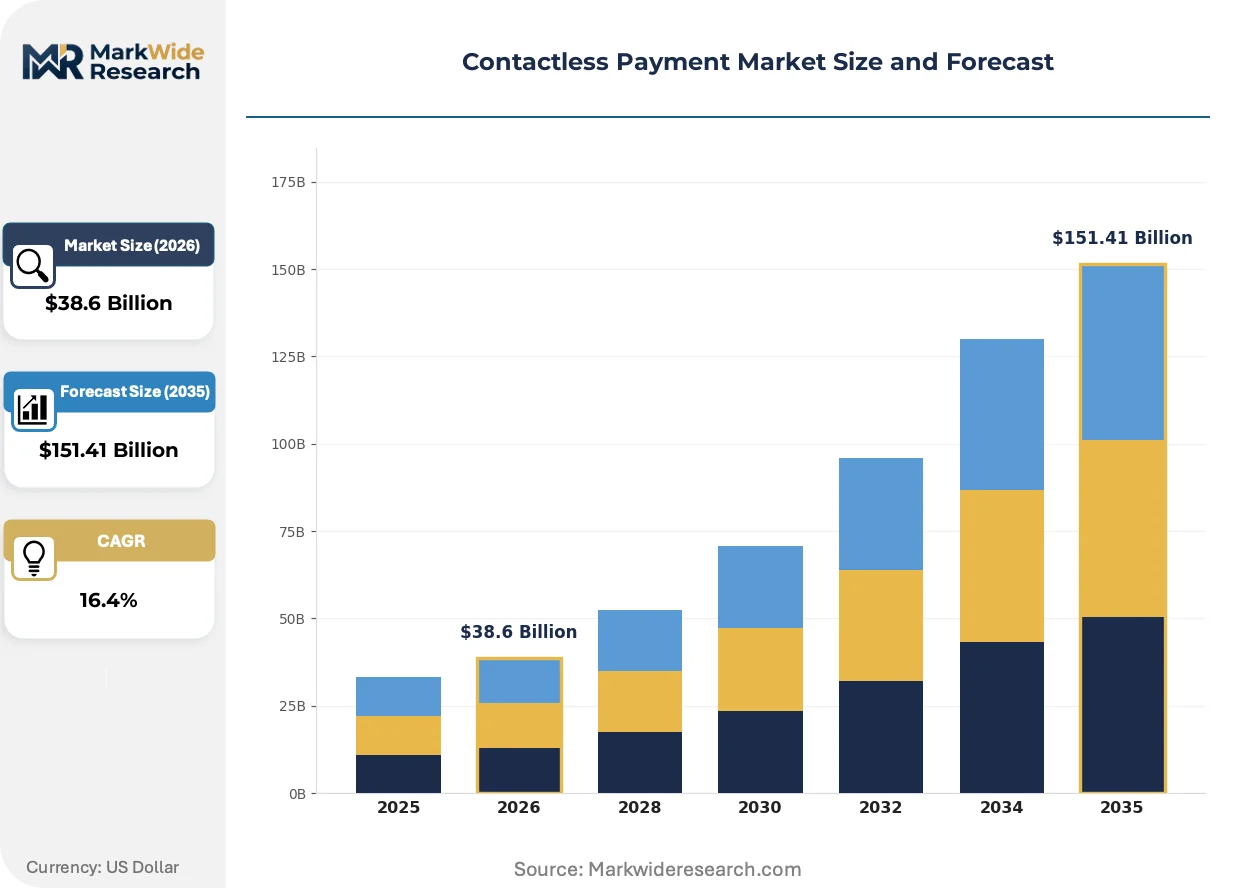
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $151.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: NFC, RFID, QR Code, Magnetic Stripe End User: Retail, Hospitality, Transportation, Healthcare Product Type: Smartphones, Wearables, Payment Terminals, Cards Deployment: Cloud-based, On-premises, Hybrid, Multi-tenant |
| Companies Covered | Square, Revolut, PayPal, Grab, JPMorgan Chase, Stripe, Klarna, Teya, Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless Payment Market Strategic Shifts & Innovations
Payment authentication is migrating from static credentials to dynamic cryptograms and biometric binds, compressing the attack surface while raising the engineering bar for terminal and wallet providers.
Biometric card technology is fragmenting the contactless hardware landscape. Fingerprint-sensor cards from Swedish and Swiss component suppliers embed capacitive sensors directly into EMV card bodies. Tier-1 issuers in France and the United Kingdom are piloting these cards for high-value contactless transactions. The technology is fragmenting authentication liability between card networks and biometric sensor manufacturers.
GDPR Article 5 data minimization requirements are constraining transaction analytics granularity. European payment processors must now pseudonymize purchase histories and limit cross-border data flows to approved jurisdictions. Merchant loyalty programs in Germany and the Netherlands are responding by shifting to on-device data vaults that retain consumer profiles locally.
Street-level commerce in India is bypassing terminal infrastructure entirely. UPI-powered QR codes displayed on laminated printouts enable contactless settlement through any smartphone camera, displacing NFC for micro-merchants. Payment aggregators are embedding sound-based confirmation tones to signal transaction completion in noisy outdoor environments.
Contactless Payment Market Segmentation
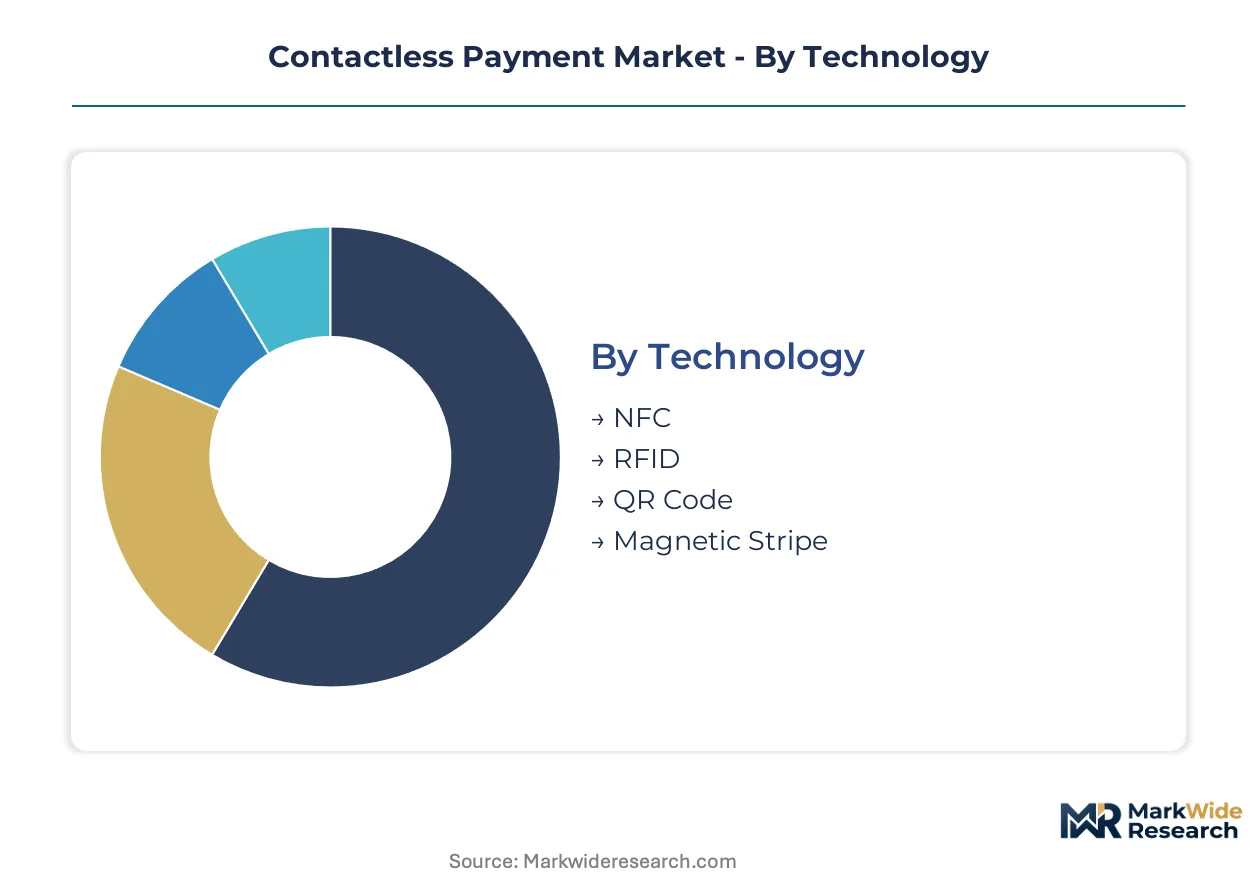
Contactless payment infrastructure fragments across four intersecting dimensions: proximity technology, merchant vertical, hardware form factor, and backend architecture. Each segmentation axis carries distinct substitution pressures from alternative payment rails and emerging authentication modalities.
Technology:
QR code deployments face the most acute substitution threat as sound-based and biometric authentication systems bypass visual scanning entirely.
- NFC:Near-field communication operates at 13.56 MHz with sub-500 millisecond transaction latency for transit-grade speed. Demand concentrates in London, São Paulo, and Singapore metropolitan transport networks where open-loop contactless acceptance embeds payment credentials into daily commute patterns.
- QR Code:Two-dimensional barcodes enable smartphone-camera initiation without dedicated terminal hardware. India's tier-2 and tier-3 cities are displacing NFC for micro-merchants through UPI-powered laminated printouts and sound-based confirmation tones.
- RFID:Radio-frequency identification supports longer-range passive tag reading for logistics and access control applications.
- Magnetic Stripe:Legacy contactless emulation through magnetic field transmission persists in backward-compatible terminal deployments.
NFC retains volume leadership; QR code holds the steepest expansion curve.
End User:
Cost tier stratification separates premium infrastructure investments from street-level merchant economics.
- Transportation:Metropolitan transit authorities mandate sub-500 millisecond authentication flows, compressing terminal engineering around speed-first architectures. São Paulo's open-loop deployment and Singapore's account-based ticketing create concentrated procurement demand for ruggedized validators.
- Retail:High-frequency, low-value purchases drive merchant terminal refresh cycles across grocery and convenience formats. PCI DSS Level 1 certification requirements bifurcate the vendor landscape into compliant infrastructure providers and second-tier operators locked out of enterprise accounts.
- Hospitality:Table-service and lodging environments prioritize integrated point-of-sale workflows over pure transaction speed.
- Healthcare:HIPAA-covered entities impose additional data security constraints on patient-facing payment interfaces.
Transportation commands the highest per-terminal investment; retail captures the broadest merchant base.
Product Type:
Application-specific form factors align with consumer device penetration curves and merchant infrastructure refresh timelines.
- Smartphones:NFC-enabled handsets function as both payment instruments and SoftPOS acceptance devices. India's UPI integration and European wallet consolidation concentrate demand in markets where smartphone density outpaces dedicated terminal deployment.
- Cards:EMV chip cards with contactless interfaces dominate mature payment corridors. Fingerprint-sensor cards from Swedish and Swiss component suppliers are fragmenting authentication liability between networks and biometric manufacturers in France and United Kingdom pilot programs.
- Wearables:Tokenized credentials embedded in watches and fitness bands serve transit and retail convenience use cases.
- Payment Terminals:Dedicated acceptance hardware faces margin compression from SoftPOS substitution and EMVCo certification backlogs extending 8-14 months.
Cards sustain transaction volume dominance; smartphones are climbing the fastest as acceptance devices.
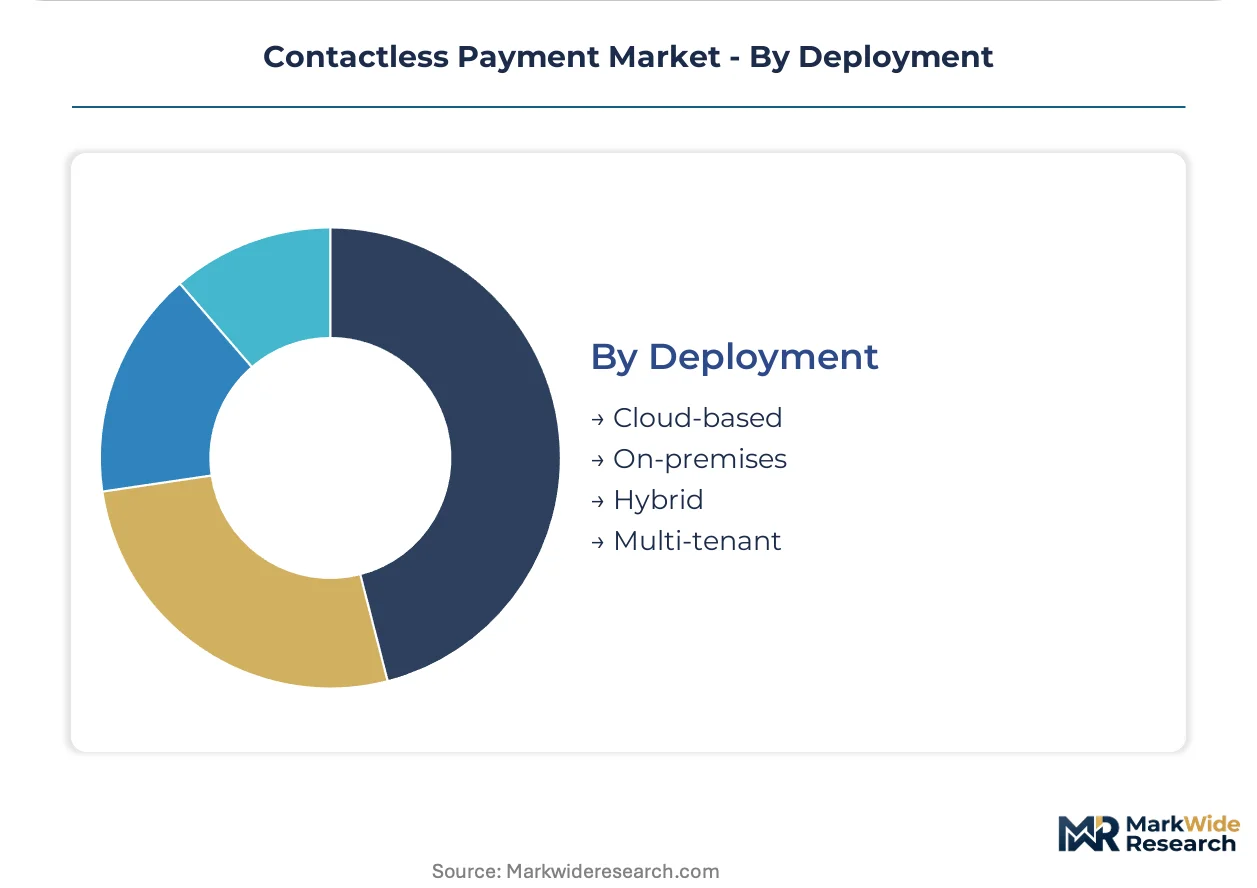
Deployment:
Margin pool concentration favors recurring SaaS architectures over capital-intensive on-site installations.
- Cloud-based:Centralized processing platforms enable real-time authorization and reduced maintenance overhead. GDPR Article 5 data minimization requirements are constraining European processors to pseudonymize purchase histories and limit cross-border flows.
- On-premises:Legacy core banking integration creates API friction for issuers maintaining batch-oriented settlement systems.
- Hybrid:Split architectures route sensitive authentication locally while pushing analytics to centralized environments.
- Multi-tenant:Shared infrastructure platforms serve payment aggregators and independent software vendors with standardized APIs.
Cloud-based deployment captures the expanding margin pool; hybrid configurations address regulatory complexity in European jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese and South Korean foundries dominate NFC controller and secure element fabrication, exposing terminal production to geopolitical disruption. India anchors demand growth through UPI-powered QR penetration. European GDPR constraints and EMVCo certification mandates reshape competitive positioning across mature payment corridors.
United States
Transit authority modernization in New York, Chicago, and San Francisco drives open-loop contactless deployment. PCI DSS Level 1 certification requirements impose six-figure audit expenditures that exclude smaller terminal vendors from enterprise procurement pools. Silicon Valley payment infrastructure providers concentrate on developer-first tooling for embedded finance platforms.
India
UPI QR codes displayed on laminated printouts enable smartphone-based contactless acceptance without dedicated terminal hardware. RBI oversight governs real-time payment rails and wallet provider licensing. Tier-2 and tier-3 cities across Maharashtra and Gujarat displace cash through sound-based confirmation tones for street-level commerce.
United Kingdom
Transport for London's account-based ticketing embeds payment credentials into daily commute patterns. GDPR Article 5 data minimization requirements constrain transaction analytics granularity and cross-border data flows. Fingerprint-sensor card pilots in London and Manchester fragment authentication liability between card networks and biometric manufacturers.
Germany
Merchant loyalty programs shift to on-device data vaults to satisfy European data retention constraints. BaFin supervision governs payment institution licensing and anti-money laundering protocols. Berlin and Hamburg payment processors pseudonymize purchase histories to enable differentiated merchant services without regulatory exposure.
Singapore
Land Transport Authority mandates sub-500 millisecond authentication flows for tap-to-ride infrastructure. Monetary Authority of Singapore pilots central bank digital currency integration with existing contactless terminals. The city-state's account-based ticketing creates concentrated procurement demand for ruggedized transit validators.
Contactless Payment Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the contactless payment ecosystem. The vendor landscape bifurcates into PCI DSS Level 1 certified infrastructure providers and second-tier operators locked out of enterprise accounts. Three archetypes dominate: integrated hardware-software stacks, single-platform architectures, and developer-first tooling specialists. Competitive moves concentrate on strategic partnerships with transit authorities and geographic expansion into tier-2 merchant categories.
Among North American payment infrastructure providers, Square and Stripe exemplify contrasting archetypes. Square anchors the integrated hardware-software tier through small-business terminal dominance. Stripe occupies the developer-first positioning that accelerates embedded finance deployments for platforms. European counterparts include Adyen, which sits within the single-platform architecture tier processing unified card-present and card-not-present flows.
| Leading Market Players |
|---|
| Square |
| Revolut |
| PayPal |
| Grab |
| JPMorgan Chase |
| Stripe |
| Klarna |
| Teya |
| Adyen |
| Others |
Cost & Logistics Intelligence
PCI DSS Level 1 certification gates both supplier qualification and price differentiation simultaneously, bifurcating terminal vendors into enterprise-accessible tiers and excluded second-tier operators while compressing margins for compliant infrastructure providers.
Pricing Analysis
PCI DSS Level 1 dictates the pricing tier structure across contactless payment infrastructure, separating certified terminal manufacturers from uncertified competitors locked out of enterprise procurement pools. Three-tier pricing stratifies across premium certified hardware, standard-compliant mid-range units, and economy-grade uncertified alternatives. Cost compression in the standard tier is intensifying because EMVCo certification backlogs extend validation timelines and raise engineering overhead. Small-business merchants exhibit highest price sensitivity, while transit authorities and tier-1 retailers prioritize certification compliance over unit economics.
Supply Chain Analysis
Inventory lead times for NFC controllers and secure elements have stretched substantially, exposing terminal manufacturers to procurement volatility and forcing buffer stock accumulation. Taiwanese and South Korean foundries anchor semiconductor fabrication for payment chips, while Chinese assembly houses dominate final terminal production. Raw material dependencies center on silicon wafers, copper interconnects, and EMV-certified plastic substrates. Single-source vulnerability concentrates in secure element manufacturing, where only two foundries qualify for financial-grade certification. Distribution runs through payment aggregators and independent software vendors with multi-tenant platform architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contactless payment infrastructure sits in early-cycle expansion, with transit-grade tap-to-ride deployments and SoftPOS smartphone acceptance creating dual penetration tailwinds across merchant categories previously excluded by dedicated terminal economics.
For Market Incumbents: Shield certification moats by accelerating EMVCo pre-certification investments ahead of competitor queue times, while deepening backward integration into secure element sourcing to offset Taiwanese foundry concentration risk. Biometric authentication substitution in Chinese retail environments and SoftPOS margin erosion threaten hardware-centric revenue streams. For New Entrants and Emerging Players: EMVCo certification fast-tracks for transit-specific validator designs unlock concentrated procurement demand from metropolitan transport authorities in São Paulo, Singapore, and London. Tier-2 Indian cities with UPI QR penetration but limited NFC terminal density represent the most penetrable white space. Developer-first tooling partnerships with payment aggregators bypass direct terminal manufacturing capital requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across SoftPOS and cloud-native processing sub-segments, shifting value capture toward software-layer margin pools. Target acquisition archetypes include biometric card component suppliers with pilot program traction in France and the United Kingdom, and privacy-preserving analytics platforms with GDPR-compliant architectures. The signal to watch is central bank digital currency pilot progression, which would reroute transaction volumes and terminal integration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| EMVCo Certification Fast-Track | Reduces 8-14 month validation queues for transit-grade terminal deployments in São Paulo and Singapore. |
| SoftPOS Platform Launch | Converts NFC-enabled smartphones into acceptance devices for gig-economy merchants without hardware investment. |
| Biometric Card Partnership | Fragments authentication liability between networks and Swedish sensor manufacturers in French pilot programs. |
| GDPR-Compliant Analytics Vault | Enables merchant loyalty differentiation through on-device data retention in German and Dutch markets. |
| CBDC Wallet Integration | Bridges European Central Bank pilot rails with existing contactless terminal infrastructure. |
Research Approach
Initial hypotheses were tested against primary input from payment network executives, terminal procurement managers at transit authorities, merchant acquiring leads, and EMVCo certification engineers, and refined through secondary validation against PCI DSS audit filings, EMVCo specification releases, RBI UPI transaction disclosures, and European payment processor annual reports. Bottom-up terminal shipment estimates triangulated against top-down payment volume projections.
Variance decomposition across the projection horizon isolates volume drivers by proximity technology, merchant vertical, hardware form factor, and backend deployment architecture. CAGRs derive from modeled adoption curves for NFC smartphone penetration, transit open-loop migration timelines, and QR code merchant onboarding rates in emerging markets. Industry-specific inputs include EMVCo certification queue data and central bank digital currency pilot progression indicators.
Decision-makers should treat outputs as directional under assumptions of sustained transit authority modernization spend and stable semiconductor supply from Taiwanese foundries; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Africa Virtual Cards Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Denmark POS Terminals Market
Payments
Face-Swiping Payment Market
Payments
Digital Payment Market
Payments
United States Payment Gateways Market
Payments
Croatia POS Terminals Market
Payments
Spain Mobile Payment Market
Payments
Malta POS Terminal Market
Payments
Australia Buy Now Pay Later Services Market
Payments
UAE Card Payments Market
Payments
South Korea Real Time Payments Market
Payments
North America POS Terminal Market
Payments
Global Prepaid Cards Market
Payments
Credit Card Payments Market
Payments
Middle East Gift Card and Incentive Card Market