
 Sweden POS Terminals Market | 2026-2036
Sweden POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden POS Terminals Market Analytics
PCI DSS Level 1 certification is reorganizing competitive access in Sweden's POS terminal sector, filtering out vendors unable to sustain annual audit cycles. Verifone Sweden AB leverages its Nordic certification pipeline to anchor enterprise deployments across Stockholm's retail chains. Worldline Group S.A competes through cloud-native terminal management that extends merchant onboarding speed. Adyen specializes in unified commerce platforms that dominate hospitality and omnichannel retail verticals.
POS terminals in Sweden comprise electronic payment acceptance devices integrating secure processors, EMV/NFC modules, and encrypted communication protocols for transaction authorization. These systems serve as the terminal node in merchant acquiring infrastructure, bridging consumer payment instruments to clearing networks. Mobile terminals and contactless terminals command expanding share as Swedish merchants prioritize line-busting flexibility and tap-to-pay speed. Fixed terminal installations retain margin concentration in high-volume grocery and big-box formats where durability and peripheral integration justify capital intensity.
Sveriges Riksbank's e-krona pilot, alongside the Swedish Financial Supervisory Authority's payment service oversight, is forcing terminal manufacturers to architect hardware-software stacks compatible with central bank digital currency rails. The EU's Payment Services Directive 2 and GDPR compliance requirements shape terminal data handling specifications and cross-border transaction transparency obligations. Stakeholders must monitor whether e-krona settlement protocols will mandate firmware-level integration or permit overlay software solutions.
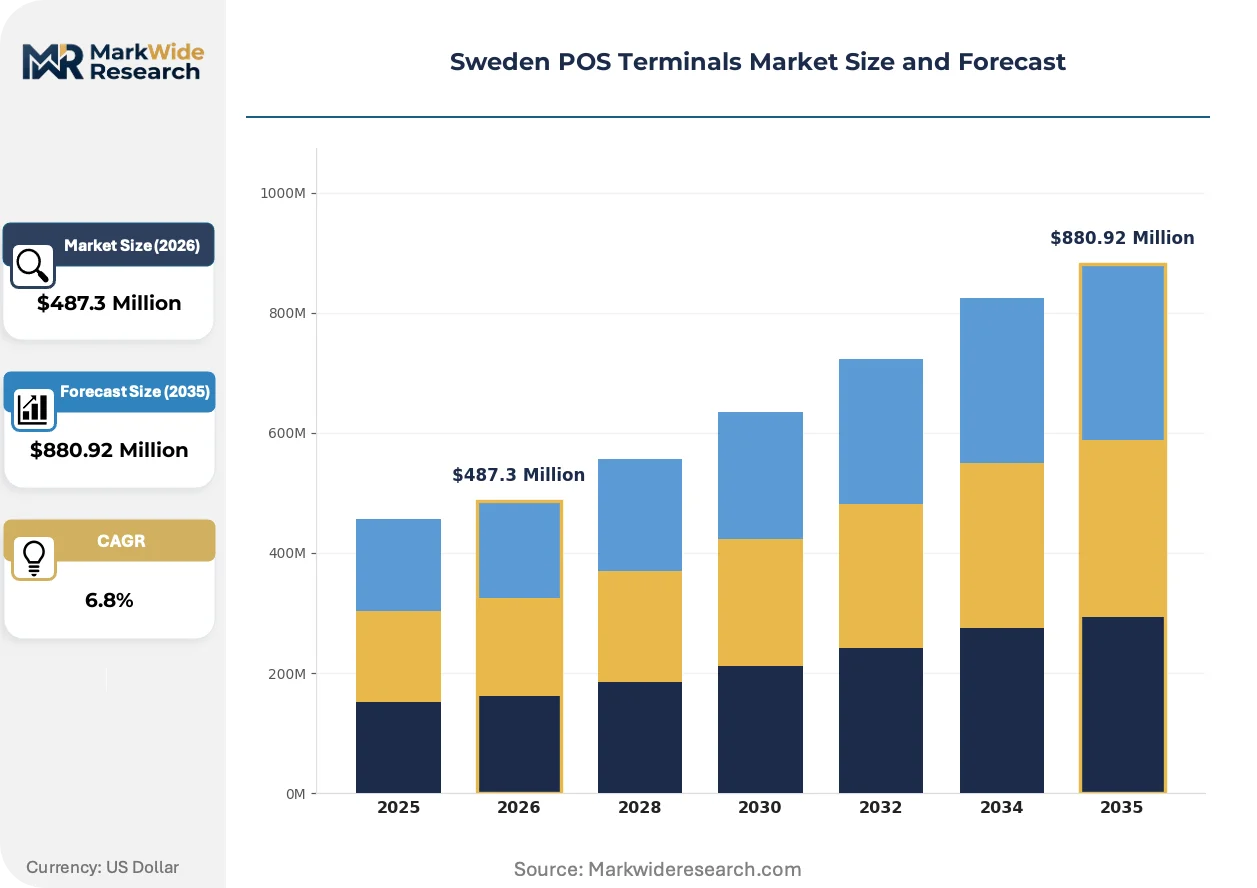
Market Dynamics
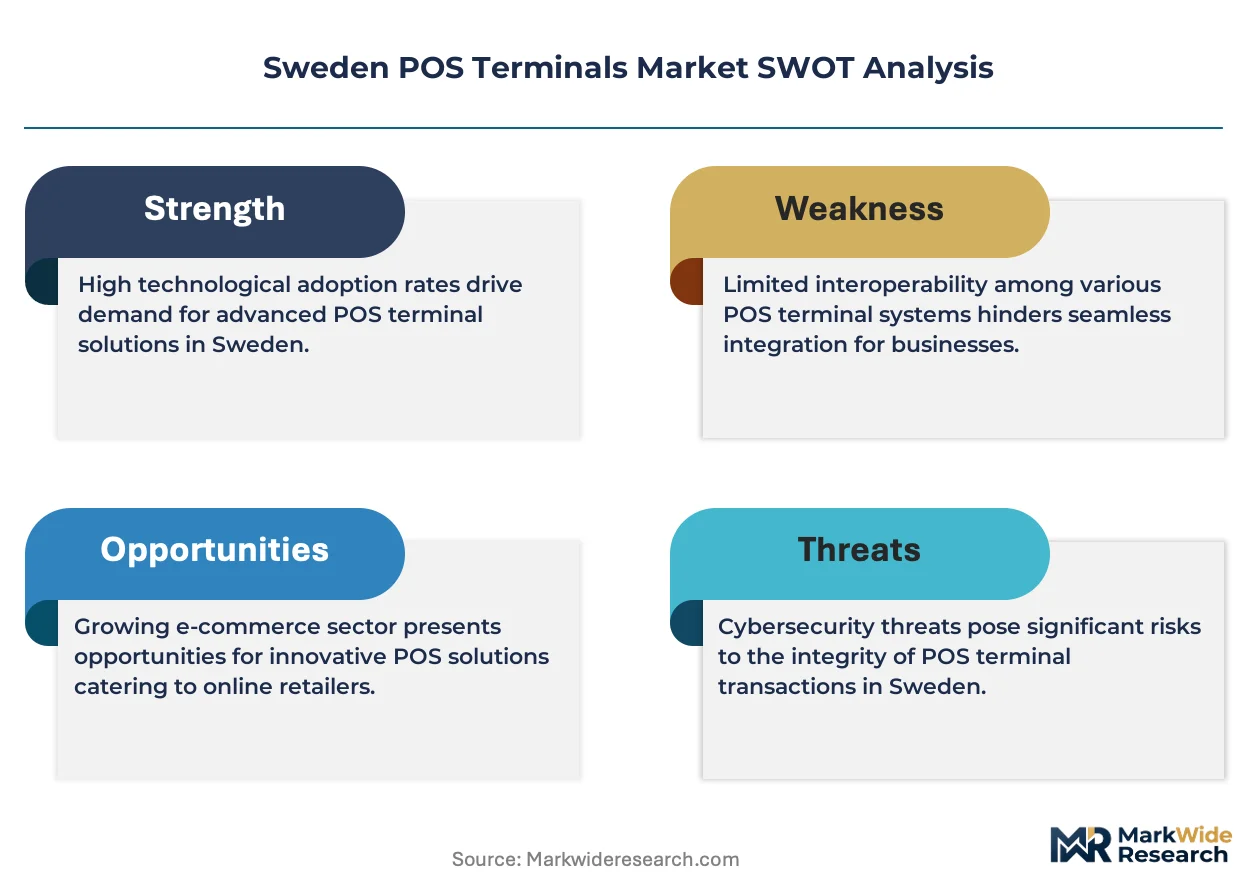
PCI DSS Level 1 certification requirements are restructuring competitive access in Sweden's POS terminal sector, filtering out vendors unable to sustain annual audit cycles while concentrating enterprise deployments among certified suppliers. Sveriges Riksbank's e-krona pilot adds a parallel hardware-software compatibility mandate that terminal manufacturers must architect into future product roadmaps.
Growth Catalysts
- Contactless infrastructure mandates:Swedish grocery chains and quick-service restaurants are expanding tap-to-pay terminal density to reduce checkout friction. EMV and NFC module integration is now standard in new merchant deployments.
- Sveriges Riksbank e-krona pilot:The central bank's digital currency initiative is forcing terminal firmware architecture toward CBDC-compatible rails. Hardware manufacturers must prepare settlement protocol integration.
- Stockholm retail corridor concentration:Enterprise merchant clusters in Sweden's capital are driving consolidated procurement of cloud-managed terminal fleets. Volume purchasing is accelerating vendor certification investments.
Market Restraints
- PCI DSS audit cost structure:Annual Level 1 certification imposes six-figure compliance burdens that exclude smaller terminal vendors from enterprise tenders. Certification concentration limits supplier diversity.
- Semiconductor supply concentration:Secure processor and EMV module sourcing depends on Asian foundry capacity. Geopolitical friction creates input volatility for Swedish terminal manufacturers.
- GDPR data handling friction:The EU's data protection framework imposes encryption and cross-border transaction transparency obligations that complicate terminal software architecture. Compliance adds development cycles.
Strategic Opportunities
- Gothenburg hospitality cluster penetration:Sweden's second-largest city shows underpenetrated terminal density in independent restaurants and hotels. Mobile and tablet-based POS solutions target this whitespace.
- Unified commerce platform convergence:Integration of in-store terminals with e-commerce payment orchestration is creating new value pools. Omnichannel merchants seek single-vendor stack consolidation.
- Swedish Financial Supervisory Authority oversight tailwind:Payment service supervision is elevating terminal security standards. Certified vendors gain preferential access to regulated merchant segments.
Industry Challenges
- Firmware development talent scarcity:Embedded security engineering and cryptographic protocol implementation skills are concentrated among few specialists. Recruitment bottlenecks delay product cycles.
- Legacy terminal replacement complexity:Merchants with depreciated hardware face integration friction when migrating to cloud-native management platforms. Data migration and peripheral compatibility extend deployment timelines.
- E-krona protocol uncertainty:Sveriges Riksbank has not finalized whether CBDC settlement will require hardware-level integration or permit software overlay solutions. Product roadmaps remain contingent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden POS Terminals Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Terminals, Mobile Terminals, Tablet Terminals, Contactless Terminals Technology: EMV, NFC, Magnetic Stripe, QR Code End User: Retail, Hospitality, Healthcare, Transportation Installation: On-premise, Cloud-based, Integrated, Standalone |
| Companies Covered | Verifone Sweden AB, Worldline Group S.A, Paypal Inc, PayEx Group, Nayax Ltd, Diebold Nixdorf, NCR Voyix, Adyen, Datecs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden POS Terminals Market Evolving Landscape
Terminal form factors and merchant acquisition models are undergoing simultaneous transformation. Three developments are compressing hardware footprints, elevating regulatory data obligations, and restructuring how Swedish merchants procure payment infrastructure.
Secure element modules are miniaturizing while maintaining cryptographic processing capacity. Swedish quick-service restaurants and food trucks are adopting pocket-sized mobile terminals at accelerating pace. Hardware compression is enabling line-busting deployment models that untether staff from fixed checkout counters.
GDPR and the EU's Payment Services Directive 2 are tightening terminal data handling specifications. Cross-border transaction transparency obligations now require encrypted storage architectures with auditable access logs. Hospitality merchants operating across Nordic borders face the steepest compliance adaptation costs.
Swedish merchant procurement is gravitating toward subscription-based terminal-as-a-service models. Capital-intensive hardware purchases are yielding to bundled processing-rate contracts with free equipment refresh cycles. Stockholm's retail chains are piloting this shift fastest, with hardware lifecycle management outsourced to acquiring partners.
Sweden POS Terminals Market Segmentation
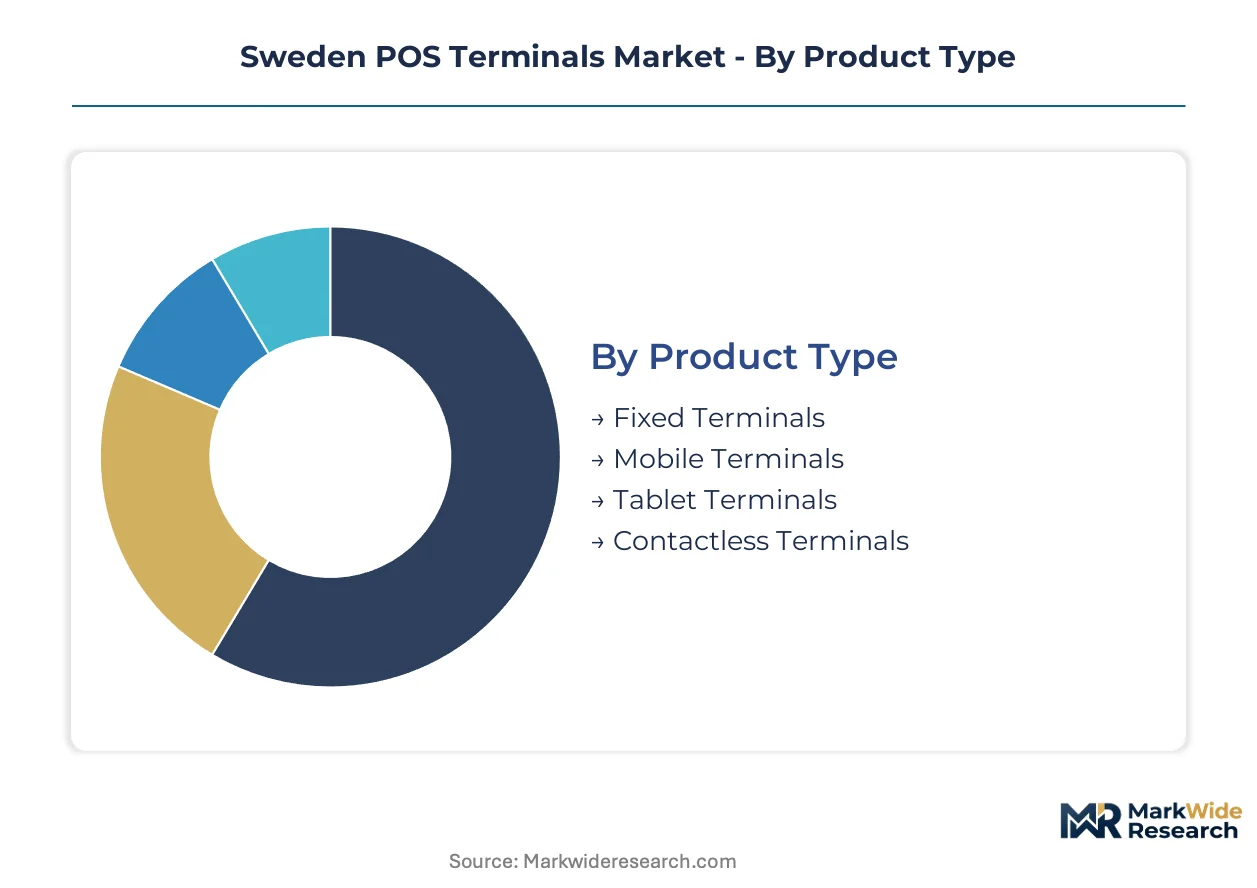
Swedish POS terminal procurement varies sharply across merchant scale and operational model. Segment boundaries determine firmware requirements, certification tiers, and hardware lifecycle economics.
Product Type:
Domestic demand concentrates in Stockholm's retail corridor and Gothenburg's hospitality cluster, with export-relevant manufacturing limited to specialized secure element production.
- Fixed Terminals:Counter-mounted devices with integrated receipt printers, barcode scanners, and cash drawer connectivity anchor high-volume grocery and big-box deployments. Stockholm's retail chains favor these for durability and peripheral integration in 24-hour operations. PCI DSS Level 1 certification requirements filter supplier access to this segment.
- Mobile Terminals:Battery-powered wireless units with Bluetooth and WiFi connectivity enable line-busting and tableside payment in restaurants. Gothenburg's independent hospitality operators are driving adoption fastest as they retrofit for contactless speed. Form factor compression is accelerating without sacrificing cryptographic processing capacity.
- Tablet Terminals:iOS and Android-based systems with detachable card readers serve micro-merchants and pop-up retail. Stockholm's seasonal market vendors and event operators favor the low capital entry point.
- Contactless Terminals:Dedicated tap-to-pay hardware with NFC antenna optimization processes transactions under 400 SEK without PIN entry. Swedish quick-service restaurants are expanding terminal density to reduce checkout friction.
Fixed terminals hold the largest share; momentum sits with mobile terminals.
Technology:
Technology selection tracks merchant risk tolerance and transaction velocity requirements, with cost tiers separating premium certified stacks from legacy acceptance modes.
- EMV:Chip card authentication with dynamic data encryption remains mandatory for card-present transactions in Sweden. Hardware certification through EMVCo ensures interoperability with Nordic acquiring networks.
- NFC:Near-field communication protocols enable tap-to-pay from cards, smartphones, and wearables. Stockholm's transit authority integration is pushing NFC into transportation verticals beyond retail.
- Magnetic Stripe:Legacy track data reading persists for international card acceptance and chargeback dispute scenarios. Declining transaction share concentrates in hospitality merchants serving non-EU visitors.
- QR Code:Camera-based payment initiation supports alternative payment schemes and account-to-account transfers. Swedish fintech wallets are piloting QR acceptance in Gothenburg's food truck clusters.
EMV dominates transaction volume; NFC is climbing the fastest.
End User:
End-user concentration shapes regional deployment patterns, with application-specific compliance requirements determining terminal specification.
- Retail:Grocery chains, fashion merchants, and electronics stores require high-throughput terminals with inventory system integration. Stockholm's retail corridor procurement concentrates enterprise-scale deployments among certified vendors.
- Hospitality:Restaurants, hotels, and cafes prioritize mobile form factors and tip-adjustment workflows. Gothenburg's independent operators show underpenetrated terminal density relative to Stockholm.
- Healthcare:Clinics and pharmacies demand HIPAA-aligned data handling with patient billing system connectivity. Swedish county healthcare procurement runs through centralized tender processes.
- Transportation:Transit operators and parking facilities need ruggedized outdoor terminals with fast transaction authorization. SL (Stockholm Transport) specifications influence Nordic procurement standards.
Retail holds the largest share; momentum sits with hospitality.
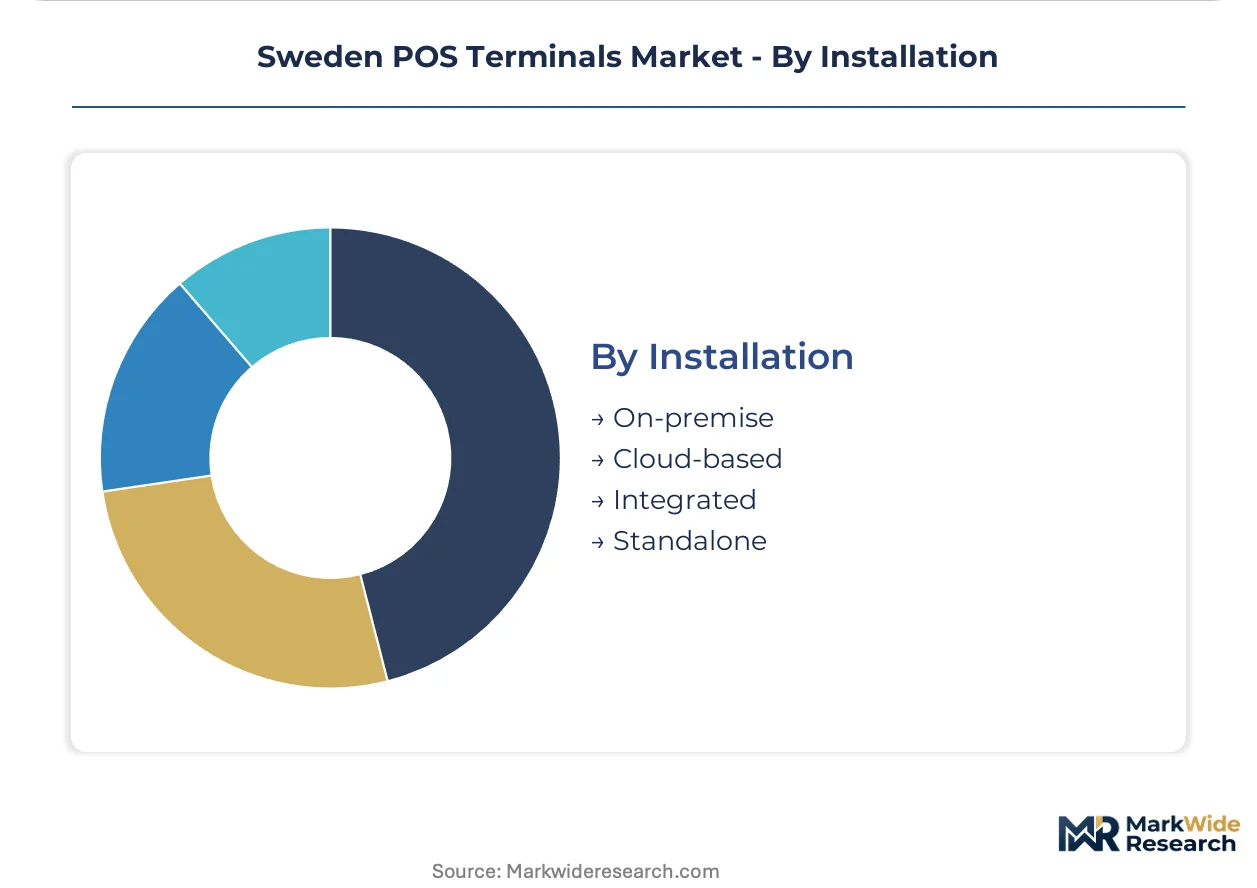
Installation:
Installation architecture determines capital deployment models and ongoing vendor relationships, with maturity stages separating legacy on-premise from cloud-native migration.
- On-premise:Local server-hosted transaction processing with dedicated network infrastructure persists in large merchants with legacy ERP integration. Replacement cycles are extending as cloud migration friction accumulates.
- Cloud-based:Terminal-as-a-service models with remote management and automatic firmware updates are displacing capital purchases. Stockholm's retail chains are piloting subscription contracts with hardware refresh guarantees.
- Integrated:POS terminals embedded within broader merchant management platforms unify payment with inventory, loyalty, and accounting. Omnichannel merchants seek single-vendor stack consolidation.
- Standalone:Independent terminals without back-office system connectivity serve micro-merchants with simple transaction needs. Lowest cost tier attracts temporary and seasonal operators.
On-premise retains the largest installed base; cloud-based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Øresund Bridge and fixed rail links connect Sweden's terminal supply chains to continental European manufacturing corridors. Copenhagen-Malmö logistics integration accelerates component flows from Nordic assembly nodes. Stockholm's retail density anchors domestic procurement volumes.
Stockholm Metropolitan Area
Enterprise grocery chains and fashion retailers drive consolidated terminal procurement across the capital region. Sveriges Riksbank's regulatory proximity shapes early e-krona compatibility testing among hardware deployers. Södermalm's independent hospitality cluster generates mobile terminal demand for tableside payment workflows.
Gothenburg
Sweden's second-largest city exhibits underpenetrated terminal density in independent restaurants and boutique hotels. The Port of Gothenburg's container throughput supports logistics efficiency for hardware distributors serving western Sweden. Haga district's food truck operators pilot QR-code and contactless acceptance formats.
Malmö and Skåne County
Cross-border commerce with Denmark generates dual-currency terminal requirements and multi-acquirer compatibility needs. The Öresund Bridge facilitates same-day hardware replenishment from Copenhagen distribution centers. Hyllie district's retail development concentrates modern terminal deployments in mixed-use commercial zones.
Uppsala
University-town retail and healthcare procurement creates specialized terminal specifications for patient billing and campus commerce. Akademiska Sjukhuset's centralized purchasing influences regional hardware standards for medical payment acceptance. Fyrislund's light industrial zone hosts terminal configuration and staging facilities.
Sweden POS Terminals Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and merchant scale segments. The vendor base stratifies between enterprise-certified suppliers sustaining PCI DSS Level 1 audits and agile specialists targeting hospitality micro-merchants. Three archetypes dominate: Nordic certification pipeline operators, cloud-native platform providers, and unified commerce stack integrators. Competitive moves concentrate on subscription-based terminal-as-a-service transitions and e-krona firmware readiness investments.
Within the certification-pipeline tier, Verifone Sweden AB anchors enterprise deployment relationships across Stockholm's retail corridor. Worldline Group S.A and Adyen exemplify cloud-native and unified commerce positioning respectively, with the latter dominating omnichannel merchant verticals. These three occupy distinct competitive vectors—hardware certification depth, terminal management velocity, and platform integration breadth—without direct feature-for-feature overlap.
| Leading Market Players |
|---|
| Verifone Sweden AB |
| Worldline Group S.A |
| Paypal Inc |
| PayEx Group |
| Nayax Ltd |
| Diebold Nixdorf |
| NCR Voyix |
| Adyen |
| Datecs |
| Others |
Value Network & Pricing Analysis
Long-term terminal-as-a-service contracts lock in hardware refresh cycles and processing-rate visibility for Swedish merchants while binding acquiring partners to PCI DSS Level 1-certified supply commitments. This contract structure concentrates procurement leverage among Stockholm's retail chains and compresses margin flexibility for smaller terminal vendors.
Pricing Analysis
Volume-discount tiering structures separate enterprise grocery chains from independent hospitality operators across three performance levels. Pricing stratifies across premium certified tiers, standard bundled service tiers, and economy standalone tiers based on certification depth and after-sales integration. Cost compression in the economy tier is intensifying because micro-merchants gravitate toward tablet-based solutions with minimal firmware overhead. Independent restaurants in Gothenburg exhibit highest price sensitivity; Stockholm's omnichannel retailers show lowest sensitivity due to unified commerce platform consolidation.
Supply Chain Analysis
Just-in-time inventory strategies dominate terminal assembly operations, though strategic stockpiling of secure processors and EMV modules has intensified following Asian foundry volatility. Manufacturing concentration centers on Taiwan, South Korea, and mainland China for cryptographic chipsets and NFC antenna components. Secure element production draws from TSMC's advanced nodes and Samsung's system-in-package facilities. Single-source vulnerability in EMVCo-certified processor supply creates exposure to geopolitical friction. Distribution runs through Copenhagen-Malmö logistics corridors with same-day replenishment to Stockholm and Gothenburg deployment sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's POS terminal sector functions as a regulatory-moat market where PCI DSS Level 1 certification creates network effects that compound with each enterprise deployment. Switching costs for merchants escalate through embedded peripheral integration and cloud-native management platform dependencies.
For Market Incumbents: Consolidate certification pipeline advantages by deepening Nordic acquiring partnerships and accelerating e-krona firmware roadmap investments. Threat substitution from QR-code wallet solutions demands preemptive NFC antenna optimization. Channel control through direct Stockholm retail chain relationships remains the critical defensive lever. For New Entrants and Emerging Players: PCI DSS Level 1 fast-track partnerships with Swedish Financial Supervisory Authority-registered auditors unlock enterprise tender access previously gated by compliance timelines. Gothenburg's independent hospitality cluster presents the most penetrable whitespace relative to Stockholm's consolidated procurement. Cloud-native terminal management with subscription pricing offers the strongest go-to-market angle against capital-intensive incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platform providers with embedded hospitality vertical expertise and e-krona protocol readiness. Long-term viability across the projection horizon hinges on unified commerce integration breadth rather than hardware manufacturing scale. The signal to watch is Sveriges Riksbank's final e-krona settlement architecture specification; hardware-level mandate would elevate firmware-capable vendors while software-overlay permission would favor agile platform specialists.| Strategic Initiative | Industry Significance |
|---|---|
| E-krona Firmware Integration | Positions vendors for Sveriges Riksbank's CBDC settlement protocol requirements. |
| Cloud-Native Terminal Management | Accelerates merchant onboarding velocity beyond on-premise deployment timelines. |
| PCI DSS Level 1 Certification Investment | Unlocks enterprise grocery and big-box procurement channels in Stockholm corridor. |
| Unified Commerce Platform Convergence | Captures omnichannel retail demand for single-vendor payment stack consolidation. |
| Gothenburg Hospitality Cluster Penetration | Addresses underpenetrated terminal density in independent restaurants and hotels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with merchant acquiring executives, terminal firmware engineers, PCI DSS audit specialists, and Swedish Financial Supervisory Authority policy leads. Secondary validation drew from Sveriges Riksbank e-krona pilot documentation, EMVCo certification registries, EU Payment Services Directive 2 implementation guidance, and Nordic acquiring network disclosure filings. Bottom-up terminal deployment estimates were triangulated against top-down merchant acquiring revenue analysis.
Across the analysis window, forecasting employed segmented modeling across product type, technology, end user, and installation architecture dimensions with regional disaggregation to Stockholm, Gothenburg, Malmö, and Uppsala clusters. CAGRs were derived from terminal shipment velocity correlated with merchant acquisition contract values. E-krona pilot progression timelines and PCI DSS audit completion rates served as industry-specific forecast sensitivity inputs.
Decision-makers should treat outputs as directional under stable central bank digital currency pilot assumptions and continued EMV/NFC protocol dominance; material deviation would warrant model refresh. Revision becomes warranted when e-krona settlement specifications mandate hardware-level integration or when semiconductor supply concentration shifts disrupt secure processor availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Europe Accounts Payable Automation Market
Payments
Croatia POS Terminals Market
Payments
Outdoor Payment Terminal Market
Payments
Transaction Monitoring Market
Payments
Digital Transfer Services Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Wearable Payments Market
Payments
LAMEA Payment Gateway Market
Payments
Mobile Payment Transaction Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Global Smart Payment Systems Market
Payments
North America Real Time Payment Market
Payments
Payment Instruments Market
Payments
Europe Credit Cards Market
Payments
Bus Card Reader Market