
 Italy Power Market | 2026-2036
Italy Power Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Power Market Outlook
Market Context
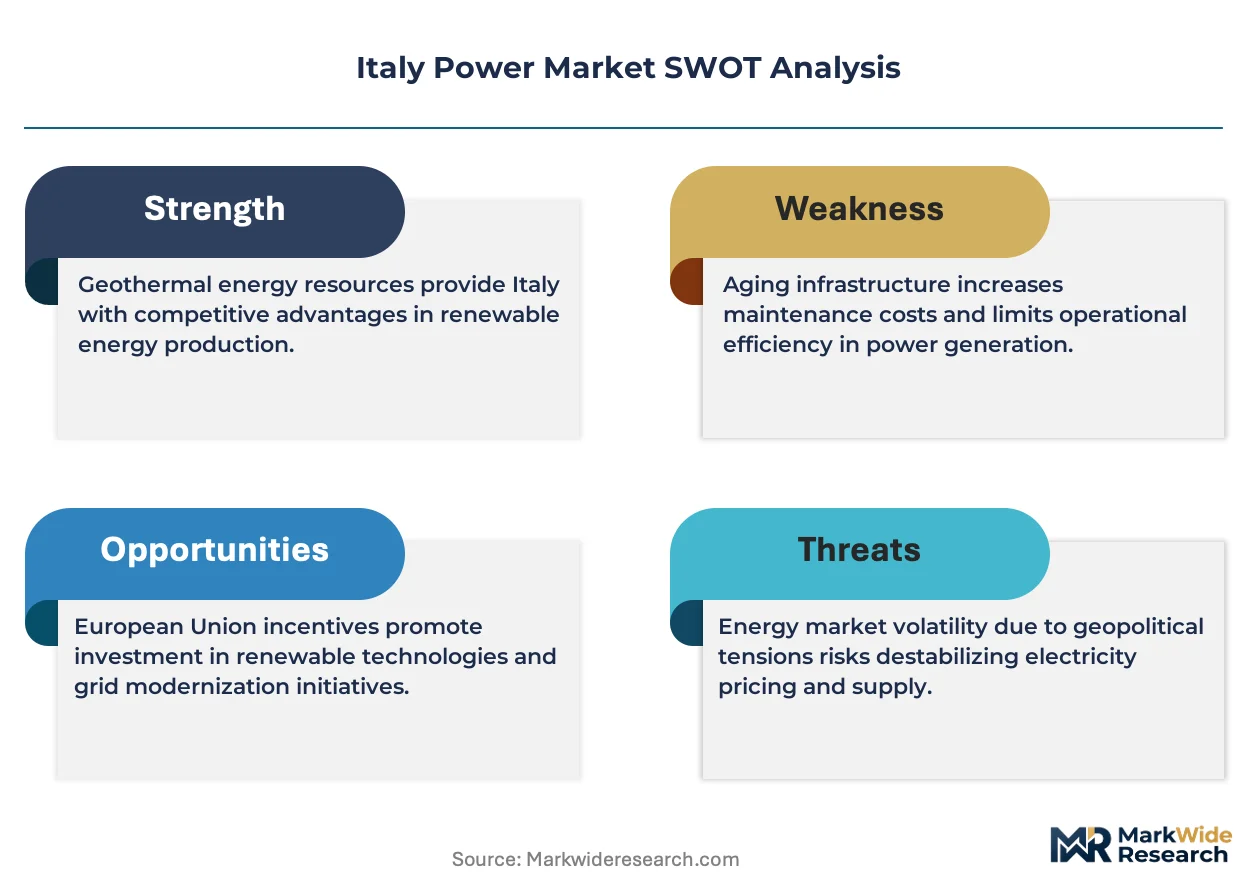
The price spread between premium green-certified power and commodity baseload electricity is hardening across Italian wholesale markets. Enel SpA leverages its integrated generation-retail footprint to sustain margin capture across both tiers. Terna SpA anchors national transmission stability through advanced grid digitalization, while Edison SpA competes aggressively in industrial power purchase agreements with flexible natural gas backup.
Technical and Segment Structure
Italy Power encompasses electricity production, transmission, distribution, and trading across voltage classes from 220 kV backbone networks to 230 V residential service, with primary commercial purpose of delivering reliable alternating current to end users. Renewable generation leads capacity additions, with solar PV occupying the fastest-expansion slot as distributed rooftop arrays multiply across northern manufacturing zones. Energy storage differentiates merchant revenue streams, while industrial end users concentrate demand-response participation due to interruptible load contracts.
Regulatory Framework
ARERA, Italy's energy regulator, shapes wholesale market design and consumer tariff structures through periodic deliberative proceedings. EU Green Deal targets and national REPowerEU implementation plans force accelerated permitting reform for solar and wind projects. Stakeholders must monitor whether grid connection queue reforms clear bottlenecks fast enough to match investor expectations for renewable project commissioning.
Market Dynamics
EU Green Deal carbon neutrality mandates are forcing accelerated electrification of Italian industrial production lines, compressing the timeline for grid-scale renewable integration and storage deployment.
Growth Catalysts
- REPowerEU Implementation:Streamlined permitting for solar PV and wind projects in Lombardy accelerates capacity additions. Manufacturing clusters in Piedmont attract concentrated private capital for hybrid renewable-storage installations.
- Industrial Electrification:Automotive and steel sectors replace gas-fired processes with electric arc furnaces and battery assembly lines. Interruptible load contracts enable demand-response revenue streams for heavy consumers.
- Grid Digitalization:Terna SpA deploys advanced monitoring systems across 220 kV backbone networks. Real-time frequency control stabilizes variable renewable infeed from northern solar clusters.
Market Restraints
- Connection Queue Bottlenecks:Grid connection backlogs in northern regions delay project commissioning. Project developers face 18-24 month waits for transmission access approvals.
- Gas Price Volatility:Flexible natural gas backup remains essential for grid balancing. Edison SpA and competitors absorb margin compression when spark spreads collapse during renewable oversupply hours.
- Land Use Conflicts:Agricultural zoning restrictions in Emilia-Romagna limit utility-scale solar deployment. Ground-mounted projects compete with food production for flat terrain.
Strategic Opportunities
- Agrisolar Convergence:Elevated solar arrays combined with crop cultivation unlock marginal land in southern regions. ARERA tariff incentives reward dual-use installations with priority dispatch.
- Industrial Microgrids:Chemical and pharmaceutical plants in Veneto deploy behind-the-meter storage with islanding capability. Backup power premiums justify capex during grid instability events.
- Green Hydrogen Offtake:Steelmakers in Taranto and chemical producers in Porto Marghera contract electrolyzer output. EU Innovation Fund subsidies bridge cost gaps with gray hydrogen.
Industry Challenges
- Specialized Technician Scarcity:Grid-scale battery installation and high-voltage maintenance require certified electricians. Training pipelines lag deployment schedules in northern manufacturing zones.
- Legacy Meter Integration:Distribution operators struggle to retrofit smart metering infrastructure across aging 230 V residential networks. Interoperability gaps between regional DSO systems complicate national data aggregation.
- Permitting Fragmentation:Municipal approval processes vary across 20 regional jurisdictions. Environmental impact assessments face inconsistent timelines between Sicily and Trentino-Alto Adige.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Power Market |
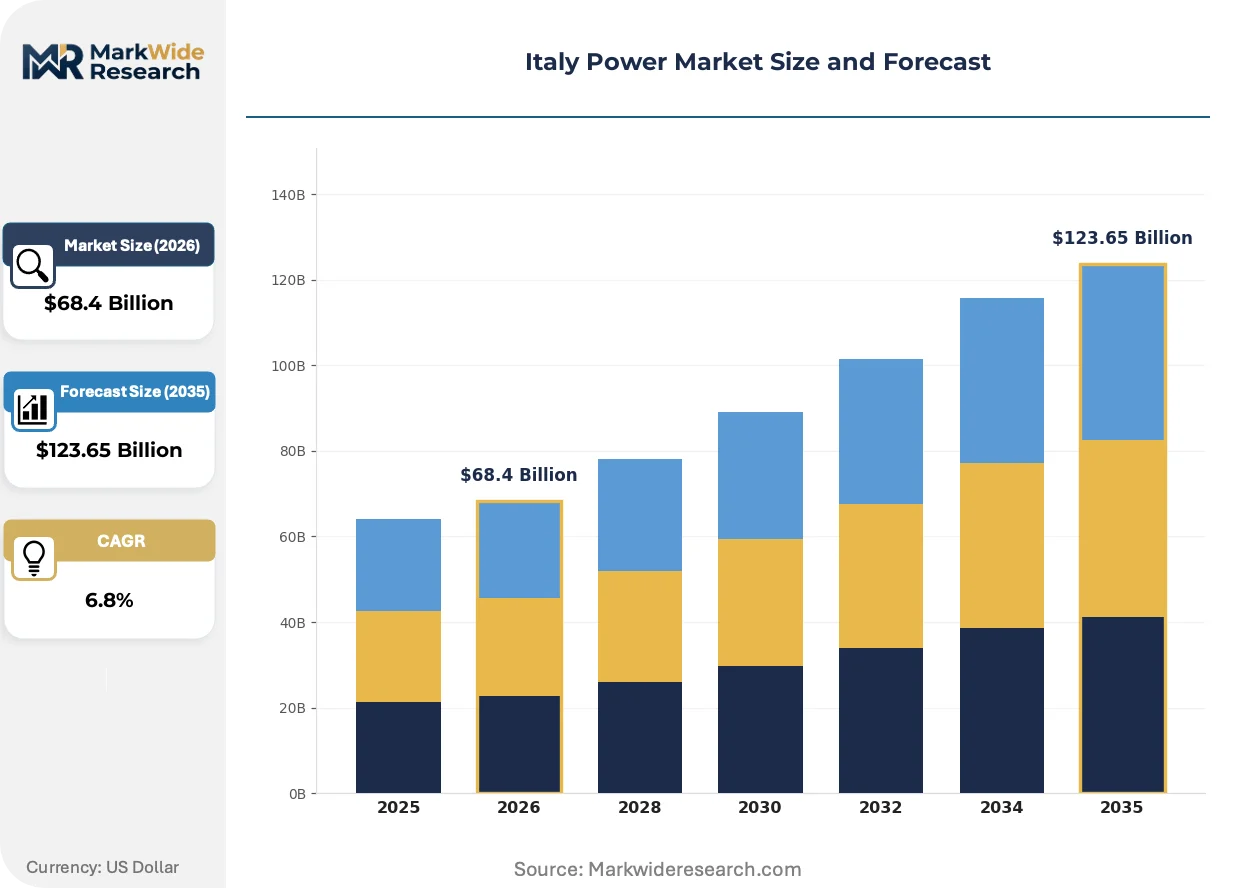
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Non-Renewable, Grid-Connected, Off-Grid Technology: Solar PV, Wind Turbines, Hydro Power, Natural Gas End User: Residential, Commercial, Industrial, Utilities Application: Electricity Generation, Energy Storage, Distribution, Demand Response |
| Companies Covered | Enel SpA, Terna SpA, Edison SpA, A2A SpA, ERG SpA, Acea SpA, Sorgenia SpA, Hera Group, Eni Plenitude, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Power Market Strategic Shifts
Artificial intelligence control systems are automating predictive maintenance and frequency regulation across Italian transmission and distribution networks. These capabilities compress operational response times and reshape competitive requirements for grid service providers.
Machine learning algorithms deployed by transmission operators are automating fault detection and self-healing grid reconfiguration. Regional distribution system operators in Lombardy and Veneto adopt these platforms to reduce outage duration. The technology is automating manual switching operations that previously required field crew dispatch.
ARERA's deliberative proceedings on capacity market design are restructuring remuneration for flexible generation assets. The regulator's proposed two-part tariff separates energy and availability payments. Industrial cogeneration operators in Emilia-Romagna recalibrate dispatch strategies to capture new capacity premiums.
Power purchase agreement structures are migrating from baseload to 24/7 carbon-free matching. Data center operators in Milan and Turin now contract for hourly renewable energy certificates. This procurement evolution forces developers to pair solar PV with four-hour battery storage rather than selling unshaped output.
Italy Power Market Segmentation
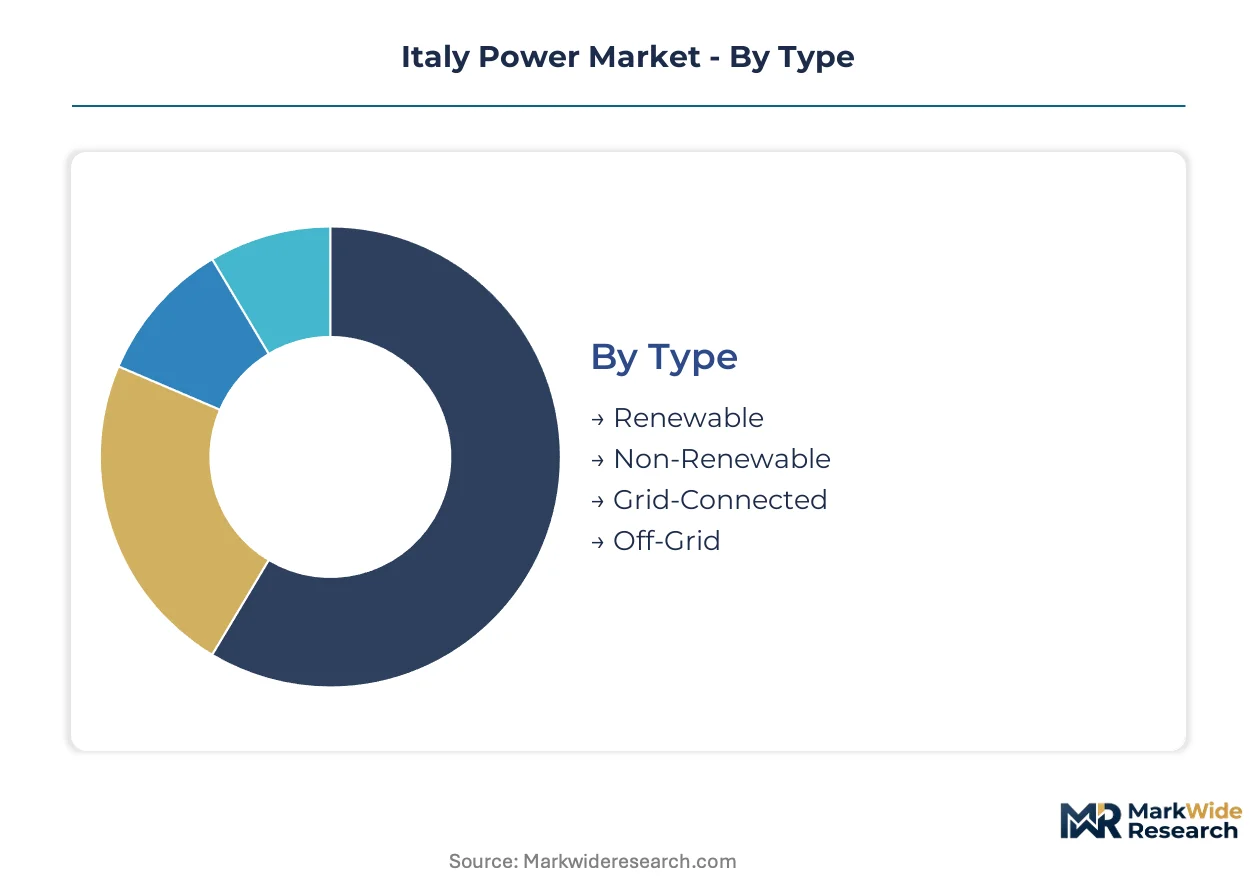
Segmentation in the Italy Power Market reveals distinct investment patterns across generation technologies and customer tiers. Procurement decisions hinge on regulatory incentives, grid access availability, and carbon certification requirements that vary sharply by end-use sector.
Type:
Investment allocation tracks the EU Green Deal's carbon neutrality mandates and ARERA's tariff structures for clean energy certificates.
- Renewable:Solar PV and wind capacity dominate new connections in Lombardy and Piedmont. ARERA priority dispatch incentives accelerate project development timelines for green-certified generation.
- Non-Renewable:Natural gas plants provide flexible balancing capacity during renewable intermittency. Edison SpA and competitors absorb margin compression when spark spreads collapse during solar oversupply hours in northern manufacturing zones.
- Grid-Connected:Centralized generation feeds 220 kV backbone networks managed by Terna SpA. Real-time frequency control systems stabilize variable renewable infeed from clustered solar installations.
- Off-Grid:Industrial microgrids with islanding capability serve chemical and pharmaceutical plants in Veneto. Backup power premiums justify capex during grid instability events in manufacturing corridors.
Grid-connected renewable leads on scale; off-grid industrial microgrids lead on momentum.
Technology:
Technology selection reflects resource availability, permitting speed, and integration costs across Italy's heterogeneous terrain.
- Solar PV:Distributed rooftop arrays multiply across northern manufacturing zones, with Lombardy attracting concentrated private capital for hybrid renewable-storage installations. ARERA streamlined permitting accelerates capacity additions in industrial clusters.
- Wind Turbines:Onshore projects face land use conflicts in agricultural regions of Emilia-Romagna. Elevated hub heights and larger rotors improve capacity factors in Apennine foothill corridors.
- Hydro Power:Pumped storage facilities in Alpine regions provide grid-scale balancing services. Terna SpA procures frequency regulation from existing reservoir infrastructure.
- Natural Gas:Combined-cycle plants remain essential for grid balancing and industrial process heat. Flexible dispatch contracts enable demand-response revenue streams for heavy consumers in steel and automotive sectors.
Solar PV commands the steepest expansion trajectory; hydro power holds the most stable revenue base.
End User:
Customer segmentation reveals divergent price sensitivity, contract structures, and decarbonization timelines across the Italian economy.
- Residential:Behind-the-meter solar and battery storage spreads through net metering incentives. Distribution operators struggle to retrofit smart metering infrastructure across aging 230 V networks in southern regions.
- Commercial:Data center operators in Milan and Turin contract for hourly renewable energy certificates. Procurement evolution forces developers to pair solar PV with four-hour battery storage rather than selling unshaped output.
- Industrial:Automotive and steel sectors replace gas-fired processes with electric arc furnaces and battery assembly lines. Interruptible load contracts enable demand-response participation for heavy consumers.
- Utilities:Merchant generators compete for capacity market payments under ARERA's proposed two-part tariff design. Availability premiums reshape dispatch strategies for flexible assets.
Industrial offtake leads on scale; commercial hourly-matching contracts lead on pricing innovation.
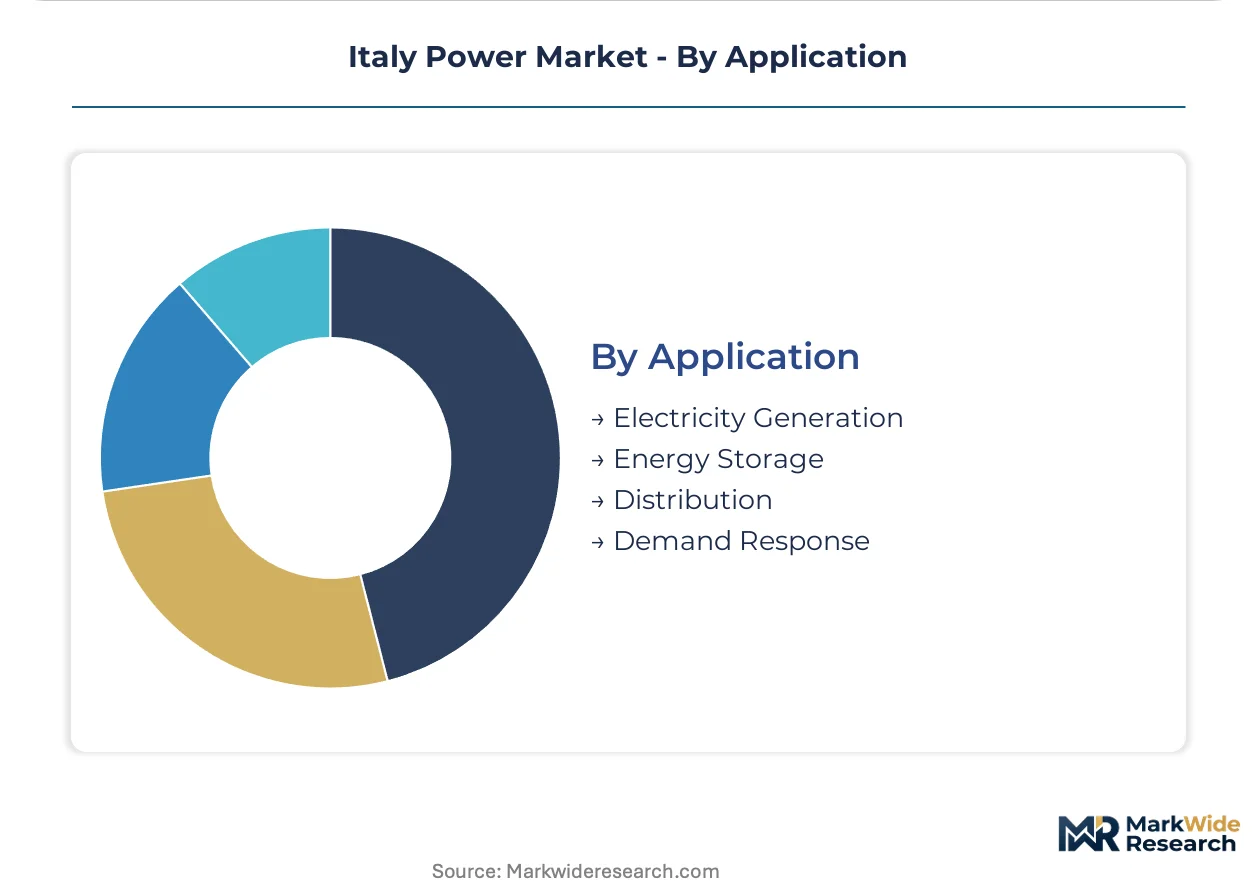
Application:
Application segmentation tracks where value capture concentrates across the power value chain from generation to end-use flexibility.
- Electricity Generation:Utility-scale solar and wind projects concentrate in northern regions with transmission access. Connection queue backlogs delay commissioning by 18-24 months in congested zones.
- Energy Storage:Four-hour lithium-ion systems pair with solar PV to meet 24/7 carbon-free procurement requirements. Grid-scale battery installation faces certified electrician scarcity in manufacturing corridors.
- Distribution:Regional DSO systems in Lombardy and Veneto adopt AI-enabled fault detection platforms. Interoperability gaps complicate national data aggregation across 20 regional jurisdictions.
- Demand Response:Interruptible load contracts aggregate industrial flexibility for Terna SpA's frequency control services. Steelmakers and chemical producers monetize curtailment capability during peak demand events.
Electricity generation leads on capital deployment; energy storage leads on growth velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized grid technicians and certified electricians concentrate in northern manufacturing corridors, anchoring deployment capacity for transmission upgrades and renewable integration across Italy's most industrialized zones.
Lombardy
Data center expansion in Milan and automotive electrification drive 24/7 carbon-free procurement demand. ARERA streamlined permitting accelerates solar PV connections for industrial clusters. Bergamo and Brescia manufacturing zones attract hybrid renewable-storage investments from private capital pools.
Piedmont
Steel sector decarbonization and battery assembly lines compress electrification timelines for heavy industry. EU Green Deal implementation funds support grid-scale battery procurement in Turin corridors. Alessandria and Novara host concentrated private investment for merchant energy storage installations.
Veneto
Chemical and pharmaceutical plants deploy islanding-capable microgrids to secure backup power premiums. Regional distribution operators adopt AI-enabled fault detection platforms under Terna SpA coordination. Verona and Padua industrial parks lead demand-response participation through interruptible load contracts.
Emilia-Romagna
Agricultural zoning restrictions limit utility-scale solar deployment on flat terrain. Municipal approval processes face inconsistent timelines for environmental impact assessments. Bologna and Modena manufacturing clusters recalibrate cogeneration dispatch strategies to capture ARERA capacity market premiums.
Lazio
Central government procurement and institutional energy demand concentrate in Rome metropolitan infrastructure. Terna SpA anchors national transmission stability operations from regional control centers. Fiumicino logistics corridors attract behind-the-meter solar installations for commercial load matching.
Italy Power Market Competitive Environment
Top-tier vendors anchor integrated generation-retail operations, while mid-scale specialists compete for industrial power purchase agreements and merchant storage revenue streams. The competitive structure stratifies across three archetypes: vertically integrated utilities controlling transmission access, independent renewable developers securing priority dispatch, and regional energy service companies aggregating distributed flexibility. Consolidation pressure concentrates among grid-connected asset operators facing connection queue bottlenecks. Competitive moves center on strategic partnerships for hybrid project development and portfolio diversification into behind-the-meter storage.
Within the integrated utility tier, Enel SpA and Terna SpA occupy positions spanning generation, transmission, and grid management functions. Edison SpA exemplifies the flexible generation archetype competing for industrial offtake contracts with natural gas backup capacity. These three entities represent the dominant competitive anchors shaping wholesale market design and transmission access allocation across Italian power markets.
| Leading Market Players |
|---|
| Enel SpA |
| Terna SpA |
| Edison SpA |
| A2A SpA |
| ERG SpA |
| Acea SpA |
| Sorgenia SpA |
| Hera Group |
| Eni Plenitude |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon neutrality mandates gate access to premium-tier green-certified power contracts and qualified renewable supply pools. ARERA tariff structures reward priority dispatch for certified generation while excluding conventional sources from premium pricing tiers, compressing margins for non-compliant suppliers.
Pricing Analysis
Bundled energy-plus-certificates service splits from unbundled commodity baseload power across Italian wholesale markets. Three-tier pricing structure across green-certified premium, standard grid-mix, and interruptible economy levels reflects carbon content and dispatch priority. Price differentiation stems from certification grade under EU Green Deal frameworks and volume scale of industrial offtake agreements. Margins are tightening for flexible natural gas backup operators when spark spreads collapse during solar oversupply hours in northern manufacturing zones. Industrial steel and automotive sectors show least price sensitivity due to carbon compliance requirements, while residential segments face highest sensitivity to distribution tariff fluctuations.
Supply Chain Analysis
Reverse-logistics flows for lithium-ion battery refurbishment and solar panel remanufacturing are emerging as secondary supply streams for grid-scale storage projects. Manufacturing concentration centers on China for solar PV modules and battery cells, Germany for power electronics and inverters, and South Korea for advanced battery chemistries. Raw material dependencies include polysilicon feedstock, lithium carbonate, and rare earth magnets for turbine generators. Single-source vulnerability for semiconductor components in grid inverters creates procurement risk for Terna SpA digitalization programs. Distribution runs through EPC contractors and specialized electrical wholesalers serving Lombardy and Piedmont industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy Power Market economics favor margin expansion through industrial electrification premiums and carbon certificate value capture. Cost compression in solar PV modules and battery cells enables developer returns even under competitive auction pressure.
For Market Incumbents: Anticipate connection queue bottlenecks by securing early transmission access reservations in northern regions. Prioritize backward integration into energy storage manufacturing to defend margins against merchant revenue volatility. Capture ARERA capacity market premiums through flexible asset dispatch optimization in Emilia-Romagna cogeneration corridors.
For New Entrants and Emerging Players: Agrisolar developers in southern Italian regions represent underserved buyer archetypes seeking dual-use land optimization. White-space targets include behind-the-meter microgrids for Veneto pharmaceutical plants and electrolyzer offtake contracts for Taranto steelmakers. Penetrate through specialized EPC partnerships offering integrated solar-plus-storage engineering rather than component-only supply.
For Investors and Strategic Acquirers: Roll-up economics work for regional energy service companies because municipal permitting fragmentation prevents national-scale organic expansion. Long-term viability hinges on portfolio diversification across generation, storage, and demand-response assets. Acquisition targets should demonstrate secured grid connection queue positions in Lombardy or Piedmont. Monitor ARERA deliberative proceedings on capacity market design for inflection signals in availability payment structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Renewable-Storage Capacity Buildout | Lombardy manufacturing zones attract concentrated private capital for solar-plus-battery installations under streamlined ARERA permitting. |
| Power Purchase Agreement Restructuring | Hourly carbon-free matching requirements from Milan data centers force 24/7 procurement innovation beyond baseload contracts. |
| Grid Digitalization Technology Licensing | Terna SpA deployment of AI-enabled fault detection platforms creates vendor opportunities across regional DSO systems. |
| Backward Integration into Battery Manufacturing | Edison SpA and competitors absorb margin compression when merchant storage revenues fluctuate with renewable oversupply cycles. |
| Green Certification Program Expansion | EU Green Deal implementation funds bridge cost gaps for electrolyzer output contracting with Porto Marghera chemical producers. |
Study Parameters
Multiple input streams — utility planning officers, IPP project developers, EPC contractors, and grid operators — were reconciled with secondary validation from ARERA regulatory filings, Terna SpA transmission data, EU Green Deal implementation documents, and project development databases. Primary interviews captured operational perspectives on connection queue dynamics and permitting timelines across Lombardy, Piedmont, and Veneto regions. Bottom-up capacity addition tracking and top-down macroeconomic scenario analysis enabled triangulation of investment flow estimates.
Cross-referencing historical commissioning patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include generation technology type, end-use sector, project scale tier, and regional grid congestion status. CAGRs were derived from capacity deployment schedules and tariff evolution assumptions. Forecast inputs incorporated industrial electrification timelines for automotive and steel sectors alongside REPowerEU permitting reform implementation pace.
Inputs from ARERA proceedings and Terna SpA grid development plans were available through the study window; gaps in municipal permitting timeline data introduce uncertainty bands around project commissioning schedules. Forecasts reflect documented assumptions regarding EU Green Deal target adherence and REPowerEU fund disbursement rates. Practitioners should monitor ARERA capacity market design finalization and connection queue reform implementation for early signals of investment flow redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Saudi Arabia Power Market
Power
Global Diesel Power Engine Market
Power
Telecom Power Rental Market
Power
Global Hydraulic Turbine Market
Power
Smart PV Inverters Market
Power
Combined Heat and Power (CHP) Systems Market
Power
Europe Microturbine Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Mexico Power Market
Power
Spain Power Market
Power
Wind Alarm Controller Market
Power
Single-Phase Microinverter Market
Power
Europe Power Market
Power
Europe Frequency Converter Market
Power
Sudan Power Market
Power
Harmonic Filter Market