

Residential Portable Inverter Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Portable Inverter Generator Market Insights
The capital-intensity gap between mass-market assemblers and engine-integrated manufacturers is collapsing as clean-sheet inverter designs lower tooling thresholds. Honda Motor leverages captive engine production to sustain margin structures that pure-brand competitors cannot match. Generac Power Systems anchors its position through vertical control over controller firmware and enclosure fabrication. Champion Power Equipment competes aggressively on retail shelf space, dominating home improvement center placements across North America.
Residential portable inverter generators convert mechanical energy from small internal combustion engines into stable alternating current through high-frequency inversion and waveform conditioning, typically achieving total harmonic distortion below three percent to safely power sensitive electronics. The dual fuel product type segment commands premium positioning as propane compatibility extends runtime flexibility during extended outages. The 1000W-2000W power capacity band leads unit volume among campers and tailgaters, while above-3000W configurations capture disproportionate value from whole-home backup applications. Home improvement centers remain the dominant distribution channel for first-time buyers seeking tactile comparison, though online retail is displacing specialty stores for replacement purchases.
The EPA regulates exhaust emissions under 40 CFR Part 90, while CARB imposes stricter standards that effectively gate California market access and influence national product planning. OSHA guidelines for temporary power in construction-adjacent settings indirectly shape industrial-feature demand in crossover residential units. NHTSA transport regulations constrain fuel tank sizing and packaging for road-shipped units. Stakeholders must monitor state-level building code amendments that increasingly mandate carbon monoxide shutoff integration as a condition of lawful sale.
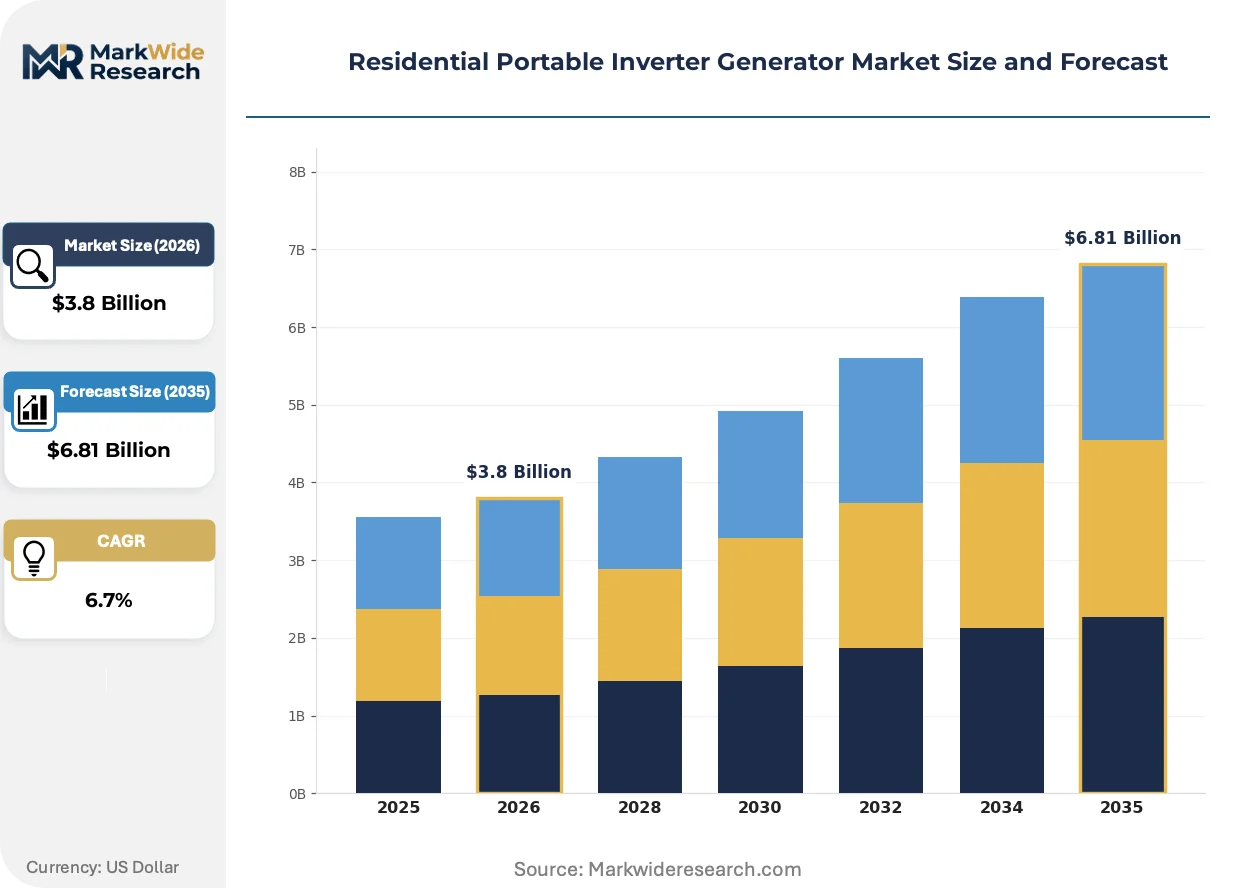
Market Dynamics
Clean-sheet inverter architectures are collapsing traditional capital barriers between engine-integrated manufacturers and pure-brand assemblers, redistributing competitive leverage toward firmware and enclosure design capabilities.
Growth Catalysts
- CARB Tier 3 Standards:California's stricter emissions thresholds accelerate R&D investment in closed-loop fuel injection and catalytic after-treatment, pulling national product roadmaps toward cleaner combustion architectures.
- Camping and Tailgating:Outdoor recreation participation drives 1000W-2000W unit demand, with recreational vehicle owners prioritizing acoustic attenuation and parallel connection capability for scalable power.
- Grid Instability Patterns:Severe weather-induced outage frequency concentrates replacement demand in Texas, Florida, and the Northeast, compressing purchase decision timelines from seasonal to event-triggered.
Market Restraints
- Steel and Aluminum Input Volatility:Enclosure and fuel tank fabrication costs fluctuate with commodity pricing, squeezing margin structures for manufacturers lacking long-term supply agreements with rolling mills.
- Small-Engine Supply Concentration:Sourcing dependency on a limited set of Japanese and Chinese engine specialists creates vulnerability to allocation constraints during demand surges.
- Substitution by Stationary Standby Systems:Permanent whole-home generators with automatic transfer switches capture affluent households seeking seamless outage response, capping portable inverter ceiling in above-5000W applications.
Strategic Opportunities
- Battery-Generator Hybrids:Lithium-ion buffer integration with compact combustion engines enables silent operation modes and peak shaving, appealing to noise-restricted campgrounds and residential neighborhoods.
- Home Improvement Center Exclusive Lines:Private-label partnerships with Lowe's and Home Depot unlock shelf placement and co-marketing investments inaccessible to independent brands.
- IRA Energy Security Tax Credits:Federal incentives for residential clean energy equipment create eligibility pathways for solar-compatible inverter generators with battery storage integration.
Industry Challenges
- Firmware Talent Scarcity:Power electronics control algorithm development requires embedded systems expertise that competes with automotive and consumer electronics sectors for limited engineering pools.
- EPA Certification Timelines:Exhaust emission validation under 40 CFR Part 90 extends product launch windows by 8-14 months, delaying revenue realization for redesigned engine families.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Portable Inverter Generator Market Trends and Innovations
Waveform conditioning algorithms and fuel flexibility architectures are redefining product differentiation, shifting competitive emphasis from raw power output toward runtime economics and electronic compatibility assurance.
GaN-based inverter switching is fragmenting the traditional IGBT-dominated power conversion landscape. Gallium nitride semiconductors enable higher switching frequencies with reduced thermal losses, allowing manufacturers to shrink heat sink mass and enclosure volume. Recreational users and professional contractors are adopting these compact units for transport-constrained applications. The technology is fragmenting established supplier relationships as semiconductor foundries outside Japan gain process maturity.
EPA's evolving small spark-ignition engine standards under 40 CFR Part 90 are forcing fuel system redesigns across the supplier base. Closed-loop electronic fuel injection replaces carbureted architectures to meet hydrocarbon and carbon monoxide limits, raising bill-of-materials costs but enabling precise air-fuel ratio control. California-bound product SKUs bear the heaviest compliance burden, with manufacturers consolidating variant counts to amortize certification investments nationally.
Buyers are consolidating purchase authority around online retail platforms for replacement and upgrade transactions. First-time purchasers still favor tactile evaluation at home improvement centers, but repeat customers prioritize specification comparison and delivery speed through Amazon and direct-to-consumer channels. This behavioral pivot concentrates marketing spend toward digital shelf optimization and review management, with the Southeast and Mountain West showing the strongest e-commerce penetration in residential categories.
Residential Portable Inverter Generator Market Segmentation
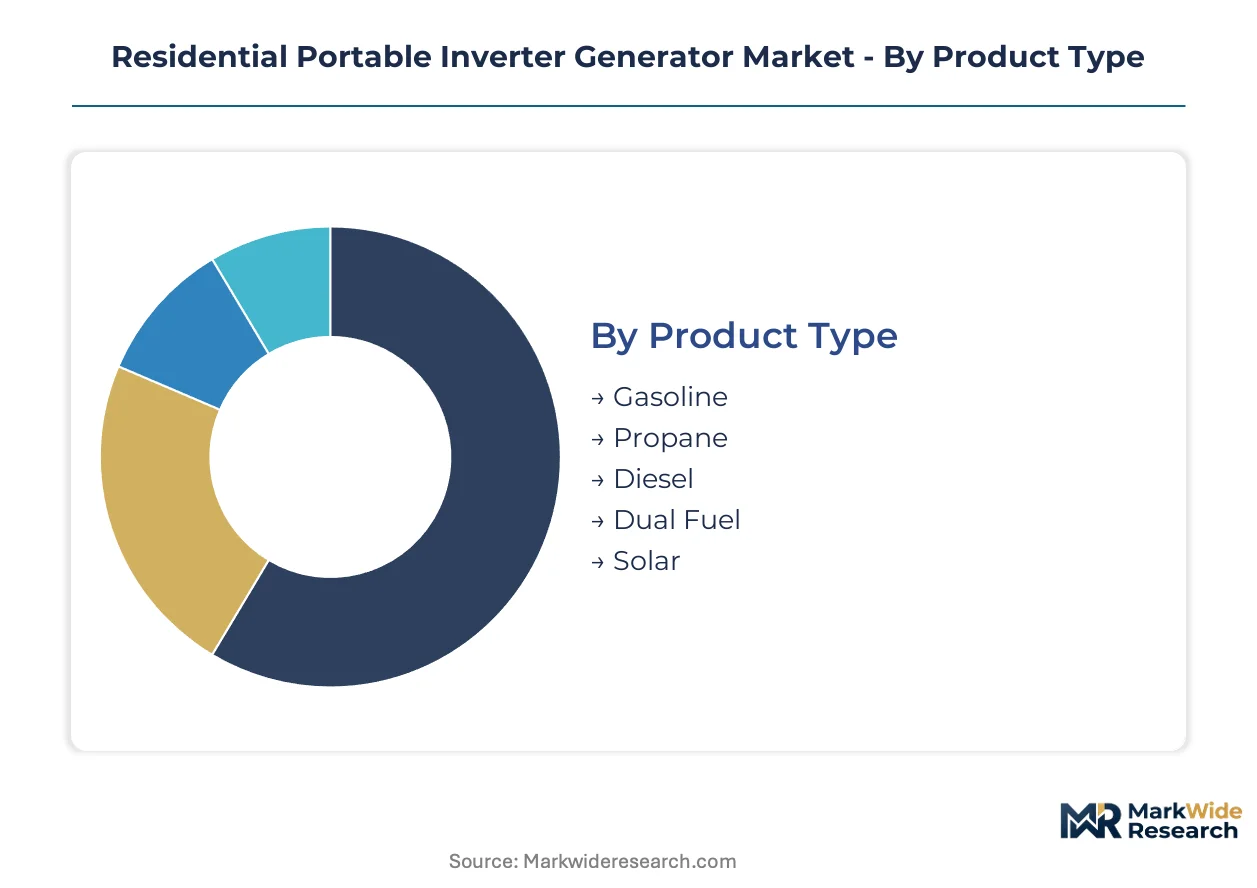
Segmentation in residential portable inverter generators reveals how fuel flexibility, power scaling, and purchase context reshape manufacturer priorities. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Domestic U.S. demand concentrates on gasoline and dual fuel architectures, while European and Australian export markets pull propane and solar-compatible variants. Cost tier differentiation separates commodity carbureted units from EFI-equipped premium offerings.
- Dual Fuel:Propane compatibility extends runtime flexibility during extended outages, with homeowners in Texas and Florida paying premiums for fuel-switching capability. EPA Tier 3 compliance costs concentrate in this segment as closed-loop injection becomes mandatory.
- Gasoline:Carbureted architectures dominate unit volume through home improvement center placements, though margin compression from steel tank volatility squeezes pure-brand assemblers lacking captive engine supply.
- Propane:Clean-burning characteristics appeal to California buyers facing CARB restrictions; tank integration adds fabrication complexity that favors vertically integrated manufacturers.
- Diesel:Compression-ignition efficiency targets commercial-adjacent residential users needing extended runtime; particulate after-treatment requirements limit supplier base to specialized engine houses.
- Solar:Battery-integrated hybrids attract IRA credit-eligible installations, with panel compatibility requirements driving controller firmware specialization.
Gasoline commands the established base. The steepest expansion runs through dual fuel configurations.
Power Capacity:
Volume-maturity alignment separates saturated sub-2000W recreational bands from growth-oriented whole-home backup categories. Application context determines whether buyers prioritize acoustic attenuation or surge capacity.
- 1000W-2000W:Parallel-connection capability enables scalable output for RV owners and tailgaters; acoustic enclosure design becomes the primary purchase differentiator in this noise-sensitive use case.
- Above 3000W:Whole-home backup applications in hurricane-prone Southeast states capture disproportionate value, though substitution by stationary standby systems caps ceiling in above-5000W configurations.
- Below 1000W:Ultra-portable units target backpacking and drone charging; lithium-ion battery substitution threatens long-term combustion relevance.
- 2001W-3000W:Contractor crossover demand drives industrial-feature inclusion; OSHA temporary power guidelines indirectly shape product specifications.
1000W-2000W anchors current volume. Above 3000W is climbing the fastest as grid instability intensifies.
End User:
Customer type fragmentation splits between event-triggered emergency purchasers and planned recreational investors, with divergent sensitivity to price, weight, and runtime specifications.
- Homeowners:Backup power needs intensify across Texas, Florida, and Northeast corridors; purchase decisions compress from seasonal planning to post-storm urgency.
- Campers:National park noise restrictions and RV park electrical codes drive demand for inverter-specific waveform conditioning below 3% THD.
- Emergency Responders:Redundant power requirements for field medical and communication equipment specify military-grade transport durability.
- Event Organizers:Festival and outdoor wedding applications prioritize rapid deployment and parallel stacking for stage and catering loads.
Homeowners command the established base. Campers are gaining share fastest as outdoor recreation participation expands.
Distribution Channel:
Channel strategy bifurcates between tactile-first acquisition for novices and specification-driven replacement buying, with geographic concentration in suburban retail corridors versus direct-to-consumer shipping zones.
- Home Improvement Centers:Lowe's and Home Depot placements dominate first-time buyer touchpoints; co-marketing investments and exclusive private-label lines lock out independent competitors.
- Online Retail:Amazon and direct-to-consumer channels displace specialty stores for replacement purchases; Southeast and Mountain West show strongest e-commerce penetration.
- Specialty Stores:Independent dealers retain relevance for contractor-grade and high-capacity units requiring technical consultation.
- Direct Sales:Manufacturer-controlled channels capture warranty and service attachment revenue, particularly for hybrid and solar-integrated systems.
Home improvement centers command the established base. Online retail is climbing the fastest as repeat purchase behavior shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in hurricane-prone coastal states show the lowest price elasticity, absorbing premiums for dual fuel capability and rapid delivery, while price-sensitive recreational purchasers in inland Mountain West states drive commoditization in the sub-2000W band.
United States
Grid reliability concerns and severe weather-induced outage frequency concentrate replacement demand in Texas, Florida, and the Northeast, compressing purchase timelines from seasonal planning to event-triggered urgency. The EPA's 40 CFR Part 90 emissions standards and California's CARB Tier 3 requirements shape national product roadmaps. Houston and Miami metropolitan areas anchor the highest per-capita generator ownership rates, with big-box retail corridors dominating distribution.
Canada
Rural cottage culture and ice storm vulnerability sustain steady demand across Ontario and Quebec provinces, with buyers prioritizing cold-start reliability and propane compatibility for remote access. Transport Canada regulations constrain fuel tank sizing for road-shipped units. The Greater Toronto Area concentrates specialty dealer networks serving contractor-grade crossover applications.
Germany
Outdoor recreation participation and camping infrastructure investment drive inverter-specific demand, with buyers emphasizing acoustic attenuation for noise-restricted campgrounds. The EU Green Deal and national building efficiency codes indirectly shape backup power planning. Industrial clusters in Baden-Württemberg and Bavaria host precision machining suppliers serving enclosure fabrication.
Japan
Disaster preparedness culture and frequent seismic events sustain replacement cycles, with buyers prioritizing compact form factors for storage-constrained urban dwellings. METI energy security guidelines influence residential backup equipment standards. The Chubu region around Nagoya anchors small-engine manufacturing concentration and controller firmware development.
Australia
Bushfire-induced grid isolation and remote property electrification drive demand for portable backup solutions, with rural buyers accepting diesel configurations for extended runtime. The country's national building regulator mandates carbon monoxide shutoff integration as a condition of lawful sale. Industrial corridors in New South Wales and Victoria concentrate metal fabrication capacity for fuel tank and enclosure production.
Residential Portable Inverter Generator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with captive engine manufacturers sustaining margin structures that pure-brand assemblers cannot replicate. The market structure consolidates around vertically integrated specialists controlling critical component supply, while private-label partnerships with home improvement centers lock out independent competitors from shelf placement. Two dominant strategic archetypes emerge: engine-integrated manufacturers leveraging backward integration into powertrain production, and firmware-focused specialists controlling waveform conditioning and controller design. Competitive moves concentrate on exclusive retail line negotiations and clean-sheet inverter architecture development to collapse traditional capital barriers.
Among engine-integrated manufacturers, Honda Motor and Yamaha Motor exemplify the captive-production archetype, with geographic origins in Japan anchoring their positioning within precision-engineering supply networks. Generac Power Systems represents the vertically integrated North American specialist, while Champion Power Equipment occupies a position within the aggressive retail-placement tier. Briggs & Stratton and Kohler sit within the established engine-house segment, their corporate suffixes indicating long-standing industrial equipment lineage. Westinghouse Electric Corporation anchors the brand-licensing archetype, leveraging historical recognition without captive manufacturing infrastructure. These named companies illustrate how competitive leverage redistributes toward firmware and enclosure design capabilities as clean-sheet architectures lower traditional tooling thresholds.
| Leading Market Players |
|---|
| Honda Motor |
| Generac Power Systems |
| Yamaha Motor |
| Briggs & Stratton |
| Cummins |
| Kohler |
| Champion Power Equipment |
| Westinghouse Electric Corporation |
| A-iPower |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen month EPA certification timelines for 40 CFR Part 90 compliance concentrate pricing power with engine-integrated manufacturers holding captive validation resources, while pure-brand assemblers absorb margin compression from extended inventory cycles. Steel and aluminum input volatility for enclosure fabrication feeds directly into tiered pricing stratification across premium EFI-equipped and commodity carbureted product lines.
Pricing Analysis
After-sales service contracts and replacement parts revenue anchor lifetime value economics for manufacturers with established dealer networks. Three-tier pricing structure across premium EFI-equipped, standard inverter, and economy carbureted levels separates Honda and Generac from Champion and Westinghouse at retail. Cost compression in the sub-2000W recreational band intensifies from lithium-ion battery substitution threats. Homeowners in hurricane-prone coastal states show the lowest price sensitivity, while Mountain West campers drive commoditization in portable entry segments.
Supply Chain Analysis
Japan and China anchor small-engine manufacturing concentration, with the Chubu region around Nagoya hosting precision machining for crankcase and cylinder production. Controller firmware development draws from embedded systems talent pools in Taiwan and South Korea, while enclosure metalwork feeds from rolling mills in the United States and Mexico. Single-source vulnerability concentrates in Japanese EFI system suppliers and Chinese aluminum casting houses. Distribution runs through home improvement center consolidation with Lowe's and Home Depot, though direct-to-consumer channels are accelerating for replacement purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parallel-connection firmware standardization and battery-generator hybrid interoperability are transforming this market toward platform-economics dynamics, where ecosystem lock-in replaces discrete product competition.
For Market Incumbents: Secure exclusive firmware licensing agreements with campground and RV park networks to embed runtime monitoring and predictive maintenance interfaces before open standards emerge. Defend margin structures by backward integration into EFI controller production, countering the threat of clean-sheet inverter architectures collapsing traditional capital barriers. Channel control through co-marketing investments with home improvement centers remains essential to shelf placement dominance. For New Entrants and Emerging Players: Differentiate on solar-compatible hybrid architectures targeting IRA credit-eligible installations in Texas and Florida, where grid instability creates urgent replacement demand. The battery-integrated segment offers the most penetrable white space, with firmware specialization for panel compatibility serving as the primary go-to-market angle against established combustion-only portfolios. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized small-engine production capacity and dormant EPA certifications. Long-term viability hinges on hybrid technology transition execution rather than combustion-only scale. Watch for state-level building code amendments mandating carbon monoxide shutoff integration as the signal for regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EFI System Backward Integration | Captive fuel injection production insulates margin structures from EPA Tier 3 compliance cost spikes. |
| Battery-Generator Hybrid Launch | Lithium-ion buffer integration unlocks silent operation modes for noise-restricted campgrounds and residential zones. |
| Home Improvement Center Exclusive Line | Private-label partnerships with Lowe's and Home Depot lock out independent competitors from retail shelf placement. |
| Parallel-Connection Firmware Platform | Scalable power architectures for RV owners create ecosystem stickiness through proprietary stacking protocols. |
| CARB Tier 3 Pre-Certification Investment | California market access gates national product roadmaps, consolidating variant counts to amortize validation costs. |
Research Methodology
Desk research of EPA certification databases, CARB executive orders, and home improvement center SKU listings preceded structured interviews with product development directors at engine-integrated manufacturers, procurement leads at pure-brand assemblers, and category buyers at Lowe's and Home Depot. Secondary validation drew from 40 CFR Part 90 filing records, steel and aluminum commodity pricing indices, and campground electrical code amendments across Texas, Florida, and California. Bottom-up unit shipment modeling triangulated against top-down revenue estimates from disclosed segment reporting.
Variance decomposition across power capacity tiers, fuel type architectures, and distribution channel splits anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers including grid reliability indices, outdoor recreation participation surveys, and residential construction permits. Industry-specific forecast inputs incorporated EPA regulatory timeline assumptions and lithium-ion battery cost curve trajectories for hybrid product viability assessment.
Material uncertainties — severe weather frequency deviation, steel tariff implementation, and EFI component allocation constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and consumer substitution elasticity between portable and stationary backup systems. Recalibration cycles align with material shifts in EPA rulemaking schedules and state-level building code adoption patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.