
 United States Laundry Appliances Market | 2026-2036
United States Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United States Laundry Appliances Market Analytics
DOE energy conservation standards is decoupling legacy manufacturing footprints from future cost structures by mandating higher efficiency thresholds that favor inverter motor platforms and heat-pump dryer architectures. Whirlpool Corporation leverages its Benton Harbor manufacturing base to sustain domestic production scale against import cost volatility. GE Appliances anchors its competitive position through vertical integration into compressor and control board production. Samsung Electronics America differentiates via connected appliance ecosystems that integrate with broader smart home platforms.
United States laundry appliances encompass electrically or gas-powered machines designed for fabric cleaning and drying, typically rated between 120V and 240V with drum capacities spanning 2.3 to 6.0 cubic feet depending on installation category. These systems employ mechanical agitation, centrifugal extraction, and thermally regulated airflow to remove soils and moisture from textiles across residential and commercial settings. Washing machines dominate unit volume within the product type dimension, though heat-pump dryers represent the fastest-expanding margin pool as energy codes tighten. Smart appliances within the technology dimension are capturing premium positioning through remote diagnostics and utility demand-response integration, while commercial laundries in the end user dimension sustain replacement demand through fleet amortization schedules tied to coin-op revenue models.
DOE appliance efficiency rules, EPA ENERGY STAR certification thresholds, and CPSC product safety standards collectively shape design requirements, testing protocols, and market access conditions for manufacturers selling into the United States. The EPA's evolving ENERGY STAR criteria specifically push water factor and modified energy factor metrics that disadvantage conventional top-load agitator designs. Stakeholders must monitor state-level electrification mandates and utility rebate program shifts that increasingly favor heat-pump technology over resistive heating elements.
Market Dynamics
DOE energy conservation standards are forcing a platform migration from conventional agitator washers to inverter-driven front-load architectures and heat-pump dryer systems across residential product lines.
Growth Catalysts
- Multi-family residential construction:Developers in Texas, Florida, and California are expanding in-unit laundry specifications as rental housing stock modernizes.
- EPA ENERGY STAR certification:Tightening water factor and modified energy factor thresholds create pull-through demand for high-efficiency replacement cycles.
- Heat-pump dryer technology:Residential adoption accelerates as utility rebate programs and state electrification mandates favor thermodynamic drying over resistive heating.
Market Restraints
- Steel and copper input volatility:Drum assemblies and motor windings face raw material cost swings that compress OEM margin structures.
- Compressor supply concentration:Heat-pump dryer adoption depends on captive or contracted rotary compressor capacity concentrated among Asian component suppliers.
- Top-load agitator obsolescence:Conventional platform engineering amortization is truncated by DOE efficiency rules that disadvantage legacy mechanical designs.
Strategic Opportunities
- Smart home ecosystem integration:Connected appliance platforms enable utility demand-response revenue streams and predictive maintenance subscription models.
- Commercial fleet electrification:Coin-op and multi-housing laundry operators face regulatory pressure to replace gas dryers with heat-pump systems.
- State-level rebate program expansion:California and New York utility incentives increasingly cover heat-pump dryer retrofits in existing housing stock.
Industry Challenges
- Heat-pump service technician scarcity:Refrigeration-cycle diagnostics and sealed-system repair skills lag behind residential appliance installer training pipelines.
- Dual certification timelines:DOE compliance testing and CPSC safety validation create sequential bottlenecks for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Laundry Appliances Market |
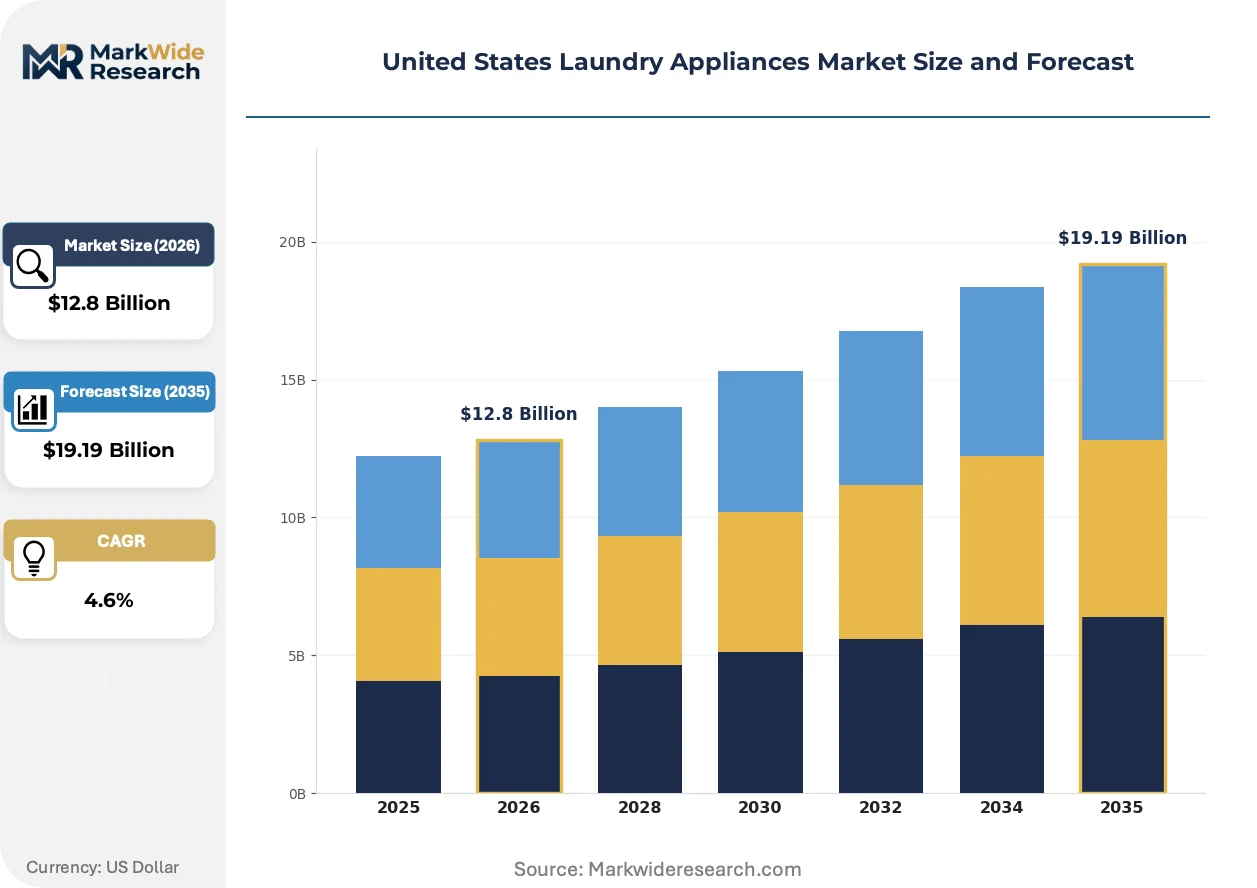
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Portable Washers Technology: Smart Appliances, Energy Efficient, Steam Technology, Conventional End User: Households, Commercial Laundries, Hotels, Hospitals Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | GE Appliances, Alliance Laundry Systems, Whirlpool Corporation, Miele USA, BSH Home Appliances, LG Electronics USA, Electrolux, Haier US, Samsung Electronics America, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Laundry Appliances Market Evolving Landscape
Connected appliance architectures and thermodynamic drying systems are compressing traditional product lifecycles while opening new revenue channels through utility integration and predictive service models.
Inverter motor platforms are decentralizing mechanical control from centralized drive systems to distributed electronic commutation. Multi-family housing developers and premium residential builders specify these systems for noise reduction and energy code compliance. The technology is decentralizing service revenue from emergency repair toward predictive maintenance subscriptions.
EPA's evolving ENERGY STAR criteria are tightening water factor thresholds that penalize conventional top-load agitator designs. Manufacturers must retool stamping and assembly lines toward front-load drum architectures. Residential replacement demand in California and Texas responds most acutely to these certification-driven assortment shifts.
Utility demand-response programs are reshaping how appliances participate in grid balancing. Smart washers and dryers in Texas and California markets now receive real-time price signals that delay cycle starts during peak load events. This behavioral adaptation is most visible among multi-family property managers seeking operating cost reduction through automated load shifting.
United States Laundry Appliances Market Segmentation
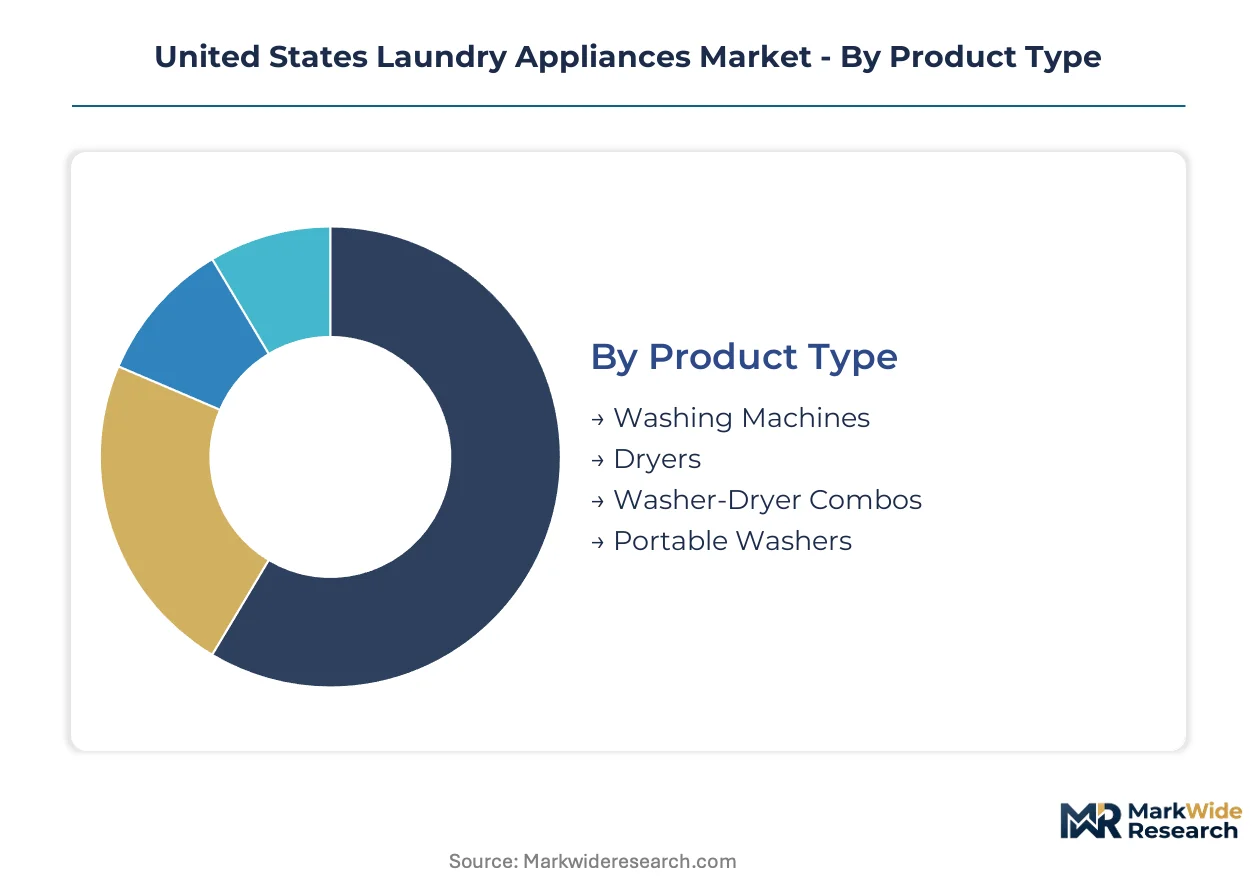
Segmentation in United States laundry appliances reveals divergent margin structures across residential replacement cycles and commercial fleet amortization. Product architecture choices cascade through technology adoption curves and channel economics, reshaping how manufacturers allocate engineering resources and inventory positions.
Product Type:
Washing machines anchor unit volume while heat-pump dryers command expanding margin pools under tightening DOE efficiency thresholds.
- Washing Machines:Front-load drum architectures with inverter motor platforms displace conventional agitator designs as EPA water factor rules tighten. Demand concentrates in Texas and California where multi-family housing construction and replacement cycles remain elevated.
- Dryers:Heat-pump thermodynamic systems using rotary compressors replace resistive heating elements under state electrification mandates. Utility rebate programs in California and New York accelerate residential adoption beyond code-minimum compliance.
- Washer-Dryer Combos:Compact all-in-one units serve space-constrained urban apartments and recreational vehicle installations.
- Portable Washers:120V countertop and wheeled units address rental housing restrictions on permanent appliance installation.
Mature deployment sits with washing machines. Newer deployment is concentrated in dryers.
Technology:
Certification tiers separate premium positioning from commodity replacement demand.
- Smart Appliances:Connected platforms integrate Wi-Fi modules and cloud diagnostics for remote cycle control and predictive maintenance subscriptions. Texas and California multi-family property managers adopt automated load-shifting to capture utility demand-response revenue.
- Energy Efficient:ENERGY STAR-qualified systems meeting EPA water factor and modified energy factor thresholds dominate replacement assortment in regulated markets.
- Steam Technology:In-drum steam injection cycles reduce wrinkling and sanitize without high-temperature water heating.
- Conventional:Mechanical timer-based controls persist in rental housing and budget replacement segments.
Energy efficient systems carry the steepest expansion trajectory as certification thresholds tighten.
End User:
Amortization schedules and regulatory pressure differentiate fleet procurement from household replacement.
- Households:Single-family and multi-family residential units drive replacement demand through product failure and kitchen renovation cycles. California and Texas housing markets sustain above-average turnover rates.
- Commercial Laundries:Coin-operated and card-operated fleet operators face compressed margins from utility rate structures and gas-to-electric conversion mandates.
- Hotels:On-premise laundry operations balance linen throughput requirements against noise and space constraints in urban properties.
- Hospitals:Infection control protocols demand thermal sanitization cycles and barrier-separated clean-soiled workflows.
Commercial laundries show the fastest technology migration under regulatory pressure.
Distribution Channel:
Channel selection reflects purchase urgency, installation complexity, and warranty service requirements.
- Online Retail:E-commerce platforms capture replacement demand from informed consumers comparing ENERGY STAR ratings and delivery windows. Major appliances require white-glove installation coordination.
- Brick-and-Mortar Stores:Big-box and independent dealers sustain showroom traffic through tactile evaluation of drum capacity and cycle noise. Texas and California markets retain strong regional appliance chains.
- Wholesale Distributors:Multi-housing and commercial laundry operators procure through contractor channels tied to new construction and renovation projects.
- Direct Sales:Manufacturer-owned stores and builder programs serve new construction specifications and volume replacement contracts.
Brick-and-mortar stores retain mature household penetration. Online retail is expanding most quickly in replacement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and Florida metropolitan areas concentrate multi-family housing development capital, accelerating in-unit laundry specification rates above national baselines. State-level electrification mandates and utility rebate programs in California and New York reshape replacement demand toward heat-pump architectures. Regional manufacturing clusters in the Midwest and Southeast sustain domestic production capacity against import volatility.
California
California's Title 24 Building Energy Efficiency Standards mandate heat-pump readiness in new residential construction, pulling forward dryer replacement cycles in Los Angeles and San Diego metro areas. The California Energy Commission administers TECH Clean California rebates covering heat-pump dryer retrofits in existing housing stock. Silicon Valley smart-home integration clusters drive connected appliance adoption among premium residential developers.
Texas
Texas leads national multi-family housing permits, with Dallas-Fort Worth and Houston developers specifying in-unit laundry at rates exceeding 85% in Class A properties. ERCOT demand-response programs enable smart appliance load-shifting revenue streams for property managers. The Dallas-Fort Worth metro anchors a distribution hub serving Southwest and Southeast replacement markets.
Florida
Florida's rapid population growth sustains above-average appliance turnover in Tampa and Orlando metropolitan statistical areas. The Florida Building Code adopts IECC 2021 efficiency baselines that disadvantage conventional top-load washer specifications. Miami-Dade County's hurricane-resistant construction standards accelerate replacement demand following storm-damage events.
New York
New York's Local Law 97 carbon emissions caps pressure multi-housing laundry operators toward electrified drying systems in New York City five-borough concentration. NYSERDA Clean Heat program rebates reduce heat-pump dryer acquisition costs for co-op and condo boards. Upstate manufacturing heritage in Rochester and Syracuse sustains service technician training pipelines.
Illinois
Illinois combines Midwest distribution centrality with Chicago metro multi-family density supporting commercial laundry fleet operations. The Illinois Commerce Commission oversees utility rebate programs targeting residential efficiency upgrades in Cook County. Rockford and Peoria industrial corridors host component stamping and motor winding suppliers serving domestic OEM assembly.
United States Laundry Appliances Market Competitive Landscape
Domestic producers anchor volume manufacturing tier; European and Asian specialists hold premium positioning through technology differentiation. The vendor structure concentrates among integrated appliance conglomerates with captive component production, mid-scale commercial laundry specialists, and electronics-platform entrants leveraging connected-home ecosystems. Two strategic archetypes dominate: vertically integrated full-line manufacturers controlling compressor and control board supply, and ecosystem-platform players monetizing software services atop hardware margins. Capacity consolidation and strategic partnerships represent the primary competitive vectors reshaping market access.
Among domestic-anchored manufacturers, Whirlpool Corporation exemplifies the vertically integrated archetype through its Benton Harbor manufacturing base and captive supply chain control. GE Appliances occupies a parallel position with backward integration into compressor production. Samsung Electronics America represents the ecosystem-platform archetype, leveraging connected appliance architectures to capture utility demand-response revenue streams. These three anchors illustrate how scale manufacturing and digital service layers compete for margin capture across replacement and new construction channels.
| Leading Market Players |
|---|
| GE Appliances |
| Alliance Laundry Systems |
| Whirlpool Corporation |
| Miele USA |
| BSH Home Appliances |
| LG Electronics USA |
| Electrolux |
| Haier US |
| Samsung Electronics America |
| Others |
Value Network & Pricing Analysis
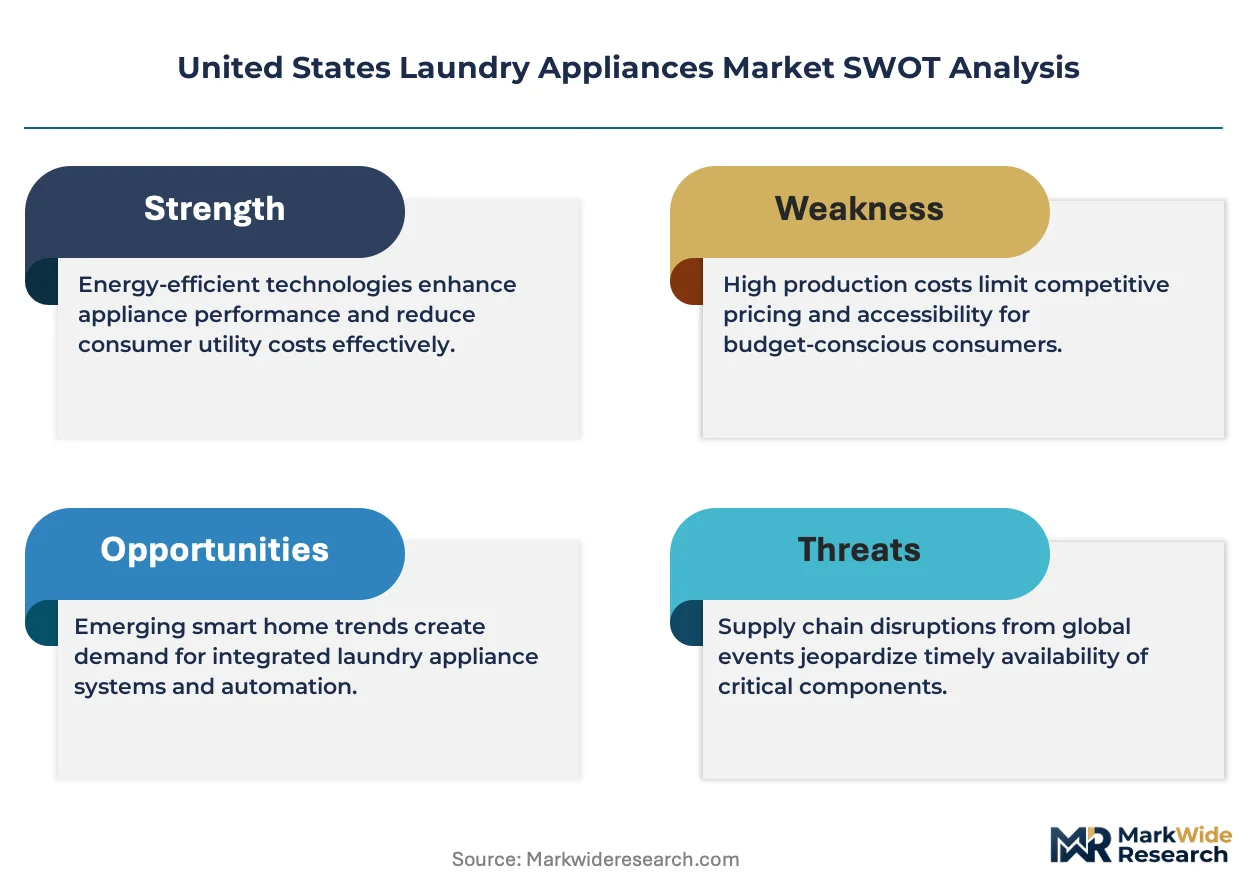
ENERGY STAR certification tiers split the United States laundry appliances landscape into parallel pricing and sourcing tracks. Premium front-load washers with heat-pump dryers command supplier investment in inverter motor and rotary compressor capacity, while conventional agitator platforms face margin compression from DOE efficiency mandates and raw material volatility.
Pricing Analysis
Short lead-time premiums reward distributors holding heat-pump dryer inventory in California and Texas markets facing electrification retrofit deadlines. Three-tier pricing structure across premium connected systems, standard ENERGY STAR-qualified units, and economy mechanical-timer models reflects certification grade and after-sales service bundling. Pricing pressure stems from steel and copper input volatility compressing OEM margins on drum assemblies and motor windings. Multi-family property managers in ERCOT-served Texas markets show least price sensitivity given demand-response revenue offsets, while budget replacement segments in Florida rental housing exhibit highest elasticity.
Supply Chain Analysis
Rotary compressor supply for heat-pump dryers rests on South Korean and Chinese specialty component producers with limited alternative sourcing. Steel sheet from domestic Midwest mills, copper winding wire from Chilean concentrate, and injection-molded control housings from Mexican maquiladoras constitute core material dependencies. Single-source vulnerability concentrates in Asian compressor capacity as OEMs convert residential dryer lines from resistive heating. Distribution runs through big-box retail showrooms in Texas and California, wholesale contractor channels for multi-housing new construction, and direct builder programs capturing new development specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States laundry appliances market operates as a cost-of-compliance arena where DOE energy conservation standards erect barrier-to-entry moats favoring manufacturers with captive inverter motor and heat-pump technology platforms.
For Market Incumbents: Cement control over rotary compressor supply through backward integration or long-term offtake agreements with South Korean suppliers. Expand Benton Harbor and Midwest manufacturing footprints to shield against tariff exposure on Asian component imports. Defend against ecosystem-platform entrants by embedding predictive maintenance subscriptions into connected appliance base.
For New Entrants and Emerging Players: Regional appliance chains in Texas and Florida offer channel partnership pathways around big-box concentration. Target commercial laundry fleet operators in New York City facing Local Law 97 electrification mandates with heat-pump dryer retrofit packages. Pursue white-glove installation service bundling as differentiation against established OEM direct channels.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap manufacturers given TECH Clean California and NYSERDA rebate program expansion catalyzing heat-pump adoption curves. Long-term viability favors players with in-house compressor production and smart home platform integration capabilities. Watch ERCOT demand-response enrollment rates and utility rebate program renewal cycles as inflection signals for connected appliance monetization.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Dryer Platform Conversion | DOE efficiency thresholds and California Title 24 mandates accelerate residential and commercial fleet migration from resistive heating. |
| Smart Home Ecosystem Integration | Wi-Fi-enabled load-shifting capabilities capture ERCOT and California utility demand-response revenue streams for property managers. |
| Rotary Compressor Supply Securement | Captive or contracted capacity with South Korean and Chinese suppliers mitigates single-source risk as OEMs convert dryer architectures. |
| Predictive Maintenance Subscription Launch | Cloud diagnostics and remote cycle control transform service revenue from emergency repair toward recurring software monetization. |
| Multi-Family Direct Sales Channel Expansion | Builder program relationships with Texas and Florida developers capture in-unit laundry specification rates exceeding national baselines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this United States laundry appliances analysis. Primary interviews with OEM product strategy directors, multi-family property managers, commercial laundry fleet operators, and utility demand-response program administrators combined with AHAM shipment statistics, DOE compliance certification databases, and EPA ENERGY STAR qualified product listings. Bottom-up unit shipment modeling and top-down value reconciliation triangulated market size estimates.
Reconciliation of AHAM manufacturer shipment data, Census Bureau appliance store sales reports, and utility rebate program participation records grounded the analytical framework. Segmentation dimensions spanned product architecture, technology tier, end-user amortization schedule, and distribution channel economics across the projection horizon. CAGRs derived from housing starts correlation, replacement cycle elasticity, and efficiency regulation phase-in schedules. Heat-pump adoption curves and smart appliance penetration rates served as industry-specific forecast inputs.
Caveats apply where DOE rulemaking delays, steel tariff modifications, or compressor supply disruptions could materially shift the outlook. Forecasts reflect assumptions around multi-family construction permit sustainability and utility incentive program continuity. A small set of triggers—Title 24 amendment timing, NYSERDA rebate renewal cycles, and ERCOT market redesign outcomes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Germany Home Appliances Market
Home Appliances
South Korea Small Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
Oman Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
Electric Household Appliances Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
UAE Small Home Appliances Market