
 India Laundry Appliances Market | 2026-2036
India Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
India Laundry Appliances Market Foresight
Market Context
Product bundling of washing machines with extended warranty and detergent subscription is shifting buyer choice toward total-cost-of-ownership models in metro India. LG Electronics India Pvt Ltd leverages its inverter direct-drive technology to sustain premium positioning in front-load segments. Whirlpool of India Ltd anchors its competitive stance through deep distribution in Tier-2 and Tier-3 towns. Godrej & Boyce Mfg Co Ltd differentiates via India-specific drum designs suited to lower water pressure conditions.
Technical and Segment Structure
India laundry appliances comprise electromechanical systems for fabric cleaning and drying, incorporating stainless-steel drums, BLDC motors rated at 1,200-1,400 RPM spin speeds, and IoT-enabled load-sensing controllers for water and energy optimization. Front-load technology leads in urban replacement cycles while fully automatic top-load variants represent the fastest-growing installed base expansion. Commercial laundromats and hospital end-user segments concentrate margin pools through bulk-capacity procurement and service-contract attachments.
Regulatory Environment and Outlook
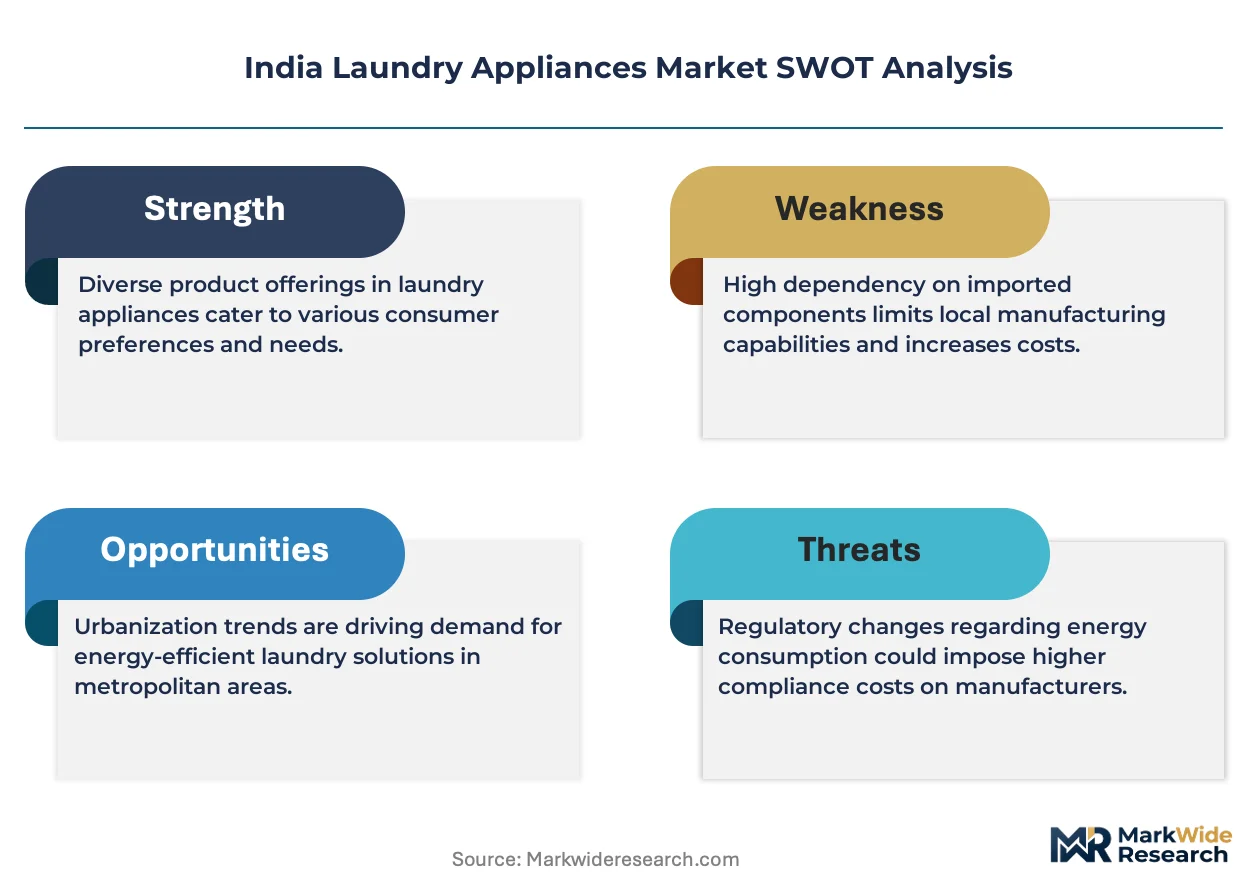
BIS mandatory energy-labeling standards and the Bureau of Energy Efficiency's star-rating program shape product design thresholds and import compliance costs for manufacturers. The PLI scheme for white goods and state-level RERA housing regulations indirectly accelerate appliance penetration in new residential stock. Stakeholders must monitor how BIS testing protocol revisions and state electricity board tariff structures alter total-cost calculations for inverter-equipped versus conventional motor platforms.
Market Dynamics
Inverter motor technology penetration across mid-tier price bands is compressing replacement cycles and forcing manufacturers to reconfigure supply chains around BLDC motor sourcing from Gujarat and Tamil Nadu component clusters.
Growth Catalysts
- BIS Energy-Efficiency Mandates:Mandatory star-rating thresholds for washing machines are phasing out conventional motor platforms and redirecting R&D budgets toward inverter-compatible control systems.
- Urban Housing Stock Expansion:RERA-regulated residential projects in Maharashtra and Karnataka are pre-installing fully automatic units, creating captive demand for front-load configurations.
- Commercial Laundromat Proliferation:Bulk-capacity procurement from hospital and hospitality end-users is concentrating margin pools in 10-15 kg segment machines with service-contract attachments.
Market Restraints
- Copper and Cold-Rolled Steel Volatility:Input cost swings for drum and motor housing materials compress assembler margins during price-lock periods with large-format retailers.
- Import Dependency for BLDC Controllers:Concentration of semiconductor sourcing from East Asian suppliers exposes assemblers to customs clearance friction and forex fluctuation.
- Water Pressure Variability:Technical limitation in rural and peri-urban distribution zones restricts deployment of sensor-heavy front-load platforms without pressure-pump retrofits.
Strategic Opportunities
- Tier-3 and Tier-4 Town Penetration:Underpenetrated districts in Uttar Pradesh and Bihar present white space for semi-automatic to fully automatic upgrade campaigns with localized financing.
- PLI Scheme for White Goods:Production-linked incentive thresholds for component localization are creating captive supply opportunities for drum and motor housing manufacturers.
- IoT-Enabled Predictive Maintenance:Convergence of load-sensing controllers with mobile-app diagnostics is opening subscription revenue streams for service bundling.
Industry Challenges
- Field Technician Skill Gaps:Shortage of trained personnel for inverter motor diagnostics and IoT controller troubleshooting extends mean-time-to-repair in remote service territories.
- BIS Testing Protocol Revisions:Compliance timeline compression for updated energy-labeling standards strains certification pipelines and delays new model launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Laundry Appliances Market |
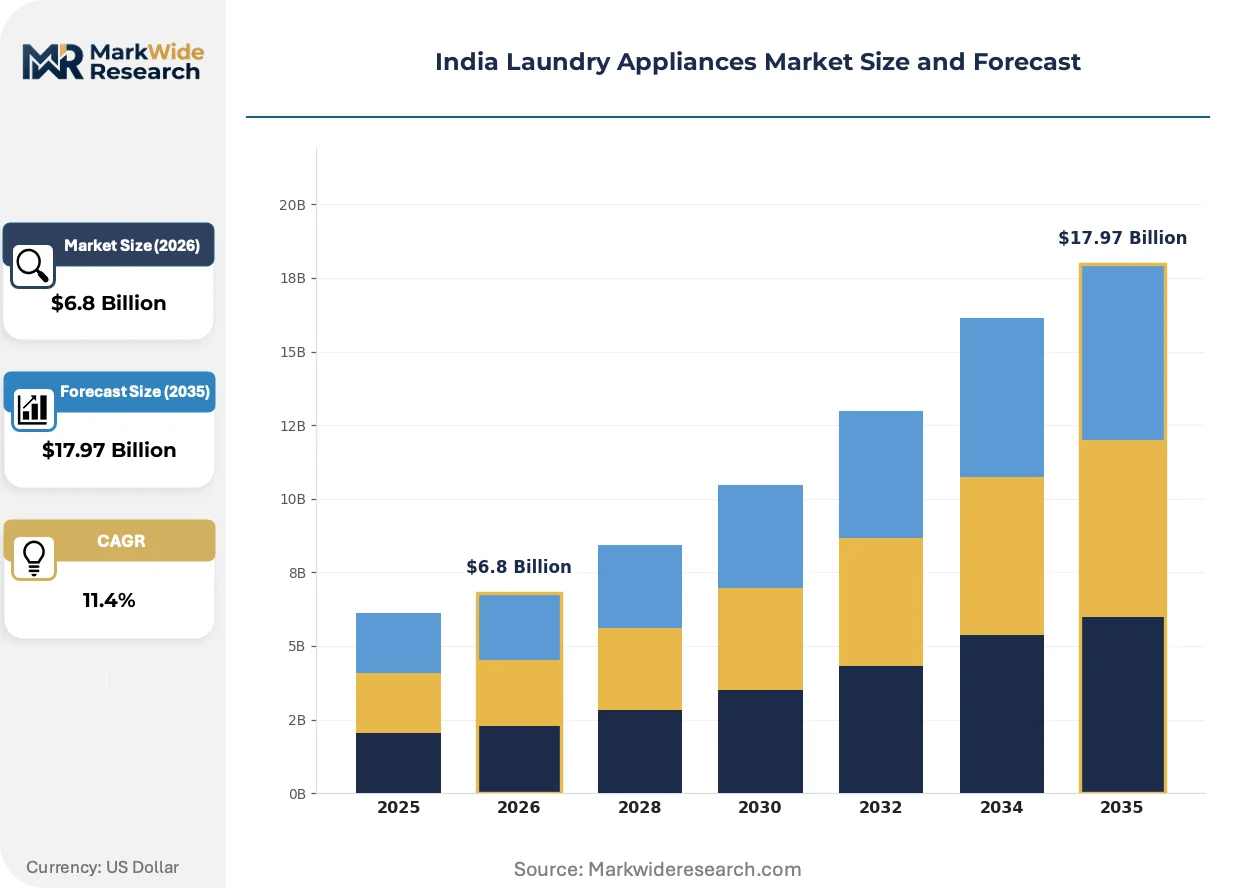
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Steam Iron End User: Residential, Commercial Laundromats, Hotels, Hospitals Technology: Front Load, Top Load, Semi-Automatic, Fully Automatic Capacity: 6-7 Kg, 8-9 Kg, Above 10 Kg, Below 6 Kg |
| Companies Covered | IFB Industries Ltd, Haier Appliances India Pvt Ltd, LG Electronics India Pvt Ltd, Panasonic Home Appliances India Co Ltd, Godrej & Boyce Mfg Co Ltd, Samsung India Electronics Pvt Ltd, Bosch, Electrolux AB, Whirlpool of India Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Laundry Appliances Market Shifts & Advancements
Product architecture in India laundry appliances is pivoting from standalone hardware sales toward integrated ownership ecosystems where hardware, consumables, and service contracts bundle into recurring revenue relationships.
BLDC inverter motor technology is converging with AI-driven load-sensing controllers to optimize water and energy draw per cycle. Urban apartment buyers in Mumbai and Bengaluru are specifying these configurations in replacement purchases. The technology convergence is compressing price premiums between mid-tier and entry-premium segments.
Bureau of Energy Efficiency star-rating program revisions are tightening mandatory efficiency thresholds for washing machine imports and domestic production. Manufacturers are reconfiguring product portfolios to meet 4-star and 5-star minimums ahead of compliance deadlines. Front-load segments in Maharashtra and Gujarat distribution networks are absorbing the fastest certification-driven model turnover.
Appliance-as-a-service bundling is displacing outright purchase in commercial end-use verticals. Hospital and hospitality procurement teams in Delhi-NCR and Bengaluru are shifting from capital expenditure to per-wash contracting with maintenance-inclusive terms. This behavior shift is most visible in 10 kg and above capacity segments where uptime guarantees dominate vendor selection.
India Laundry Appliances Market Segmentation
Segmentation in India laundry appliances reveals how purchasing decisions split between urban efficiency-seekers and cost-conscious rural upgraders. Understanding these divides helps manufacturers align inverter motor investments with the right capacity tiers and distribution channels.
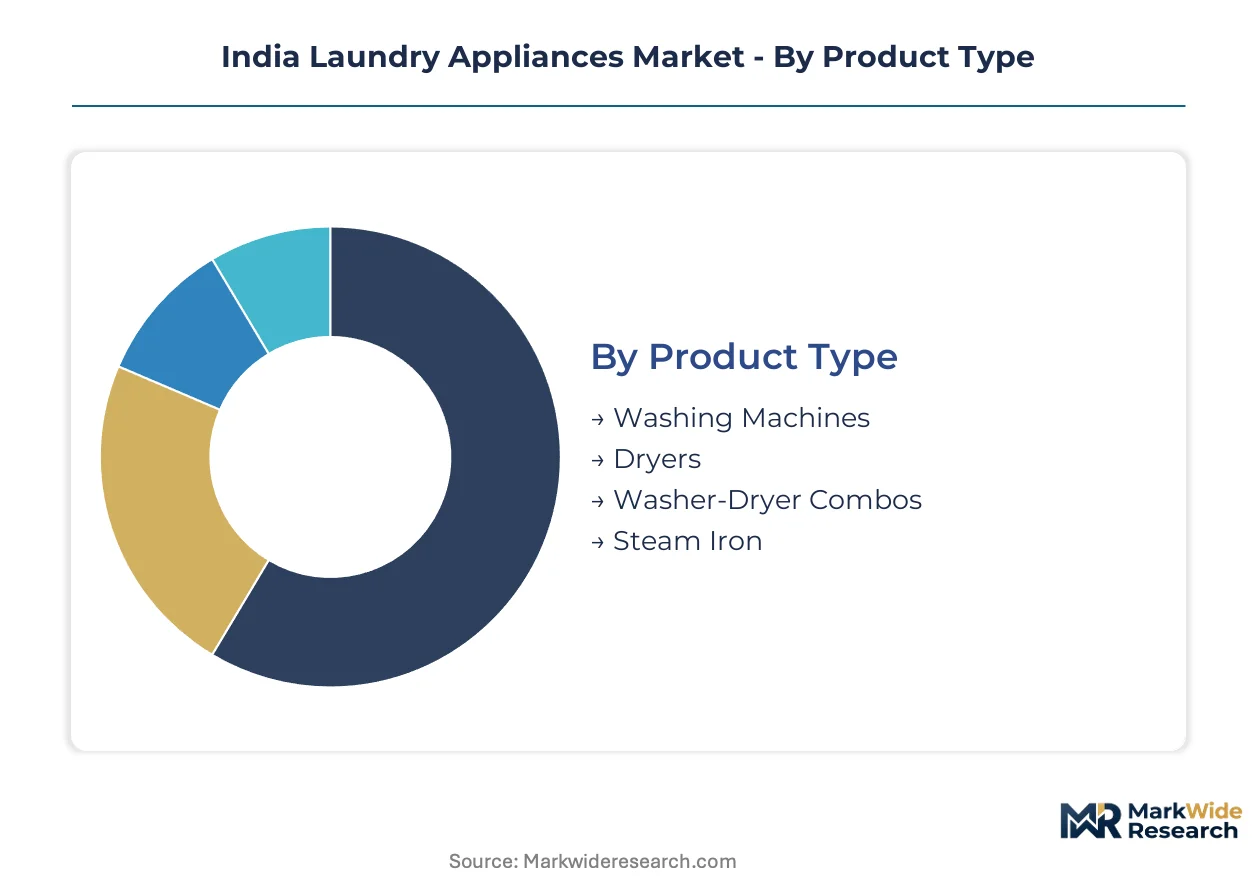
Product Type:
Buyers in this category differentiate by whether they prioritize standalone washing performance or integrated fabric care ecosystems.
- Washing Machines:Stainless-steel drum configurations with BLDC inverter motors rated at 1,200-1,400 RPM dominate urban replacement cycles in Maharashtra and Gujarat. BIS energy-efficiency mandates are phasing out conventional motor platforms and redirecting R&D budgets toward inverter-compatible control systems.
- Dryers:Heat-pump and condenser technologies remain niche in India due to electricity tariff sensitivity, though monsoon-season demand in Mumbai and Bengaluru is expanding adoption among apartment dwellers lacking drying balconies. RERA-regulated residential projects are beginning to specify venting infrastructure.
- Washer-Dryer Combos:Space-constrained urban buyers in Delhi-NCR accept longer cycle times for footprint reduction. Water pressure variability in peri-urban zones restricts deployment without pressure-pump retrofits.
- Steam Iron:Garment care adjuncts sold through appliance retail bundling in Tier-2 and Tier-3 towns.
Volume sits with Washing Machines; growth tilts toward Dryers.
End User:
Procurement authority in this category ranges from household decision-makers to facilities managers with uptime guarantee requirements.
- Residential:Individual households upgrading from semi-automatic to fully automatic platforms drive the largest unit volumes. Financing schemes and extended warranty bundling are shifting buyer choice toward total-cost-of-ownership models in metro India.
- Commercial Laundromats:Bulk-capacity procurement concentrates margin pools in 10-15 kg segment machines with service-contract attachments. Hospital and hospitality procurement teams in Delhi-NCR and Bengaluru are shifting from capital expenditure to per-wash contracting.
- Hotels:Linen throughput requirements demand industrial-grade front-load configurations with IoT-enabled predictive maintenance subscriptions.
- Hospitals:Infection control protocols specify high-temperature wash cycles and stainless-steel drum sanitation features.
Residential captures unit volume; Commercial Laundromats command premium pricing power.
Technology:
Technical sophistication in this category separates buyers by water access, electricity reliability, and space constraints.
- Front Load:Horizontal-axis drum designs with gravity-fed water systems achieve superior BIS star ratings. Urban apartment buyers in Mumbai and Bengaluru specify these configurations in replacement purchases as inverter motor technology compresses price premiums between mid-tier and entry-premium segments.
- Top Load:Vertical-axis designs with agitator or impeller mechanisms dominate fully automatic installed base expansion. Godrej & Boyce Mfg Co Ltd differentiates via India-specific drum designs suited to lower water pressure conditions.
- Semi-Automatic:Twin-tub configurations persist in underpenetrated districts of Uttar Pradesh and Bihar where localized financing enables upgrade campaigns.
- Fully Automatic:Single-tub operation with microprocessor-controlled cycles represents the steepest expansion trajectory as housing stock expansion in Karnataka and Maharashtra pre-installs these units.
Semi-Automatic holds residual volume; Fully Automatic climbs the fastest.
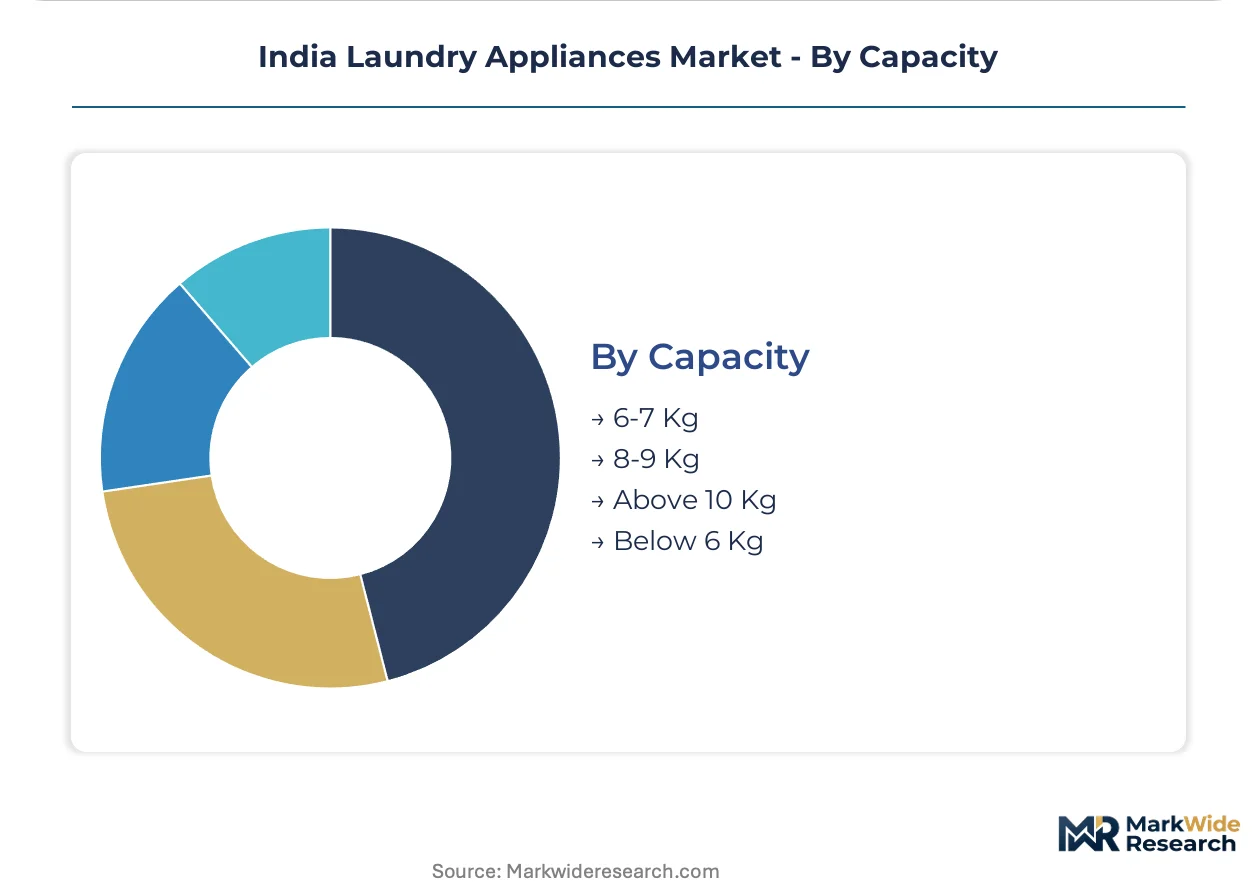
Capacity:
Household size and commercial throughput requirements in this category map directly to drum volume specifications.
- 6-7 Kg:Standard nuclear family configurations dominate urban replacement cycles. LG Electronics India Pvt Ltd leverages inverter direct-drive technology to sustain premium positioning in this front-load segment.
- 8-9 Kg:Extended family and dual-income households in Tier-2 towns are expanding this tier as fully automatic top-load variants penetrate deeper distribution networks.
- Above 10 Kg:Commercial laundromat and hospital procurement concentrates bulk-capacity margin pools. Uptime guarantees dominate vendor selection in Delhi-NCR and Bengaluru.
- Below 6 Kg:Compact configurations for single-person households and space-constrained Mumbai apartments.
6-7 Kg maintains installed base dominance; Above 10 Kg gains share fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate manufacturing capacity for BLDC motor components and stainless-steel drum fabrication. BIS energy-efficiency mandates and state-level RERA housing regulations create divergent demand patterns across India's major industrial corridors.
Maharashtra
Mumbai's apartment densification drives replacement demand for front-load configurations with inverter direct-drive systems. The state's RERA-registered residential projects mandate pre-installed fully automatic units in new housing stock. Pune and Nashik industrial clusters host drum and motor housing component suppliers serving western India distribution networks.
Gujarat
Surat and Ahmedabad manufacturing zones anchor BLDC motor production for mid-tier price band penetration. The state's PLI scheme for white goods component localization attracts drum fabricators and controller assembly operations. Vadodara's engineering base supplies pressure-pump retrofits for water-variable deployment zones.
Karnataka
Bengaluru's tech workforce replacement cycles favor IoT-enabled load-sensing controllers with mobile-app diagnostics. The state's electricity board tariff structures incentivize 4-star and 5-star BIS certified models in urban replacement purchases. Mysuru and Hubli-Dharwad distribution hubs extend fully automatic penetration into Tier-2 towns.
Tamil Nadu
Chennai's commercial laundromat proliferation concentrates bulk-capacity procurement from hospital and hospitality verticals. The state's component manufacturing ecosystem supplies semiconductor-dependent BLDC controllers to assemblers nationwide. Coimbatore's industrial engineering base fabricates heat-pump dryer subassemblies for monsoon-season demand pockets.
Delhi-NCR
The capital region's hospital procurement teams shift from capital expenditure to per-wash contracting with maintenance-inclusive terms. Haryana's warehousing and logistics infrastructure supports northern India distribution for 10-15 kg commercial segment machines. Noida's service technician training centers address field diagnostic skill gaps for inverter motor platforms.
India Laundry Appliances Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price bands in India's laundry appliance sector. Market structure consolidates around three to four dominant assemblers with captive distribution networks, while component suppliers fragment across Gujarat and Tamil Nadu manufacturing clusters. Strategic archetypes separate inverter technology licensors from drum design specialists and commercial service-contract integrators. Competitive moves concentrate on backward integration into motor controller sourcing and geographic expansion through Tier-3 town financing partnerships.
Among India-based manufacturers, Godrej & Boyce Mfg Co Ltd and Whirlpool of India Ltd occupy positions in the mid-tier and mass-market vectors respectively. LG Electronics India Pvt Ltd exemplifies the premium-tier archetype through sustained inverter direct-drive positioning. These three entities represent distinct strategic postures: localized engineering adaptation, deep distribution penetration, and technology-forward urban targeting.
| Leading Market Players |
|---|
| IFB Industries Ltd |
| Haier Appliances India Pvt Ltd |
| LG Electronics India Pvt Ltd |
| Panasonic Home Appliances India Co Ltd |
| Godrej & Boyce Mfg Co Ltd |
| Samsung India Electronics Pvt Ltd |
| Bosch |
| Electrolux AB |
| Whirlpool of India Ltd |
| Others |
Supply & Pricing Matrix
BIS energy-efficiency mandates gate both qualified supply and premium-tier pricing access, as star-rating compliance costs filter out low-efficiency assemblers while concentrating margin pools among inverter motor-certified manufacturers serving Maharashtra and Gujarat distribution networks.
Pricing Analysis
Margin tightening in mid-tier price bands reflects copper and cold-rolled steel volatility compressing assembler margins during price-lock periods with large-format retailers. Three-tier pricing structure across premium, standard, and economy levels separates BIS 5-star certified inverter models from 3-star conventional motor platforms and semi-automatic entry units. Cost-down pressure on standard-tier SKUs accelerates because import dependency for BLDC controllers exposes assemblers to customs clearance friction and forex fluctuation. Commercial laundromat buyers exhibit lowest price sensitivity due to per-wash contracting models, while rural residential upgraders in Uttar Pradesh and Bihar remain most price-sensitive.
Supply Chain Analysis
Refurbishment flows for drum and motor housing components from warranty returns feed secondary parts markets in Tamil Nadu and Gujarat manufacturing zones. Component sourcing concentrates in India, China, and South Korea for BLDC controllers, stainless-steel drum fabrication, and inverter motor subassemblies. Raw material dependencies on copper windings, cold-rolled steel sheets, and semiconductor-grade silicon create exposure to commodity price volatility and single-source vulnerability for controller ICs. Distribution runs through company-owned service networks and large-format retail partnerships anchored in Mumbai, Bengaluru, and Delhi-NCR.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's laundry appliance sector sits in a technology-transition phase where BLDC inverter motor platforms displace conventional motor architectures across mid-tier and premium price bands.
For Market Incumbents: Deepen captive supply of motor controllers through backward integration into Gujarat and Tamil Nadu component clusters to defend against import-dependency risks and BIS compliance timeline compression. Anchor premium positioning through sustained inverter direct-drive R&D investment while locking Tier-2 and Tier-3 distribution through localized financing partnerships that delay emerging entrant access. For New Entrants and Emerging Players: IoT-enabled predictive maintenance subscriptions offer a technology-first wedge into commercial laundromat and hospital procurement segments where uptime guarantees dominate vendor selection. Target underpenetrated districts in Bihar and eastern Uttar Pradesh for semi-automatic to fully automatic upgrade campaigns with regional language service networks and pressure-pump retrofit bundling. For Investors and Strategic Acquirers: PLI scheme threshold achievements for component localization are the leading indicator that captive supply economics will separate viable assemblers from import-dependent competitors over the medium-term horizon. Acquire drum fabricators and motor housing specialists with established BIS certification pipelines rather than distribution-heavy assemblers exposed to retail price-lock risks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BLDC Controller Sourcing | Reduces exposure to East Asian semiconductor supply disruptions and customs friction. |
| IoT-Enabled Predictive Maintenance Platform Launch | Opens recurring subscription revenue streams from hospital and hospitality procurement teams. |
| Tier-3 Town Financing Partnership Expansion | Captures semi-automatic upgrade demand in Bihar and Uttar Pradesh ahead of competitor entry. |
| BIS 5-Star Certification Pipeline Investment | Ensures compliance with tightening mandatory efficiency thresholds ahead of protocol revisions. |
| Commercial Service-Contract Integration | Shifts revenue mix from transactional hardware sales to per-wash contracting with uptime guarantees. |
Research Methodology
Independent corroboration across primary interviews with product development engineers at leading assemblers, procurement managers at commercial laundromat chains, and BIS certification specialists underwrites the qualitative findings. Secondary validation draws from Bureau of Energy Efficiency star-rating databases, PLI scheme disclosure filings, and Maharashtra and Gujarat state industrial development records. Bottom-up demand modeling across residential, commercial laundromat, hospital, and hospitality end-use segments triangulates with top-down macroeconomic indicators for housing stock expansion and electricity tariff structures.
Rate-of-change decomposition across the analysis window segments growth by product type, technology tier, capacity band, and regional adoption pattern. CAGRs derive from installed base turnover assumptions, replacement cycle compression factors, and penetration rate trajectories in underpenetrated districts. Industry-specific forecast inputs incorporate BIS testing protocol revision timelines and state-level RERA housing registration data for pre-installation demand capture.
Several conditions sit outside the modeled scope, including unforeseen raw material price spikes beyond historical volatility bands, abrupt BIS compliance deadline accelerations, and geopolitical disruptions to semiconductor supply chains. Practitioners should monitor PLI localization threshold achievements, state electricity board tariff restructuring announcements, and field technician training pipeline expansion rates for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Home Appliances Glass Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Smart Home Connect Dishwasher Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
China Laundry Appliances Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
Germany Major Home Appliance Market
Home Appliances
Residential Cooker Hoods Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
US Household Appliances Market
Home Appliances
Oman Home Appliances Market
Home Appliances
Germany Home Appliances Market