
 South Africa Home Appliances Market | 2026-2036
South Africa Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Home Appliances Market Analytics
Multi-source procurement from Asian manufacturing hubs is broadening the supplier base for South African retailers. Defy anchors its position through backward integration into local assembly plants in Durban. Samsung competes on connected-home ecosystems, while Hisense leverages aggressive pricing to occupy the mid-range tier. Bosch differentiates through extended warranty programs and premium positioning in major urban centers.
Home appliances encompass electrically powered machines designed for domestic tasks including food preservation, textile cleaning, meal preparation, and surface sanitation, typically operating on 220-240V at 50Hz with energy efficiency ratings from A+++ to D under South African labeling requirements. Refrigerators command the largest product type share due to continuous operation needs and replacement cycles tied to compressor longevity. Washing machines represent the fastest-growing product type as water-scarce regions drive demand for low-consumption drum designs. The consumer segment splits sharply between urban households seeking smart-enabled units and rural households prioritizing durability over connectivity features.
The National Regulator for Compulsory Specifications (NRCS) enforces safety and energy standards under the Compulsory Specification for Energy Efficiency and Labelling of Electrical Appliances, while the South African Bureau of Standards (SABS) certifies electromagnetic compatibility and mechanical safety for imported goods. NERSA's tariff structures indirectly shape demand by influencing operating cost calculations among electricity-sensitive buyers. Stakeholders must monitor alignment between local content requirements under South Africa's industrial policy and the cost structures of fully imported finished goods.
Market Dynamics
Load-shedding intensity is restructuring South Africa's home appliances sector, forcing manufacturers to prioritize inverter-compatible compressor designs and dual-power refrigeration systems as baseline specifications rather than premium features.
Growth Catalysts
- NERSA efficiency mandates:Minimum energy performance standards for electrical appliances are accelerating replacement cycles among electricity-cost-sensitive households in Gauteng and the Western Cape.
- Water-scarce region design:Low-consumption drum technologies in washing machines are penetrating metropolitan Durban corridors where municipal water restrictions persist.
- Middle-income urbanization:Electrification rate convergence with income expansion in Johannesburg's peripheral townships is creating first-time appliance ownership demand.
Market Restraints
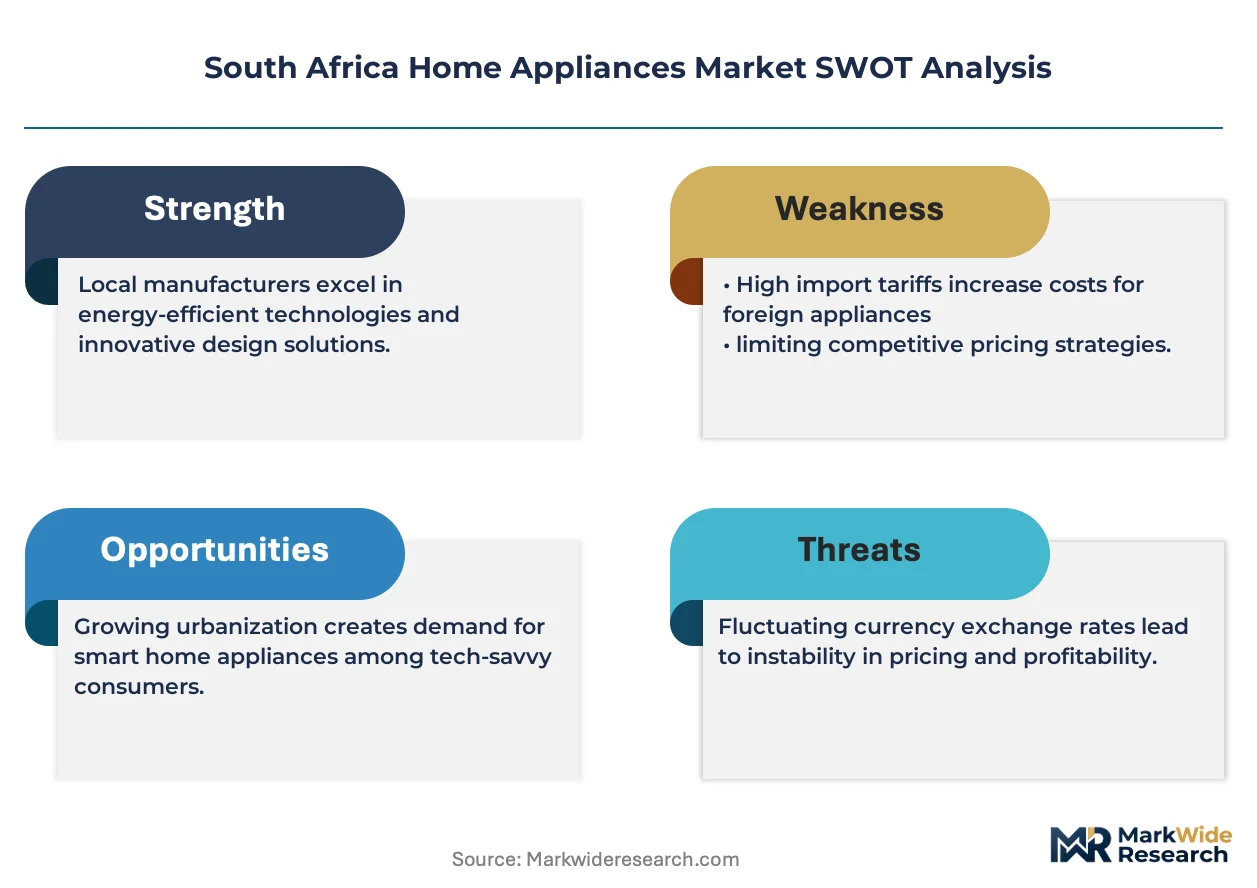
- Import tariff volatility:South Africa's industrial policy local content requirements create cost friction for fully imported finished goods, compressing margin structures for distributor networks.
- Currency-driven input cost instability:Rand weakness against Asian manufacturing hub currencies inflates landed costs for compressor and control module components.
- Grid reliability dependency:Eskom's generation capacity constraints limit addressable market expansion in rural electrification zones where backup power infrastructure remains absent.
Strategic Opportunities
- Solar-hybrid appliance integration:DC-native refrigeration and laundry systems compatible with residential photovoltaic installations are capturing early adoption in Western Cape off-grid housing developments.
- Rural durability-first positioning:Extended-warranty service networks targeting Limpopo and Eastern Cape provinces where repair infrastructure scarcity currently blocks premium product penetration.
- NRCS certification streamlining:Pre-approval alignment with the National Regulator for Compulsory Specifications' safety and electromagnetic compatibility protocols is reducing time-to-market for compliant manufacturers.
Industry Challenges
- Technician certification bottlenecks:SABS-qualified service personnel scarcity in secondary cities delays after-sales network expansion beyond Johannesburg, Cape Town, and Durban.
- Inventory financing compression:Working capital intensity for retailers holding rand-denominated stock against dollar-pegged supplier obligations strains distributor liquidity during depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Home Appliances Market |
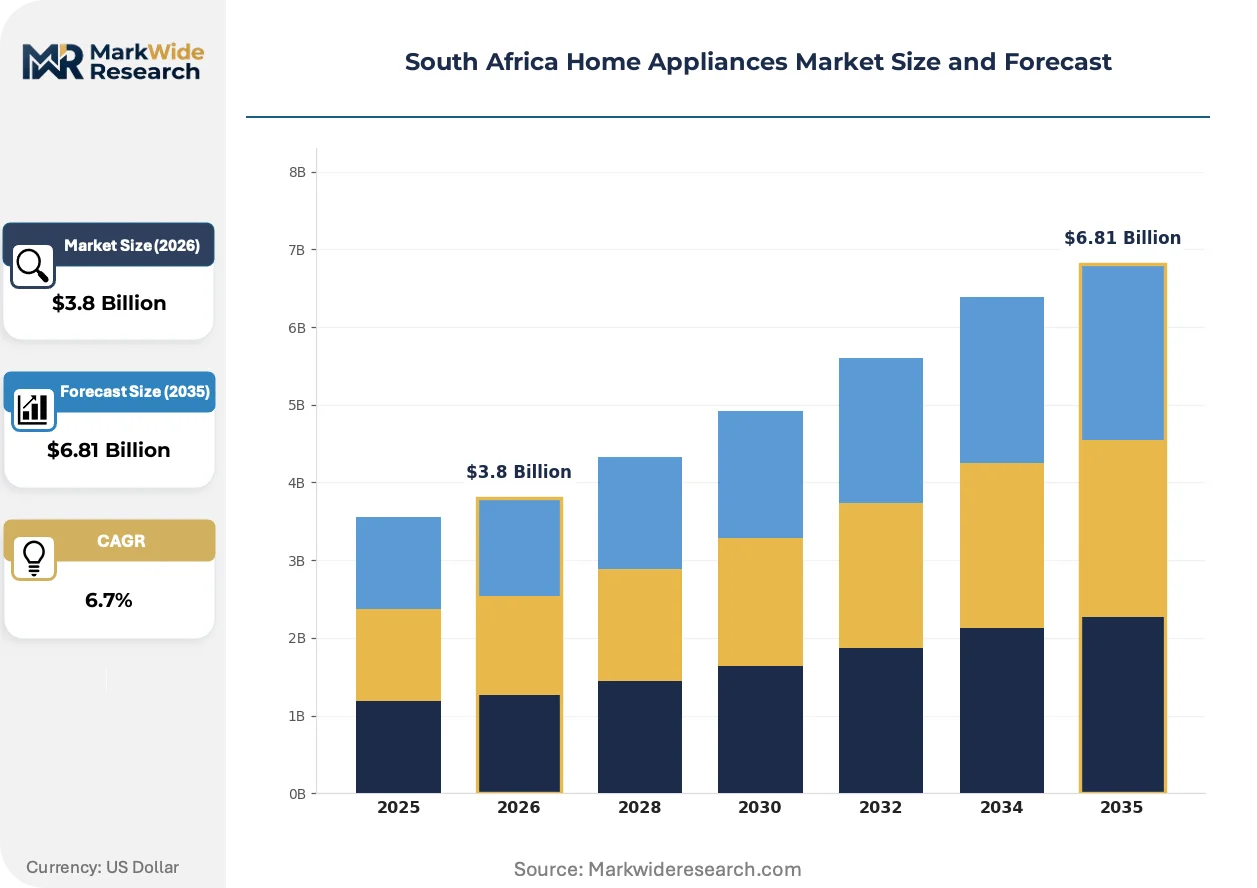
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Dishwashers Consumer Segment: Urban Households, Rural Households, High-Income Consumers, Middle-Income Consumers Brand Category: Premium Brands, Mid-Range Brands, Budget Brands, Local Brands Distribution Channel: Online Retailers, Department Stores, Specialty Stores, Wholesale Distributors |
| Companies Covered | Samsung, Smeg, Defy, Milex, Russell Hobbs, Hisense, Bosch, Haier, LG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Home Appliances Market Evolving Landscape
Domestic appliance functionality is bifurcating between connected-home ecosystems for urban middle-income households and ruggedized simplicity for grid-unreliable environments, with manufacturers now engineering distinct product architectures for each trajectory.
Inverter-driven compressor technology is rewriting refrigeration energy consumption profiles across South African metropolitan markets. Middle-income households in Cape Town's Atlantic Seaboard corridor are specifying variable-speed cooling systems as standard equipment. This capability compression is eliminating fixed-speed compressor inventory from premium retail channels within three years.
NERSA's tariff structure revisions are forcing recalibration of operating cost calculations among electricity-sensitive buyers. Industrial consequence flows through to manufacturer R&D prioritization, with energy efficiency ratings now dominating point-of-sale marketing materials. Low-consumption drum washing machine categories show the strongest demand response to these regulatory price signals.
Retailer procurement consolidation is concentrating volume leverage among Johannesburg-based distribution networks. Independent appliance stores in Durban's northern suburbs are ceding share to national chain direct-sourcing arrangements that bypass traditional wholesaler markups. This channel compression is most visible in refrigerator and washing machine categories where price transparency pressures margin structures.
South Africa Home Appliances Market Segmentation
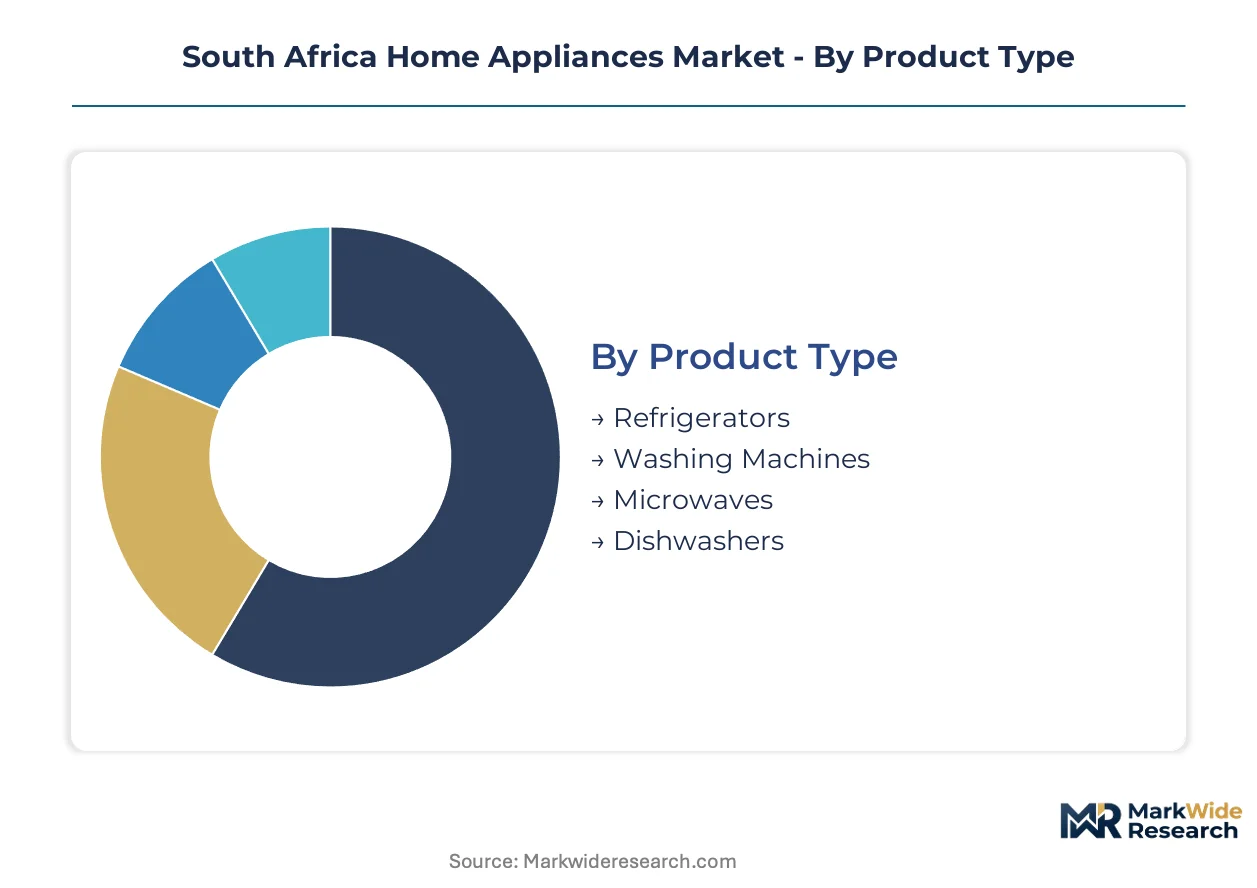
Home appliance demand in South Africa fractures along electrification reliability and income stratification lines. Manufacturers engineer divergent product architectures for grid-stable metropolitan corridors versus load-shedding-exposed peri-urban zones. Understanding these fault lines determines which specifications, pricing tiers, and channel strategies capture volume.
Product Type:
Integration depth varies sharply—refrigeration and laundry systems operate as standalone infrastructure investments, while cooking and cleaning appliances embed within broader kitchen ecosystems.
- Refrigerators:Continuous-operation compressor systems dominate household energy budgets and replacement cycles. Gauteng and Western Cape metropolitan buyers prioritize inverter-compatible variable-speed cooling as baseline specification. NERSA efficiency mandates are compressing fixed-speed inventory out of premium retail channels.
- Washing Machines:Low-consumption drum designs penetrate water-scarce Durban corridors where municipal restrictions persist. Front-loading configurations command price premiums for water efficiency, while top-loading units retain share in rural durability-first markets.
- Microwaves:Countertop units serve as entry-point electrification appliances in Johannesburg's peripheral townships.
- Dishwashers:Built-in configurations concentrate in Atlantic Seaboard high-income segments; freestanding units lag penetration due to water cost sensitivity.
Refrigerators lead volumes today; washing machines are gaining share fastest.
Consumer Segment:
Cost tier stratification determines specification trade-offs between connectivity features and ruggedized simplicity.
- Urban Households:Smart-enabled ecosystems and connected-home integration drive specification in Johannesburg, Cape Town, and Durban corridors. Middle-income expansion in metropolitan peripheries creates first-time ownership demand for energy-efficient refrigeration.
- Middle-Income Consumers:Operating cost calculations dominate purchase decisions as NERSA tariff structures reshape total cost of ownership math. This segment shows strongest demand response to efficiency rating marketing.
- Rural Households:Durability prioritization over connectivity features blocks premium product penetration where repair infrastructure scarcity persists.
- High-Income Consumers:Extended warranty programs and premium positioning concentrate in major urban centers with established service networks.
Urban households anchor current revenue; middle-income consumers show steepest expansion trajectory.
Brand Category:
Supply concentration among Asian manufacturing hubs shapes margin structures across pricing tiers.
- Premium Brands:Extended warranty programs and electromagnetic compatibility certification differentiate positioning. Service network density in secondary cities remains a constraint.
- Mid-Range Brands:Aggressive pricing occupies the volume tier where electrification rate convergence meets income expansion. Procurement consolidation among national chains compresses traditional wholesaler markups.
- Budget Brands:Price transparency pressures margin structures in refrigerator and washing machine categories where specification standardization is highest.
- Local Brands:Backward integration into Durban assembly plants anchors positioning against import tariff volatility and local content requirements.
Mid-range brands capture volume today; premium brands are climbing the fastest on service network expansion.
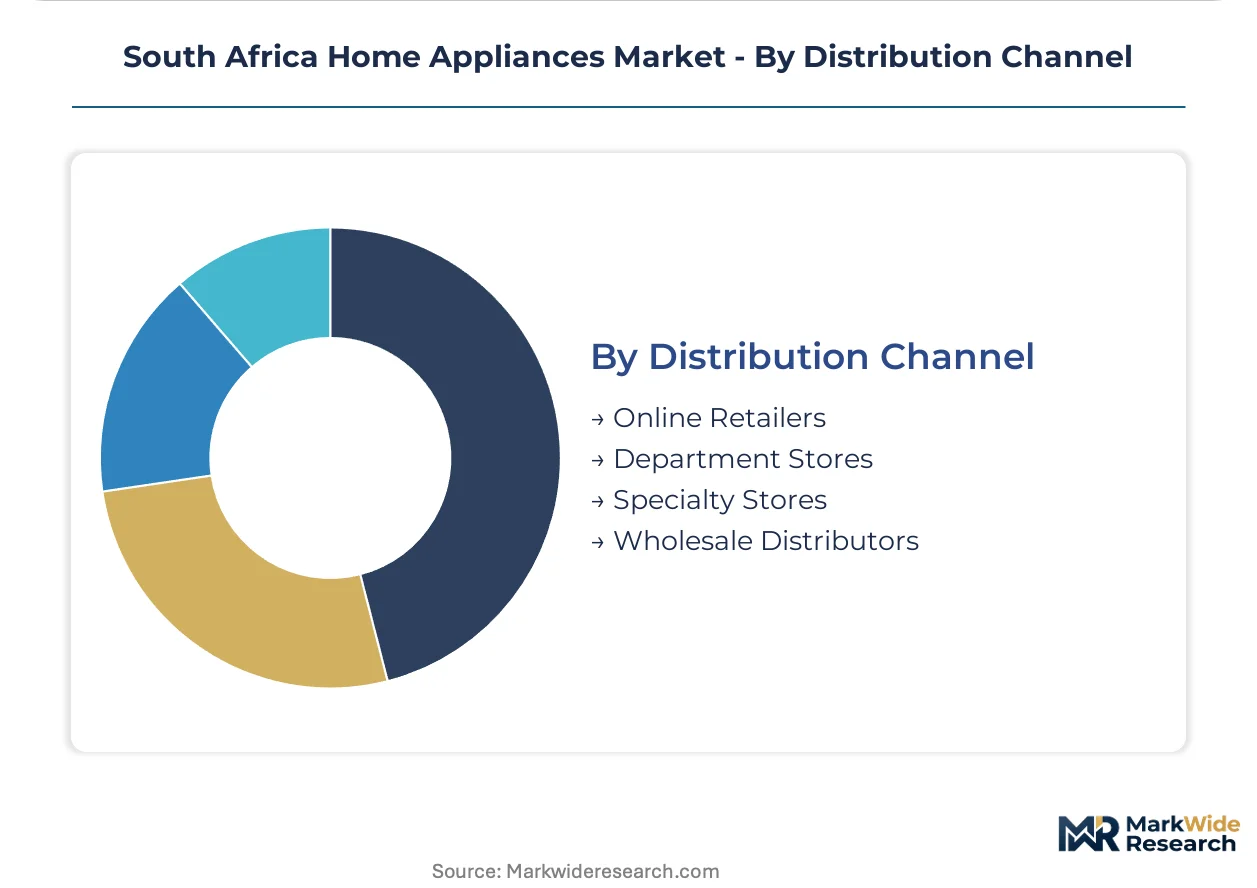
Distribution Channel:
Customer type and purchase journey complexity determine channel viability for high-consideration versus impulse appliance categories.
- Online Retailers:Price transparency accelerates share capture in standardized categories where physical inspection matters less. National chain direct-sourcing arrangements bypass traditional wholesaler markups.
- Specialty Stores:Technical consultation and installation coordination retain relevance for built-in dishwasher and integrated refrigeration configurations.
- Department Stores:Foot traffic dependency limits appliance category focus in formats without dedicated home goods floor space.
- Wholesale Distributors:Independent appliance stores in Durban's northern suburbs cede share to consolidated procurement networks with volume leverage.
Specialty stores lead high-consideration sales today; online retailers are expanding most quickly in standardized categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg-Pretoria corridor anchors South Africa's home appliances demand through electrification density and middle-income household concentration. Metropolitan retail networks and distributor procurement consolidation concentrate volume leverage in Gauteng's urban core. Provincial regulatory alignment with national efficiency mandates shapes local market access conditions.
Gauteng
Inverter-compatible refrigeration systems penetrate Johannesburg's peripheral townships where first-time ownership demand converges with NERSA tariff sensitivity. The province's metropolitan municipalities enforce building code compliance that favors energy-efficient appliance specifications in new residential developments. Pretoria-Tshwane manufacturing zones host Defy's backward-integrated assembly operations serving domestic distribution networks.
Western Cape
Solar-hybrid DC-native appliances capture early adoption in Atlantic Seaboard off-grid housing developments where residential photovoltaic installations expand. Cape Town's municipal water restrictions accelerate low-consumption washing machine penetration among middle-income households. The city's specialty retail channels retain dominance for built-in dishwasher configurations requiring technical consultation.
KwaZulu-Natal
Durban's northern suburbs concentrate national chain direct-sourcing arrangements that bypass traditional wholesaler markups in refrigerator and washing machine categories. The province's coastal humidity conditions drive demand for corrosion-resistant compressor housings in refrigeration systems. Local assembly plants in Durban anchor procurement strategies against import tariff volatility.
Eastern Cape
Rural durability-first positioning targets extended-warranty service networks where repair infrastructure scarcity currently blocks premium product penetration. Port Elizabeth-Gqeberha logistics corridors facilitate landed cost management for Asian manufacturing hub imports. Provincial electrification rate gaps limit addressable market expansion in former homeland territories.
Limpopo
Grid reliability dependency constrains market development in rural electrification zones where Eskom generation capacity constraints and absent backup power infrastructure overlap. Polokwane retail networks serve as distribution nodes for ruggedized simplicity product architectures engineered for load-shedding-exposed environments. Technician certification bottlenecks delay after-sales service network expansion beyond primary urban corridors.
South Africa Home Appliances Market Competitive Landscape
Global majors compete with regional champions across pricing tiers and distribution channel control in South Africa's appliances sector. The market structure fragments between premium service-network builders, mid-range volume players, and local-integrated cost defenders. Three archetypes dominate: Asian manufacturing hub exporters leveraging scale economics, European premium brands differentiating through warranty programs, and South African assemblers exploiting local content compliance. Competitive moves concentrate on procurement consolidation bypassing traditional wholesalers and backward integration into Durban assembly capacity.
Among Asian manufacturing hub exporters, Samsung and Hisense exemplify divergent positioning strategies within the same geographic origin tier. Samsung occupies the connected-home ecosystem vector where smart-enabled specifications anchor premium metropolitan positioning. Hisense sits within aggressive mid-range pricing tiers where volume capture in electrification-expansion zones drives procurement scale. Defy anchors the local-integrated archetype through captive Durban assembly that mitigates import tariff exposure and satisfies industrial policy local content requirements. Bosch represents European premium differentiation where extended warranty programs and SABS-certified service network density justify price positioning in major urban centers with established technical infrastructure.
| Leading Market Players |
|---|
| Samsung |
| Smeg |
| Defy |
| Milex |
| Russell Hobbs |
| Hisense |
| Bosch |
| Haier |
| LG |
| Others |
Value Network & Pricing Analysis
National retail chains in Johannesburg's procurement consolidation zones anchor per-unit transactional pricing that compresses traditional wholesaler markups in refrigerator and washing machine categories. This buyer concentration feeds back into supplier sourcing decisions, with landed cost management overriding brand premium considerations for volume-tier procurement teams.
Pricing Analysis
Input-cost pass-through from rand weakness against Asian manufacturing hub currencies intensifies pricing pressure across mid-range and economy tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates on energy efficiency certification grade and after-sales service bundling. Price differentiation stems from NERSA efficiency mandates and SABS certification costs. Middle-income electrification-expansion households in Gauteng peripheries show highest price sensitivity; Atlantic Seaboard high-income segments show lowest.
Supply Chain Analysis
Single-source vulnerability sits with compressor and control module suppliers concentrated in China and South Korea. Raw material dependencies include copper windings, refrigerant gases, and electronic control boards. Tariff exposure from South Africa's local content requirements under industrial policy creates structural risk for fully imported finished goods. Distribution runs through Johannesburg-based consolidated procurement networks that bypass traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's home appliances sector functions as a geographic-arbitrage play where Durban assembly capacity offers cost shelter against rand-driven import inflation that punishes fully landed competitors. NERSA efficiency mandates and local content compliance create regulatory differentiation between domestic-integrated and import-dependent supply models.
For Market Incumbents: Hedge against currency-driven margin compression by deepening backward integration into Durban assembly plants and captive component sourcing. Defy anchors this strategy through existing local manufacturing infrastructure. Prioritize SABS-certified service network density in secondary cities where technician scarcity blocks premium positioning. For New Entrants and Emerging Players: The mid-range price-point gap between Samsung's connected-home premium and budget-tier durability-first products offers white-space capture opportunity. Target Limpopo and Eastern Cape rural electrification zones where extended-warranty service networks currently underpenetrate. Enter through solar-hybrid DC-native appliance specialization for Western Cape off-grid housing developments. For Investors and Strategic Acquirers: Asian manufacturing hub exporters with scale economics are the most active acquirer in this space. Long-term viability hinges on procurement consolidation leverage and NRCS certification streamlining capabilities. Monitor load-shedding intensity trajectories as inflection indicator for inverter-compatible compressor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Local Assembly | Durban manufacturing capacity shields margin structures from rand volatility and satisfies NERSA local content requirements. |
| Solar-Hybrid Product Line Expansion | DC-native refrigeration systems capture Western Cape off-grid housing demand where residential photovoltaic installations expand. |
| Service Network Certification Investment | SABS-qualified technician pipelines unlock premium positioning in secondary cities beyond Johannesburg, Cape Town, and Durban. |
| Efficiency Rating Marketing Prioritization | NERSA tariff structure revisions make energy consumption labeling the dominant point-of-sale decision driver for middle-income buyers. |
| Procurement Consolidation Partnership | Direct-sourcing arrangements with national chains bypass traditional wholesaler markups in standardized refrigerator and washing machine categories. |
Research Methodology
Multiple input streams — appliance manufacturer procurement directors, national retail chain category buyers, SABS certification specialists, and NRCS regulatory affairs leads — were reconciled against customs import records, NERSA tariff filings, and Eskom electrification zone databases. Secondary validation drew from retailer point-of-sale audit data, municipal water restriction records, and residential photovoltaic installation permits. Bottom-up channel volume estimates and top-down macroeconomic absorption models were triangulated for convergence.
Data-stream reconciliation across product type, consumer segment, brand tier, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle analysis, electrification rate convergence modeling, and income expansion elasticity estimates. Forecast inputs incorporated load-shedding intensity scenarios and NERSA efficiency mandate compliance cost curves.
Caveats apply where Eskom generation capacity constraints, rand volatility against Asian manufacturing hub currencies, or NRCS certification timeline extensions could materially shift the outlook. Forecasts reflect assumptions about electrification rate progression and tariff structure stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Home Appliance (Wet and Cold) Market
Home Appliances
Range Hood Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Europe White Goods Market
Home Appliances
Europe Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Household Fridge Market
Home Appliances
Chile Home Appliances Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
China Home Appliances Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
Built-In Appliance Market