
 Bahrain Major Home Appliances Market | 2026-2036
Bahrain Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Major Home Appliances Market Outlook
Retail leasing and installment-based financing is fragmenting competitive access across Bahrain's appliance sector. Samsung Electronics leverages its brand infrastructure to dominate premium smart appliance showrooms in Manama. Midea Group anchors its position through cost-engineered air conditioner portfolios distributed via electrical retail chains. Haier Group competes on connected refrigerator platforms tailored to Gulf household configurations.
Bahrain major home appliances comprise electrically powered domestic equipment—refrigerators maintaining 0°C to 5°C fresh compartments, washing machines with 6-12 kg drum capacities, split-system air conditioners rated from 9,000 to 24,000 BTU, and built-in or freestanding ovens—manufactured through stamped steel forming, refrigerant charging, and automated assembly processes for residential food preservation, climate control, and fabric cleaning. Refrigerators occupy the largest value share as replacement cycles shorten in coastal humidity conditions. Smart Appliances and IoT-Enabled Devices represent the fastest-expanding technology cluster, though Conventional Appliances still sustain volume through price-sensitive expatriate households. High Efficiency and Eco-Friendly energy ratings concentrate margin pools where electricity tariff awareness shapes purchasing calculus.
Bahrain's Electricity and Water Authority enforces minimum energy performance standards for imported cooling equipment, compressing market access for uncertified manufacturers. The country's national product safety regulator mandates GCC conformity marking for all household electrical goods, creating compliance cost barriers for non-regional suppliers. Stakeholders must monitor how upcoming building code revisions for residential energy intensity reshape specification requirements for developers and retail channels alike.
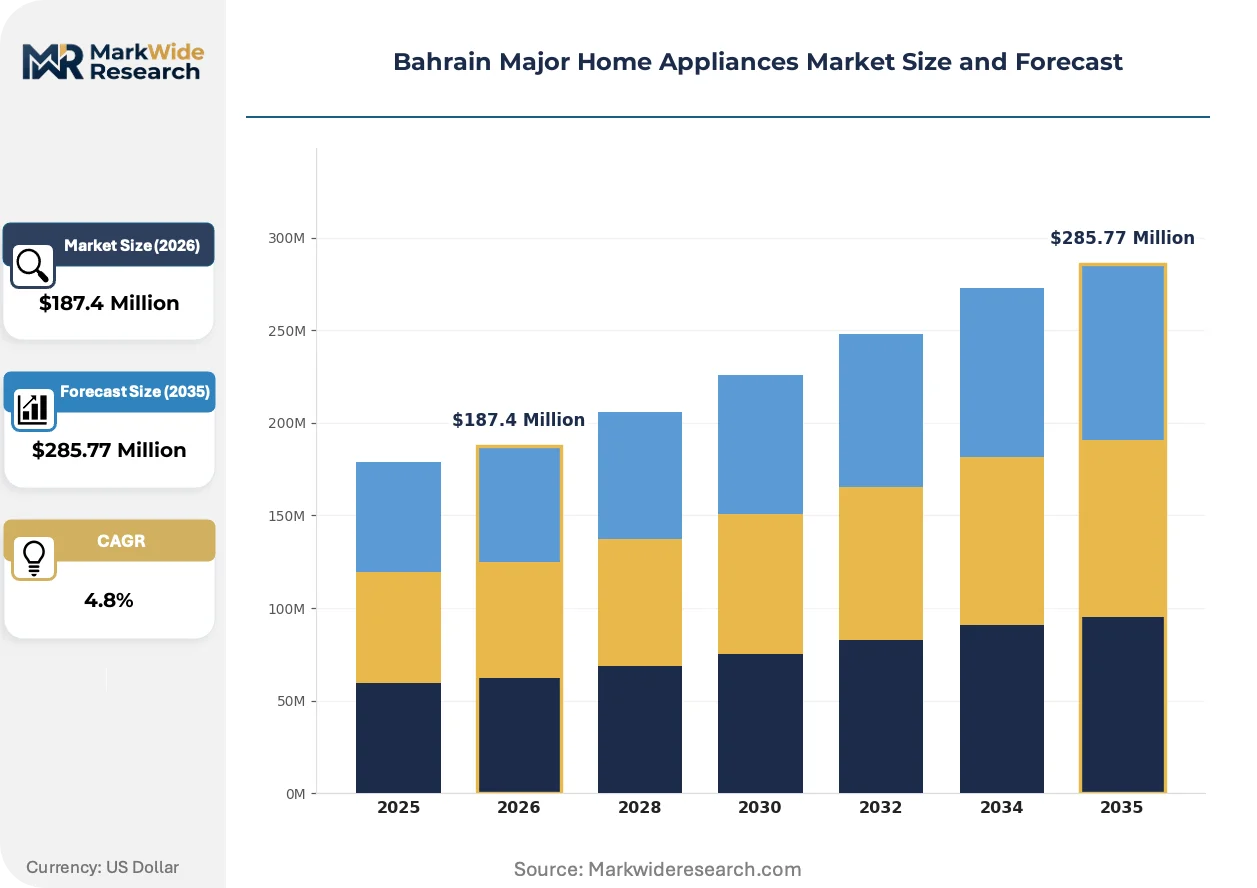
Market Dynamics
Residential construction momentum in Riffa and Muharraq is compressing replacement cycles for cooling and food preservation equipment, while Bahrain's Electricity and Water Authority tightens energy performance thresholds for imported air conditioners.
Growth Catalysts
- Residential construction permits:Developer activity in Bahrain's northern governorates is pulling forward refrigerator and washing machine installations in new unit deliveries.
- Smart appliance connectivity:IoT-enabled refrigeration platforms are capturing premium household segments in Manama's high-rise towers through remote monitoring capabilities.
- Energy efficiency mandates:Bahrain's national cooling equipment standards are filtering uncertified manufacturers from import channels, consolidating compliant supplier positions.
Market Restraints
- Refrigerant input volatility:Hydrofluorocarbon supply constraints and phase-down schedules are compressing margins for air conditioner assemblers dependent on imported cooling circuits.
- Import concentration risk:Appliance supply chains cluster through Jebel Ali transshipment corridors, exposing Bahrain distributors to Gulf-wide logistics disruptions.
- Technical limitation in humidity corrosion:Coastal salt-air degradation shortens compressor lifespans below manufacturer-rated intervals, accelerating warranty claim exposure.
Strategic Opportunities
- Underpenetrated Southern Governorate:Riffa and Isa Town residential zones present whitespace for mid-tier refrigerator and washing machine distribution expansion.
- Solar-thermal cooling convergence:Hybrid photovoltaic-absorption air conditioning systems align with Bahrain's building code revisions for residential energy intensity reduction.
- Installment financing channel innovation:Electrical retail chains are embedding consumer credit products directly at point-of-sale, expanding addressable household budgets.
Industry Challenges
- Field technician certification gaps:Smart appliance diagnostics require IoT troubleshooting competencies that Bahrain's service workforce currently lacks at scale.
- Compliance timeline compression:GCC conformity marking documentation requirements are extending product registration lead times for non-regional manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Major Home Appliances Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Air Conditioners, Ovens Energy Efficiency: Low Consumption, Medium Consumption, High Efficiency, Eco-Friendly Technology: Smart Appliances, IoT-Enabled Devices, Conventional Appliances, Hybrid Models Distribution Channel: Online Retail, Electrical Stores, Department Stores, Direct Sales |
| Companies Covered | Whirlpool Corporation, Midea Group Co., Ltd., Samsung Electronics Co., Ltd., Panasonic Corporation, Electrolux AB, LG Electronics Inc., BSH Hausgeräte GmbH, Hitachi, Ltd., Haier Group Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Major Home Appliances Market Strategic Shifts
Connected appliance ecosystems and energy performance thresholds are restructuring how Bahraini households evaluate equipment replacement decisions, shifting purchasing criteria from upfront cost to lifecycle operating economics.
Inverter-driven compressor technology is digitizing temperature modulation in residential refrigeration, replacing fixed-speed motor architectures with variable-frequency drives that adjust cooling output to thermal load. Affluent households in Manama's Seef and Juffair districts are specifying these platforms at accelerated rates. This capability is digitizing maintenance scheduling through predictive algorithm integration that flags compressor stress before failure.
Bahrain's Electricity and Water Authority enforces minimum energy performance standards for imported cooling equipment, compressing market access for uncertified manufacturers. The regulatory friction is elevating compliance investment requirements for regional distributors. Split-system air conditioners rated above 18,000 BTU face the steepest certification barriers, forcing specification shifts toward tier-1 supplier portfolios.
Households are unbundling after-sales service from original equipment purchases, engaging independent technicians for out-of-warranty repairs rather than authorized service networks. This fragmentation is disrupting traditional margin structures for electrical retail chains dependent on extended warranty attachments. The pattern concentrates in expatriate-heavy districts where price sensitivity overrides brand loyalty in replacement decisions.
Bahrain Major Home Appliances Market Segmentation
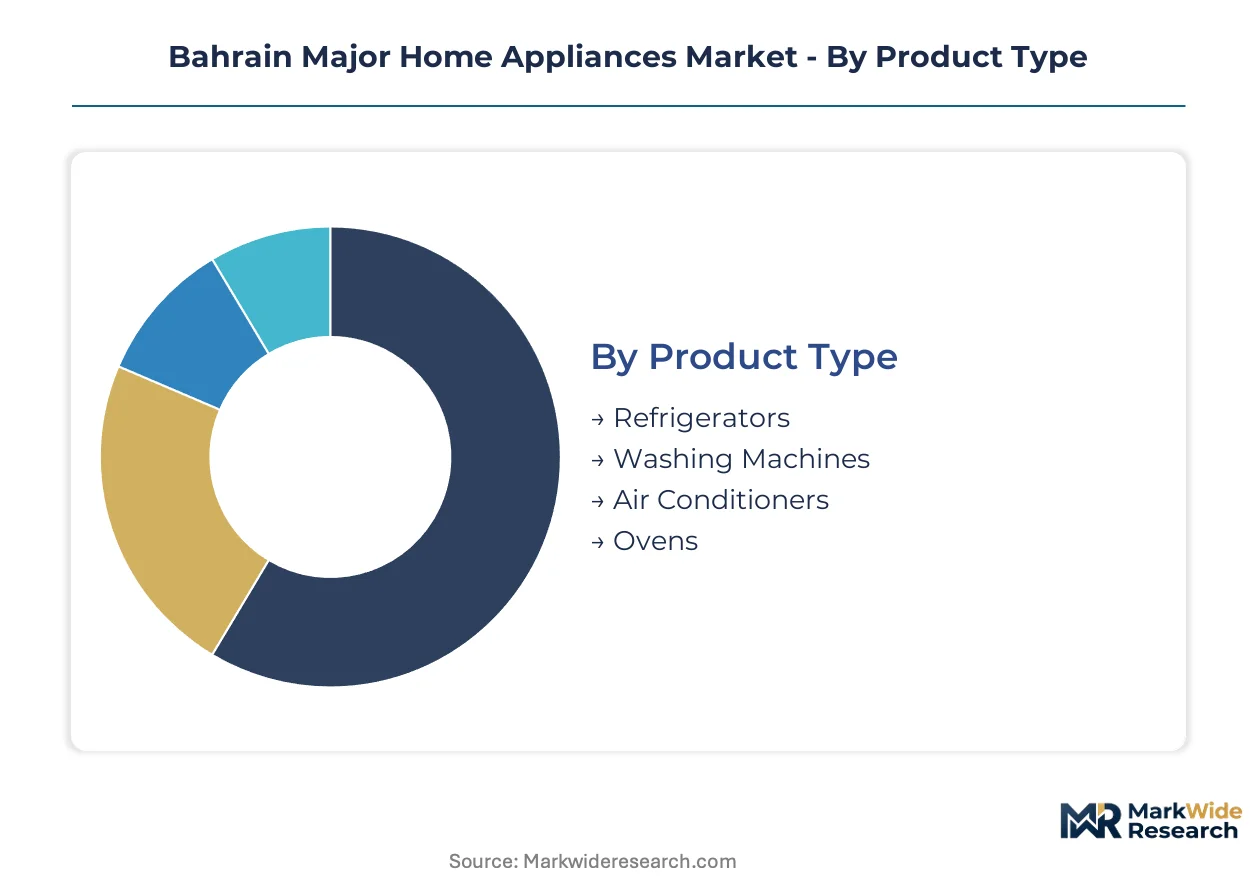
Segmentation in Bahrain's major home appliances market reveals how service infrastructure, regulatory compliance, and channel economics fragment purchasing behavior across household types. Each dimension carries distinct margin profiles and replacement cycle dynamics.
Product Type:
After-sales-service intensity varies sharply across product categories, with cooling equipment demanding specialized refrigerant handling and compressor diagnostics that constrain independent technician participation.
- Refrigerators:Compression-based cooling systems with fresh compartments maintaining 0°C to 5°C and freezer sections at -18°C. Demand concentrates in Riffa and Muharraq residential developments where new unit installations outpace replacement cycles. Coastal humidity accelerates condenser coil corrosion, shortening service intervals below manufacturer specifications.
- Air Conditioners:Split-system units rated 9,000 to 24,000 BTU using inverter-driven compressors for variable cooling output. Installations cluster in Manama's high-rise towers where building management contracts specify tier-1 supplier portfolios to satisfy Bahrain's Electricity and Water Authority certification requirements.
- Washing Machines:Front-load and top-load configurations with 6-12 kg drum capacities. Expatriate households in Isa Town drive volume through price-sensitive replacement decisions.
- Ovens:Built-in and freestanding electric or gas-fired cooking appliances. Premium specifications concentrate in Seef and Juffair districts.
By volume, air conditioners lead. By growth pace, smart-enabled refrigerators are ahead.
Energy Efficiency:
Cost tier stratification shapes competitive positioning, with electricity tariff awareness elevating lifecycle operating economics over upfront purchase price in affluent segments.
- High Efficiency:Equipment exceeding Bahrain's minimum energy performance standards for imported cooling equipment. Demand concentrates in Manama's high-rise residential towers where developer specifications mandate certified units.
- Eco-Friendly:Platforms using natural refrigerants and photovoltaic-thermal hybrid systems. Solar-thermal cooling convergence in Southern Governorate residential zones drives specification interest.
- Medium Consumption:Standard-compliant equipment balancing capital cost with operating expense. Mid-tier distribution channels in Riffa and Isa Town sustain volume.
- Low Consumption:Entry-grade equipment without advanced inverter technology. Price-sensitive expatriate households in Muharraq drive replacement demand.
By volume, medium consumption equipment leads. By margin expansion, high efficiency products are climbing the fastest.
Technology:
Application maturity separates connected platforms requiring IoT troubleshooting competencies from conventional architectures serviceable through established technician networks.
- Smart Appliances:Connected platforms with predictive maintenance algorithms and remote monitoring capabilities. Affluent households in Seef and Juffair districts specify these at accelerated rates.
- IoT-Enabled Devices:Refrigeration and climate control equipment with cloud-integrated diagnostics. Field technician certification gaps in Bahrain's service workforce constrain penetration.
- Conventional Appliances:Non-connected electromechanical systems with fixed-speed motors. Expatriate-heavy districts sustain volume through price-driven replacement.
- Hybrid Models:Equipment combining connected monitoring with traditional control interfaces. Transitional positioning captures upgrading households.
By volume, conventional appliances lead. By share gain, smart appliances are expanding most quickly.
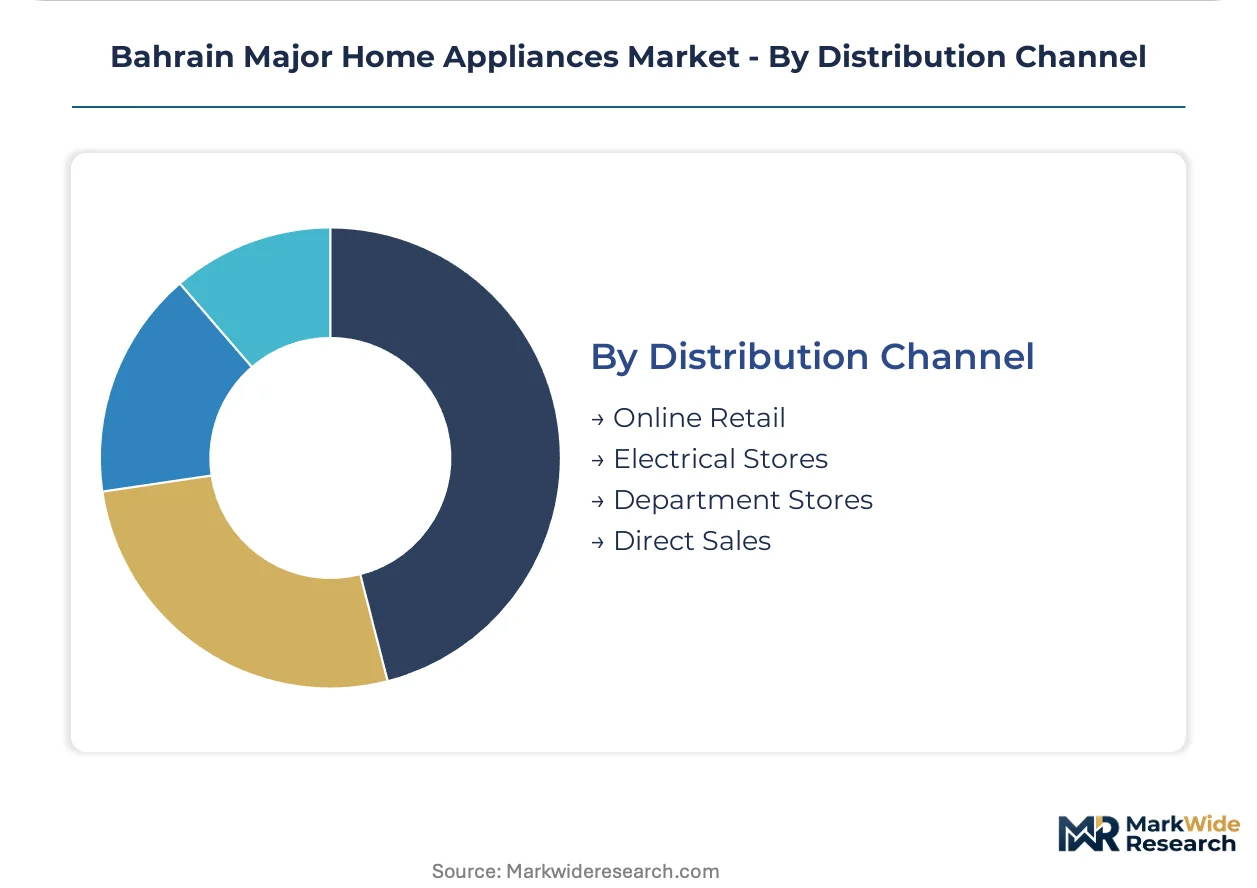
Distribution Channel:
Customer type fragmentation distinguishes installment-financing channels serving budget-constrained households from premium showroom experiences targeting specification-driven purchasers.
- Electrical Stores:Specialized retail chains embedding consumer credit products at point-of-sale. Installment financing innovation expands addressable household budgets across Northern Governorate.
- Online Retail:Digital platforms with delivery logistics concentrated through Jebel Ali transshipment corridors. Import concentration risk exposes distributors to Gulf-wide disruptions.
- Department Stores:General merchandise retailers with appliance sections. Mid-tier refrigerator and washing machine distribution reaches underpenetrated Southern Governorate zones.
- Direct Sales:Manufacturer-controlled showroom networks and builder-direct specifications. Premium smart appliance demand in Manama's high-rise towers concentrates here.
By volume, electrical stores lead. By channel innovation pace, online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Manama's high-rise residential towers exceeds that of Southern Governorate distribution zones by substantial margins, reflecting specification-grade developer mandates versus price-sensitive household budgets. This asymmetry shapes inventory deployment and margin capture across Bahrain's appliance channels.
Manama Capital Governorate
Smart-enabled refrigeration platforms and inverter-driven air conditioners dominate specification sheets for Seef and Juffair district towers. Bahrain's Electricity and Water Authority certification requirements filter non-compliant suppliers from high-rise developer procurement. Direct sales channels and premium showroom networks concentrate service infrastructure in this corridor.
Northern Governorate
Muharraq residential developments pull forward washing machine and refrigerator installations through new unit completions. Installment financing penetration runs deepest here via electrical retail chains embedding consumer credit at point-of-sale. Expatriate-heavy districts sustain mid-tier equipment volume through replacement-driven purchasing.
Southern Governorate
Riffa and Isa Town present whitespace for refrigerator and washing machine distribution expansion with underpenetrated mid-tier channels. Solar-thermal cooling convergence aligns with upcoming building code revisions for residential energy intensity. Department store appliance sections reach budget-constrained households that direct sales networks bypass.
Central Governorate
Isa Town's mixed residential-commercial fabric drives hybrid demand for both conventional and connected platforms. Field technician certification gaps constrain smart appliance penetration despite household interest. Independent repair networks fragment after-sales service economics away from authorized channels.
Bahrain Major Home Appliances Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in refrigerant handling and compressor supply. Bahrain's market structure consolidates around tier-1 supplier portfolios that satisfy Electricity and Water Authority certification requirements, compressing access for uncertified manufacturers. Three archetypes dominate: full-line platform integrators with connected ecosystems, cost-engineered volume specialists, and premium specification houses serving developer mandates. Competitive moves concentrate on compliance-driven portfolio rationalization and installment financing channel partnerships that expand addressable household budgets.
Among the named suppliers, Samsung Electronics Co., Ltd. and Midea Group Co., Ltd. exemplify contrasting strategic positions within this structure. Samsung Electronics occupies a platform-integrator archetype with connected ecosystem capabilities specified in Manama's premium residential towers. Midea Group Co., Ltd. anchors cost-engineered air conditioner portfolios distributed through electrical retail chains. Haier Group Corporation represents a third archetype with connected refrigerator platforms adapted to Gulf household configurations. These three companies illustrate how certification compliance, channel access, and technology positioning segment competitive terrain.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Midea Group Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Panasonic Corporation |
| Electrolux AB |
| LG Electronics Inc. |
| BSH Hausgeräte GmbH |
| Hitachi, Ltd. |
| Haier Group Corporation |
| Others |
Value Chain & Pricing Dynamics
Jebel Ali transshipment corridors concentrate appliance import flows into Bahrain, compressing margin capture for distributors while elevating pricing power for tier-1 suppliers with direct logistics arrangements. This upstream chokepoint funnels downstream cost structures toward certification-compliant portfolios that satisfy Bahrain's Electricity and Water Authority mandates.
Pricing Analysis
Configured-to-order pricing for smart-enabled refrigeration platforms commands substantial premiums over standard split-system air conditioner SKUs distributed through electrical retail chains. Three-tier pricing structure across premium, standard, and economy levels separates developer-specified units in Manama's high-rise towers from mid-tier Riffa installations and price-sensitive Muharraq replacement demand. Pricing pressure stems from refrigerant input volatility and hydrofluorocarbon phase-down schedules compressing assembler margins. Expatriate households in Isa Town exhibit highest price sensitivity, while Seef district premium buyers prioritize lifecycle operating economics over upfront capital outlay.
Supply Chain Analysis
Export-control regimes on compressor motor technologies and IoT semiconductor components constrain component flows from China, South Korea, and Taiwan into regional assembly operations. Bahrain's appliance manufacturing draws from stamped steel forming in India, refrigerant charging equipment from Germany, and inverter-drive controllers from Japan. Single-source vulnerability concentrates in Jebel Ali transshipment corridors where Gulf-wide logistics disruptions propagate downstream. Distribution runs through electrical retail chains embedding installment financing, online platforms dependent on transshipment logistics, and direct sales networks serving developer procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's major home appliances market is accelerating through energy efficiency mandate tightening and smart appliance connectivity proliferation, creating dual-trajectory disruption for incumbent positioning and new entrant access.
For Market Incumbents: Harden certification investment pipelines to preempt Electricity and Water Authority threshold escalations while anchoring channel control through exclusive installment financing partnerships with electrical retail chains. Compressor refrigerant handling capabilities and IoT diagnostics infrastructure represent critical defensive moats against emerging connected-platform specialists. Vertical integration into after-sales service networks counters independent technician fragmentation eroding warranty attachment economics. For New Entrants and Emerging Players: Mid-tier refrigerator and washing machine distribution in Southern Governorate's Riffa and Isa Town residential zones represents the most penetrable entry point, with solar-thermal cooling convergence aligning with upcoming building code revisions. Department store appliance sections in underpenetrated zones bypass direct sales network saturation. Embedded consumer credit products at point-of-sale enable budget-constrained household access without competing on brand equity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding exclusive tier-1 supplier relationships and Jebel Ali logistics contracts. Five-to-ten year viability hinges on compliance cost absorption capacity and smart appliance service infrastructure scaling. Monitor Electricity and Water Authority certification timeline compression for early signals of distributor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Efficiency Certification Investment | Preemptive compliance with Bahrain's Electricity and Water Authority thresholds secures import channel access against regulatory exclusion. |
| Installment Financing Channel Partnership | Embedded consumer credit at electrical retail chains expands addressable household budgets across price-sensitive expatriate segments. |
| Smart Appliance Service Infrastructure Buildout | IoT diagnostics capabilities capture premium replacement cycles in Manama's Seef and Juffair district towers. |
| Solar-Thermal Cooling Portfolio Development | Hybrid photovoltaic-absorption systems align with Bahrain's residential energy intensity building code revisions. |
| Southern Governorate Distribution Expansion | Department store appliance sections reach underpenetrated Riffa and Isa Town households that direct sales networks bypass. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across Bahrain's appliance value chain, including electrical retail chain procurement directors, developer specification engineers, field service technicians, and distributor logistics managers. Primary interview insights combined with secondary validation from Bahrain's Electricity and Water Authority regulatory filings, GCC conformity marking documentation, customs import records, and regional trade flow databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Calibration anchored historical penetration rates against regulatory mandate implementation timelines and construction permit trajectories across the projection horizon. Segmentation dimensions modeled include product type, energy efficiency tier, technology architecture, and distribution channel, with additional granularity on developer-specified versus retail-purchased equipment. CAGRs derived from regression-weighted scenario analysis incorporating electricity tariff elasticity and replacement cycle compression in coastal humidity conditions.
Practitioners should monitor refrigerant phase-down schedule acceleration, GCC conformity marking documentation requirement extensions, and building code revision implementation timelines for early signals of forecast deviation. Material shifts in Electricity and Water Authority certification thresholds or Jebel Ali corridor logistics disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Australia Washing Machine Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
United Kingdom Home Appliances Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Electric Household Appliances Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
Home Laundry Appliances Market