
 UAE Home Appliances Market | 2026-2036
UAE Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Home Appliances Market Analytics
MOHAP's updated energy efficiency mandates for cooling appliances is rebalancing the cost-of-entry calculus for new market participants. LG Electronics Gulf leverages its inverter compressor R&D pipeline to sustain premium positioning across the Emirates. Samsung Gulf Electronics anchors its portfolio through smart appliance ecosystems that integrate with regional IoT platforms. Haier Middle East competes on manufacturing scale, offering localized production flexibility that reduces landed cost for bulk hospitality contracts.
UAE home appliances comprise electrically powered devices designed for domestic tasks, typically operating at 220-240V/50Hz with ambient temperature ratings up to 50°C for Gulf climate compatibility; these units perform food preservation, garment cleaning, thermal comfort, and meal preparation functions for residential and commercial end users. Refrigerators command the largest product type share due to mandatory food storage requirements in high-temperature climates, though inverter-based air conditioners capture the fastest growth trajectory as building codes tighten cooling load standards. Smart appliances within the technology dimension attract disproportionate margin pools as hotels and luxury residential developers specify connected-device infrastructure, while traditional appliances face gradual displacement in new construction.
MOHAP administers product safety and energy labeling protocols that directly determine market access for imported appliances, while the Emirates Authority for Standardization and Metrology (ESMA) enforces ECAS conformity marks that test thermal performance under Gulf-specific ambient conditions. BIS-equivalent alignment for Indian-origin components and Saudi SFDA cross-border recognition agreements further complicate multi-country supply documentation for vendors serving the UAE. Stakeholders must monitor MOHAP's phased efficiency tier upgrades and ESMA's expanding scope for smart-device cybersecurity standards to anticipate compliance cost trajectories.
Market Dynamics
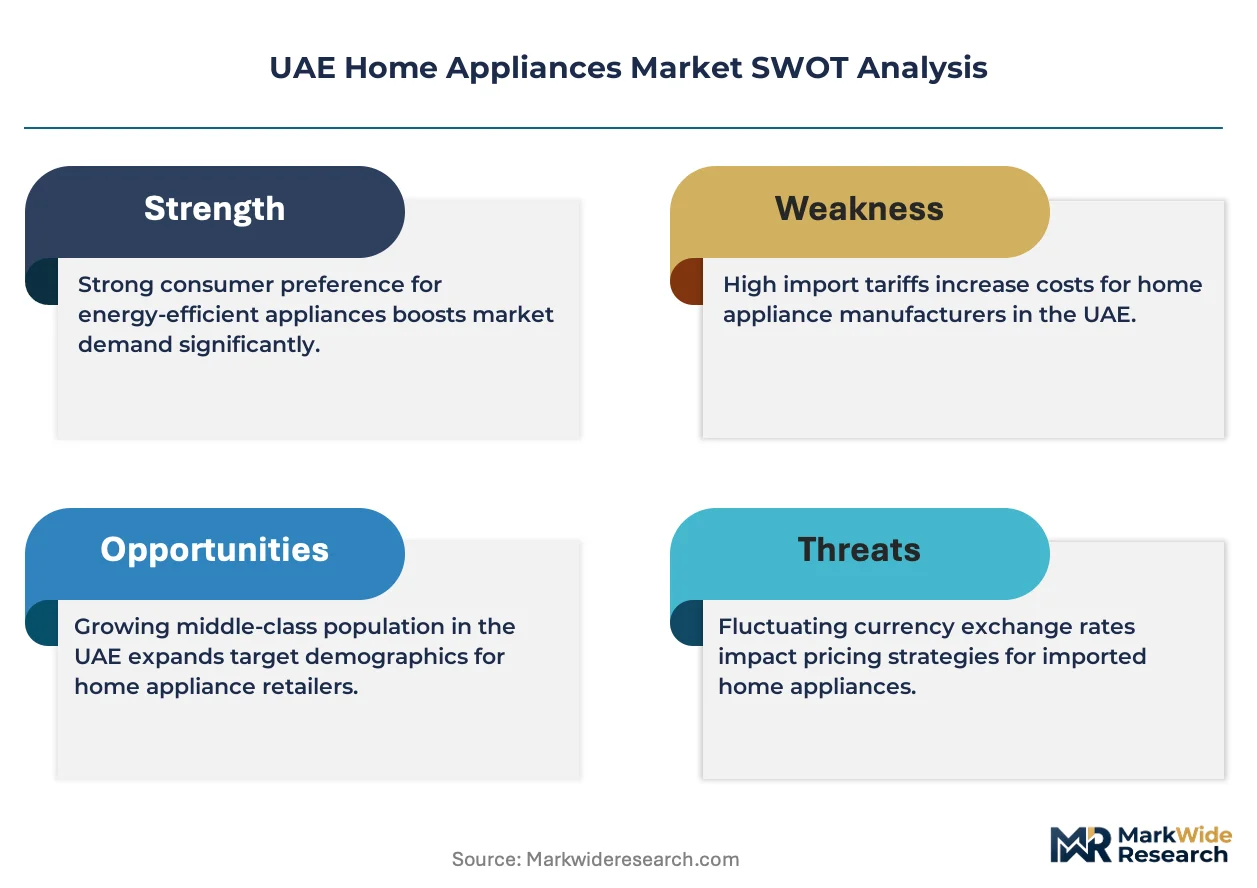
MOHAP's phased energy efficiency tier upgrades are compressing the competitive set by forcing inverter-grade compressor adoption across all import portfolios, while ESMA's expanding cybersecurity scope for smart appliances creates dual compliance burdens that favor capital-rich manufacturers.
Growth Catalysts
- Inverter compressor mandates:MOHAP's tightened cooling appliance standards eliminate fixed-speed compressor imports, pulling replacement demand forward among price-sensitive segments previously served by basic units.
- Luxury residential pipeline:Dubai's villa developments specify built-in kitchen suites with integrated smart infrastructure, creating anchor demand for premium appliance portfolios.
- Hospitality contract scale:Bulk procurement from hotel operators favors suppliers with localized assembly flexibility, rewarding manufacturing investments that reduce landed cost and delivery lead times.
Market Restraints
- Copper and rare-earth input volatility:Compressor motor laminations and permanent magnet materials face price swings that compress margin predictability for manufacturers locked into annual hospitality contracts.
- Import concentration risk:Appliance assembly for the UAE concentrates in Southeast Asian facilities, exposing supply continuity to shipping lane congestion and port capacity constraints at Jebel Ali.
- Smart-device interoperability limitations:Fragmented IoT protocols between property management systems and consumer smart home platforms create integration friction that delays specification decisions.
Strategic Opportunities
- Abu Dhabi secondary market penetration:Lower smart home integration rates in the capital emirate create whitespace for mid-tier appliance portfolios with upgradeable connectivity modules.
- ESMA cybersecurity pre-certification:Early alignment with expanding smart-device security standards positions vendors for preferred supplier status as mandates harden.
- Solar-thermal hybrid cooling:Convergence of photovoltaic rooftop installations with absorption chiller technology opens commercial segments seeking grid-independent thermal management.
Industry Challenges
- Field service technician scarcity:Inverter-grade diagnostics and smart appliance network troubleshooting require skill sets that outpace vocational training program output across the Emirates.
- Multi-jurisdiction certification timelines:BIS-equivalent documentation for Indian components plus Saudi SFDA cross-border recognition creates documentation bottlenecks that extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Home Appliances Market |
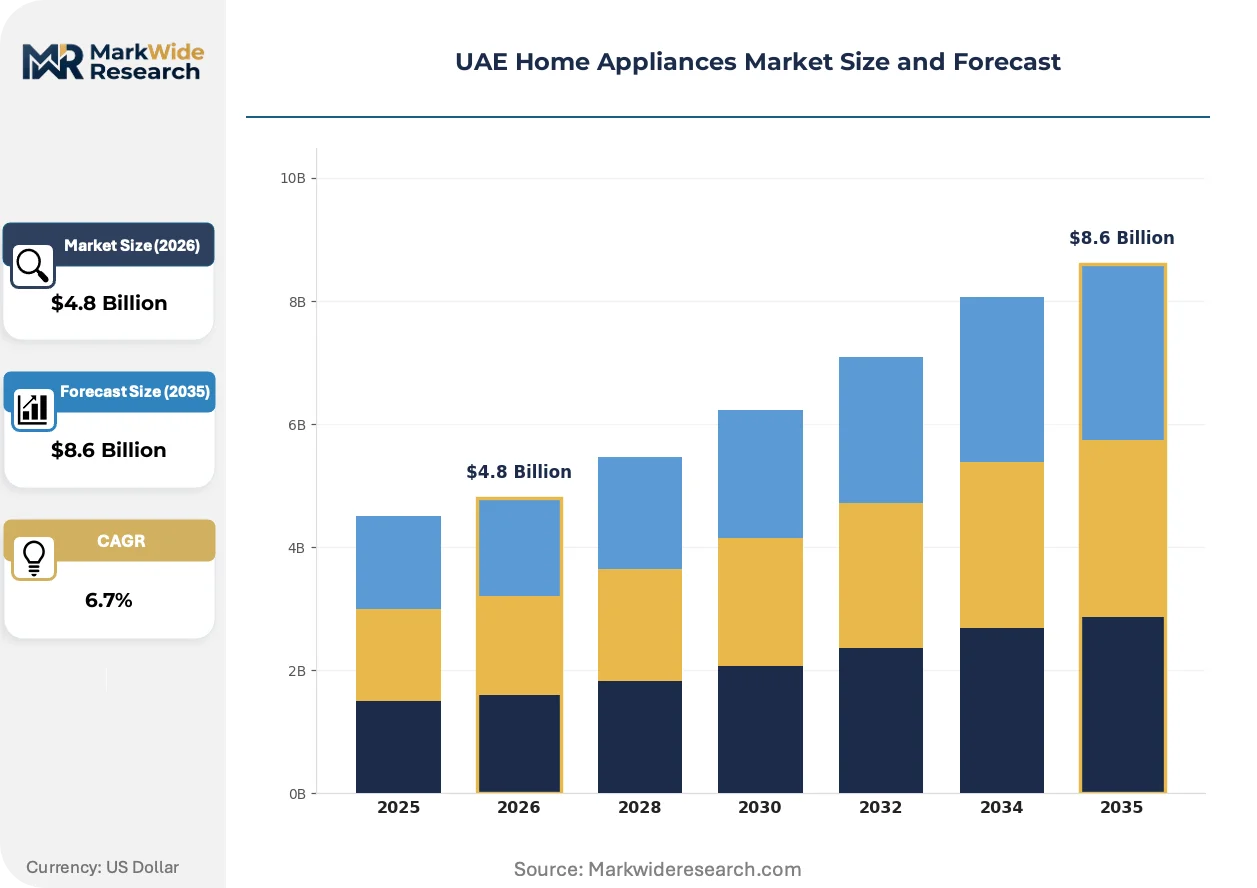
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Air Conditioners End User: Households, Hotels, Restaurants, Retail Outlets Distribution Channel: Online, Showrooms, Wholesale, Direct Sales Technology: Smart Appliances, Energy Efficient, Inverter Technology, Traditional Appliances |
| Companies Covered | Whirlpool Middle East, Panasonic Marketing MEA, LG Electronics Gulf, Electrolux Middle East, Midea Middle East, Samsung Gulf Electronics, Haier Middle East, Nikai Group, Bosch-Siemens Home Appliances, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Home Appliances Market Evolving Landscape
Appliance functionality is converging with building energy management systems, compressing the boundary between standalone white goods and integrated infrastructure. This shift rewards manufacturers with software competencies alongside thermal engineering heritage.
AI-enabled predictive maintenance is automating fault detection in cooling compressors before thermal performance degradation triggers energy penalty. High-end residential developers in Dubai are specifying these capabilities as standard, compressing the replacement cycle for legacy units that lack diagnostic connectivity. The technology is automating service contract bundling into initial appliance sales, shifting margin capture from hardware to recurring revenue streams.
ESMA's expanding scope for smart-device cybersecurity standards is forcing firmware architecture redesigns ahead of mandatory certification deadlines. Manufacturers must embed over-the-air update capabilities and encrypted communication protocols from the design phase, raising non-recurring engineering costs for new product introductions. Hospitality procurement teams are prioritizing pre-certified platforms to avoid retrofit liability, compressing the vendor shortlist to early movers.
Direct-to-developer specification is displacing traditional retail channel dominance for new construction volumes. Luxury residential projects in Abu Dhabi and Dubai are consolidating appliance selection into master developer procurement offices, bypassing distributor markups but demanding extended warranty terms and white-label service capabilities. This channel compression is most visible in the premium built-in segment, where specification decisions precede individual consumer purchase authority.
UAE Home Appliances Market Segmentation
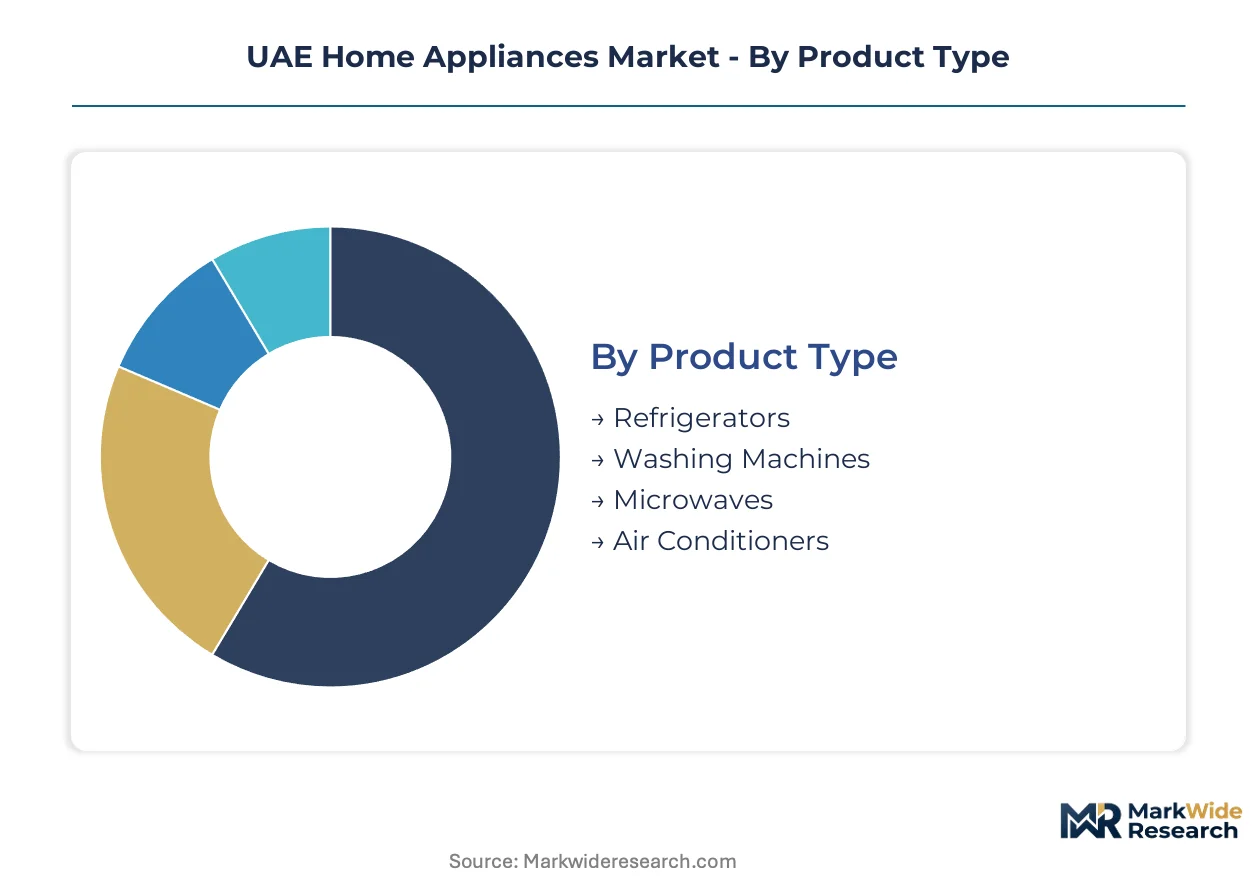
Segmentation reveals how MOHAP efficiency mandates and ESMA certification protocols reshape procurement patterns across distinct buyer clusters. Understanding these divides exposes where inverter-grade premiums command pricing power versus where traditional units still penetrate.
Product Type:
Upgrade cycles vary dramatically by thermal load intensity and compressor technology maturity, with high-ambient Gulf conditions accelerating replacement timelines for cooling-intensive categories.
- Refrigerators:Compressor-driven units with 220-240V/50Hz operation and 50°C ambient ratings dominate residential specification. Dubai villa developments mandate side-by-side and French-door configurations with inverter compressors to meet MOHAP tier requirements.
- Air Conditioners:Split-system and packaged units with variable-speed inverter drives capture specification share as building codes tighten cooling load standards. Abu Dhabi hospitality contracts specify these for operational cost control.
- Washing Machines:Front-load platforms with heat-pump drying integration serve high-end residential segments.
- Microwaves:Built-in and countertop formats concentrate in retail channel inventory.
Refrigerators sit at the top of the volume ranking, with air conditioners climbing the fastest.
End User:
Procurement scale and specification authority diverge sharply between individual purchase decisions and consolidated developer-controlled selection.
- Households:Individual buyers in Dubai and Sharjah drive replacement demand through retail and online channels, with smart-home compatibility influencing premium segment selection.
- Hotels:Bulk procurement from Abu Dhabi and Dubai hospitality operators favors suppliers with localized assembly flexibility and extended warranty terms.
- Restaurants:Commercial kitchen equipment specifications prioritize durability and rapid service response.
- Retail Outlets:Appliance retail chains and electronics hypermarkets serve as inventory staging points for immediate fulfillment.
Hotels command the largest contract values, with households generating the highest transaction frequency.
Distribution Channel:
Channel economics shift as direct-to-developer specification displaces traditional retail markups in new construction volumes.
- Showrooms:Branded experience centers in Dubai Mall and Yas Mall anchor premium positioning for built-in kitchen suites.
- Online:E-commerce platforms capture replacement-cycle purchases from price-comparison shoppers.
- Wholesale:Distributor networks serve contractor and project-based procurement with volume pricing.
- Direct Sales:Manufacturer-to-developer relationships bypass intermediary margins for master-planned community specifications.
Showrooms retain the highest margin per unit, with direct sales expanding most quickly in new construction.
Technology:
Regulatory tier upgrades and cybersecurity mandates compress the viable technology set toward connected, efficient platforms.
- Inverter Technology:Variable-speed compressor drives with permanent magnet motors eliminate fixed-speed imports under MOHAP's tightened cooling appliance standards. These units pull replacement demand forward among segments previously served by basic models.
- Smart Appliances:Wi-Fi-enabled platforms with over-the-air update capabilities and encrypted protocols align with ESMA's expanding cybersecurity scope. Dubai luxury developers specify these as standard infrastructure.
- Energy Efficient:Units meeting MOHAP efficiency labeling requirements serve price-sensitive segments seeking compliance without connectivity premiums.
- Traditional Appliances:Fixed-speed, non-connected units face gradual displacement in new construction while persisting in replacement markets.
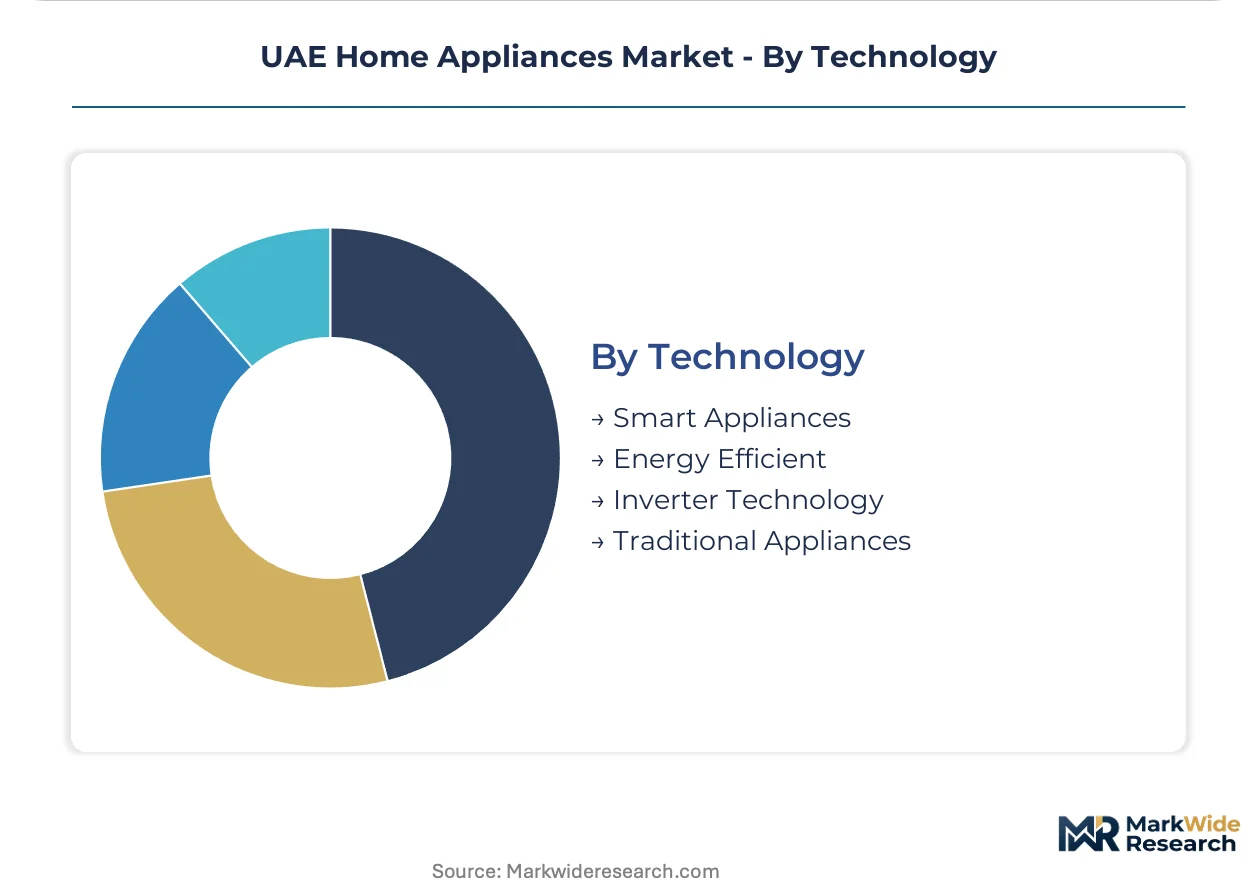
Inverter technology holds the dominant installed base position, with smart appliances gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized field service technicians for inverter-grade diagnostics cluster in Dubai and Abu Dhabi, creating a talent moat that slows competitor expansion into secondary emirates. This concentration shapes how appliance portfolios penetrate distinct sub-markets.
Dubai
Luxury villa developments and smart home infrastructure drive specification demand for premium built-in kitchen suites. MOHAP's energy labeling enforcement operates most stringently here, accelerating inverter compressor adoption. Dubai Marina and Downtown Dubai residential clusters anchor developer-direct procurement channels that bypass traditional retail markups.
Abu Dhabi
Hospitality contract scale from hotel operators favors suppliers with localized assembly flexibility and extended warranty terms. ESMA conformity assessment timelines run longer here, compressing product launch windows for new entrants. Yas Island and Saadiyat Island hospitality corridors concentrate bulk procurement decisions.
Sharjah
Price-sensitive household replacement demand flows through retail and wholesale channels serving mid-tier appliance segments. MOHAP's efficiency tier upgrades pull demand forward among segments previously served by fixed-speed imports. Industrial zones near Sharjah International Airport host distributor staging facilities for northern emirate fulfillment.
Northern Emirates
Ras Al Khaimah and Fujairah present whitespace for mid-tier portfolios with upgradeable connectivity modules as smart home penetration lags Dubai benchmarks. ESMA certification costs weigh disproportionately on low-volume shipments to these markets. Hospitality developments along the east coast generate intermittent contract opportunities for durable commercial kitchen equipment.
UAE Home Appliances Market Competitive Landscape
The competitive structure tilts toward multinational electronics conglomerates with regional Gulf subsidiaries. Capital-rich manufacturers with inverter compressor R&D pipelines and smart appliance firmware capabilities dominate specification channels. Three archetypes populate the field: Korean electronics majors with integrated smart home ecosystems, European premium specialists with built-in kitchen heritage, and Chinese scale players with manufacturing flexibility. Geographic expansion through direct-to-developer relationships and portfolio diversification into connected-device platforms represent the dominant competitive moves.
Within the multinational electronics tier, LG Electronics Gulf, Samsung Gulf Electronics, and Haier Middle East occupy distinct positioning vectors. LG Electronics Gulf exemplifies the R&D-anchored archetype leveraging compressor technology pipelines. Samsung Gulf Electronics represents the ecosystem-integrated model with smart home platform convergence. Haier Middle East sits within the manufacturing-scale archetype offering localized production flexibility for bulk contract fulfillment.
| Leading Market Players |
|---|
| Whirlpool Middle East |
| Panasonic Marketing MEA |
| LG Electronics Gulf |
| Electrolux Middle East |
| Midea Middle East |
| Samsung Gulf Electronics |
| Haier Middle East |
| Nikai Group |
| Bosch-Siemens Home Appliances |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap distributors across Sharjah and Ras Al Khaimah anchor wholesale channel pricing discipline, compressing margin capture for multinational manufacturers while simultaneously buffering landed cost volatility through consolidated import volumes. Their ownership concentration enables forward-contracting flexibility that insulates retail markups from spot freight fluctuations at Jebel Ali.
Pricing Analysis
Bundled extended warranty and installation services separate premium inverter-grade appliance pricing from unbundled transactional retail sales of basic replacement units. Three-tier pricing structure across premium, standard, and economy levels tracks MOHAP efficiency certification tiers and ESMA cybersecurity pre-qualification status. Pricing pressure stems from copper and rare-earth magnet cost volatility in compressor motor laminations. Hospitality procurement teams in Abu Dhabi exhibit lowest price sensitivity due to operational cost control priorities, while Sharjah household replacement buyers drive hardest bargain hunting.
Supply Chain Analysis
Copper winding wire and permanent magnet materials for inverter compressor motors rest on Chinese and Japanese specialty metal producers, with rare-earth processing concentrated in China's Inner Mongolia corridor. Plastic resin housings and electronic control modules draw from South Korean and Taiwanese component specialists. Single-source vulnerability runs through Southeast Asian final assembly facilities serving UAE-bound shipments. Distribution runs through Jebel Ali port consolidation followed by distributor staging at Sharjah International Airport industrial zones for northern emirate fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UAE home appliances hinges on inverter compressor cost curves flattening as manufacturing scale accumulates, while premium smart-appliance specification share climbs in Dubai villa developments.
For Market Incumbents: Cement specification lock-in through ESMA cybersecurity pre-certification ahead of mandate hardening, and deepen backward integration into compressor motor lamination supply through captive sourcing agreements with Chinese rare-earth processors. Threat from Haier's localized manufacturing flexibility demands channel control reinforcement in hospitality procurement offices. For New Entrants and Emerging Players: Mid-tier appliance buyers in Ras Al Khaimah and Fujairah represent the most penetrable whitespace, with upgradeable connectivity modules addressing lagging smart-home infrastructure. Target Abu Dhabi secondary market through distributor partnerships offering extended warranty bundling that matches incumbent service capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among European premium specialists with built-in kitchen heritage but limited Gulf regional presence. Long-term viability frames around software-enabled service revenue streams displacing hardware margin dependence. Signal to watch is MOHAP efficiency tier upgrade cadence accelerating replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| ESMA Cybersecurity Pre-Certification | Early alignment positions vendors for preferred supplier status as mandates harden. |
| Backward Integration into Rare-Earth Sourcing | Captive magnet supply agreements insulate compressor cost from spot price volatility. |
| Direct-to-Developer Specification Channel | Bypassing distributor markups captures margin in Dubai Marina and Downtown Dubai clusters. |
| Field Service Technician Training Programs | Inverter-grade diagnostic capabilities address scarcity constraining competitor expansion. |
| Solar-Thermal Hybrid Cooling Partnerships | Photovoltaic-absorption chiller convergence opens commercial grid-independent segments. |
Research Methodology
Multiple input streams — structured interviews with appliance procurement managers at Dubai hospitality operators, technical consultations with ESMA conformity assessment officers, and trade data analysis — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from MOHAP energy labeling registries, customs import manifests at Jebel Ali, and distributor inventory records across Sharjah wholesale networks. Primary fieldwork engaged category buyers at electronics hypermarkets, aftermarket service heads, and master developer specification officers.
Historical shipment volumes were cross-referenced against panel input from compressor technology suppliers and inverter control module specialists to anchor projection assumptions across the analysis window. Segmentation modeling spanned product type, end-user procurement scale, distribution channel economics, and technology tier compliance status. CAGRs were derived from replacement cycle compression analysis and new construction pipeline tracking, with inputs from copper price futures and rare-earth magnet supply forecasts.
Inputs from MOHAP efficiency tier registries and ESMA certification timelines were available through the study window; gaps in real-time distributor inventory positioning introduce uncertainty bands around quarterly volume allocations. Forecasts reflect documented assumptions regarding regulatory upgrade cadence and supply chain continuity. A small set of triggers — MOHAP mandate acceleration, Jebel Ali port capacity constraints, and field service technician training program output — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Europe Residential Water Heaters Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Residential Washing Machine Market