
 Residential Dishwashers Market | 2026-2036
Residential Dishwashers Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Dishwashers Market Analytics
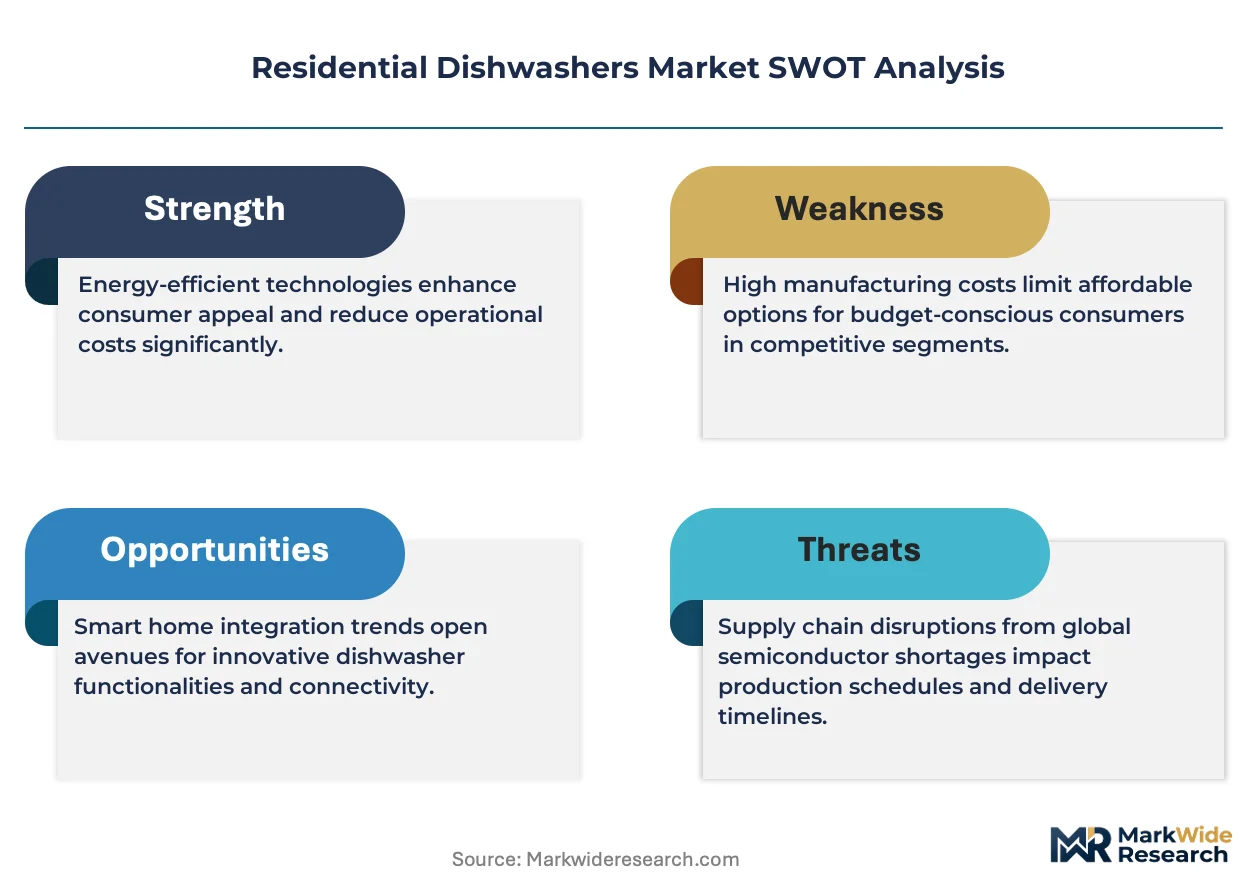
Connected appliance ecosystems and AI-driven wash cycle optimization is rewriting how manufacturers engineer residential dishwashers for predictive maintenance and remote diagnostics. Robert Bosch GmbH leverages its Home Connect platform to anchor premium positioning in European markets. Samsung Electronics Co. Ltd. competes through SmartThings integration across its full appliance suite. Whirlpool Corporation sustains manufacturing scale advantages in North American production.
A residential dishwasher is an electromechanical cleaning appliance that uses pressurized hot water, detergent dispensing systems, and heated drying cycles to sanitize tableware, typically operating at 120-160°F wash temperatures with 3-6 gallon water consumption per cycle. Its primary purpose is to automate food soil removal while reducing manual labor and water usage versus hand washing. Built-in models dominate volume and margin pools due to new construction integration and kitchen renovation cycles, while smart technology features represent the fastest-expanding feature tier as Wi-Fi connectivity becomes standard across mid-range and premium price bands. Drawer configurations occupy a specialized niche for compact urban dwellings where space constraints limit full-size installation.
The US Department of Energy administers ENERGY STAR efficiency thresholds that dictate minimum market entry requirements for water and electricity consumption. The European Commission enforces Ecodesign regulations and EU Energy Label standards that phase out lower-efficiency models from EU market access. China's GB standards and MIIT directives establish domestic efficiency benchmarks for imported and locally manufactured units. Stakeholders must monitor how tightening efficiency mandates in multiple jurisdictions affect component costs and which manufacturers absorb compliance investments versus passing them through pricing structures.
Market Dynamics
Connected appliance ecosystems and AI-driven wash cycle optimization are restructuring competitive advantage around predictive maintenance capabilities and data platform control. Manufacturers now compete on software integration depth rather than hardware specifications alone.
Growth Catalysts
- ENERGY STAR efficiency thresholds:The US Department of Energy's tightening water and electricity consumption mandates are accelerating replacement cycles as older models lose market access. Home renovation contractors increasingly specify certified units to meet building code compliance.
- Suburban homeowner demand:New residential construction in the United States, Germany, and China is embedding built-in dishwashers as standard kitchen fixtures. This buyer segment demonstrates the fastest expansion in absolute unit terms.
- Wi-Fi connectivity standardization:Smart technology features are migrating from premium tiers into mid-range price bands, expanding addressable market for connected diagnostics and remote cycle management.
Market Restraints
- Stainless steel and semiconductor input volatility:Component cost swings compress margin predictability for manufacturers operating at scale. Supply agreements for control boards and pump motors face repricing pressure.
- EU Ecodesign phase-out schedules:Lower-efficiency model elimination is forcing inventory write-downs and accelerated R&D cycles. Compliance investments must absorb testing and certification overhead.
- Drawer configuration technical ceiling:Compact urban formats face capacity constraints that limit soil removal performance versus full-size alternatives. Space-constrained installations trade cleaning efficacy for footprint reduction.
Strategic Opportunities
- China's GB standard efficiency tiers:Domestic benchmark alignment creates positioning room for imported and locally manufactured units meeting higher grades. MIIT directive enforcement is raising baseline market entry requirements.
- Voice assistant and home energy management convergence:Integration with utility demand-response programs enables peak-load shifting. Manufacturers partnering with grid operators can monetize load flexibility.
- Direct-to-installer channel development:Bypassing traditional retail through kitchen renovation contractor networks captures decision-point influence. This route shortens specification-to-installation timelines.
Industry Challenges
- Firmware and embedded systems engineering talent scarcity:Connected appliance development requires software competencies outside traditional white goods engineering. Recruitment competition with consumer electronics and automotive sectors elevates compensation costs.
- Cross-jurisdiction certification timeline compression:Simultaneous ENERGY STAR, EU Energy Label, and GB standard testing creates sequential bottlenecks. Parallel track submission strategies demand duplicate testing investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Dishwashers Market |
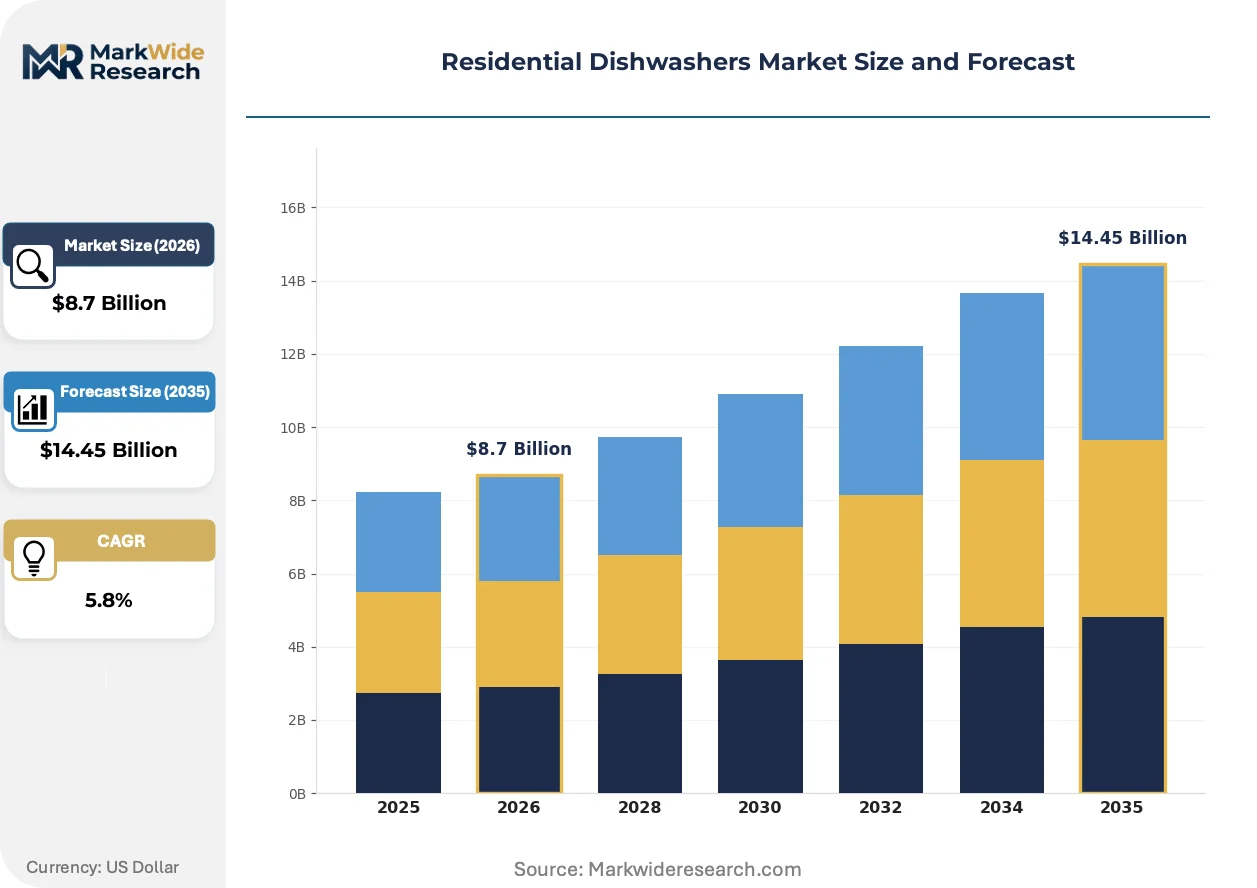
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Portable, Drawer, Countertop Feature: Energy Efficiency, Smart Technology, Quick Wash, Noise Reduction End User: Homeowners, Renters, Property Managers, Builders Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Whirlpool Corporation, Samsung Electronics Co. Ltd., Robert Bosch GmbH, LG Electronics Inc., General Electric Company, Miele, Electrolux AB, BSH Hausgeräte GmbH, ASKO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Dishwashers Market Evolving Landscape
Digital twin architectures and edge computing deployment are redefining how dishwasher manufacturers approach field performance optimization and service model transformation. The convergence of hardware instrumentation with cloud analytics is generating new value capture mechanisms.
Sensor fusion arrays combining turbidity detection, load weight measurement, and thermal imaging are virtualizing the traditional pre-rinse assessment function. Premium buyer segments in Germany and the United States are adopting these configurations at accelerated rates. This capability compression is eliminating the need for manual cycle selection and reducing water overconsumption from conservative user defaults.
The European Commission's Ecodesign regulations and EU Energy Label standards are systematically removing lower-efficiency models from EU market access. Industrial consequence includes forced portfolio rationalization and accelerated development of heat pump drying systems. Mid-range product tiers face the steepest redesign burden as they must absorb premium-tier efficiency features without full price repositioning.
Buyer preference is rotating toward integrated kitchen ecosystems over standalone appliance purchases. Kitchen renovation channels in the United States are displacing big-box retail as the primary specification point for built-in models. This pattern concentrates most visibly in suburban developments where contractor packages bundle appliances with cabinetry and countertop installation.
Residential Dishwashers Market Segmentation
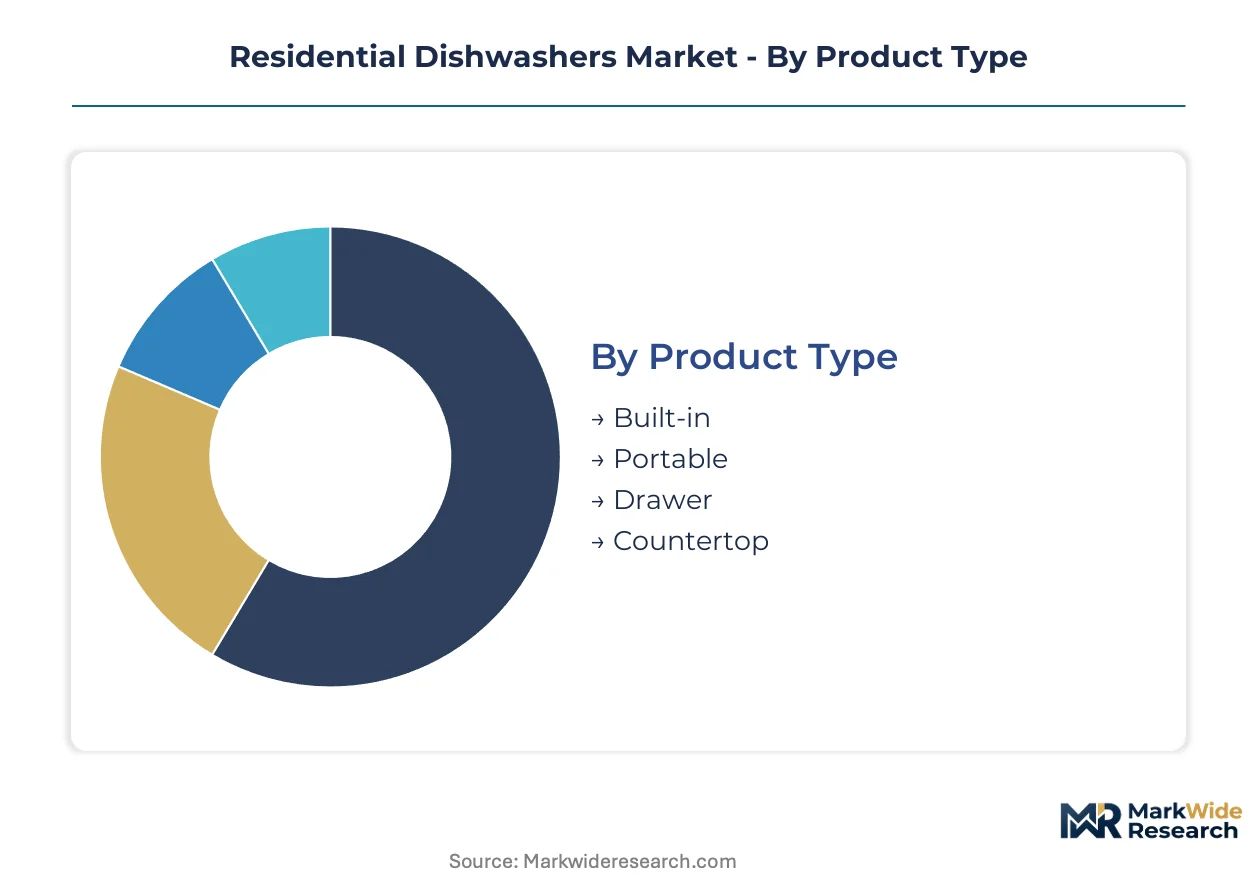
Residential dishwasher segmentation reveals how purchase cycles, specification authority, and channel economics fragment demand across installation types, feature tiers, and buyer categories. Understanding these fault lines clarifies where manufacturers must align product development with replacement velocity versus new construction timing.
Product Type:
Built-in models turn over slowest, tied to decade-plus kitchen renovation cycles, while portable and countertop formats cycle faster through rental turnover and temporary living situations.
- Built-in:These units integrate permanently beneath countertops with dedicated plumbing connections, typically featuring 24-inch standard widths and 12-16 place settings capacity. Suburban new construction in the United States and Germany embeds these as standard fixtures, with ENERGY STAR certification now mandatory for market access. Built-in models anchor the volume base while smart technology variants gain share at the steepest rate.
- Portable:Freestanding units on casters connect temporarily to kitchen faucets, serving renters and space-constrained dwellings without permanent installation. Demand concentrates in urban apartment markets where lease terms preclude structural modifications.
- Drawer:Split-configuration designs allow independent wash zones in compact footprints, typically 24-inch widths divided into two stacked drawers. These occupy a specialized niche for galley kitchens and aging-in-place renovations requiring reduced bending.
- Countertop:Compact units sitting atop counters wash 4-6 place settings using manual water connections. College dormitories and RV installations drive replacement demand for these lowest-capacity formats.
Built-in configurations dominate absolute unit economics while drawer and countertop segments expand most quickly from small bases in space-constrained urban housing.
Feature:
Cost tier stratification separates premium positioning through sensor-driven automation from compliance-driven efficiency mandates that compress mid-range margins.
- Energy Efficiency:Heat pump drying, variable speed motors, and soil sensors reduce water and electricity consumption below ENERGY STAR thresholds. EU Ecodesign regulations and US Department of Energy mandates are forcing this feature into base specifications across all price tiers.
- Smart Technology:Wi-Fi connectivity, app-based cycle control, and voice assistant integration enable remote diagnostics and predictive maintenance alerts. Wi-Fi-enabled models are climbing the fastest in German and US premium segments as kitchen ecosystem integration becomes a purchase criterion.
- Quick Wash:Accelerated 30-60 minute cycles sacrifice some cleaning performance for time-sensitive users. Working households with irregular meal timing drive adoption of this convenience feature.
- Noise Reduction:Insulation packages and brushless motors achieve sub-44 decibel operation for open-concept kitchens. Luxury suburban renovations specify these for living space adjacency.
Energy efficiency features anchor regulatory compliance while smart technology capabilities capture the steepest share gains in contractor-specified premium installations.
End User:
Customer type determines specification authority, with builders and property managers making bulk decisions while homeowners and renters exercise individual choice within constraint.
- Homeowners:Individual purchasers selecting units for primary residences, exercising full discretion over feature prioritization and brand preference. Suburban renovation cycles in the United States concentrate demand for mid-to-premium built-in models with extended warranties.
- Renters:Tenants lacking installation authority who rely on landlord-provided appliances or portable self-purchase options. Urban rental markets in Germany and China drive demand for countertop and portable formats with minimal footprint.
- Property Managers:Multi-unit housing operators standardizing across portfolios for maintenance efficiency and replacement part commonality. These buyers prioritize reliability metrics and service network coverage over feature differentiation.
- Builders:New construction developers specifying appliances in bulk for pre-sale housing packages. US suburban developments represent the fastest-expanding absolute demand source for standard-grade built-in units with contractor pricing.
Builders anchor volume concentration in expansion markets while homeowners drive the steepest upgrade trajectory toward connected and efficiency-optimized configurations.
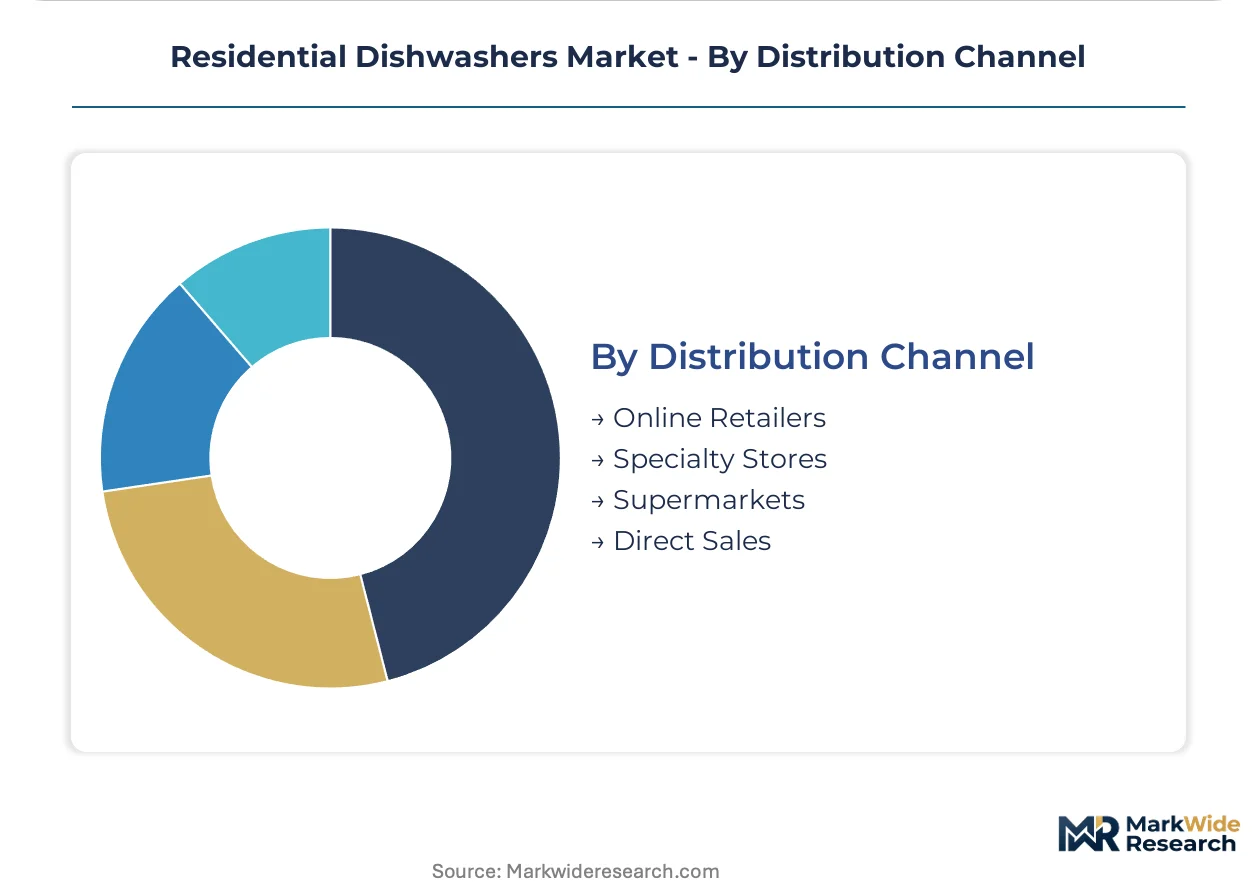
Distribution Channel:
Channel selection reflects where specification decisions occur, with direct-to-installer routes shortening timelines versus retail paths that emphasize consumer comparison.
- Online Retailers:E-commerce platforms enabling specification research, price comparison, and delivery scheduling without physical showroom visits. Replacement purchases in the United States increasingly initiate through Amazon and manufacturer direct sites.
- Specialty Stores:Kitchen and bath showrooms offering design consultation alongside appliance specification. These channels capture premium built-in sales tied to renovation project management.
- Supermarkets:Big-box retailers providing immediate availability and competitive pricing for standard-grade portable and countertop units. Price-sensitive renters and emergency replacements drive this channel's relevance.
- Direct Sales:Manufacturer-to-contractor relationships bypassing retail markup for new construction volume. Builder procurement teams in Germany and the United States negotiate these arrangements for multi-unit projects.
Specialty stores anchor premium built-in volume while direct sales channels gain share fastest as builder procurement centralizes and retail intermediation faces margin pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in residential dishwashers tilt toward import dependence in high-consumption markets while manufacturing clusters serve regional demand. The United States, Germany, and China anchor three distinct supply-demand configurations shaped by regulatory divergence and construction cycles.
United States
Suburban new construction embeds built-in units as standard fixtures, with ENERGY STAR certification now mandatory for market access. The US Department of Energy administers tightening efficiency thresholds that accelerate replacement cycles. Manufacturing concentrates in the Midwest industrial corridor where Whirlpool Corporation sustains scale advantages in North American production.
Germany
Kitchen renovation contractors specify premium connected models through specialty channels, displacing big-box retail as the primary specification point. The European Commission enforces Ecodesign regulations and EU Energy Label standards that phase out lower-efficiency models. Robert Bosch GmbH leverages its Home Connect platform to anchor premium positioning in European markets from its Baden-Württemberg base.
China
Urban apartment markets drive demand for compact and portable formats where lease terms preclude permanent installation. MIIT directives and GB standards establish domestic efficiency benchmarks for imported and locally manufactured units. Manufacturing clusters in the Yangtze River Delta serve both domestic consumption and export assembly for regional Asian markets.
Japan
Space-constrained dwellings sustain demand for drawer configurations and countertop units with reduced footprints. METI efficiency standards and JIS certification requirements shape product development priorities. Tokyo-Osaka corridor distribution networks emphasize noise reduction features for open-concept living spaces.
South Korea
Apartment-centric housing stock favors built-in integration during new construction phases. SmartThings ecosystem integration drives premium positioning as Wi-Fi connectivity becomes standard across mid-range price bands. Seoul Capital Area concentration supports Samsung Electronics Co. Ltd.'s connected appliance development.
Residential Dishwashers Market Competitive Landscape
On the supply side, the industry is consolidating around platform ecosystems rather than hardware specifications alone. Three structural archetypes dominate: full-line appliance conglomerates with smart home integration capabilities, European engineering specialists commanding premium positioning through durability reputation, and Asian electronics manufacturers leveraging semiconductor supply chain proximity for connected feature development. Competitive moves concentrate on strategic partnerships with utility operators for demand-response programs and direct-to-installer channel bypass of retail intermediation.
Within the full-line conglomerate tier, Whirlpool Corporation and Samsung Electronics Co. Ltd. exemplify divergent ecosystem strategies. Robert Bosch GmbH occupies a position as the European engineering specialist archetype. These three anchors illustrate how competitive advantage is restructuring around software integration depth and data platform control rather than traditional hardware specifications.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics Co. Ltd. |
| Robert Bosch GmbH |
| LG Electronics Inc. |
| General Electric Company |
| Miele |
| Electrolux AB |
| BSH Hausgeräte GmbH |
| ASKO |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese component manufacturing is compressing supplier margins and enabling aggressive pricing postures among OEMs sourcing control boards and pump motors. This utilization dynamic feeds directly into mid-range product tier repositioning as manufacturers absorb efficiency compliance costs rather than pass through to suburban renovation buyers.
Pricing Analysis
Builder procurement teams anchor contract-based long-term offtake structures across new construction channels, with pricing stratifying across ENERGY STAR certification grades, smart feature bundles, and after-sales service tiers. Cost compression in stainless steel inputs and semiconductor components is intensifying because of commodity volatility, pressuring standard-grade margins most severely while premium connected configurations retain pricing power. Property managers exhibit highest price sensitivity due to portfolio standardization mandates, whereas specialty showroom buyers demonstrate lowest sensitivity when ecosystem integration justifies premium positioning.
Supply Chain Analysis
Contract manufacturing concentration rests with Whirlpool Corporation's Midwest assembly footprint, Robert Bosch GmbH's Baden-Württemberg operations, and Yangtze River Delta clusters serving Samsung Electronics Co. Ltd. and domestic Chinese brands. Geographic supply concentration centers on the United States, Germany, and China for finished goods assembly, with critical component dependencies spanning Malaysian semiconductor packaging, Turkish steel finishing, and Mexican motor winding operations. Single-source vulnerability in Wi-Fi module supply creates exposure to FCC certification delays. Distribution runs through direct-to-installer channels for builder volume, specialty showrooms for renovation replacement, and big-box retail for portable emergency purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from hand-washing behavior persistence in cost-conscious segments and compact urban dwellings where drawer configurations underperform. Defense requires embedding dishwashers deeper into kitchen ecosystem lock-in.
For Market Incumbents: Entrench platform ecosystem control by deepening Home Connect and SmartThings integration depth to raise switching costs for renovation buyers. Secure backward integration into heat pump drying module production to defend margin position against EU Ecodesign compliance investments. Counter portable format substitution threat by bundling built-in specifications into contractor kitchen packages. For New Entrants and Emerging Players: Establish a beachhead in China's GB standard premium efficiency tier where imported positioning remains underdeveloped relative to local manufacturing. Target countertop and portable segments in German urban rental markets through Amazon-direct distribution bypassing established retail intermediation. Exploit firmware engineering talent scarcity by acquiring connected appliance software specialists rather than building in-house. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heat pump drying system development as EU Ecodesign mandates force platform redesigns. Long-term viability favors manufacturers with captive semiconductor sourcing relationships and installer channel control rather than retail-dependent brands. Acquisition target archetype: mid-tier European engineering specialists with durability reputation but lagging smart connectivity. Monitor ENERGY STAR threshold revision announcements as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Drying System Development | EU Ecodesign compliance forces R&D redirection toward energy recovery architectures. |
| Direct-to-Installer Channel Expansion | Bypasses retail margin capture in US suburban new construction specification. |
| Smart Home Platform Integration | Home Connect and SmartThings ecosystems lock renovation buyers into replacement continuity. |
| Semiconductor Supply Agreement | Long-term control board sourcing mitigates FCC certification timeline compression risk. |
| Voice Assistant Partnership | Utility demand-response program eligibility enables peak-load shifting monetization. |
Research Methodology
Cross-validation between manufacturer production disclosures and customs trade data anchors the qualitative findings in this study. Primary interviews with kitchen renovation contractors, appliance procurement managers at multi-unit developers, specialty showroom specification consultants, and ENERGY STAR certification engineers combined with secondary validation from US Department of Energy rulemaking dockets, EU Ecodesign implementing measures, MIIT directive publications, and SEC 10-K appliance segment disclosures. Bottom-up unit shipment modeling and top-down value aggregation triangulate market size estimates.
Calibration against historical replacement cycle patterns and new construction permit flows shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include installation type, feature tier, end-user category, and distribution channel, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from slope analysis of efficiency mandate adoption curves and smart feature penetration rates. Key forecast inputs encompass suburban housing starts in the United States and kitchen renovation permit velocity in Germany.
Macroeconomic conditions sit as an overlay; deviation in mortgage rate trajectories and construction material cost indices would shift the trajectory. Forecasts reflect underlying assumptions about regulatory enforcement continuity and technology cost decline curves. Quarterly review of ENERGY STAR certification submission volumes and EU Energy Label reclassification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Household Refrigerator Market
Home Appliances
Russia Home Appliances Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Egypt Major Home Appliances Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Sweden Home Appliances Market
Home Appliances
Germany Small Home Appliance Market
Home Appliances
Qatar Major Home Appliances Market
Home Appliances
Undercounter Refrigerators Market