
 United Kingdom Air Purifier Market | 2026-2036
United Kingdom Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Air Purifier Market Insights
DEFRA's Clean Air Strategy is broadening the addressable market for building-grade filtration across England and Wales. Dyson Limited leverages its domestic R&D footprint to sustain premium positioning in smart-enabled residential units. Daikin Airconditioning UK Ltd. anchors its competitive stance through HVAC-integrated centralized systems for commercial clients. Philips N.V. differentiates via medical-grade HEPA certifications that command specification in NHS procurement channels.
United Kingdom air purifiers are electromechanical devices employing fibrous media, activated carbon beds, or ultraviolet germicidal irradiation to remove particulate matter, volatile organic compounds, and biological aerosols from enclosed air volumes. HEPA filtration dominates the product type landscape due to established NHS procurement protocols and BSI certification requirements, while smart technology represents the fastest-expanding technology segment as IoT-enabled units gain traction in residential and commercial retrofit applications. The end user structure tilts toward residential demand in Greater London, though industrial uptake accelerates in Midlands manufacturing corridors where OSHA-aligned occupational exposure limits tighten.
BSI standards, DEFRA air quality frameworks, and NHS estates technical guidance collectively shape product certification pathways and procurement eligibility for UK market participants. The Medicines and Healthcare products Regulatory Agency influences clinical-grade device classifications that constrain market access for uncertified imports. Stakeholders must monitor evolving Building Regulations Part F ventilation amendments and anticipate how MEES efficiency standards will redirect capital toward integrated air handling retrofits.
Market Dynamics
DEFRA's Clean Air Strategy is compressing compliance timelines for commercial buildings across England and Wales, forcing accelerated replacement cycles for legacy HVAC infrastructure and expanding specification requirements for building-grade filtration systems.
Growth Catalysts
- Healthcare procurement mandates:NHS estates technical guidance now embeds HEPA filtration specifications into capital refurbishment programs. Acute trusts in Greater London face the tightest compliance deadlines.
- Building Regulations Part F amendments:Ventilation performance standards for new residential developments in urban centers are tightening mechanical extract requirements. Developers specify integrated air handling units to satisfy airtightness targets.
- Midlands manufacturing corridor expansion:OSHA-aligned occupational exposure limits for particulate matter are driving industrial uptake in automotive and aerospace supply chains across Birmingham and Coventry.
Market Restraints
- Activated carbon input volatility:Coconut shell charcoal supply concentrates in Southeast Asian processing hubs. Freight cost fluctuations compress margin structures for carbon-bed manufacturers serving the UK market.
- BSI certification timelines:Third-party testing protocols for medical-grade device classification create six-to-nine-month market entry delays for imported units lacking prior EU MDR equivalence.
- Filter media supply concentration:Microglass HEPA paper production clusters in German and Swiss specialty chemical corridors. UK assemblers face single-source risk for high-efficiency grades specified in NHS contracts.
Strategic Opportunities
- Scotland's net-zero building stock:Scottish Government heat-in-building regulations are accelerating deep retrofit programs in Glasgow and Edinburgh social housing. Integrated ventilation-with-filtration packages command specification preference.
- IoT-enabled predictive maintenance:Sensor-embedded units converging with building management systems allow service revenue unbundling from hardware sales. Facilities management contractors in London's commercial office sector pilot subscription models.
- Education sector capital programs:Department for Education condition improvement funding is directing capital toward indoor air quality upgrades in aging school estates. Priority jurisdictions include Manchester and West Yorkshire.
Industry Challenges
- Electrostatic precipitator integration complexity:Retrofit installations in 1970s commercial building stock require structural assessment of existing ductwork. Project delays erode contractor margins on fixed-price maintenance contracts.
- UV-C lamp disposal compliance:Waste electrical and electronic equipment regulations impose mercury-containing lamp handling protocols. Service networks lack licensed treatment capacity outside Southeast England.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Air Purifier Market |
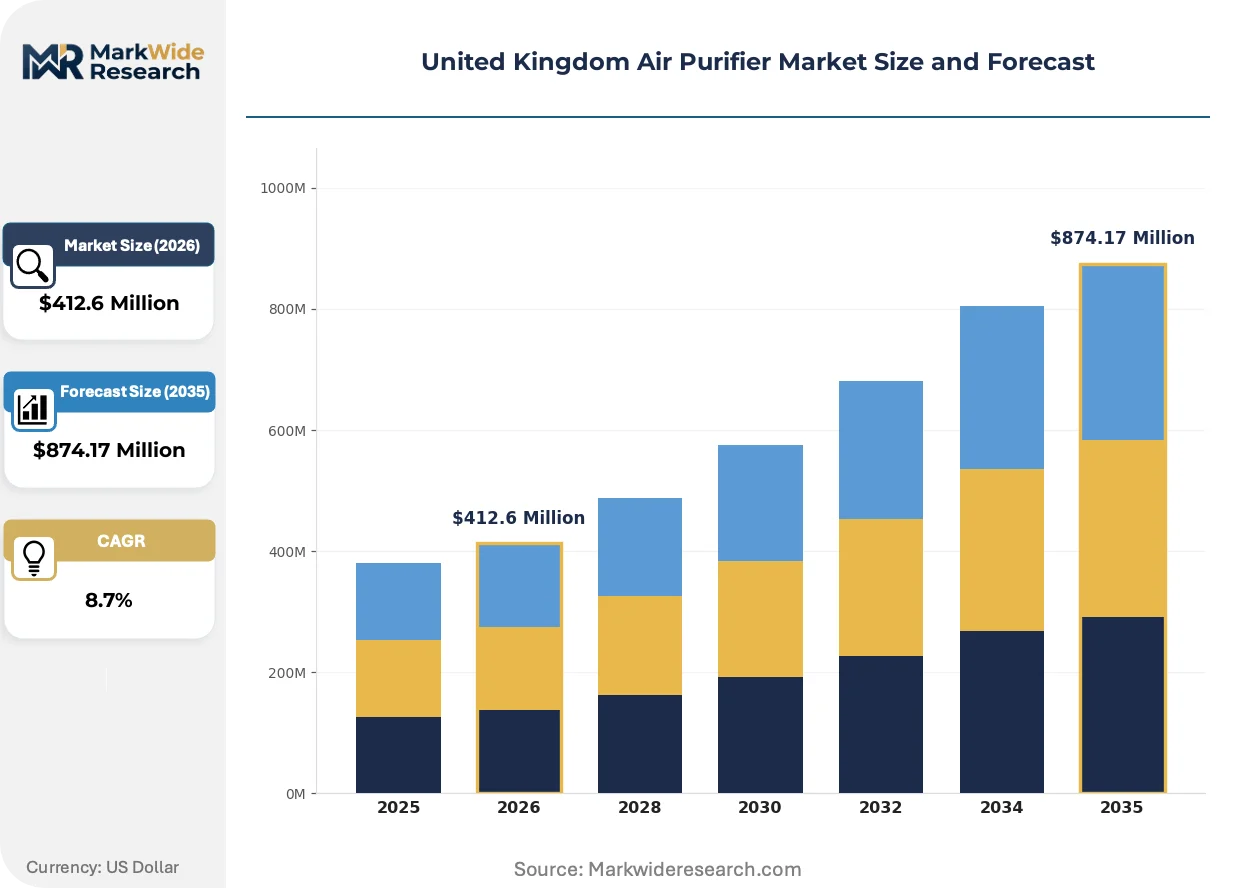
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Ionic, UV-C Technology: Smart, Portable, Standalone, Centralized End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Dyson Limited, Daikin Airconditioning UK Ltd., Honeywell International Inc., Koninklijke Philips N.V., The Camfil Group, Panasonic UK & Ireland, Samsung Electronics (UK) Ltd., MANN+HUMMEL GmbH, Blueair AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Air Purifier Market Trends and Innovations
Electrochemical sensor miniaturization is collapsing the cost curve for real-time particulate and VOC monitoring. This capability migration is redrawing competitive boundaries between standalone purification hardware and integrated environmental control platforms.
Photocatalytic oxidation using titanium dioxide coatings is rewriting performance expectations for VOC degradation in compact residential units. Buy-to-let landlords in Greater London are specifying these systems to satisfy impending selective licensing air quality conditions. The technology is compressing the addressable market for activated carbon replacement cartridges in sub-50-square-meter applications.
DEFRA's 2023 update to the Environmental Improvement Plan is mandating PM2.5 concentration limits below WHO interim targets for urban agglomerations. Local authorities in Bristol and Leeds are embedding these thresholds into planning conditions for major residential developments. Specifiers are responding by oversizing mechanical ventilation with heat recovery systems to ensure margin against future tightening.
Aggregated procurement through housing association frameworks is consolidating buyer power across England's social rented sector. Traditional distributor networks serving independent electrical retailers are losing specification influence to direct manufacturer relationships with procurement consortia. The shift is most advanced in Southeast England where housing association concentration enables volume-based tendering.
United Kingdom Air Purifier Market Segmentation

UK air purifier procurement channels diverge sharply across specification regimes. NHS estates, housing associations, and independent households each trigger distinct product configurations and certification requirements.
Product Type:
Filtration media selection hinges on contaminant target and regulatory compliance tier.
- HEPA:Microglass fiber media achieving 99.97% efficiency at 0.3 microns dominates acute healthcare specifications. NHS capital refurbishment programs in Greater London mandate this grade for isolation wards and operating theatres.
- Activated Carbon:Coconut shell-derived charcoal beds adsorb VOCs and odour compounds. Buy-to-let landlords in Bristol specify carbon-integrated units to satisfy selective licensing air quality conditions.
- Ionic:Electrostatic precipitation systems charge particulate matter for collection on oppositely charged plates. These units face specification resistance in DEFRA-monitored public buildings due to ozone emission concerns.
- UV-C:Low-pressure mercury lamps deliver germicidal irradiation at 253.7 nanometres. Clinical-grade installations in West Midlands NHS trusts require MHRA device registration.
HEPA leads on scale; UV-C leads on momentum.
Technology:
Integration depth with building systems determines capital allocation and service revenue potential.
- Smart:IoT-enabled units embed particulate and VOC sensors with cloud-connected diagnostics. Facilities management contractors in London's commercial office sector pilot subscription-based predictive maintenance models.
- Centralized:HVAC-integrated air handling units serve new-build commercial developments. Building Regulations Part F amendments drive specification in airtight residential towers across Manchester and Leeds.
- Portable:Self-contained plug-in units target residential retrofit applications. Southeast England housing associations aggregate procurement through framework agreements.
- Standalone:Floor-mounted systems with caster mobility address temporary healthcare capacity. Nightingale hospital legacy estates in England retain these for surge preparedness.
Centralized systems command the highest project values; smart connectivity is climbing the fastest.
End User:
Exposure limit stringency and compliance timeline pressure vary dramatically across sectors.
- Residential:Urban households in Greater London respond to indoor air quality benchmarking. Developer specifications increasingly bundle mechanical ventilation with heat recovery.
- Commercial:Office landlords face DEFRA Clean Air Strategy deadlines for building-grade filtration. Grade A stock in Birmingham and Edinburgh prioritizes tenant wellness certifications.
- Industrial:Midlands automotive and aerospace supply chains adopt OSHA-aligned occupational exposure controls. Particulate matter monitoring precedes capital deployment.
- Automotive:Cabin air filtration integrates with HVAC modules for premium vehicle lines. UK-based assembly plants source through tier-one supplier networks.
Residential absorbs the greatest unit volume; industrial uptake shows the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects buyer scale, specification complexity, and service bundling requirements.
- Direct Sales:Manufacturers engage housing association consortia and NHS procurement hubs through framework agreements. Volume commitments override distributor margins.
- Online:E-commerce platforms serve replacement filter cartridge demand and residential unit purchases. Consumer ratings visibility shapes brand consideration.
- Retail:Electrical superstores and independent dealers stock portable units for immediate pickup. Greater London footfall concentrates in big-box out-of-town formats.
- Wholesale:HVAC distributors supply mechanical contractors with building-integrated systems. Technical support and spare parts availability determine supplier loyalty.
Direct sales secure the largest contract values; online channels are gaining share fastest.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Greater London and the West Midlands anchor the United Kingdom's air purification technology base. Regional demand patterns diverge sharply between urban air quality compliance pressures and industrial occupational health mandates.
Greater London and Southeast England
Healthcare estates and buy-to-let housing stock drive procurement volume. NHS capital refurbishment programs embed HEPA specifications into acute trust isolation wards. The Nightingale hospital legacy estates retain surge-capacity portable units for pandemic preparedness.
West Midlands
Automotive and aerospace supply chains adopt OSHA-aligned particulate exposure controls across Birmingham and Coventry. Manufacturing employers face tightening occupational health audits. Filter-integrated local exhaust ventilation systems command specification preference in legacy factory retrofits.
North England
Department for Education condition improvement funding directs capital toward school estate air quality upgrades. Manchester and West Yorkshire authorities embed indoor environmental quality thresholds into building condition assessments. Aging HVAC infrastructure replacement cycles accelerate.
Scotland
Scottish Government heat-in-building regulations accelerate deep retrofit programs in Glasgow and Edinburgh social housing. Integrated ventilation-with-filtration packages satisfy net-zero building stock targets. Housing association framework procurement consolidates buyer power.
Wales
Local authority selective licensing schemes in Cardiff and Newport impose air quality conditions on private rental stock. Buy-to-let landlords specify compact photocatalytic oxidation units to satisfy compliance deadlines. Developer specifications increasingly bundle mechanical ventilation with heat recovery in new residential towers.
United Kingdom Air Purifier Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the United Kingdom air purifier market. Domestic assembly operations face margin pressure from German and Swiss filter media supply concentration. Three archetypes dominate: premium consumer brands leveraging domestic R&D footprints, HVAC-integrated systems specialists, and medical-grade certification holders. Competitive intensity centers on procurement framework penetration and predictive maintenance service bundling.
Among UK-anchored premium positioning holders, Dyson Limited exemplifies the domestic R&D-driven archetype. Daikin Airconditioning UK Ltd. and Koninklijke Philips N.V. represent the HVAC-integrated and medical-grade certification tiers respectively. These three occupy positions spanning residential smart-enabled units through NHS procurement channels.
| Leading Market Players |
|---|
| Dyson Limited |
| Daikin Airconditioning UK Ltd. |
| Honeywell International Inc. |
| Koninklijke Philips N.V. |
| The Camfil Group |
| Panasonic UK & Ireland |
| Samsung Electronics (UK) Ltd. |
| MANN+HUMMEL GmbH |
| Blueair AB |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between medical-device HEPA specifications and residential commodity units manifests in both pricing power concentration and supply chain tiering across the United Kingdom air purifier market. NHS procurement protocols anchor premium pricing through MHRA-registered channels, while unbranded imports compete on landed cost through e-commerce platforms.
Pricing Analysis
Bundled predictive maintenance contracts versus unbundled hardware-only transactions now define the dominant pricing split in commercial segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with MHRA-registered UV-C systems commanding substantial premiums over BSI-compliant residential units. Cost compression in activated carbon-integrated models is intensifying because Southeast Asian charcoal supply volatility feeds through to UK assemblers. Social housing consortia exhibit highest price sensitivity, while acute NHS trusts prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss microglass HEPA paper production, where specialty chemical corridors control high-efficiency grades specified in NHS contracts. UK assembly operations draw from Southeast Asian coconut shell charcoal processors for activated carbon beds and Chinese sensor component manufacturers for IoT-enabled units. Tariff exposure on carbon media imports creates margin instability for mid-tier manufacturers. Distribution runs through HVAC wholesale networks for commercial projects, bypassing traditional electrical retail channels.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in service revenue unbundling and premium-tier certification investments, as electrochemical sensor cost collapse enables predictive maintenance subscription models.
For Market Incumbents: Anchor defensive positioning through backward integration into filter media supply and exclusive framework agreements with housing association consortia. Certification investment in MHRA device registration creates switching costs against emerging Asian manufacturers. Channel control through direct NHS procurement hub relationships protects specification influence from distributor disintermediation. For New Entrants and Emerging Players: Facilities management contractors represent the most accessible channel partner type for subscription-based service penetration. White-space targets include Scotland's social housing deep retrofit programs and West Midlands manufacturing corridor occupational health compliance mandates. A go-to-market angle emphasizing IoT-enabled predictive maintenance bypasses incumbent hardware margin compression. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented distributor networks lose procurement influence to direct manufacturer relationships. Long-term viability favors asset-light designers with captive certification pathways over capital-heavy assemblers exposed to input volatility. Acquisition targets should display housing association framework penetration and aftermarket service revenue traction. The signal to watch is Department for Education capital program acceleration in North England school estate upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Device Registration Investment | Unlocks NHS procurement eligibility and acute trust specification preference. |
| Housing Association Framework Penetration | Consolidates buyer power and enables volume-based tendering in social housing. |
| Predictive Maintenance Service Launch | Converts hardware transactions into recurring revenue through sensor-embedded diagnostics. |
| Backward Integration into Filter Media | Reduces single-source dependency on German and Swiss microglass suppliers. |
| Scotland Net-Zero Retrofit Partnership | Captures integrated ventilation-filtration demand from Glasgow and Edinburgh social housing. |
Research Methodology
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each territory combined with secondary validation. Interviews with NHS estates directors, housing association procurement leads, HVAC contractors, and sensor technology engineers informed demand-side assumptions. Secondary sources include DEFRA air quality monitoring data, NHS procurement hub contract disclosures, Building Regulations Part F amendment documentation, and BSI certification registries. Bottom-up unit shipment estimates triangulate against top-down addressable market sizing.
Granularity-level modeling disaggregates volume and value across product type, technology integration depth, end-user sector, and distribution channel throughout the forecast period. Segment-specific CAGRs derive from regulatory compliance timeline analysis and capital program funding trajectories. Industry-specific inputs encompass NHS estate refurbishment schedules, Department for Education condition improvement fund allocations, and Scottish Government heat-in-building regulation implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Building Regulations amendments and activated carbon supply chain disruptions. Forecasts reflect documented assumptions regarding DEFRA Clean Air Strategy enforcement intensity and MHRA device classification pathway stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Electric Blankets Market
Household Items
Snow Blower Market
Household Items
Leaf Blower Market
Household Items
Dishwashing Products Market
Household Items
Electric Air Freshener Market
Household Items
Tablet Tissue Paper Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
Insulated Tumblers Market
Household Items
Car Air Freshener Market
Household Items
Soap Tablet Market
Household Items
Smart Spin Mop Market
Household Items
Candle Air Fresheners Market
Household Items
Smart Shower Market
Household Items
Mirror Holder Market
Household Items
Multi Pocket Holders Market
Household Items
Water Purifier Bottle Market