
 Japan Home Appliances Market | 2026-2036
Japan Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Home Appliances Market Foresight
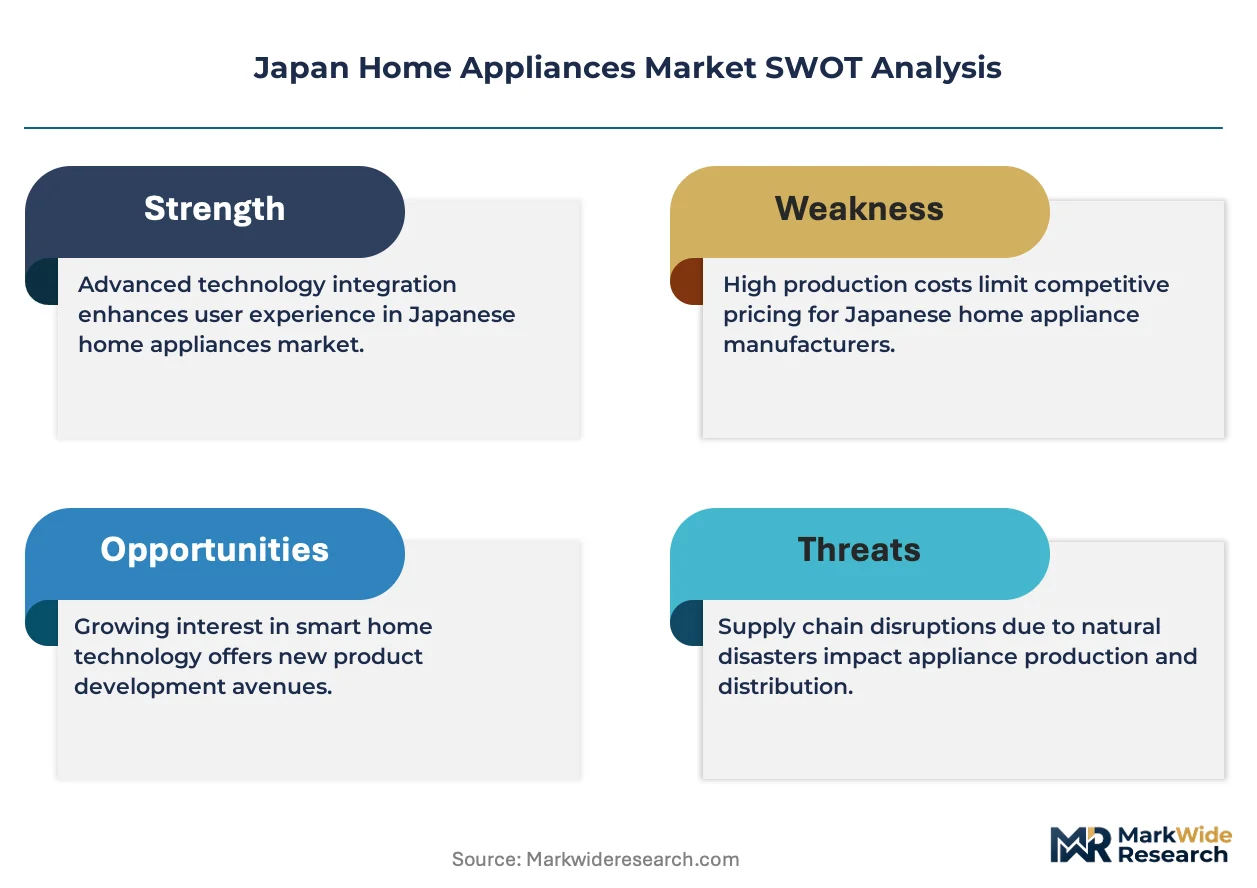
Japan is narrowing its manufacturing focus toward premium, energy-efficient home appliances as domestic labor costs rise and export competition intensifies. Panasonic Corporation leverages its vertical integration into compressor and inverter technologies to sustain margin leadership in refrigeration and climate control. Hitachi Global Life Solutions anchors its position through advanced washing systems with AI-driven load sensing. Sharp Corporation competes aggressively in smart kitchen segments, differentiating through proprietary plasma cluster ion air purification integrated across its product line.
Japan home appliances encompass electrically powered devices designed for domestic tasks including food preservation, garment care, thermal cooking, and ambient climate management, typically operating at 100V/50-60Hz with power consumption profiles measured under JIS C 9801 testing protocols. These products serve residential and commercial end users by automating labor-intensive household operations while optimizing energy and water utilization. Refrigerators command the largest revenue pool among product types, driven by premiumization toward multi-door configurations with vacuum insulation panels. Air conditioners represent the fastest-growing category, propelled by heat wave frequency and regulatory pressure under the F-Gas Regulation alignment. Smart appliances technology is displacing traditional controls as IoT-enabled platforms allow remote diagnostics and demand-response integration with utility grids.
METI enforces the Top Runner Program, which mandates that manufacturers meet progressively stricter energy efficiency benchmarks for refrigerators, air conditioners, and washing machines, directly shaping product development roadmaps and replacement demand timing. JIS standards and the Act on Rationalizing Energy Use collectively establish technical barriers that favor established domestic manufacturers with testing infrastructure and compliance expertise. PMDA oversight extends to appliances with health-related claims, such as air purifiers and humidifiers, adding a secondary regulatory layer for product positioning. Stakeholders must monitor how impending revisions to carbon neutrality targets and circular economy requirements for appliance recycling reshape cost structures and design priorities.
Market Dynamics
METI's Top Runner Program compresses replacement cycles for refrigerators and air conditioners by mandating progressively stricter energy efficiency benchmarks, forcing manufacturers to accelerate R&D cadences while urban households in Tokyo and Osaka upgrade to connected kitchen ecosystems.
Growth Catalysts
- Regulatory pressure from METI:The Top Runner Program mandates efficiency improvements that trigger premature replacement of aging appliances in Japanese households.
- Heat wave frequency:Rising ambient temperatures in the Greater Tokyo Area and Kansai region accelerate demand-response-ready air conditioning systems.
- Vacuum insulation panels:Multi-door refrigerator configurations with advanced thermal barriers command premium positioning in space-constrained urban apartments.
Market Restraints
- Copper and rare earth input volatility:Compressor manufacturing depends on concentrated upstream supply chains vulnerable to price swings.
- Domestic labor cost escalation:Manufacturing wages in Japan constrain mass-market appliance pricing flexibility versus Southeast Asian assembly alternatives.
- Apartment size limitations:Floor area constraints in Tokyo prefecture housing stock cap unit dimensions and refrigeration volume demand.
Strategic Opportunities
- Utility grid integration:IoT-enabled demand-response platforms allow appliances to participate in Tokyo Electric Power Company load-balancing programs.
- Health-claim air treatment:PMDA oversight of air purifiers and humidifiers creates certification-based differentiation for plasma cluster ion technologies.
- Rural prefecture penetration:Tohoku and Hokkaido regions show underdeveloped smart appliance adoption relative to Greater Tokyo saturation.
Industry Challenges
- Firmware integration complexity:Legacy appliance architectures resist seamless retrofitting with IoT connectivity stacks and cloud diagnostic protocols.
- JIS C 9801 testing bottlenecks:Certification timelines for revised energy consumption measurement protocols delay product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Home Appliances Market |
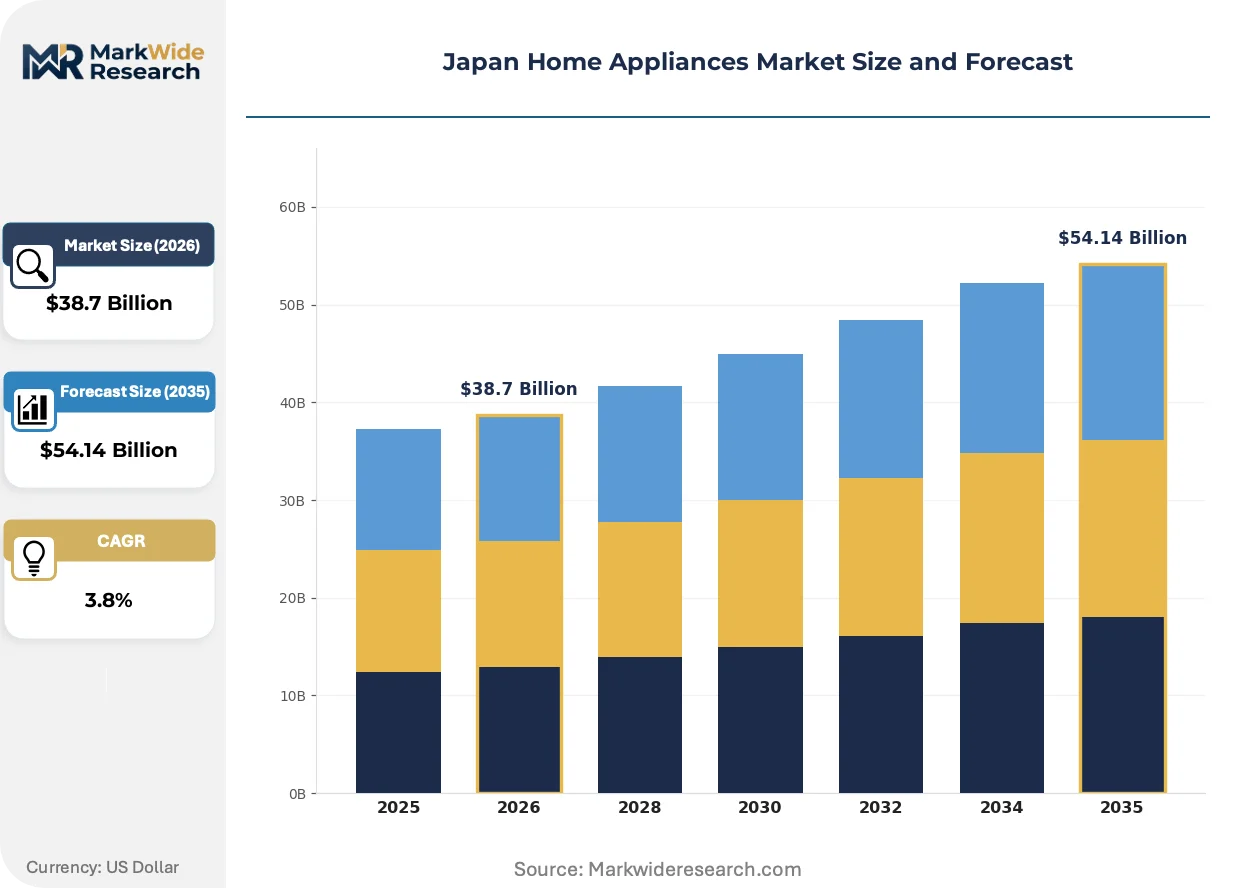
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Air Conditioners End User: Residential, Commercial, Retail, Hospitality Distribution Channel: Online, Offline, Direct Sales, Retail Chains Technology: Smart Appliances, Energy-Efficient, IoT-Enabled, Traditional |
| Companies Covered | Panasonic Corporation, Hitachi Global Life Solutions, Sharp Corporation, Toshiba Corporation, Mitsubishi Electric Corporation, Daikin Industries, Rinnai Corporation, Zojirushi Corporation, Tiger Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Home Appliances Market Shifts & Advancements
Digital twin architectures are virtualizing product development cycles, compressing time-to-market for energy-efficient designs while regulatory pressure from METI and PMDA reshapes compliance roadmaps.
Edge computing modules embedded in refrigerator and climate control units are virtualizing diagnostic and optimization functions previously handled by centralized cloud infrastructure. Tokyo-area utilities and appliance manufacturers deploy these distributed processors to enable real-time load balancing without latency-dependent internet connectivity. This architecture is virtualizing the traditional service model by shifting predictive maintenance algorithms directly onto device hardware.
METI's impending revisions to circular economy requirements for appliance recycling impose new design-for-disassembly mandates on refrigerator and washing machine manufacturers. The regulation forces material passport documentation and rare earth recovery protocols that elevate production costs. Air conditioner manufacturers face the steepest compliance burden due to F-Gas Regulation alignment requirements for refrigerant containment and end-of-life chemical recovery.
Japanese households are consolidating appliance procurement around ecosystem bundles rather than single-unit purchases. Retail channels in Osaka and Nagoya report rising attachment rates for connected kitchen suites sold alongside climate control packages. This bundling behavior concentrates purchasing power with vertically integrated manufacturers capable of cross-category interoperability certification under JIS standards.
Japan Home Appliances Market Segmentation
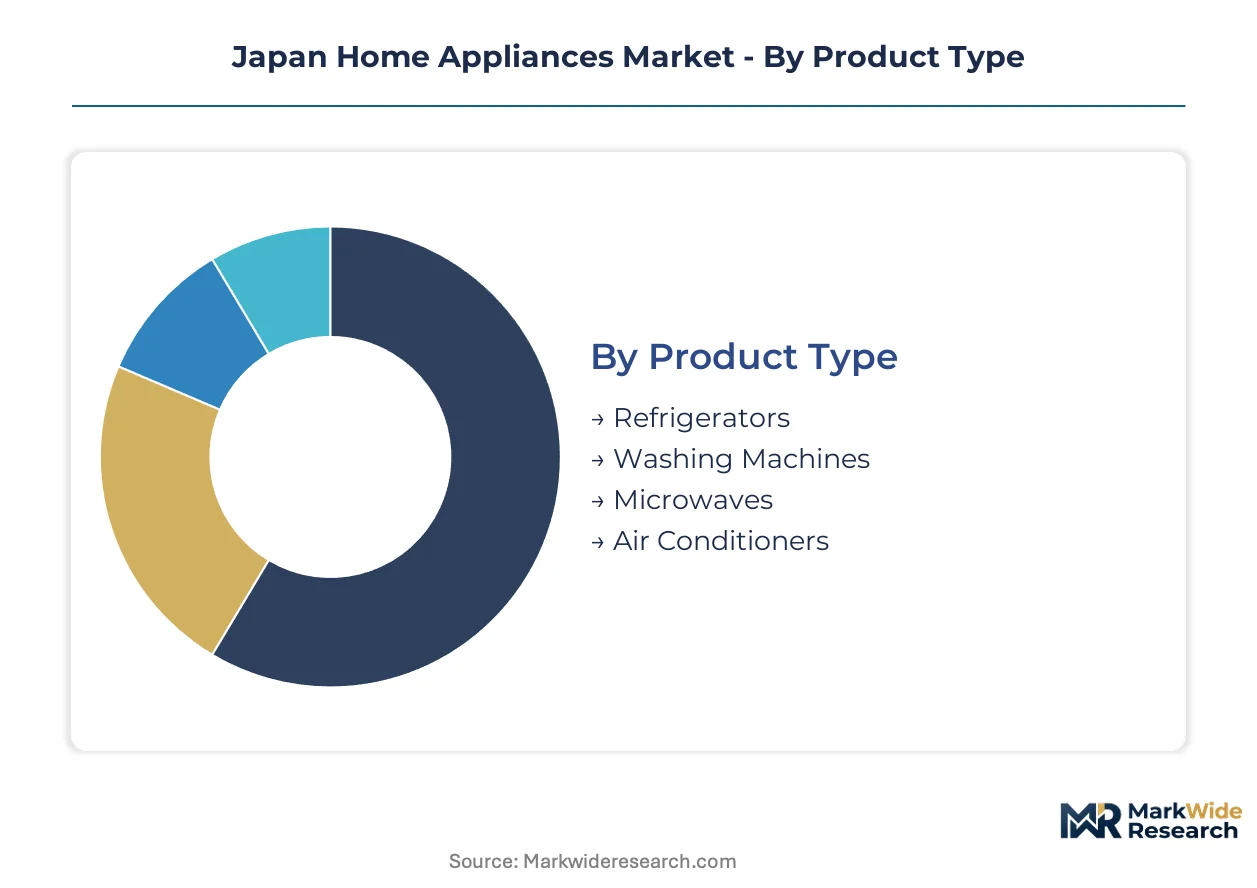
Segmentation in Japan's home appliances market reveals distinct service and margin profiles across product categories. After-sales service intensity varies dramatically by segment, shaping manufacturer investment in technical support infrastructure and spare parts logistics networks throughout the archipelago.
Product Type:
After-sales service intensity peaks with refrigeration and climate control systems requiring specialized technician dispatch and refrigerant handling certification.
- Refrigerators:Multi-door configurations with vacuum insulation panels demand precision compressor maintenance and sealed system repairs. Tokyo and Osaka prefectures concentrate replacement demand as METI Top Runner deadlines accelerate upgrade cycles for aging units.
- Air Conditioners:Split-system and heat-pump variants require biannual filter maintenance and refrigerant recovery protocols under F-Gas Regulation alignment. Kansai region heat wave frequency drives the steepest service call volume growth among all product types.
- Washing Machines:Drum and top-load formats need less frequent technician intervention but generate substantial water inlet valve and drainage pump replacement demand.
- Microwaves:Magnetron failure and door seal degradation represent primary service events; compact urban kitchens favor countertop units with minimal field repair economics.
By volume, washing machines lead Japanese household penetration. By growth pace, air conditioners are expanding most quickly.
End User:
Cost tier differentiation separates residential procurement from commercial volumes, with hospitality and retail segments commanding premium pricing for durability specifications.
- Residential:Individual household purchasers prioritize compact footprints and JIS C 9801 efficiency ratings for space-constrained Tokyo apartments. Replacement timing accelerates under METI regulatory pressure.
- Commercial:Laundromat operators and food service establishments demand extended warranty coverage and rapid response service level agreements.
- Retail:Appliance showroom and electronics retail chains require climate control systems with continuous operation reliability and remote monitoring capabilities.
- Hospitality:Ryokan and hotel operators specify whisper-quiet refrigeration and air conditioning with plasma cluster ion air purification for guest room differentiation.
Residential segments dominate unit shipments. Hospitality applications command the highest average selling prices per installation.
Distribution Channel:
Volume concentration tilts toward offline retail, though direct manufacturer engagement is gaining share in connected appliance categories requiring installation coordination.
- Online:E-commerce platforms capture growing microwave and small appliance volume but struggle with refrigerator and air conditioner delivery complexity.
- Offline:Yodobashi Camera, Bic Camera, and regional electronics chains anchor the majority of climate control and refrigeration transactions with bundled installation services.
- Direct Sales:Panasonic and Hitachi maintain factory-direct channels for premium multi-door refrigerator and AI-enabled washing system lines.
- Retail Chains:Home center networks including Cainz and Komeri distribute compact appliances to rural Tohoku and Hokkaido prefectures with limited brand boutique presence.
Offline channels handle the greatest transaction value. Direct sales channels are climbing the fastest as manufacturers capture margin from ecosystem bundling.
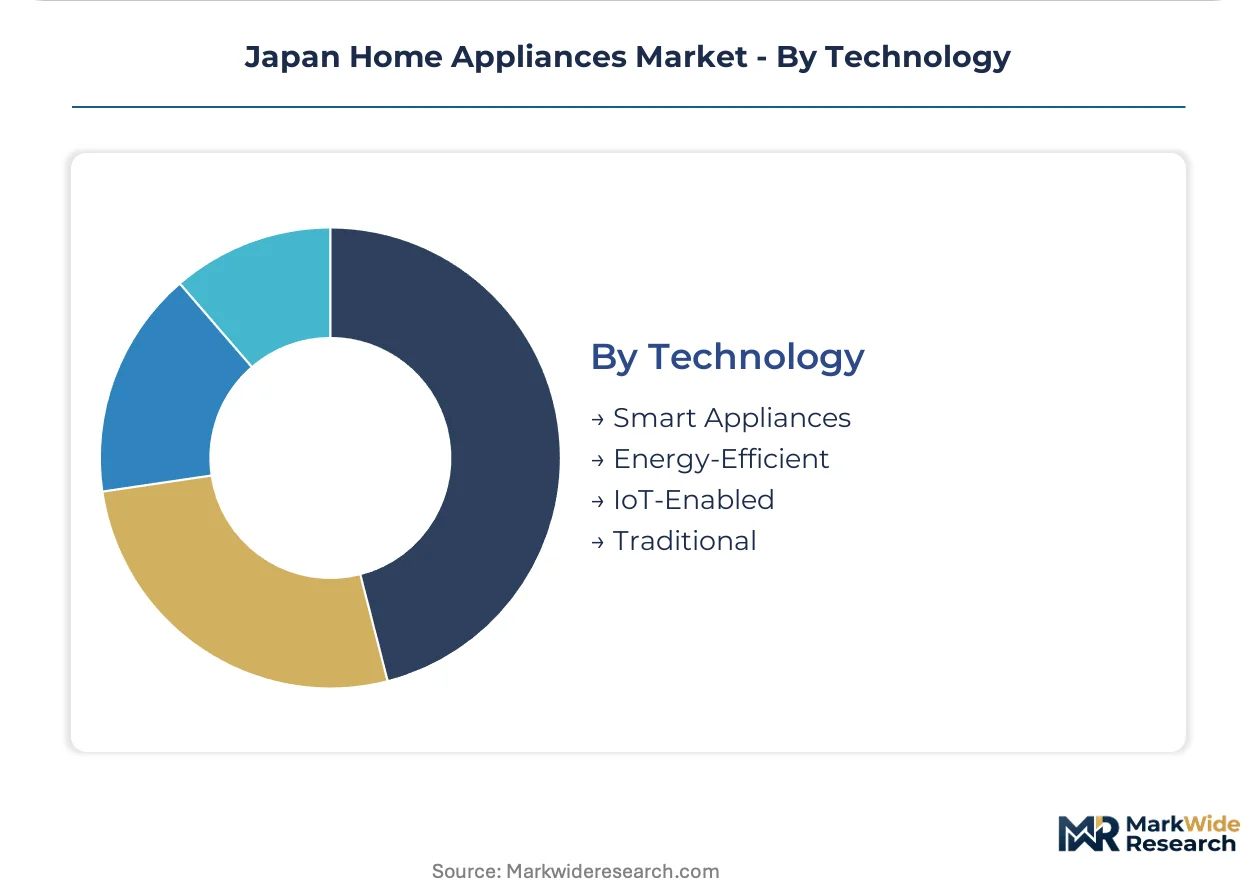
Technology:
Customer type stratification separates early IoT adopters in Greater Tokyo from price-sensitive traditional appliance purchasers in peripheral prefectures.
- Smart Appliances:Wi-Fi enabled refrigerators and climate control units integrate with Tokyo Electric Power Company demand-response programs. Firmware update requirements create ongoing manufacturer-customer relationships beyond point-of-sale.
- Energy-Efficient:Top Runner Program compliance mandates inverter compressors and advanced insulation across all major product categories, with efficiency labeling driving purchasing decisions.
- IoT-Enabled:Edge computing modules embedded in appliance hardware enable predictive maintenance algorithms without cloud dependency, particularly valued in rural Hokkaido with intermittent connectivity.
- Traditional:Non-connected mechanical controls persist in rental apartment stock and budget-conscious segments where replacement cycles extend beyond regulatory optimums.
Energy-efficient technology dominates current installed base. IoT-enabled systems are gaining share fastest as utility grid integration incentives expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration tilts toward the Greater Tokyo Area and Osaka-Kobe industrial corridor, where compressor fabrication and inverter assembly anchor the domestic supply base. Prefecture-level demand variation reflects housing density, climate exposure, and regulatory compliance deadlines.
Kanto/Tokyo
Space-constrained apartments drive compact multi-door refrigerator demand with vacuum insulation panels. METI's Top Runner Program accelerates replacement cycles in Tokyo, Chiba, and Saitama prefectures. The Keihin industrial zone sustains Panasonic and Hitachi manufacturing facilities with captive compressor production.
Kansai/Osaka
Heat wave frequency in Osaka, Kyoto, and Hyogo prefectures expands demand-response-ready air conditioning installations. The Osaka-Kobe corridor hosts Sharp Corporation's smart kitchen ecosystem development. Local utilities integrate IoT-enabled appliances into Kansai Electric Power Company load-balancing programs.
Chubu/Nagoya
Toyota-adjacent supply chain discipline influences appliance manufacturing quality standards in Aichi, Gifu, and Shizuoka prefectures. Mitsubishi Electric anchors climate control production in the region. Nagoya-based retail chains report rising attachment rates for connected kitchen bundles.
Hokkaido
Extended heating seasons sustain demand for high-efficiency air-source heat pumps in Sapporo and Asahikawa. JIS C 9801 compliance timelines lag national averages due to remote service infrastructure gaps. Local utilities pilot edge-computing modules for intermittent connectivity environments.
Kyushu
Fukuoka and Kitakyushu manufacturing bases export compressors and inverter components to Southeast Asian assembly plants. Summer humidity drives dehumidifier and air purifier demand with plasma cluster ion differentiation. Regional power utilities test demand-response integration with residential cooling systems.
Japan Home Appliances Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with captive compressor and inverter technologies. The vendor base organizes around three archetypes: vertically integrated conglomerates with in-house semiconductor fabrication, specialist climate-control manufacturers with refrigerant expertise, and precision-engineering houses focused on compact thermal solutions. Competitive moves concentrate on ecosystem bundling across kitchen and climate categories, plus backward integration into rare-earth magnet supply chains for compressor motors.
Within the conglomerate tier, Panasonic Corporation, Hitachi Global Life Solutions, and Sharp Corporation occupy positions defined by cross-category interoperability certification and JIS standards compliance. Panasonic exemplifies the vertically integrated archetype through captive compressor manufacturing. Hitachi represents AI-enabled washing system specialization. Sharp anchors smart kitchen platform development with air purification integration. These three entities collectively shape regulatory engagement with METI and PMDA while setting efficiency benchmarks under the Top Runner Program.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Hitachi Global Life Solutions |
| Sharp Corporation |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Daikin Industries |
| Rinnai Corporation |
| Zojirushi Corporation |
| Tiger Corporation |
| Others |
Supply & Pricing Matrix
Copper and rare earth price volatility compresses margin buffers across all pricing tiers while forcing manufacturers toward captive sourcing strategies for compressor motors. METI's Top Runner Program compliance costs and F-Gas Regulation alignment requirements reshape procurement priorities, widening the spread between premium IoT-enabled bundles and economy mechanical units.
Pricing Analysis
METI's Top Runner Program dictates the pricing tier structure across Japanese home appliances. Three-tier pricing separates premium multi-door refrigerators with vacuum insulation panels from standard inverter-equipped units and economy mechanical-control alternatives. Price differentiation hinges on JIS C 9801 efficiency certification grade and after-sales service bundling. Cost compression in economy tiers intensifies because Southeast Asian assembly alternatives undercut domestic labor rates. Commercial hospitality buyers show least price sensitivity, while residential Tokyo apartment dwellers prioritize compact footprints over absolute cost.
Supply Chain Analysis
Extended payment terms from appliance manufacturers to rare earth magnet suppliers stabilize upstream liquidity during commodity swings. Compressor fabrication draws from China, Malaysia, and domestic Kyushu facilities. Neodymium magnet and copper winding dependencies create single-source vulnerability for high-efficiency motor production. Tariff exposure on Chinese rare earth exports threatens cost structures for inverter compressor lines. Distribution runs through Yodobashi Camera and Bic Camera retail chains with bundled installation coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's home appliances sector approaches a platform-economics inflection as ecosystem bundling displaces single-unit procurement. Cross-category interoperability certification under JIS standards concentrates purchasing power with manufacturers capable of unified kitchen-climate control integration.
For Market Incumbents: Pre-empt firmware obsolescence by accelerating edge-computing module deployment across refrigerator and climate control lines. Secure captive rare earth magnet supply through backward integration into neodymium procurement channels. METI's impending circular economy design-for-disassembly mandates threaten margin structures for legacy product architectures.
For New Entrants and Emerging Players: Establish a beachhead in Hokkaido and Tohoku rural prefectures where smart appliance penetration lags Greater Tokyo saturation. Target hospitality segment air purification systems with PMDA health-claim certification as the most penetrable niche. Pursue direct utility partnership models with Hokkaido Electric Power Company for demand-response platform integration.
For Investors and Strategic Acquirers: METI's Top Runner Program deadline reshapes the acquisition landscape toward manufacturers with testing infrastructure and compliance expertise. Long-term viability favors vertically integrated entities with in-house compressor production and semiconductor fabrication capabilities. Monitor F-Gas Regulation alignment progress as the signal for refrigerant handling certification value inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Ecosystem Bundle Development | Cross-category interoperability certification under JIS standards captures consolidated household procurement budgets. |
| Edge Computing Module Integration | Tokyo Electric Power Company demand-response programs reward distributed processing without cloud dependency. |
| Rare Earth Magnet Backward Integration | Captive neodymium sourcing insulates compressor motor production from Chinese export tariff exposure. |
| PMDA Health-Claim Certification | Plasma cluster ion air purification differentiation commands hospitality segment premium positioning. |
| Rural Prefecture Direct Sales Expansion | Hokkaido and Tohoku service infrastructure gaps create first-mover advantage in underpenetrated smart appliance markets. |
Research Methodology
A spread of perspectives from appliance manufacturing executives, METI regulatory affairs specialists, Tokyo Electric Power Company grid planning officers, and Yodobashi Camera category buyers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through METI Top Runner Program filings, JIS C 9801 testing protocol documentation, and F-Gas Regulation alignment disclosures. Customs records tracking compressor and inverter component trade flows, plus utility demand-response program enrollment data, anchored supply-side calibration. Bottom-up prefecture-level shipment estimates and top-down manufacturer revenue triangulation produced convergent market sizing.
Demand-supply balance framing shaped the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end user category, distribution channel format, and technology tier with IoT connectivity status. CAGRs were derived from replacement cycle acceleration under regulatory pressure and heat wave frequency correlation with climate control demand. Forecast inputs incorporated METI efficiency benchmark revision timelines and PMDA health-claim certification pipeline status.
Stress conditions across copper price bands, rare earth export restriction scenarios, and JIS testing protocol revision timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through and ecosystem bundling attachment rate trajectories. Macroeconomic deviation, regulatory timeline shifts, or breakthrough thermal insulation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Small Home Appliances Market
Home Appliances
North America Luxury Appliance Market
Home Appliances
Built-In Hobs Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
Undercounter Refrigerators Market
Home Appliances
UK Household Appliances Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
United Kingdom Home Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
Asia-Pacific Small Home Appliances Market