
 LED Tube Market | 2026-2036
LED Tube Market Size, Share, and Industry Trends Forecast 2026-2036
LED Tube Market Foresight
China's Guangdong province is reconfiguring regional supply dynamics through concentrated LED packaging and tube assembly capacity. Signify Holding leverages vertical integration across phosphor sourcing and driver manufacturing to sustain cost leadership in European exports. Cree Lighting anchors its position through silicon carbide substrate expertise that differentiates thermal performance in high-lumen commercial deployments. ams OSRAM competes by controlling premium emitter die supply to tier-one fixture OEMs.
An LED tube is a linear solid-state lighting device comprising an aluminum heat sink, polycarbonate or glass diffuser, and SMD LED array operating typically at 100-150 lumens per watt, designed to replace fluorescent T8 and T5 lamps in commercial and industrial ceiling grids. Indoor product types dominate volume shipments due to the scale of office, education, and healthcare retrofit cycles, though Smart tubes command margin premiums through integrated sensors and networked controls. Direct Wire technology leads replacement demand where ballast bypass simplifies maintenance, while Plug and Play installations retain share in facilities prioritizing minimal labor disruption during upgrades.
China's SAMR enforces GB 30255 efficiency standards that phase out sub-100 lm/W products, while the EU Ecodesign Directive through national regulators like Germany's KBA-aligned building codes mandates minimum efficacy for public procurement. India's BIS certification under the CEA's energy efficiency labeling program creates compliance barriers for unqualified imports. Stakeholders must monitor divergence between regional efficiency thresholds and wireless interoperability standards as procurement specifications harden.
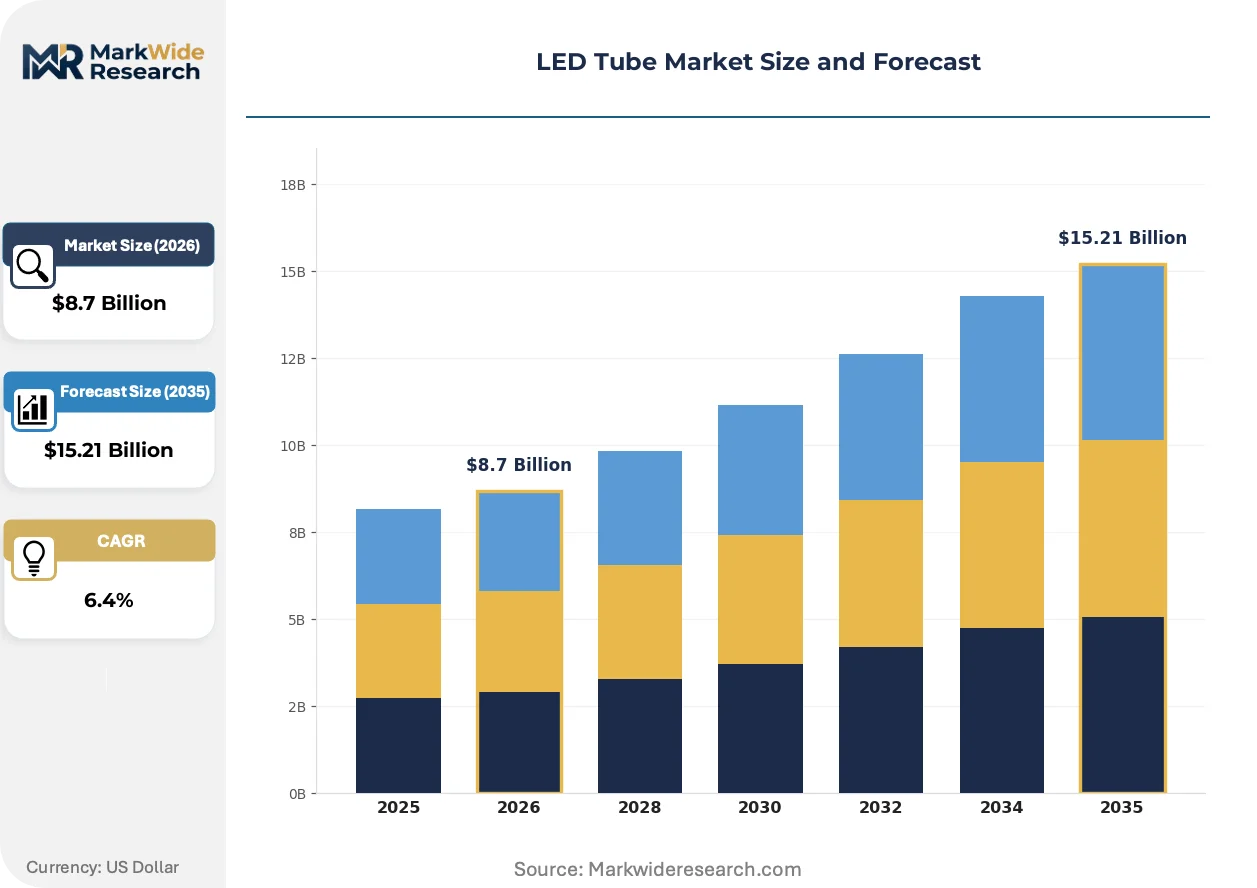
Market Dynamics
Ballast bypass retrofit cycles and China's GB 30255 efficiency mandates are compressing replacement timelines while concentrating procurement around certified high-efficacy suppliers. This structural pressure favors vertically integrated manufacturers with captive phosphor and driver capacity.
Growth Catalysts
- Commercial retrofit mandates:Germany's KBA-aligned building codes and EU Ecodesign Directive minimum efficacy rules are accelerating T8 and T5 fluorescent replacement in office and retail infrastructure.
- GB 30255 efficiency standards:China's SAMR enforcement phases out sub-100 lm/W products, eliminating low-tier competition and consolidating demand around certified domestic and export-capable manufacturers.
- Urban build-out concentration:Southeast Asian manufacturing clusters and commercial real estate expansion in Vietnam and Indonesia are expanding installed base requirements for linear solid-state lighting.
Market Restraints
- Rare earth phosphor cost volatility:Europium and yttrium supply concentration in Chinese refining operations creates input price instability for high-CRI emitter formulations.
- Legacy ballast compatibility friction:Facilities with magnetic ballast infrastructure face labor-intensive dual-mode wiring assessments that delay upgrade decisions.
- Substitute technology pressure:Integrated LED panel and linear suspended fixtures are displacing retrofit tube demand in new commercial construction specifications.
Strategic Opportunities
- Smart tube sensor convergence:Integration of occupancy detection and daylight harvesting controls with DALI-2 wireless protocols opens premium specification channels in healthcare and education verticals.
- India BIS certification gap:Unqualified import barriers under CEA energy efficiency labeling create first-mover advantage for compliant suppliers in institutional procurement.
- Direct Wire technology penetration:Ballast bypass simplification enables electrical contractor channel expansion where maintenance cost reduction drives specification authority.
Industry Challenges
- Electrical contractor skill fragmentation:Variable training in dual-mode wiring and driver compatibility assessment creates installation quality inconsistency and callback liability.
- Wireless interoperability certification delays:Divergence between Zigbee, Bluetooth Mesh, and proprietary control protocols extends product validation timelines for networked tube portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Tube Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor, Outdoor, Smart, Emergency Technology: Direct Wire, Hybrid, Plug and Play, Diode Installation: Surface Mount, Recessed, Suspended, Wall Mounted End User: Commercial, Residential, Industrial, Agricultural |
| Companies Covered | Signify Holding, Acuity Brands, Cree Lighting, ams OSRAM, General Electric, Sylvania, LG Electronics, Eaton, Philips Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Tube Market Shifts & Advancements
Emitter die architecture and control protocol convergence are redefining product differentiation beyond lumen-per-watt metrics. Manufacturers now compete on thermal management integration and networked serviceability.
Chip-on-board LED arrays with silicon carbide thermal substrates are hybridizing conventional tube form factors with high-lumen commercial performance previously requiring dedicated high-bay fixtures. Large-format retail and logistics facilities in North America are specifying these configurations for 50,000-hour maintenance intervals. The technology is hybridizing price positioning between standard retrofit tubes and premium integrated luminaires.
EU Ecodesign Directive amendments through national transposition are tightening minimum efficacy thresholds and mandating repairability documentation for public procurement eligibility. German federal building codes now exclude sub-120 lm/W products from tender consideration. Commercial specification teams are responding by pre-qualifying suppliers with in-house photometric testing and circular design certifications.
Facilities management procurement is consolidating specification authority around lifecycle cost models that unbundle hardware from installation and commissioning services. Third-party energy service companies are displacing traditional distributor relationships in multi-site retail and healthcare rollouts. This pattern is most visible in US and UK markets where power purchase agreements and performance contracting dominate institutional retrofit finance.
LED Tube Market Segmentation
LED tube market segmentation reveals divergent service intensity requirements across installation complexity and control integration levels. Procurement specifications now weight lifecycle maintenance obligations alongside upfront hardware costs, reshaping supplier qualification criteria.
Product Type:
After-sales service intensity varies sharply across product categories, with sensor-integrated and emergency-rated configurations demanding specialized commissioning support and extended warranty terms.
- Indoor:Standard aluminum heat sink and polycarbonate diffuser configurations dominate office, education, and healthcare retrofit volume. Demand concentrates in Southeast Asian manufacturing clusters where urban commercial build-outs expand installed base requirements.
- Smart:Integrated occupancy detection and daylight harvesting controls with DALI-2 wireless protocols command premium margins. Healthcare and education verticals in Germany and the UK specify these for networked serviceability and 50,000-hour maintenance intervals.
- Outdoor:IP65-rated enclosures with enhanced thermal management serve parking structures and covered walkways.
- Emergency:Battery backup and inverter-integrated variants require UL 924 or equivalent safety certification and specialized installation protocols.
By volume, Indoor leads. By growth pace, Smart is expanding most quickly.
Technology:
Cost tier stratification separates ballast-dependent legacy compatibility from simplified electrical infrastructure approaches that reduce total installed cost.
- Direct Wire:Ballast bypass installation eliminates magnetic and electronic ballast compatibility issues, reducing long-term maintenance liability. Electrical contractor channels in North America specify these where labor cost reduction drives procurement authority.
- Plug and Play:Compatible with existing electronic ballasts to minimize installation disruption. Facilities with limited maintenance windows in Japan and South Korea retain this specification for operational continuity.
- Hybrid:Dual-mode wiring accommodates both ballast and direct wire configurations.
- Diode:Discrete emitter architectures for specialized high-CRI applications.
Direct Wire dominates new specification. Plug and Play retains defensive share in risk-averse procurement.
Installation:
Application environment dictates mounting hardware complexity and associated labor cost structures.
- Surface Mount:Direct ceiling grid attachment for T8 and T5 fluorescent replacement in standard commercial infrastructure. Volume concentrates in US office retrofit cycles driven by IRA-aligned efficiency incentives.
- Recessed:T-bar integration for clean aesthetic specifications in healthcare and institutional settings.
- Suspended:Cable or rod mounting for high-bay industrial and retail applications requiring directional adjustability.
- Wall Mounted:Vertical surface applications in corridors and storage facilities.
Surface Mount leads volume. Suspended shows steepest expansion trajectory in logistics facility specifications.
End User:
Customer type determines specification authority concentration and procurement financing mechanisms.
- Commercial:Office, retail, and hospitality retrofits dominate absolute volume. Germany's KBA-aligned building codes and EU Ecodesign Directive mandates accelerate T8 and T5 replacement timelines.
- Industrial:Manufacturing and warehousing applications prioritize high-lumen output and extended maintenance intervals.
- Residential:Limited penetration due to fixture compatibility constraints and consumer installation skill barriers.
- Agricultural:Controlled environment horticulture and livestock facility applications with moisture-resistant requirements.
Commercial leads volume. Industrial is climbing fastest on logistics build-out concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB 30255 enforcement is compressing replacement timelines across China's commercial building stock while concentrating procurement around certified high-efficacy suppliers. Germany's KBA-aligned building codes and the EU Ecodesign Directive are accelerating T8 and T5 fluorescent replacement in European office infrastructure. Southeast Asian manufacturing clusters in Vietnam and Indonesia are expanding installed base requirements as urban commercial build-outs proceed.
China
Guangdong province hosts concentrated LED packaging and tube assembly capacity serving domestic retrofit programs and export markets. SAMR's GB 30255 standards phase out sub-100 lm/W products, eliminating low-tier competition and consolidating demand around certified manufacturers. Shenzhen and Dongguan industrial zones are scaling automated surface-mount production lines to meet efficiency threshold compliance.
Germany
Federal building codes aligned with KBA standards now exclude sub-120 lm/W products from public procurement tender consideration. The EU Ecodesign Directive's national transposition mandates repairability documentation and minimum efficacy thresholds for institutional specifications. Industrial zones in North Rhine-Westphalia and Bavaria are pre-qualifying suppliers with in-house photometric testing and circular design certifications.
United States
IRA-aligned efficiency incentives are accelerating office retrofit cycles in major metropolitan commercial corridors. OSHA workplace lighting standards and state-level energy codes create compliance layering that favors certified high-efficacy suppliers. The Southeast and Midwest manufacturing belts are seeing electrical contractor channel expansion for Direct Wire ballast bypass installations.
Vietnam
Manufacturing cluster expansion in northern industrial provinces is driving commercial real estate build-outs requiring linear solid-state lighting infrastructure. The Ministry of Industry and Trade's energy efficiency labeling program is tightening import compliance barriers. Ho Chi Minh City and Hanoi metropolitan areas are concentrating demand from logistics facility specifications and retail infrastructure development.
India
Bureau of Indian Standards certification under the CEA's energy efficiency labeling program creates procurement barriers for unqualified imports in institutional segments. Maharashtra and Gujarat industrial corridors are expanding manufacturing capacity to serve domestic commercial retrofit demand. Delhi-NCR and Bangalore metropolitan regions are specifying high-efficacy tubes for healthcare and education verticals with networked controls integration.
LED Tube Market Competitive Landscape
Capability concentration sits with vertically integrated phosphor and driver specialists; scale advantage sits with diversified lighting conglomerates with established electrical contractor channels. The market structure separates into three tiers: captive emitter die suppliers controlling premium OEM relationships, assembly specialists with regional certification advantages, and diversified industrial conglomerates leveraging existing fixture distribution. Two competitive moves dominate: backward integration into phosphor sourcing and driver manufacturing to sustain cost leadership, and strategic partnerships with energy service companies to capture multi-site retrofit finance flows.
Within the vertically integrated tier, Signify Holding and ams OSRAM exemplify archetypes of upstream control over critical emitter and phosphor supply chains. Cree Lighting occupies a position representing silicon carbide substrate expertise for thermal performance differentiation. These three anchors illustrate how competitive positioning separates between those controlling premium die supply to tier-one fixture OEMs and those leveraging captive manufacturing capacity for export cost leadership.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| Cree Lighting |
| ams OSRAM |
| General Electric |
| Sylvania |
| LG Electronics |
| Eaton |
| Philips Lighting |
| Others |
Supply & Pricing Matrix
Rare earth phosphor cost volatility from Chinese europium and yttrium refining concentration determines both the premium spread for high-CRI emitter formulations and the geographic clustering of backward-integrated manufacturers. Procurement teams now weight captive phosphor sourcing against spot-market exposure when qualifying suppliers for multi-site retrofit contracts.
Pricing Analysis
Export pricing from Guangdong province runs 15-25 percent below European domestic production after accounting for Germany's KBA-aligned certification overhead. Three-tier pricing structure across premium, standard, and economy levels separates DALI-2 networked configurations from basic Direct Wire retrofits and unbranded commodity tubes. Cost compression in the economy tier is intensifying because India's BIS certification barriers are redirecting surplus Chinese capacity into price-sensitive Southeast Asian markets. Electrical contractor channels in North America show least price sensitivity where lifecycle maintenance contracts bundle hardware with installation services.
Supply Chain Analysis
Contract manufacturing concentrates in Shenzhen and Dongguan industrial zones where Foxconn and Luxshare hold automated surface-mount capacity for LED packaging and tube assembly. Guangdong province, Taiwan, and Vietnam host the dominant share of emitter die fabrication and final assembly operations. Raw material dependencies center on silicon carbide substrates from Cree Lighting's North Carolina operations, europium-doped phosphors from Chinese rare earth refiners, and aluminum heat sink extrusions from domestic metals processors. Single-source vulnerability in Chinese phosphor refining creates tariff exposure for high-CRI formulations. Distribution runs through electrical contractor channels in North America, energy service companies in the UK, and institutional procurement frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase driven by the convergence of EU Ecodesign Directive mandates and China's GB 30255 enforcement compressing replacement timelines across commercial building stock.
For Market Incumbents: Build certification moats around in-house photometric testing and circular design documentation to pre-qualify for German federal tender exclusion thresholds. Defensive moves center on captive phosphor sourcing agreements with Chinese rare earth refiners and DALI-2 wireless protocol certification investment. Integrated LED panel substitutes threaten retrofit tube demand in new construction specifications.
For New Entrants and Emerging Players: India's BIS certification gap under the CEA's energy efficiency labeling program offers first-mover access to institutional healthcare and education procurement. White-space targets include emergency-rated battery backup configurations requiring UL 924 certification and Smart tube sensor convergence for networked controls in German healthcare verticals. Go-to-market positioning through third-party energy service companies bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: EU Ecodesign Directive amendments reshaping the acquisition landscape favor targets with repairability documentation and premium emitter die supply relationships. Long-term viability over a multi-year horizon rests on silicon carbide thermal substrate expertise and vertical integration depth. Acquisition archetypes include mid-cap assembly specialists with regional certification advantages in India or Vietnam. Watch for divergence between Zigbee and Bluetooth Mesh protocol adoption as inflection signal for networked tube portfolio valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphor Sourcing | Captive europium and yttrium supply from Chinese refiners insulates margin from rare earth price spikes. |
| DALI-2 Wireless Protocol Certification | Germany's KBA-aligned building codes mandate networked serviceability for healthcare and education specifications. |
| Energy Service Company Partnership | Third-party ESCOs displace traditional distributors in US and UK multi-site retail retrofit finance flows. |
| India BIS Certification Investment | CEA energy efficiency labeling barriers create procurement advantage in Maharashtra and Gujarat institutional segments. |
| Silicon Carbide Thermal Substrate Scale-Up | Cree Lighting's substrate expertise differentiates high-lumen commercial performance for 50,000-hour maintenance intervals. |
Research Methodology
Desk research of customs trade databases, SEC filings from lighting conglomerates, and EU Ecodesign Directive national transposition documents preceded structured interviews with electrical contractor procurement heads, facilities management directors, LED packaging plant managers, and energy service company specification leads. Primary fieldwork combined with secondary validation from SAMR GB standard enforcement records and BIS certification registries. Bottom-up volume estimates from country-level retrofit cycle analysis were triangulated against top-down value projections from manufacturer revenue disclosures.
Assumptions held fixed across the analysis window include China's GB 30255 efficiency threshold enforcement timeline and Germany's KBA-aligned building code minimum efficacy rules. Variables modeled across the projection horizon encompass wireless protocol adoption rates, rare earth phosphor price trajectories, and electrical contractor channel penetration by Direct Wire technology. Segmentation dimensions included product type, installation complexity, control integration level, and regional regulatory cluster. CAGRs were derived from replacement cycle compression rates and urban commercial build-out intensity in Southeast Asian manufacturing clusters. Industry-specific inputs incorporated IRA-aligned efficiency incentive disbursement patterns and logistics facility specification trends.
Practitioners should monitor phosphor cost volatility, wireless interoperability certification delays, and substitute technology displacement from integrated LED panels for early signals of forecast revision. Forecasts reflect documented assumptions about regulatory enforcement continuity and commercial retrofit mandate expansion. Quarterly review of SAMR compliance audit results, EU Ecodesign Directive amendment timelines, and electrical contractor channel inventory levels is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
LED Control Unit Market
LED
France LED Lighting Market
LED
France Outdoor LED Lighting Market
LED
North America Outdoor LED Lighting Market
LED
Chip on Board LED Market
LED
US Outdoor LED Lighting Market
LED
LED Flip Chip Market
LED
Global Outdoor LED Lighting Market
LED
LED Services Market
LED
Germany Automotive LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
Programmable LED Drivers Market
LED
Middle East and Africa Indoor LED Lighting Market
LED
LED Power Supplies Market
LED
LED Mask Market
LED
China Indoor LED Lighting Market