
 Global Macular Degeneration Treatment Market | 2026-2036
Global Macular Degeneration Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Macular Degeneration Treatment Market Foresight
The capital-intensity divergence between biologics manufacturers and device-centric therapy developers is unwinding competitive boundaries in macular degeneration care. Regeneron Pharmaceuticals sustains its position through captive manufacturing of aflibercept and deep ophthalmology specialization. F. Hoffmann-La Roche navigates the landscape with sustained biosimilar defense spending and global retina clinic networks. Novartis anchors its presence through geographic dominance in European ophthalmology markets and premium pricing power.
Macular degeneration treatment encompasses pharmacologic and procedural interventions targeting retinal pigment epithelium degradation and choroidal neovascularization, with anti-VEGF agents requiring intravitreal injection at 4-8 week intervals to suppress vascular endothelial growth factor-mediated angiogenesis. The primary commercial purpose centers on preserving central visual acuity in aging populations experiencing geographic atrophy or wet-form disease progression. Anti-VEGF agents occupy the dominant revenue position due to chronic dosing requirements and established reimbursement codes, while intravitreal injection delivery mode commands the procedural volume share across ophthalmic clinics and ambulatory surgical centers. Dry macular degeneration and geographic atrophy segments represent the fastest-expanding therapy areas as complement C3 and C5 inhibitors gain regulatory traction.
FDA, EMA, and Japan's PMDA govern ophthalmic biologic approval pathways, with each agency imposing distinct visual acuity endpoint requirements and post-market safety monitoring obligations that shape clinical trial design and commercialization timelines. The EU AI Act and FDA software-as-medical-device frameworks are beginning to intersect with diagnostic imaging tools used in treatment patient selection and monitoring. Stakeholders must monitor complement inhibitor pipeline readouts and biosimilar entry sequencing to calibrate portfolio and pricing decisions.
Market Dynamics
FDA and EMA accelerated approval pathways for novel complement inhibitors are compressing development timelines and forcing established anti-VEGF franchises to defend pricing power through outcome-based contracting mechanisms.
Growth Catalysts
- EMA's PRIME designation:Expedited regulatory review for complement C3 and C5 inhibitors targeting geographic atrophy is shortening commercialization timelines for pipeline assets.
- Aging demographics in Japan:PMDA reimbursement density for intravitreal therapies aligns with the fastest-aging population cohort, concentrating demand for chronic dosing regimens.
- Gene therapy manufacturing scale-up:Viral vector production capacity expansion is enabling single-dose wet AMD interventions that challenge chronic anti-VEGF dependency.
Market Restraints
- Intravitreal injection capacity constraints:Retina specialist availability limits procedural throughput in rural United States markets, creating geographic access disparities.
- Biosimilar pricing compression:Reference product defense spending by originator firms is diverting R&D capital from novel mechanism discovery.
- EU MDR compliance costs:Diagnostic imaging device re-certification requirements are delaying AI-enabled patient selection tool deployment.
Strategic Opportunities
- Germany's DiGA pathway:Digital health application reimbursement for remote monitoring creates channel expansion potential for home-based visual acuity tracking.
- Sustained-release formulation convergence:Polymeric depot technologies combined with anti-VEGF biologics are enabling 6-month dosing intervals that reduce clinic burden.
- Underpenetrated India:Tier-2 and tier-3 city ophthalmology infrastructure expansion presents volume opportunity for cost-optimized biosimilar portfolios.
Industry Challenges
- Vitreoretinal surgeon training pipelines:Fellowship program capacity constraints in the United States and Europe limit procedural workforce expansion.
- Gene therapy cold chain complexity:Ultra-low temperature logistics requirements for AAV-based treatments create distribution infrastructure gaps in emerging markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Macular Degeneration Treatment Market |
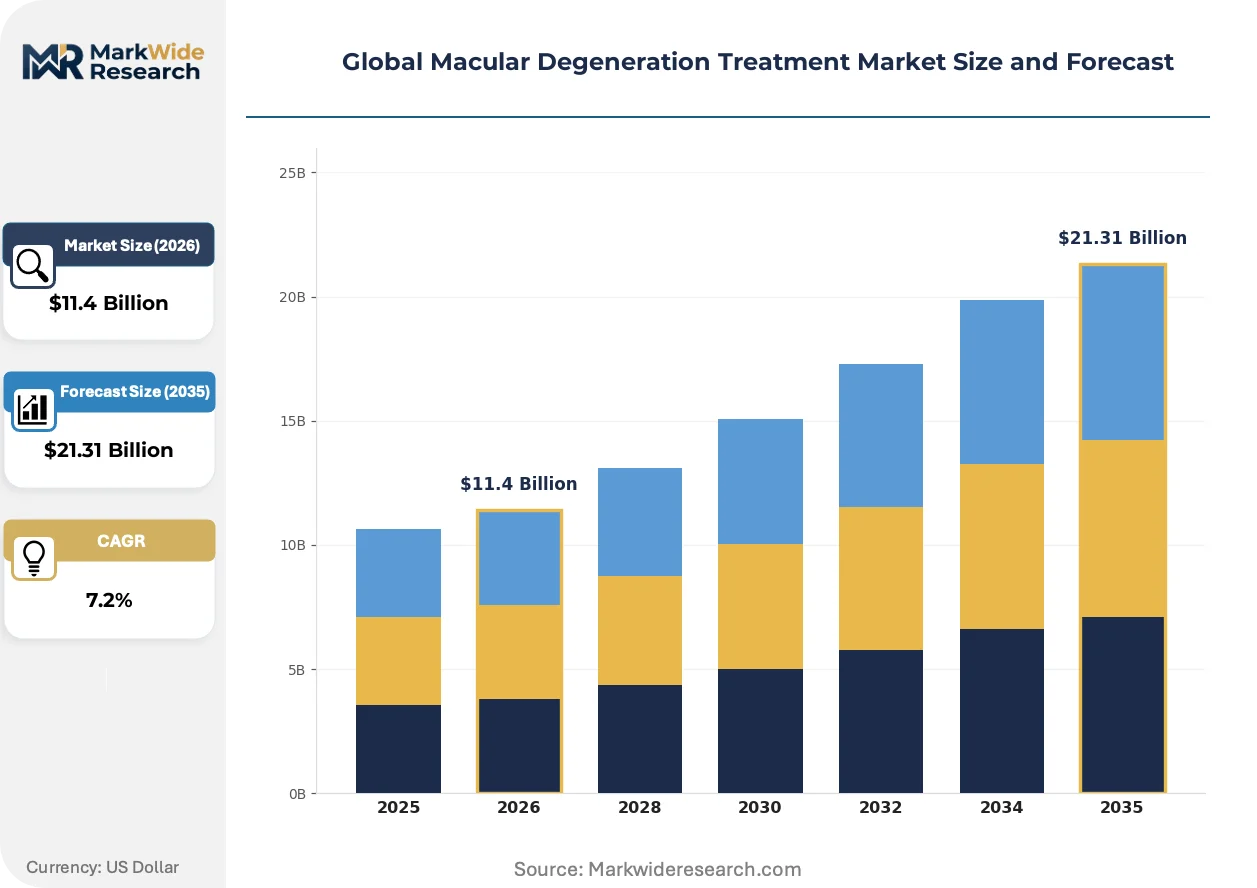
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $21.31 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-VEGF Agents, Photodynamic Therapy, Corticosteroids, Laser Therapy Therapy Area: Wet Macular Degeneration, Dry Macular Degeneration, Geographic Atrophy, Polypoidal Choroidal Vasculopathy Delivery Mode: Intravitreal Injection, Oral Medication, Topical Administration, Subretinal Injection End User: Ophthalmic Clinics, Eye Hospitals, Ambulatory Surgical Centers, Research Institutes |
| Companies Covered | Regeneron Pharmaceuticals Inc., F. Hoffmann-La Roche Ltd, Novartis AG, Bayer AG, AbbVie Inc., Apellis Pharmaceuticals Inc., Santen Pharmaceutical Co. Ltd., Bausch Health Companies Inc., Alcon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Macular Degeneration Treatment Market Shifts & Advancements
Complement inhibition mechanisms are advancing from rare disease origins into mass-market ophthalmology, while diagnostic AI tools and sustained-release delivery systems simultaneously reshape patient selection and treatment cadence.
Port delivery systems with refillable intravitreal reservoirs are displacing conventional monthly injection schedules. Ophthalmic clinics in the United States and Germany are adopting these implants at accelerating pace as physicians seek to reduce treatment burden. The technology is displacing high-frequency clinic visits and compressing the addressable market for conventional syringe-based anti-VEGF administration.
EU AI Act conformity requirements for diagnostic imaging software are mandating algorithmic transparency documentation and post-market performance monitoring. Device manufacturers must now maintain clinical validation datasets spanning diverse demographic cohorts. Retina clinics deploying optical coherence tomography AI tools face the steepest compliance adaptation costs.
Patient self-monitoring applications with home visual acuity testing are fragmenting traditional clinic-centric follow-up models. Teleophthalmology platforms in Japan and Germany are capturing monitoring encounters previously conducted in-person. This shift concentrates procedural revenue in injection-only visits while unbundling diagnostic reimbursement.
Global Macular Degeneration Treatment Market Segmentation
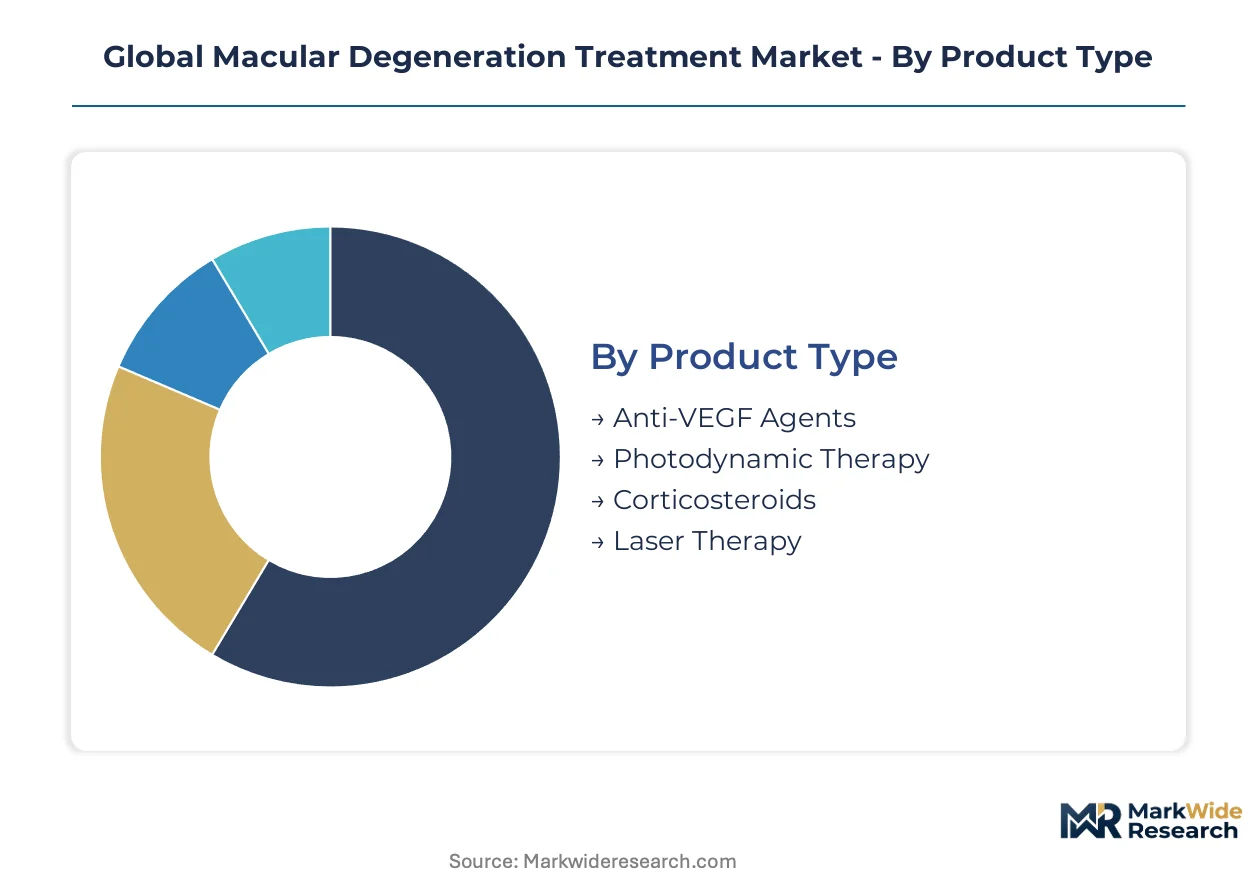
Treatment modality segmentation in macular degeneration reveals shifting competitive boundaries between chronic injectable therapies and emerging single-intervention alternatives. Portfolio positioning depends on matching reimbursement density to procedural infrastructure across distinct patient access channels.
Product Type:
Anti-VEGF agents face the most intense substitution pressure from sustained-release formulations and gene therapy candidates that threaten their chronic dosing dependency.
- Anti-VEGF Agents:Intravitreal biologics including ranibizumab, aflibercept, and brolucizumab that suppress vascular endothelial growth factor signaling. Demand concentrates in United States ophthalmic clinics where Medicare Part B reimbursement density supports monthly injection schedules. Chronic administration requirements generate recurring revenue but create treatment burden that sustains pipeline threat from longer-acting alternatives.
- Photodynamic Therapy:Verteporfin-activated laser intervention targeting choroidal neovascularization beneath the fovea. German retina specialists retain select use for polypoidal choroidal vasculopathy subtypes where anti-VEGF monotherapy response remains incomplete. Declining procedural volume reflects competitive displacement by combination regimens.
- Corticosteroids:Intravitreal steroid implants for persistent macular edema.
- Laser Therapy:Thermal photocoagulation for extrafoveal neovascular lesions.
Anti-VEGF agents retain volume leadership; sustained-release formulation convergence holds the steepest expansion curve.
Therapy Area:
Cost tier stratification separates premium-priced biologics for wet disease from emerging mass-market opportunities in dry degeneration segments.
- Wet Macular Degeneration:Neovascular form driven by choroidal vessel proliferation beneath the retina. Japanese and United States markets concentrate demand where intravitreal therapy infrastructure is most mature. Anti-VEGF dependency sustains the largest revenue pool despite biosimilar entry pressure.
- Geographic Atrophy:Advanced dry form characterized by retinal pigment epithelium atrophy expanding from the macula. Complement C3 and C5 inhibitors are gaining regulatory traction fastest in this segment. United States FDA accelerated approvals and EMA PRIME designations are compressing commercialization timelines for pipeline assets.
- Dry Macular Degeneration:Early to intermediate atrophic disease without neovascularization.
- Polypoidal Choroidal Vasculopathy:Variant neovascular subtype with branching vascular networks.
Wet macular degeneration retains volume leadership; geographic atrophy holds the steepest expansion curve.
Delivery Mode:
Application intensity varies dramatically between high-frequency clinic-based administration and patient-directed alternatives that fragment traditional care models.
- Intravitreal Injection:Direct vitreous cavity delivery via pars plana needle insertion. United States ambulatory surgical centers and ophthalmic clinics handle the dominant procedural volume. Retina specialist availability constraints in rural markets create geographic access disparities that limit expansion.
- Subretinal Injection:Surgical delivery beneath the retinal pigment epithelium for gene therapy vectors. Viral vector production scale-up is enabling single-dose wet AMD interventions. Ultra-low temperature logistics requirements create distribution infrastructure gaps limiting emerging market penetration.
- Oral Medication:Systemic complement inhibition for geographic atrophy.
- Topical Administration:Eye drop formulations with limited posterior segment penetration.
Intravitreal injection retains volume leadership; subretinal injection holds the steepest expansion curve.
End User:
Customer type concentration reflects reimbursement alignment and procedural complexity requirements that favor specialized settings over generalist care.
- Ophthalmic Clinics:Dedicated retina practices with optical coherence tomography imaging and intravitreal injection capacity. Germany and Japan show the highest clinic density per capita. Germany's DiGA pathway for digital health applications is creating channel expansion potential for remote monitoring integration.
- Ambulatory Surgical Centers:Outpatient facilities capturing port delivery system implantation and complex surgical cases. United States Medicare reimbursement codes favor ASC settings for higher-complexity procedures. Sustained-release formulation adoption is accelerating procedural migration from clinic to surgical environments.
- Eye Hospitals:Academic and tertiary referral centers handling complex cases.
- Research Institutes:Clinical trial sites for pipeline asset development.
Ophthalmic clinics retain volume leadership; ambulatory surgical centers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity due to dense reimbursement frameworks, while demand in India and rural United States markets remains acutely sensitive to out-of-pocket cost exposure. This divergence concentrates premium biologic adoption in Western Europe and East Asia while biosimilar volume accumulates in emerging economies.
United States
Medicare Part B reimbursement density sustains chronic anti-VEGF injection schedules across ophthalmic clinics and ambulatory surgical centers. FDA accelerated approval pathways for complement inhibitors are compressing commercialization timelines for geographic atrophy therapies. Retina specialist concentration in Boston, New York, and California metro areas masks severe access gaps in rural Midwest and Mountain West states.
Germany
EMA PRIME designation uptake and statutory health insurance reimbursement alignment create the lowest patient cost burden for novel therapies in Europe. Germany's DiGA pathway for digital health applications enables remote monitoring reimbursement that fragments traditional clinic-centric follow-up models. Bavaria and North Rhine-Westphalia host the densest retina specialist networks and highest intravitreal procedural volume per capita.
Japan
PMDA reimbursement density for intravitreal therapies aligns with the fastest-aging population cohort globally, concentrating demand for chronic dosing regimens. METI industrial policy supports domestic ophthalmic device manufacturing scale-up. Tokyo, Osaka, and Nagoya medical centers drive adoption of sustained-release port delivery systems that reduce treatment burden.
India
Tier-2 and tier-3 city ophthalmology infrastructure expansion presents volume opportunity for cost-optimized biosimilar portfolios as reference biologics remain inaccessible to most patients. CDSCO regulatory pathways for biosimilar approval are streamlining market entry for domestic manufacturers. Maharashtra and Karnataka state clusters concentrate retina specialist training programs and intravitreal injection capacity.
United Kingdom
NICE technology appraisal processes impose distinct cost-effectiveness thresholds that delay or restrict access to premium-priced complement inhibitors relative to German benchmarks. NHS England commissioning frameworks concentrate wet AMD treatment in specialized retina centers. London, Manchester, and Birmingham academic medical centers anchor clinical trial recruitment for pipeline gene therapy assets.
Global Macular Degeneration Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in macular degeneration treatment, with vertical integration into viral vector manufacturing and sustained-release formulation development creating separation from device-centric competitors. The upper tier combines captive biologics production with deep ophthalmology specialization, while mid-tier players compete through geographic density in reimbursement-rich markets. Three archetypes dominate: integrated biologics manufacturers with retina-focused portfolios, diversified pharma conglomerates defending anti-VEGF franchises, and emerging gene therapy specialists building single-dose alternatives. Competitive intensity centers on M&A targeting sustained-release delivery platforms and strategic partnerships bridging diagnostic AI with therapeutic selection.
Within the integrated biologics tier, Regeneron Pharmaceuticals Inc. and F. Hoffmann-La Roche Ltd exemplify contrasting defensive postures—one through captive manufacturing depth, the other through global clinic network scale. Novartis AG occupies a position bridging European geographic dominance with premium pricing power in complement inhibition. Bayer AG represents the diversified conglomerate archetype, leveraging ophthalmology as one therapeutic vertical among broader pharmaceutical portfolios. These three anchors illustrate how competitive positioning depends on matching manufacturing control to reimbursement access density across United States, German, and Japanese markets.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Bayer AG |
| AbbVie Inc. |
| Apellis Pharmaceuticals Inc. |
| Santen Pharmaceutical Co. Ltd. |
| Bausch Health Companies Inc. |
| Alcon Inc. |
| Others |
Supply & Pricing Matrix
Viral vector manufacturing scale economies in the United States and Europe concentrate production capacity among a handful of GMP-certified facilities, creating dual pressure on price floors for gene therapy candidates and forcing chronic anti-VEGF manufacturers to defend recurring revenue through outcome-based contracting mechanisms.
Pricing Analysis
Injection-only visit reimbursement drives lifetime value capture across ophthalmic clinics and ambulatory surgical centers. Three-tier pricing structure across premium biologics, biosimilar alternatives, and emerging gene therapies separates originator anti-VEGF agents from follow-on products and single-dose interventions. Cost compression in the biosimilar tier is intensifying because of reference product defense spending diverting R&D capital. Tier-2 and tier-3 city clinics in India exhibit the highest price sensitivity, while Japanese and German retina specialists demonstrate the lowest elasticity due to dense statutory reimbursement frameworks.
Supply Chain Analysis
Cold chain inventory requirements for AAV-based gene therapies extend lead times and limit geographic reach to metropolitan medical centers with ultra-low temperature infrastructure. Active pharmaceutical ingredient production draws from Switzerland, Singapore, and the United States for complement inhibitors, while viral vector manufacturing rests on capacity in Massachusetts, North Carolina, and Bavaria. Single-source vulnerability in sterile fill-finish capacity creates bottlenecks for intravitreal biologics. Distribution runs through specialty pharmacy networks and direct-to-clinic cold chain logistics for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote monitoring service layers are expanding faster than hardware-centric delivery systems, creating attach-rate opportunities for digital health platforms that fragment traditional clinic-centric follow-up models.
For Market Incumbents: Secure captive manufacturing of sustained-release formulations to defend against gene therapy substitution threat. Deepen backward integration into viral vector production capacity to control cost structure for pipeline assets. Lock in retina specialist training partnerships to limit procedural workforce expansion by competitors. For New Entrants and Emerging Players: Differentiate on home-based visual acuity tracking integrated with teleophthalmology platforms. Target tier-2 and tier-3 city ophthalmology infrastructure in India where reference biologics remain inaccessible. Pursue CDSCO biosimilar approval pathways as the fastest go-to-market angle for cost-optimized portfolios. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sustained-release delivery platform specialists with polymeric depot capabilities. Five-to-ten year viability hinges on matching manufacturing control to reimbursement access density across United States, German, and Japanese markets. Watch FDA accelerated approval readouts for complement inhibitors as the signal indicating inflection toward dry AMD addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval and EMA PRIME designation compress commercialization timelines for pipeline assets. |
| Manufacturing Scale-Up | Viral vector production capacity expansion enables single-dose wet AMD interventions challenging chronic anti-VEGF dependency. |
| Licensing Agreement | Strategic partnerships bridging diagnostic AI with therapeutic selection reshape patient selection and treatment cadence. |
| Pipeline Diversification | Complement C3 and C5 inhibitors gain regulatory traction fastest in geographic atrophy segments. |
| Reimbursement Strategy | Outcome-based contracting mechanisms defend pricing power against biosimilar entry pressure in Medicare Part B markets. |
Research Methodology
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from CMS Medicare reimbursement data, PMDA approval records, and ophthalmology society practice pattern surveys. Bottom-up patient flow modeling and top-down revenue reconciliation provided cross-check triangulation.
Variance decomposition across treatment modality, therapy area, delivery mode, and end user segments shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and price trajectory modeling. Forecast inputs incorporated retina specialist density projections, biosimilar entry sequencing assumptions, and regulatory approval probability weightings for pipeline assets.
Material uncertainties — biosimilar pricing compression velocity, gene therapy manufacturing yield improvements, and retina specialist fellowship expansion rates — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Synoptophore Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Global Anterior Uveitis Treatment Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Lazy Eye Market
Ophthalmology
3D Printed Ophthalmic Implants Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Tobramycin Eye Drop Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Superficial Punctate Keratitis Treatment Market
Ophthalmology
Vernal Keratoconjunctivitis Market
Ophthalmology
Tonometry Market
Ophthalmology
Macular Edema and Macular Degeneration Market