
 Ophthalmic Drugs and Devices Market | 2026-2036
Ophthalmic Drugs and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Drugs and Devices Market Analytics
Multi-source procurement for excimer laser components is shifting toward captive manufacturing among top-tier suppliers. Novartis leverages its integrated retina franchise to sustain biologic drug supply chains across major markets. Alcon anchors the surgical devices segment through direct control of phacoemulsification system production. Johnson & Johnson competes in the refractive surgery space with differentiated femtosecond laser platforms.
Ophthalmic drugs and devices comprise therapeutic formulations and precision instruments designed for ocular tissue intervention, including intraocular lenses with specific dioptric power ranges and anti-VEGF biologics requiring cold-chain distribution. Their primary purpose spans vision restoration, disease progression halting, and refractive error correction across clinical and surgical settings. Drug delivery systems occupy the highest-margin tier within the technology dimension due to sustained-release implant development, while telemedicine represents the fastest-expanding channel as remote diagnostic imaging protocols gain clinical validation. Glaucoma treatment commands stable volume within the application dimension, though retinal disorders attract disproportionate R&D allocation from biologic developers.
The FDA governs device premarket clearance and pharmaceutical approval pathways for the US market, while the EMA coordinates centralized marketing authorization across EU member states for ophthalmic biologics. REACH compliance shapes material selection for intraocular lens polymers and surgical instrument coatings, directly influencing supplier qualification timelines. Stakeholders must monitor how evolving AI-based diagnostic classification rules from multiple regulators reshape software-enabled device submission requirements and post-market surveillance obligations.
Market Dynamics
Hospital-based cataract surgery programs are consolidating purchasing power around femtosecond laser platforms, compressing vendor margins while accelerating platform standardization across surgical networks.
Growth Catalysts
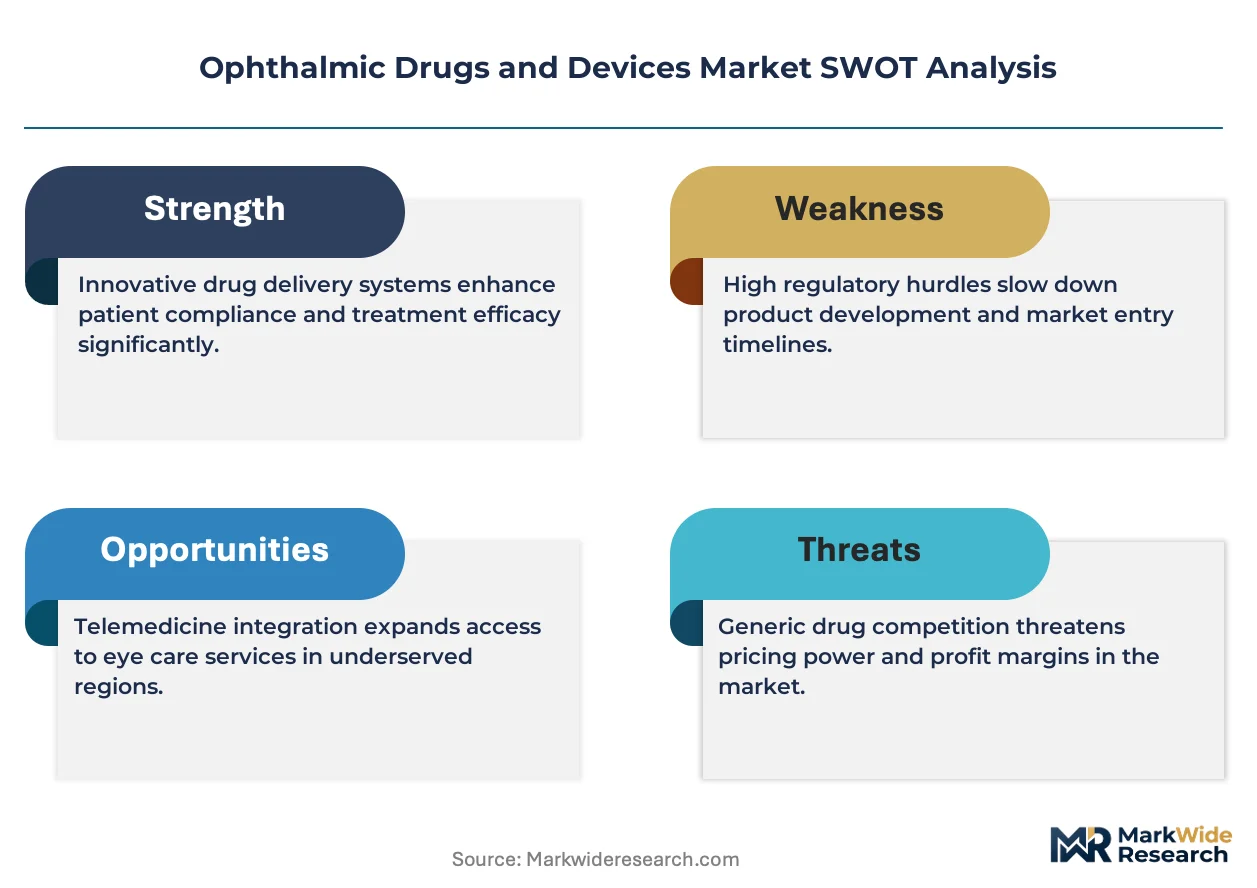
- FDA 510(k) Pathway Modernization:Streamlined premarket notification procedures for ophthalmic devices are compressing clearance timelines and accelerating commercial launch schedules for surgical instrument manufacturers.
- India Tier-2 City Expansion:Private eye hospital chains in cities like Jaipur, Lucknow, and Indore are scaling surgical volume through standardized phacoemulsification protocols and centralized supply chains.
- Anti-VEGF Biologic Cold-Chain Infrastructure:Sustained investment in temperature-controlled distribution networks is extending biologic drug reach into secondary markets previously constrained by logistics limitations.
Market Restraints
- Excimer Laser Component Supply Concentration:Captive manufacturing strategies among top-tier suppliers are creating procurement bottlenecks for mid-tier device assemblers dependent on external optical component sourcing.
- REACH Polymer Compliance Costs:ECHA material safety requirements for intraocular lens polymers are extending supplier qualification timelines and elevating raw material certification expenses.
- Biologic Biosimilar Substitution Pressure:Emerging therapeutic alternatives to originator anti-VEGF agents are threatening pricing power across retina treatment franchises in regulated markets.
Strategic Opportunities
- Telemedicine Diagnostic Protocol Validation:Remote retinal imaging reimbursement frameworks in Germany and France are opening new service delivery channels beyond traditional clinic-based examination models.
- Sustained-Release Implant Technology Convergence:Integration of biodegradable polymer science with precision dosing engineering is creating next-generation glaucoma drug delivery platforms with extended therapeutic windows.
- Japan's PMDA Accelerated Review Pathway:Priority designation mechanisms for breakthrough ophthalmic devices are attracting R&D investment toward AI-enabled diagnostic classification systems.
Industry Challenges
- Femtosecond Laser Technician Certification Bottlenecks:Specialized training requirements for platform operation are constraining surgical volume expansion at facilities with limited staff development capacity.
- Multi-Jurisdiction AI Diagnostic Software Compliance:Divergent classification rules between FDA, EMA, and PMDA for machine learning-enabled devices are fragmenting development roadmaps and inflating regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Drugs and Devices Market |
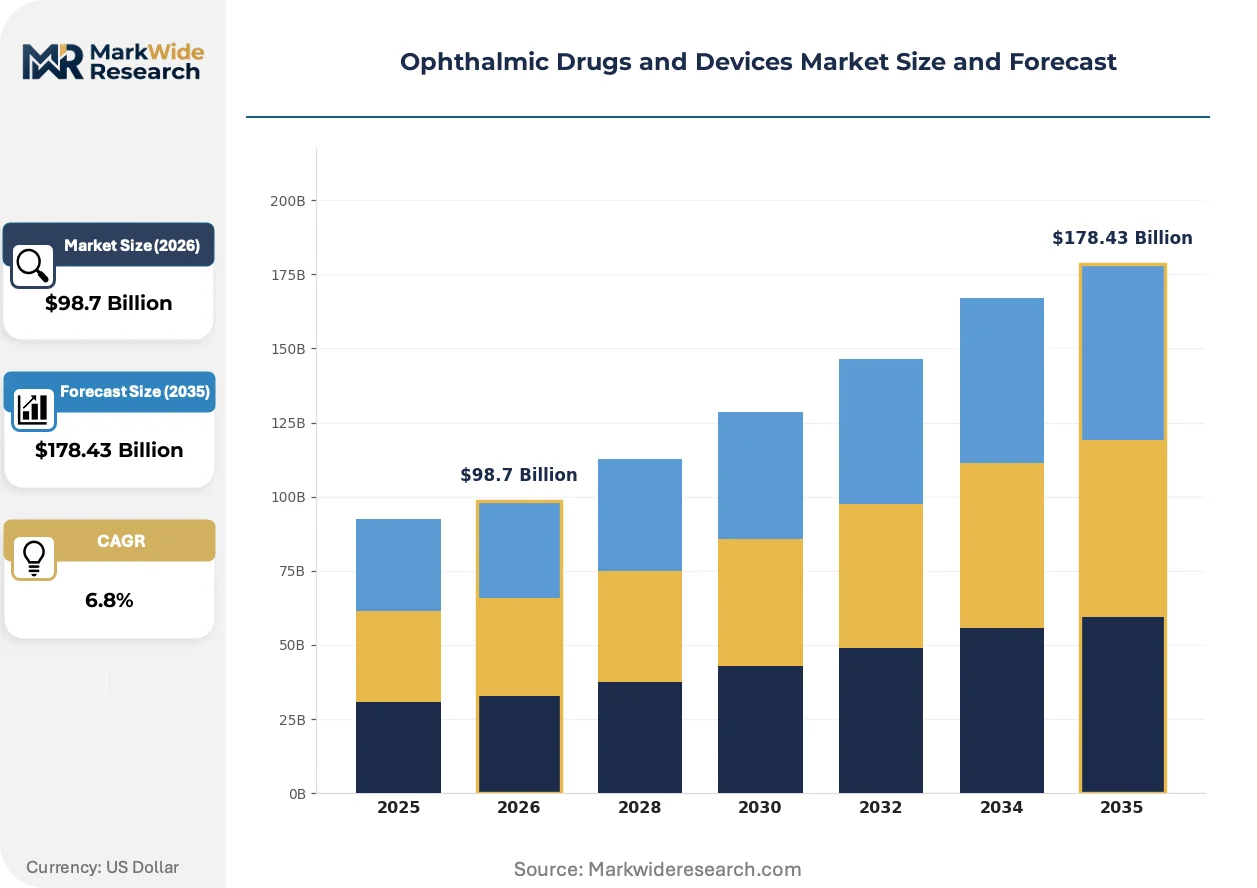
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eye Drops, Ointments, Surgical Instruments, Diagnostic Devices Application: Glaucoma Treatment, Cataract Surgery, Retinal Disorders, Dry Eye Syndrome End User: Hospitals, Clinics, Home Care, Research Laboratories Technology: Laser Therapy, Implantable Devices, Drug Delivery Systems, Telemedicine |
| Companies Covered | Novartis, Alcon, Bausch Health, Regeneron Pharmaceuticals, Allergan, Santen Pharmaceutical, Johnson & Johnson, Carl Zeiss, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Drugs and Devices Market Evolving Landscape
Digital imaging protocols and automated surgical planning are compressing procedure preparation cycles while elevating outcome predictability across refractive and cataract surgery segments.
Extended-depth-of-focus intraocular lens designs are unifying distance and intermediate vision correction in single-implant procedures. Premium cataract surgery centers in South Korea and Spain are adopting these platforms at accelerated rates. The technology is unifying previously segmented presbyopia-correcting product categories into consolidated premium-tier offerings.
EMA's Medical Device Regulation transition deadlines are forcing ophthalmic instrument manufacturers to revalidate legacy product portfolios under strengthened clinical evidence requirements. Surgical microscope and phacoemulsification system suppliers are accelerating notified body engagement to secure extended certification timelines. Retinal diagnostic imaging devices face the most compressed compliance windows due to software-enabled functionality classifications.
Direct-to-hospital procurement of femtosecond laser maintenance contracts is displacing traditional distributor-mediated service arrangements. Large ophthalmology hospital groups in Brazil and Mexico are negotiating multi-year platform service bundles that unbundle capital acquisition from operational support. This restructuring concentrates vendor relationship management within centralized procurement functions rather than dispersed surgical department budgets.
Ophthalmic Drugs and Devices Market Segmentation
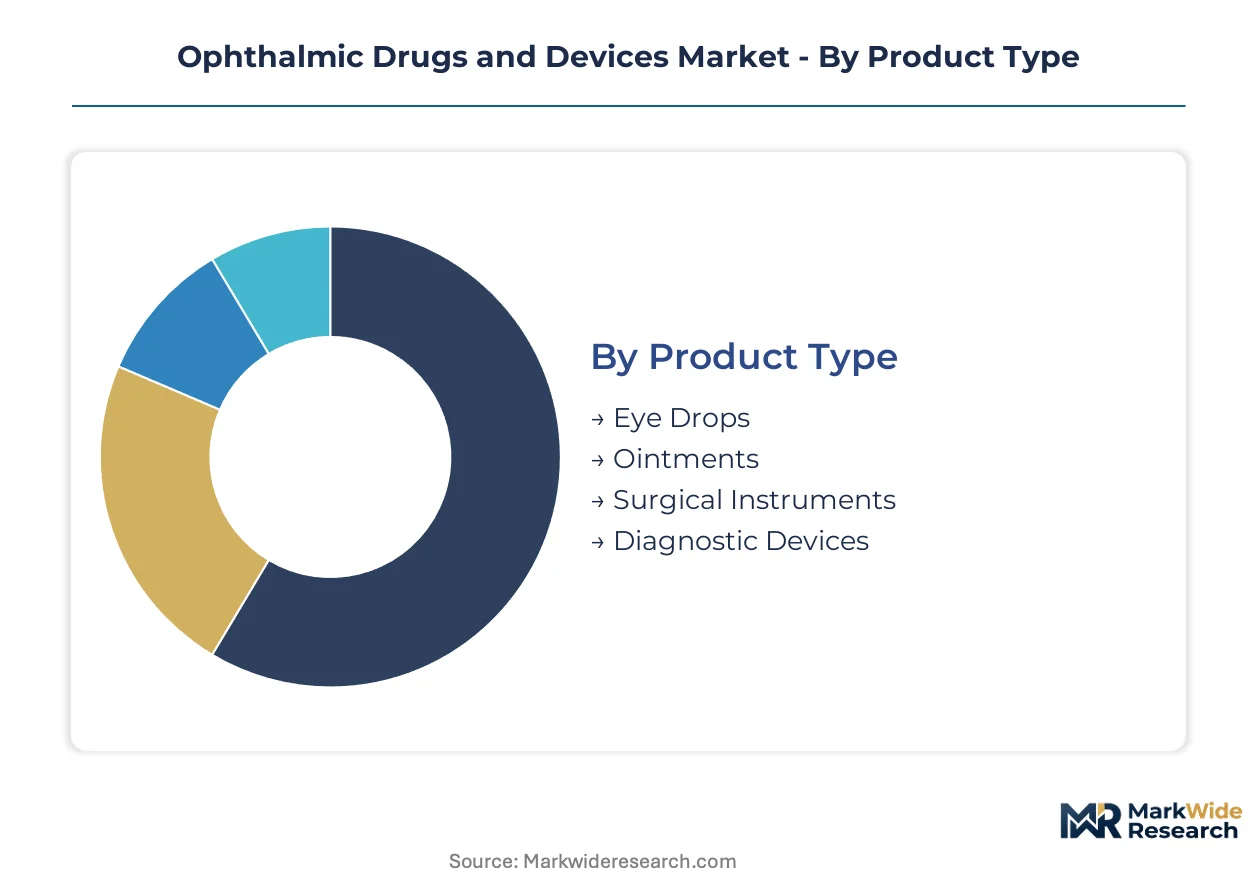
Segmentation in ophthalmic markets separates capital-intensive surgical platforms from consumable drug formulations, with each category demanding distinct procurement cycles and regulatory pathways. Understanding these divisions clarifies where pricing power concentrates and which segments attract disproportionate R&D investment.
Product Type:
Capital requirements vary sharply across this category, with surgical instruments demanding the heaviest upfront manufacturing investment while eye drops operate on commoditized production economics.
- Surgical Instruments:Femtosecond laser platforms and phacoemulsification systems require precision optical engineering and extended FDA 510(k) clearance timelines. Hospital procurement departments in India are consolidating purchasing power around standardized platform configurations to compress vendor margins.
- Diagnostic Devices:Optical coherence tomography systems and automated perimeters integrate AI-enabled image classification algorithms requiring multi-jurisdiction software validation. Germany and France are validating remote diagnostic imaging reimbursement frameworks that accelerate clinic adoption of portable screening units.
- Eye Drops:Topical formulations span lubricating artificial tears to prescription anti-inflammatory solutions with varying viscosity profiles. Manufacturing concentrates among contract pharmaceutical facilities with sterile filling capabilities.
- Ointments:Semisolid ocular preparations provide prolonged corneal contact time for overnight therapeutic delivery. Compounding pharmacies and regional manufacturers supply this segment with limited brand concentration.
Most installed capacity flows through Surgical Instruments. Expansion is steepest in Diagnostic Devices.
Application:
Procedure volume distribution across this category reflects demographic aging patterns and reimbursement accessibility rather than disease prevalence alone.
- Cataract Surgery:Phacoemulsification with intraocular lens implantation represents the highest-volume elective surgical procedure globally. Private eye hospital chains in India's tier-2 cities are scaling standardized surgical protocols to capture underserved demand.
- Retinal Disorders:Anti-VEGF biologic injections for age-related macular degeneration require cold-chain distribution infrastructure and specialized vitreoretinal surgical capability. Biosimilar substitution pressure is threatening originator pricing power in regulated European markets.
- Glaucoma Treatment:Medical therapy with prostaglandin analogs and surgical intervention with minimally invasive devices command stable clinical volume. Sustained-release implant development is extending therapeutic windows and reducing patient compliance burden.
- Dry Eye Syndrome:Prescription immunomodulatory drops and punctal occlusion devices address evaporative and aqueous-deficient subtypes. Diagnostic differentiation between subtypes remains inconsistent across primary care settings.
Procedure volume concentrates in Cataract Surgery. Technology investment is climbing fastest in Retinal Disorders.
End User:
Procurement authority and budget allocation mechanisms differ fundamentally between institutional purchasers and individual consumers across this category.
- Hospitals:Integrated health systems negotiate multi-year capital equipment leases and bundled service contracts for femtosecond laser maintenance. Centralized procurement functions in Brazil and Mexico are displacing traditional distributor-mediated arrangements.
- Clinics:Independent ophthalmology practices prioritize portable diagnostic devices and consumable surgical supplies with rapid turnover. Reimbursement rate compression is forcing equipment financing creativity.
- Home Care:Self-administered eye drops and warming masks for meibomian gland dysfunction bypass clinical intermediaries. E-commerce channels are capturing growing share of replenishment purchases.
- Research Laboratories:Academic medical centers and contract research organizations source specialized imaging systems and investigational drug compounds for clinical trial execution. Funding cycles drive irregular procurement patterns.
Capital deployment is heaviest in Hospitals. Patient volume is migrating fastest toward Clinics.
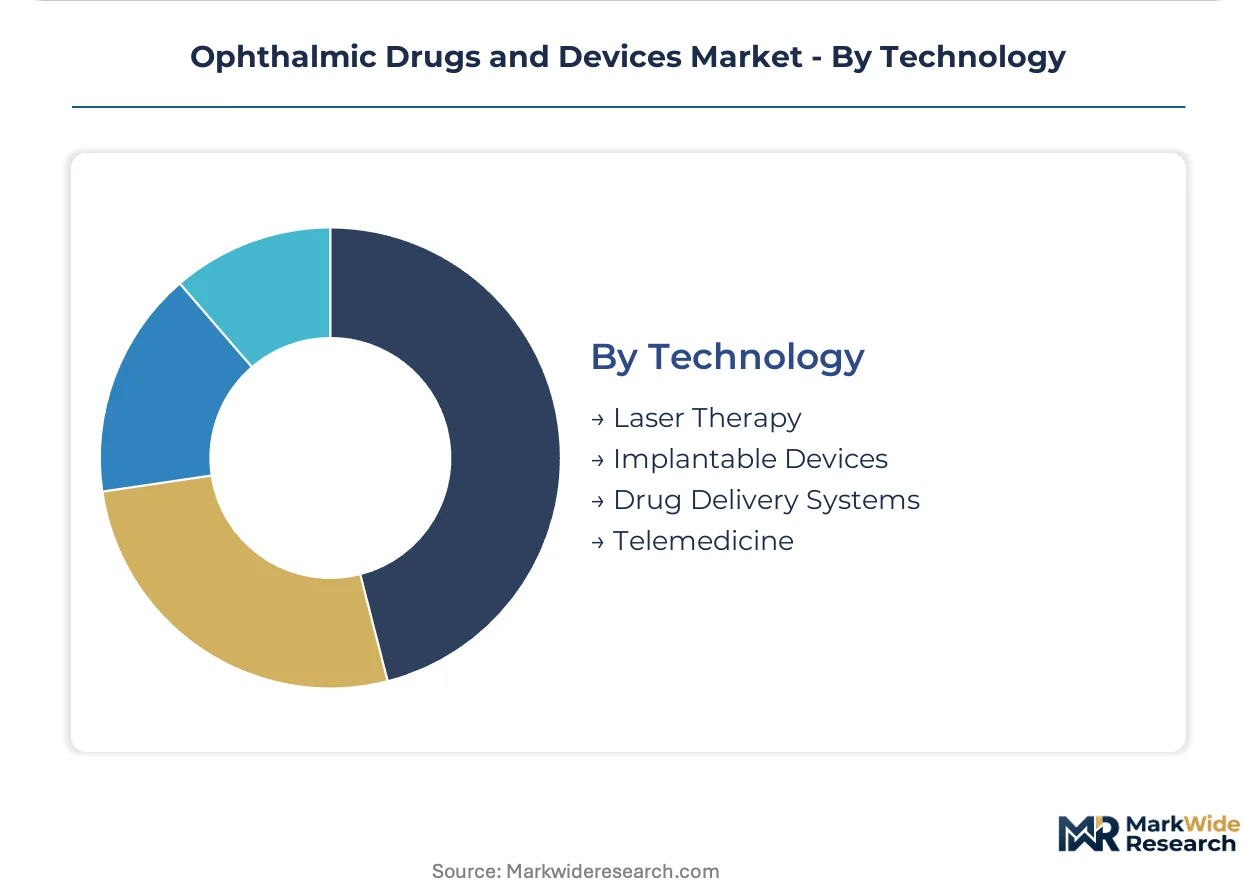
Technology:
Regulatory classification complexity and software validation burden separate this category into distinct commercialization timelines.
- Drug Delivery Systems:Biodegradable sustained-release implants for glaucoma and biodegradable intravitreal inserts for retinal disease combine polymer science with precision dosing engineering. These platforms command the highest margin tier within the technology dimension due to extended therapeutic windows and reduced administration frequency.
- Telemedicine:Remote retinal imaging protocols and AI-enabled diagnostic classification systems are gaining clinical validation fastest in Germany and France. Regulatory divergence between FDA, EMA, and PMDA for machine learning-enabled devices is fragmenting development roadmaps.
- Laser Therapy:Excimer and femtosecond platforms for refractive and cataract surgery require specialized technician certification and preventive maintenance infrastructure. Component supply concentration among captive manufacturers is creating procurement bottlenecks for mid-tier assemblers.
- Implantable Devices:Intraocular lenses with extended-depth-of-focus designs and glaucoma drainage shunts demand biocompatible material validation under REACH polymer compliance requirements. ECHA material safety rules are extending supplier qualification timelines.
Revenue concentration sits with Drug Delivery Systems. Regulatory attention is intensifying most around Telemedicine.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's tier-2 city clusters anchor surgical device demand expansion. Private hospital chains in Jaipur, Lucknow, and Indore scale phacoemulsification volume through centralized procurement. FDA 510(k) modernization and EMA MDR transition deadlines reshape clearance timelines across major markets.
United States
Hospital systems consolidate femtosecond laser purchasing through multi-year capital leases. FDA streamlined premarket notification procedures compress device clearance cycles. The Research Triangle and Greater Boston clusters concentrate AI-enabled diagnostic development for retinal imaging platforms.
Germany
Reimbursement frameworks for remote retinal imaging accelerate telemedicine adoption in ambulatory settings. EMA Medical Device Regulation transition deadlines force surgical microscope revalidation under strengthened clinical evidence rules. The Stuttgart-Munich corridor houses precision optical engineering clusters serving laser platform manufacturers.
India
Private eye hospital chains in tier-2 cities scale standardized cataract surgical protocols to capture underserved demand. CDSCO streamlined medical device registration procedures reduce import clearance friction. The Hyderabad-Bengaluru corridor concentrates contract manufacturing for intraocular lens polymers.
Japan
PMDA accelerated review pathways attract R&D investment toward AI-enabled diagnostic classification systems. METI priority designation mechanisms for breakthrough ophthalmic devices compress regulatory timelines. The Osaka-Kobe manufacturing belt anchors phacoemulsification system component fabrication.
Brazil
Large ophthalmology hospital groups negotiate multi-year femtosecond laser service bundles unbundling capital acquisition from operational support. ANVISA medical device registration harmonization with Mercosur standards reduces cross-border certification burden. São Paulo's private hospital networks concentrate premium cataract surgery volume.
Ophthalmic Drugs and Devices Market Competitive Landscape
Global majors compete with regional champions across surgical device and biologic drug segments. Market structure shows consolidation at the platform level alongside fragmentation in consumable supply. Three archetypes dominate: integrated pharmaceutical-device conglomerates, pure-play surgical instrument specialists, and biologic-focused retina franchises. Competitive moves concentrate on captive manufacturing integration and multi-year hospital service contracting.
Among integrated pharmaceutical-device conglomerates, Novartis, Alcon, and Johnson & Johnson occupy positions spanning biologic drug supply chains and precision surgical platforms. Novartis exemplifies the retina franchise archetype through integrated anti-VEGF biologic distribution. Alcon anchors the surgical devices segment with direct control over phacoemulsification system production. Johnson & Johnson represents diversified platform competition in femtosecond laser systems. These three entities illustrate how vertical control over critical components shapes procurement relationships with hospital networks.
| Leading Market Players |
|---|
| Novartis |
| Alcon |
| Bausch Health |
| Regeneron Pharmaceuticals |
| Allergan |
| Santen Pharmaceutical |
| Johnson & Johnson |
| Carl Zeiss |
| Bayer |
| Others |
Value Network & Pricing Analysis
Intraocular lens polymer costs cascade through three pricing strata, with REACH-certified European suppliers commanding premium positioning against Indian contract manufacturers serving economy-tier hospital chains in Jaipur and Lucknow. Cold-chain distribution expenses for anti-VEGF biologics further stratify pricing, as temperature-controlled logistics infrastructure concentrates pricing power with vertically integrated retina franchises.
Pricing Analysis
Input-cost pass-through from excimer laser optical components flows asymmetrically across premium and standard tiers, with captive manufacturers absorbing less margin compression than external-dependent assemblers. Price differentiation rests on FDA 510(k) clearance tier and after-sales service bundling, with hospital groups in Brazil and Mexico negotiating multi-year maintenance contracts that unbundle capital from operational support. Cost compression in standard-tier phacoemulsification systems intensifies as Indian tier-2 city chains consolidate procurement volume. Clinic-based buyers exhibit highest price sensitivity, while integrated hospital systems prioritize platform standardization over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle femtosecond laser platform demand from large ophthalmology groups, displacing traditional distributor-mediated arrangements in Brazil and Mexico. Geographic supply concentration centers on Germany for precision optical engineering, India for intraocular lens polymer contract manufacturing, and Japan for phacoemulsification system components. Raw material dependencies include biocompatible polymers for implants, rare-earth optical elements for laser systems, and sterile-grade packaging for biologic drugs. Single-source vulnerability in excimer laser component sourcing creates procurement bottlenecks for mid-tier device assemblers. Distribution runs through centralized hospital procurement functions rather than dispersed surgical department budgets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ophthalmic drugs and devices function as a stable compounder, with demographic aging and chronic disease prevalence ensuring procedure volume expansion across economic cycles.
For Market Incumbents: Deploy captive manufacturing of critical optical components to neutralize supply concentration risks from German and Japanese precision engineering suppliers. Consolidate hospital service contracting through multi-year platform bundles that unbundle capital acquisition from maintenance, defending against emerging pure-play surgical instrument specialists. Deepen backward integration into intraocular lens polymer production to compress REACH compliance costs and accelerate supplier qualification timelines. For New Entrants and Emerging Players: Private eye hospital chains in India's tier-2 cities represent the most penetrable channel partner type, with standardized phacoemulsification protocols creating entry points for cost-optimized platform configurations. Target telemedicine diagnostic protocol validation in Germany and France, where remote retinal imaging reimbursement frameworks are opening service delivery channels beyond traditional clinic models. Pursue software-enabled device development with AI-based diagnostic classification systems, leveraging Japan's PMDA accelerated review pathway to compress regulatory timelines versus FDA and EMA routes. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier device assemblers face procurement bottlenecks from captive optical component suppliers and extended REACH polymer qualification timelines. Long-term viability favors integrated pharmaceutical-device conglomerates with vertical control over biologic cold-chain distribution and precision surgical platform production. Monitor biosimilar substitution rates in European retina treatment markets as an inflection indicator for originator pricing power erosion. Target acquisition archetypes include sustained-release implant technology developers with biodegradable polymer platforms and AI-enabled diagnostic software specialists with multi-jurisdiction regulatory validation.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year femtosecond laser service bundles with Brazilian ophthalmology groups concentrate vendor relationships. |
| CE Marking Pathway | EMA MDR transition deadlines force surgical microscope revalidation under strengthened clinical evidence requirements. |
| Software Companion Development | AI-enabled diagnostic classification systems attract PMDA accelerated review priority designation in Japan. |
| Reimbursement Strategy | Remote retinal imaging validation in Germany and France opens telemedicine service delivery channels. |
| FDA Submission | Streamlined 510(k) premarket notification procedures compress ophthalmic device clearance timelines. |
Research Methodology
Coverage spans the United States, Germany, India, Japan, and Brazil, with primary inputs from each market informing demand and supply-side dynamics. The research combines structured interviews with hospital procurement managers, vitreoretinal surgeons, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation from FDA 510(k) filings, EMA Medical Device Regulation transition documentation, CDSCO registration databases, PMDA priority designation records, and ANVISA harmonization protocols. Bottom-up procedure volume modeling and top-down market sizing triangulate across data sources to ensure consistency.
Granularity-level modeling operates at the intersection of product type, application, end user, and technology dimensions, with specific attention to femtosecond laser platform configurations, anti-VEGF biologic cold-chain distribution tiers, and sustained-release implant polymer specifications. CAGRs derive from procedure volume trajectories, pricing trend analysis, and technology substitution patterns across the projection horizon. Industry-specific forecast inputs include hospital capital equipment lease renewal cycles, tier-2 city surgical volume scaling in India, and EMA MDR compliance deadline impacts on product portfolio revalidation.
Revisions become necessary when regulatory divergence in AI diagnostic software classification between FDA, EMA, and PMDA fragments development roadmaps, or when biosimilar substitution accelerates beyond base-case assumptions in European retina markets. Forecasts reflect documented assumptions regarding demographic aging trajectories, reimbursement rate stability, and supply chain concentration in precision optical component manufacturing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Extended and Continuous Wear Lenses Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
Europe Primary Angle-Closure Glaucoma Market
Ophthalmology
Choroideremia Treatment Market