
 Vernal Keratoconjunctivitis Treatment Market | 2026-2036
Vernal Keratoconjunctivitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Vernal Keratoconjunctivitis Treatment Market Analytics
Pediatric allergy-ophthalmology crossover care is decoupling from general ophthalmology practice, creating dedicated treatment pathways for severe pediatric ocular surface disease. Santen Pharmaceutical leverages its established dry-eye infrastructure to extend into allergic conjunctivitis specialty channels across Japan and Europe. Novartis anchors its position through sustained investment in ocular immunology, while Allakos competes on differentiated mast-cell-targeting biologic platforms.
Vernal keratoconjunctivitis treatment encompasses pharmacological interventions targeting eosinophil-driven, Th2-mediated inflammation of the tarsal and limbal conjunctiva, typically requiring topical corticosteroid pulse therapy with intraocular pressure monitoring to prevent steroid-induced glaucoma. The primary commercial purpose centers on preventing corneal shield ulcers, limbal stem-cell deficiency, and permanent vision loss in pediatric and adolescent populations across arid and high-pollen climates. Immunotherapy segments are gaining structural priority as disease-modifying potential attracts payer interest, while mast cell stabilizers occupy a mature, margin-compressed maintenance niche. Topical delivery mode dominates value pools due to direct ocular surface action and established reimbursement, though injectable biologics represent the fastest-growing segment as severe-refractory cases shift toward office-based administration.
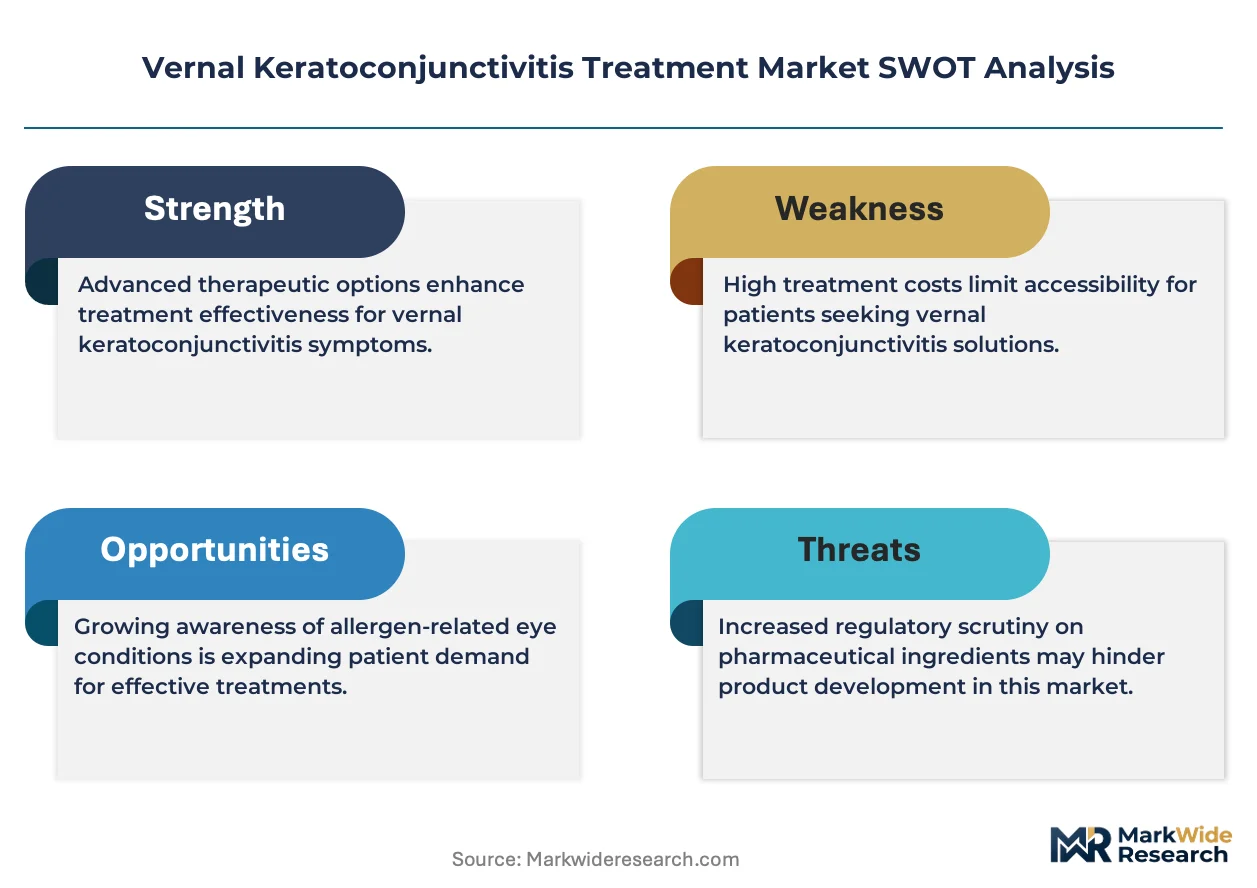
FDA orphan drug incentives and EMA pediatric investigation plans are reshaping clinical trial design, with both regulators demanding long-term safety data for chronic pediatric ocular steroid exposure. REACH compliance for preservative-free formulations and ISO 13485 quality management standards further constrain formulation choices and manufacturing site selection for European market access. Stakeholders must monitor how payer evidence requirements for biologic VKC therapies evolve relative to existing corticosteroid cost benchmarks.
Market Dynamics
Biologics targeting the Th2-inflammatory cascade are redirecting clinical investment away from corticosteroid-reliant protocols, forcing manufacturers to rebuild manufacturing capacity around cold-chain monoclonal antibody delivery.
Growth Catalysts
- FDA Orphan Drug Incentives:The designation pathway accelerates pediatric VKC trial timelines and provides seven-year market exclusivity, drawing venture capital into ocular immunology pipelines.
- Desert Belt Disease Prevalence:Arid climates across the Mediterranean littoral and Central Asia generate concentrated pediatric caseloads that sustain specialist referral networks and justify dedicated service line investment.
- Topical Biologic Formulation Advances:Nanoparticle-enabled ocular surface penetration is reducing systemic exposure concerns and expanding the addressable population beyond steroid-intolerant patients.
Market Restraints
- Corticosteroid Cost Benchmarking:Payers in Germany and France reference generic dexamethasone pricing when evaluating biologic reimbursement, compressing net revenue per treated eye.
- Preservative-Free Manufacturing Concentration:Single-dose vial production clusters in Switzerland and Ireland, creating supply vulnerability and extended lead times for Asian markets.
- Long-Term Safety Data Requirements:EMA pediatric investigation plans mandate five-year follow-up studies that delay label expansion and consume 40% of clinical development budgets.
Strategic Opportunities
- Sub-Saharan Africa Service Gaps:Underdiagnosis in Nigeria and Kenya presents first-mover potential for mobile ophthalmology units partnered with regional allergy clinics.
- Combination Biologic-Steroid Protocols:Concurrent IL-4/IL-13 blockade with short-course corticosteroid pulses is opening maintenance therapy segments previously reserved to mast cell stabilizers.
- Teleophthalmology Referral Networks:Remote slit-lamp imaging platforms are compressing time-to-diagnosis in rural Australia and enabling centralized biologic prescribing authority.
Industry Challenges
- Pediatric Ocular Immunology Training Shortfalls:Fellowship programs in the United States and Japan graduate fewer than 30 specialists annually, constraining site activation for multi-center trials.
- ISO 13485 Certification Backlogs:European notified body capacity constraints are extending quality management system approval timelines by 8-14 months for preservative-free formulation lines.
- Cold-Chain Distribution Integrity:Temperature excursions during last-mile delivery to Middle Eastern clinics compromise biologic potency and trigger batch rejection disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vernal Keratoconjunctivitis Treatment Market |
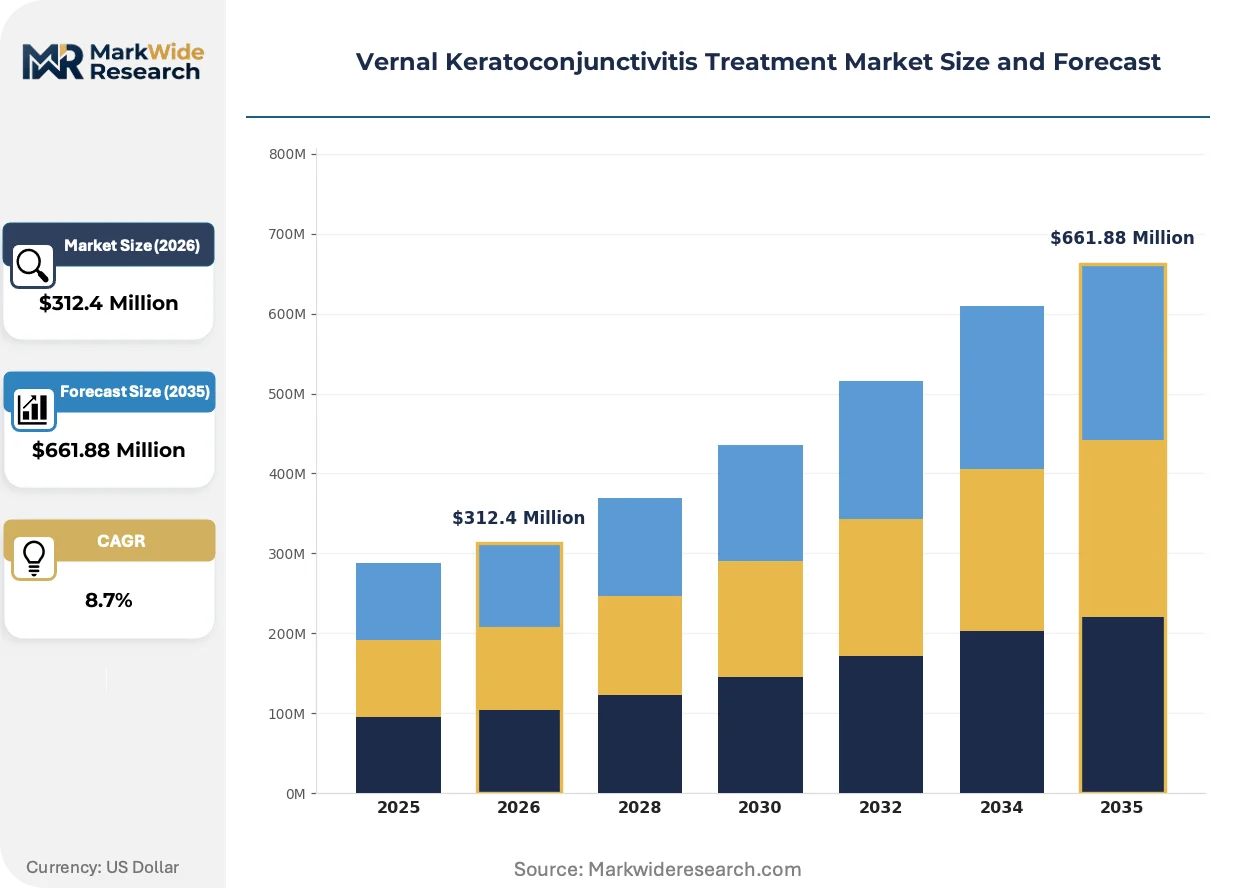
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Steroidal Drops, Immunotherapy, Mast Cell Stabilizers Delivery Mode: Topical, Injectable, Oral, Inhalation End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Treatment Approach: Preventive Care, Symptomatic Treatment, Long-term Management, Acute Care |
| Companies Covered | Sun Pharmaceutical, Senju Pharmaceutical, Santen Pharmaceutical, iCo Therapeutics, Allakos, Alcon, Novartis, Akari Therapeutics, Bausch Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vernal Keratoconjunctivitis Treatment Market Evolving Landscape
Targeted immunomodulation is displacing broad-spectrum anti-inflammatory protocols across severe ocular surface disease, with formulation science and diagnostic biomarker adoption converging to enable precision therapy selection.
Anti-IL-4Rα receptor antagonists are integrating into first-line severe VKC protocols through subcutaneous depot formulations that reduce dosing frequency from daily drops to monthly injections. Pediatric allergy-ophthalmology crossover clinics in California and Texas are adopting these platforms fastest, compressing the addressable market for topical calcineurin inhibitors and redirecting pharmacy benefit management spend toward specialty drug tiers.
EMA's 2024 revision to pediatric investigation plans now requires ocular surface biomarker stratification before randomization, forcing sponsors to incorporate conjunctival impression cytology into trial designs. This regulatory shift extends enrollment timelines but improves payer evidence quality, with German statutory health insurers now conditioning reimbursement on documented eosinophil-driven inflammation subtyping.
Caregiver-driven demand for steroid-sparing alternatives is reshaping treatment initiation patterns, with parents of pediatric patients in Saudi Arabia and the UAE requesting biologic referrals within 90 days of diagnosis rather than awaiting corticosteroid failure. Academic medical centers in Riyadh and Dubai are responding by embedding allergy-immunology co-consults into ophthalmology workflows, compressing the traditional 18-month escalation pathway to six months.
Vernal Keratoconjunctivitis Treatment Market Segmentation
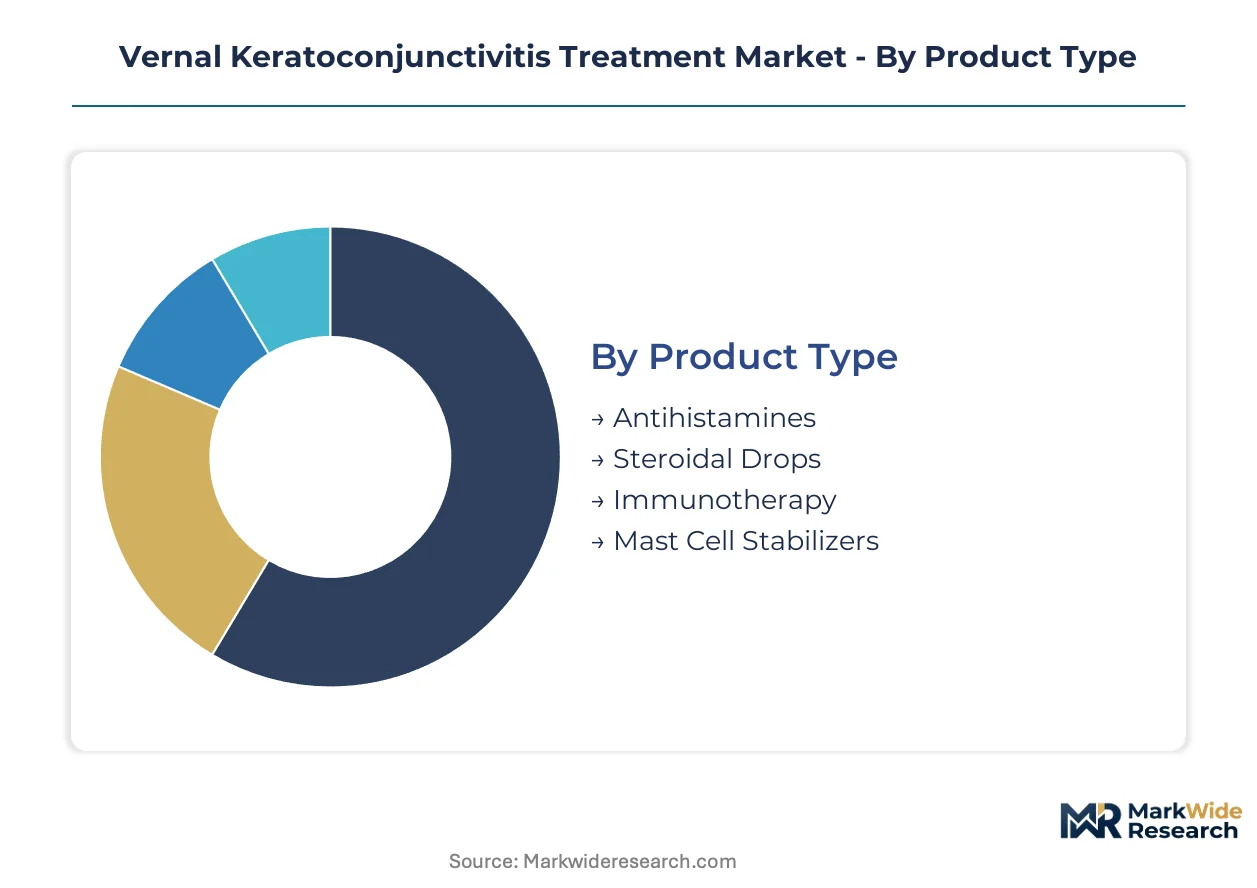
Vernal keratoconjunctivitis treatment segments reflect the tension between acute symptom control and disease-modifying intervention. Product formulation and delivery mode choices determine reimbursement tier placement and patient adherence in pediatric populations.
Product Type:
Mechanism of action defines clinical positioning and payer willingness to escalate therapy beyond generic corticosteroid benchmarks.
- Antihistamines:H1-receptor antagonists provide rapid relief of ocular pruritus through competitive histamine blockade. Demand clusters in primary care settings across the Mediterranean littoral where pollen exposure drives seasonal flare-ups and OTC availability reduces specialist referral burdens.
- Steroidal Drops:Potent glucocorticoid formulations suppress Th2-mediated inflammation through NF-κB pathway inhibition. German and French statutory insurers reference generic dexamethasone pricing when evaluating newer alternatives, compressing net revenue despite clinical efficacy in shield ulcer prevention.
- Immunotherapy:Subcutaneous allergen desensitization modifies disease trajectory through IgE-mediated tolerance induction. Saudi Arabia's Ministry of Health expanded pediatric allergy clinic capacity in Riyadh and Jeddah to accommodate rising referral volumes.
- Mast Cell Stabilizers:Cromolyn sodium and lodoxamide prevent degranulation through chloride channel blockade. Japanese PMDA-approved preservative-free formulations command premium positioning in maintenance therapy segments.
Mature deployment sits with steroidal drops. Newer deployment is concentrated in immunotherapy protocols.
Delivery Mode:
Route selection balances onset speed against systemic exposure risk in chronically treated children.
- Topical:Eye drops and ointments deliver direct ocular surface concentration with minimal plasma absorption. Swiss and Irish manufacturing clusters dominate preservative-free vial production, creating supply vulnerability for Asian markets.
- Injectable:Subcutaneous depot formulations enable monthly IL-4Rα blockade versus daily drop regimens. California and Texas pediatric allergy-ophthalmology crossover clinics adopted these platforms fastest, compressing time-to-biologic initiation.
- Oral:Systemic antihistamines address concurrent allergic rhinitis but achieve limited conjunctival tissue penetration. UAE caregivers increasingly reject oral-first protocols in favor of localized therapy.
- Inhalation:Nebulized corticosteroid delivery remains experimental for ocular surface disease, confined to academic medical center protocols in Japan and Australia.
Topical administration dominates current volume. Injectable biologics are gaining share fastest among steroid-refractory severe cases.
End User:
Site of care determines diagnostic sophistication and therapy escalation authority.
- Hospitals:Academic medical centers manage complicated VKC with corneal shield ulcers or limbal stem cell deficiency. King Khaled Eye Specialist Hospital in Riyadh anchors regional referral networks for the Gulf Cooperation Council.
- Clinics:Dedicated pediatric ophthalmology and allergy crossover practices drive biologic adoption through streamlined co-consult workflows. Less than 30 fellowship-trained specialists graduate annually in the United States and Japan, constraining site activation.
- Home Care:Caregiver-administered maintenance therapy requires preservative-free formulations to minimize surface toxicity. REACH compliance for European market access limits formulation choices.
- Ambulatory Surgical Centers:Minor procedures including superficial keratectomy for shield ulcers occur in outpatient surgical settings. Limited VKC-specific volume restricts dedicated service line investment.
Hospital-based diagnosis dominates severe case identification. Clinic-based management is expanding most quickly as dedicated pediatric allergy-ophthalmology pathways mature.
Treatment Approach:
Temporal framing of intervention shapes pharmaceutical procurement patterns and patient journey design.
- Preventive Care:Pre-seasonal mast cell stabilizer initiation and environmental allergen avoidance. Australian teleophthalmology networks compress time-to-preventive protocol initiation in rural Queensland and Western Australia.
- Symptomatic Treatment:Reactive antihistamine and corticosteroid pulse therapy during acute flares. Nigerian and Kenyan underdiagnosis leaves this segment underpenetrated relative to disease prevalence.
- Long-term Management:Chronic immunomodulation to prevent corneal complications and vision loss. EMA pediatric investigation plans mandate five-year follow-up studies that consume 40% of clinical development budgets.
- Acute Care:Emergency intervention for shield ulcers, pseudogerontoxon, or secondary infection. Dubai's centralized pediatric ophthalmology hub receives emergency transfers from across the UAE.
Symptomatic treatment retains the largest patient volume. Long-term management is climbing the fastest as disease-modifying biologics reshape therapeutic goals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in pharmaceutical manufacturing hubs concentrate VKC treatment production capacity. Tax incentives in Basel, Switzerland and Hyderabad, India attract sterile formulation investments. Cold-chain infrastructure gaps in emerging markets redirect distribution strategies toward regional fill-finish partnerships.
United States
Pediatric allergy-ophthalmology crossover clinics in California and Texas drive biologic adoption fastest. FDA orphan drug designation accelerates trial timelines for severe pediatric ocular surface disease. King of Prussia, Pennsylvania anchors specialty pharmacy distribution networks for injectable IL-4Rα antagonists.
Switzerland
Preservative-free manufacturing clusters in Basel supply European and Asian markets with single-dose vial capacity. Swissmedic quality standards exceed EMA baseline requirements, creating certification bottlenecks for new market entrants. Novartis maintains ocular immunology R&D concentration in Basel through sustained infrastructure investment.
Japan
PMDA-approved preservative-free mast cell stabilizer formulations command premium positioning in maintenance therapy segments. METI subsidies for pediatric rare disease drug development offset clinical trial costs for domestic sponsors. Osaka-based manufacturing sites specialize in nanoparticle-enabled ocular surface penetration technologies.
Saudi Arabia
Ministry of Health expansion of pediatric allergy clinic capacity in Riyadh and Jeddah accommodates rising VKC referral volumes. SFDA streamlined biologic registration pathways for severe allergic conditions reduce time-to-market by 8-12 months. King Khaled Eye Specialist Hospital anchors Gulf Cooperation Council referral networks for complicated cases with corneal shield ulcers.
India
CDSCO accelerated approval pathways for orphan ocular diseases attract contract manufacturing investment to Hyderabad and Bengaluru clusters. Domestic generic corticosteroid production supplies price-sensitive markets across South Asia and Sub-Saharan Africa. Telangana's pharmaceutical special economic zone offers 15-year tax holidays for sterile ophthalmic formulation facilities.
Vernal Keratoconjunctivitis Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Concentration sits with integrated ophthalmology pharmaceutical companies controlling distribution through specialty pharmacy networks. Three archetypes dominate: large-cap diversified ophthalmology portfolios, mid-cap biologic platform developers, and regional generic steroidal drop suppliers. M&A activity targets nanoparticle formulation capabilities while strategic partnerships secure preservative-free manufacturing capacity.
Within the biologic platform tier, Allakos and Akari Therapeutics exemplify mast-cell-targeting development strategies. Santen Pharmaceutical occupies a position bridging Japanese domestic leadership with European expansion through established dry-eye infrastructure. Novartis anchors the diversified ophthalmology archetype through sustained ocular immunology investment spanning topical and injectable modalities.
| Leading Market Players |
|---|
| Sun Pharmaceutical |
| Senju Pharmaceutical |
| Santen Pharmaceutical |
| iCo Therapeutics |
| Allakos |
| Alcon |
| Novartis |
| Akari Therapeutics |
| Bausch Health |
| Others |
Value Network & Pricing Analysis
Caregiver-driven demand for preservative-free biologic formulations in Saudi Arabia and the UAE is forcing manufacturers to qualify Swiss and Irish fill-finish capacity at premium rates. This procurement preference compresses margins on standard steroidal drops while elevating pricing power for cold-chain monoclonal antibody delivery.
Pricing Analysis
Short lead-time premiums for preservative-free single-dose vials command 15-20% markups over standard multi-dose presentations in European markets. Three-tier pricing structure across premium biologic, standard corticosteroid, and economy generic segments reflects certification grade and cold-chain handling requirements. Price differentiation hinges on ISO 13485 quality tier and REACH compliance status. Cost compression in the steroidal drop tier is intensifying as German statutory insurers reference generic dexamethasone benchmarks. Pediatric allergy-ophthalmology crossover clinics demonstrate lowest price sensitivity due to reimbursement tier protection, while primary care settings in Mediterranean markets exhibit highest sensitivity.
Supply Chain Analysis
Dual-sourcing mandates from European notified bodies require manufacturers to qualify backup fill-finish sites in Switzerland and Ireland simultaneously. Active pharmaceutical ingredient production concentrates in India and China, with sterile formulation capacity clustering in Basel and Hyderabad. Raw material dependencies include recombinant monoclonal antibodies, nanoparticle excipients, and preservative-free buffer systems. Single-source vulnerability persists in Swiss single-dose vial production for Asian markets. Distribution runs through specialty pharmacy networks anchored in King of Prussia, Pennsylvania, with regional cold-chain partnerships covering Middle Eastern last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preservative-free manufacturing concentration in Basel and Dublin creates structural supply constraints that prop biologic pricing premiums. This capacity bottleneck limits rapid volume scaling and sustains margin protection for qualified suppliers.
For Market Incumbents: Anchor market position through backward integration into nanoparticle formulation capabilities and captive supply of cold-chain distribution infrastructure. Defend against emerging mast-cell-targeting platforms by accelerating EMA pediatric investigation plan submissions. Prioritize certification investment in ISO 13485 quality management systems to extend manufacturing exclusivity windows. For New Entrants and Emerging Players: Launch via teleophthalmology referral partnerships in rural Australia and centralized biologic prescribing authority models. Target underpenetrated symptomatic treatment segments in Nigeria and Kenya through mobile ophthalmology units partnered with regional allergy clinics. Pursue sub-Saharan Africa service gaps as the most penetrable geography, leveraging contract manufacturing at Hyderabad sterile formulation clusters to bypass European capacity constraints. For Investors and Strategic Acquirers: The window for entry favors mid-cap biologic platform developers with mast-cell-targeting differentiation and existing EMA pediatric investigation plans. Long-term viability rests on disease-modifying mechanism validation and payer evidence quality exceeding corticosteroid cost benchmarks. Watch for SFDA streamlined biologic registration pathway expansions across Gulf Cooperation Council markets as the inflection signal for regional manufacturing investment.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Submission | Five-year follow-up study design satisfies German statutory insurer reimbursement conditions for biologic therapies. |
| Preservative-Free Manufacturing Scale-Up | Basel and Dublin capacity expansion reduces supply vulnerability for Asian markets and compresses lead times. |
| Teleophthalmology Referral Network Partnership | Remote slit-lamp imaging platforms in Queensland enable centralized biologic prescribing authority and faster diagnosis. |
| Cold-Chain Distribution Infrastructure Investment | Regional fill-finish partnerships in Riyadh address temperature excursion risks in Middle Eastern last-mile delivery. |
| Nanoparticle Formulation Capability Acquisition | Osaka-based penetration technologies expand addressable population beyond steroid-intolerant pediatric patients. |
Research Methodology
FDA orphan drug designations, EMA pediatric investigation plans, and ClinicalTrials.gov entries formed the secondary backbone for pipeline and regulatory tracking. Primary interviews with pediatric ophthalmology fellowship directors, formulary access specialists at German statutory insurers, and procurement managers at King Khaled Eye Specialist Hospital validated therapeutic adoption patterns. Bottom-up and top-down triangulation combined prescription volume modeling with payer budget impact assessments across Mediterranean and Gulf Cooperation Council markets.
Bottom-up patient-flow modeling across treatment lines, delivery modes, and regional regulatory clusters anchored the analytical framework. Segmentation dimensions included mechanism of action, administration route, and pediatric allergy-ophthalmology crossover clinic penetration. CAGRs derived from epidemiological prevalence projections and biologic adoption curve assumptions. Forecast inputs incorporated SFDA registration pathway timelines and EMA ocular surface biomarker stratification requirements.
The model assumes a particular technology adoption path; alternative pathways for topical nanoparticle-enabled biologics would alter the outlook if systemic exposure concerns diminish. Forecasts reflect assumptions about corticosteroid-refractory case identification rates and specialist referral network expansion. Deviation in EMA pediatric investigation plan enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Pediatric Vitrectomy Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Retina Health Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Global Hemianopsia Market
Ophthalmology
Intraocular Lymphoma Treatment Market
Ophthalmology
Tonometry Market
Ophthalmology
Excimer and Femtosecond Ophthalmic Lasers Market