
 Retinoblastoma Treatment Market | 2026-2036
Retinoblastoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Retinoblastoma Treatment Market Intelligence
Ophthalmic oncology manufacturing capacity in North America is broadening as specialized biologics production scales up. Novartis leverages its cell and gene therapy infrastructure to anchor supply of advanced retinoblastoma interventions. Pfizer competes through integrated oncology platforms that extend from clinical development to hospital distribution networks.
Retinoblastoma treatment encompasses multimodal interventions targeting malignant retinal tumors arising from RB1 gene mutations, primarily affecting children under five years. Chemotherapy remains the structural backbone of first-line protocols, though intravitreal injection delivery modes are gaining traction for localized tumor control with reduced systemic toxicity. Laser therapy occupies a mature margin pool in early-stage disease management, while radiation therapy faces structural pressure from organ-sparing alternatives.
The FDA's orphan drug program and EMA's pediatric investigation plans shape clinical trial design and market access pathways for novel retinoblastoma therapies. Health Canada and the PMDA enforce comparable pediatric oncology standards that filter which delivery technologies achieve commercial adoption. Stakeholders must monitor how regulatory convergence across these agencies affects development prioritization for intraocular versus systemic administration routes.
Market Dynamics
The retinoblastoma treatment landscape pivots on intravitreal chemotherapy delivery systems displacing systemic protocols, compressing hospitalization requirements while elevating precision dosing demands on compounding infrastructure.
Growth Catalysts
- FDA Orphan Drug Designation:The accelerated approval pathway compresses clinical trial timelines for rare pediatric oncology indications, drawing venture capital into retinoblastoma-specific drug development.
- Intravitreal Injection Protocols:Localized tumor control via direct ocular delivery reduces systemic toxicity profiles, expanding eligibility for infants with bilateral disease.
- Pediatric Cancer Center Clustering:Concentration of specialized retinoblastoma units in metropolitan treatment hubs concentrates patient volumes that justify dedicated ocular oncology pharmacy investments.
Market Restraints
- Specialized Compounding Infrastructure:Intravitreal chemotherapy requires sterile manufacturing capabilities that few hospital pharmacies possess, creating supply bottlenecks for melphalan and topotecan formulations.
- RB1 Genetic Testing Access:Molecular diagnostic confirmation delays treatment initiation in resource-constrained settings where next-generation sequencing capacity remains limited.
- Radiation Therapy Obsolescence:Long-term secondary malignancy risks from external beam protocols drive rapid abandonment, stranding sunk capital in linear accelerator installations.
Strategic Opportunities
- Sub-Saharan Africa Screening Networks:Red reflex photography deployed through primary care expansion creates early detection pipelines where advanced disease presentation currently dominates.
- EMA Pediatric Investigation Plans:The mandated pediatric study requirements for oncology approvals generate funding mechanisms that subsidize retinoblastoma trial infrastructure.
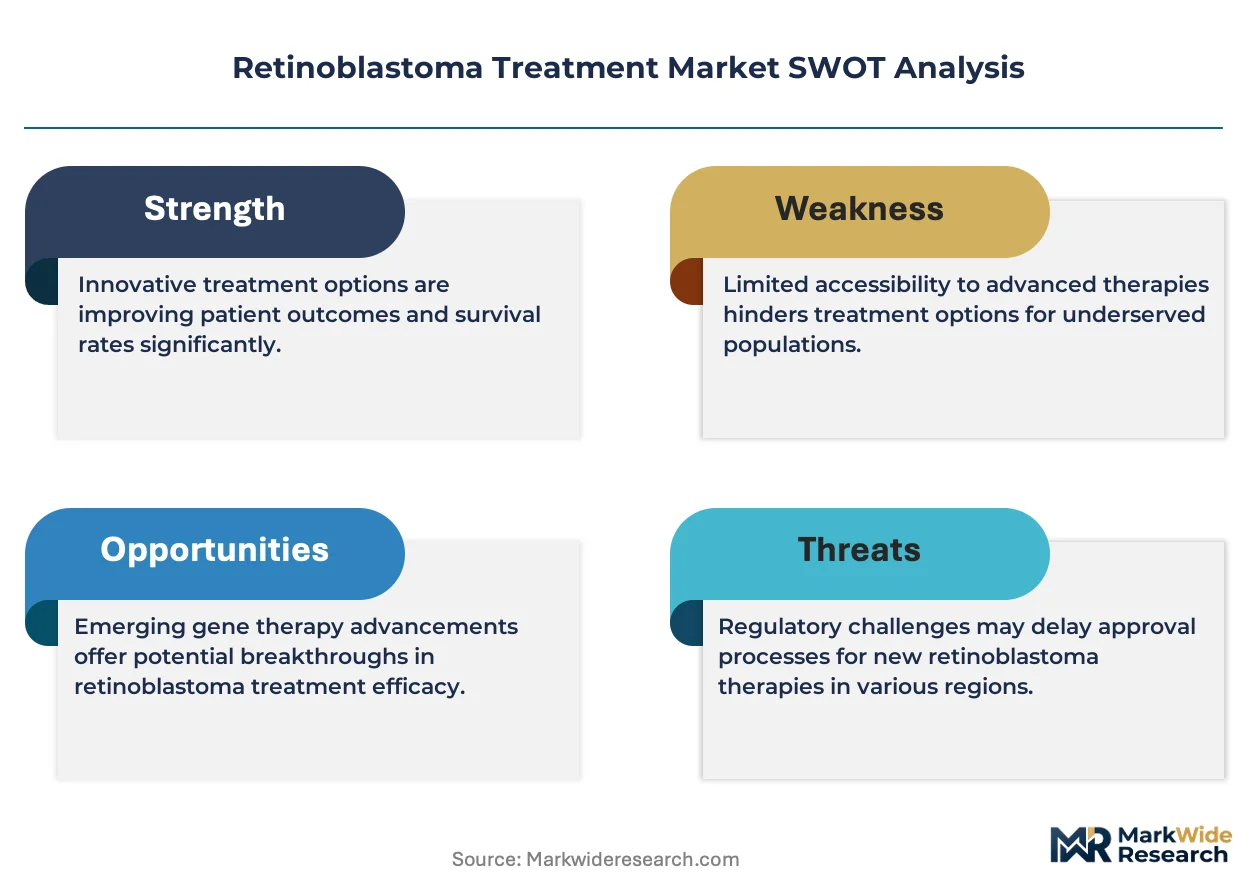
- Gene Therapy Convergence:CRISPR-based RB1 correction protocols combined with adeno-associated viral vectors promise definitive intervention beyond chemo-reduction paradigms.
Industry Challenges
- Ocular Oncology Fellowship Scarcity:The subspecialty training pipeline produces fewer than twenty qualified specialists annually across the United States, constraining center expansion.
- Multi-Institutional Trial Coordination:Low patient incidence necessitates international consortium structures that fragment data governance across Health Canada, PMDA, and FDA jurisdictions.
- Salvage Enucleation Counseling:Parental resistance to eye removal despite failed conservative protocols delays definitive surgery, elevating metastatic risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinoblastoma Treatment Market |
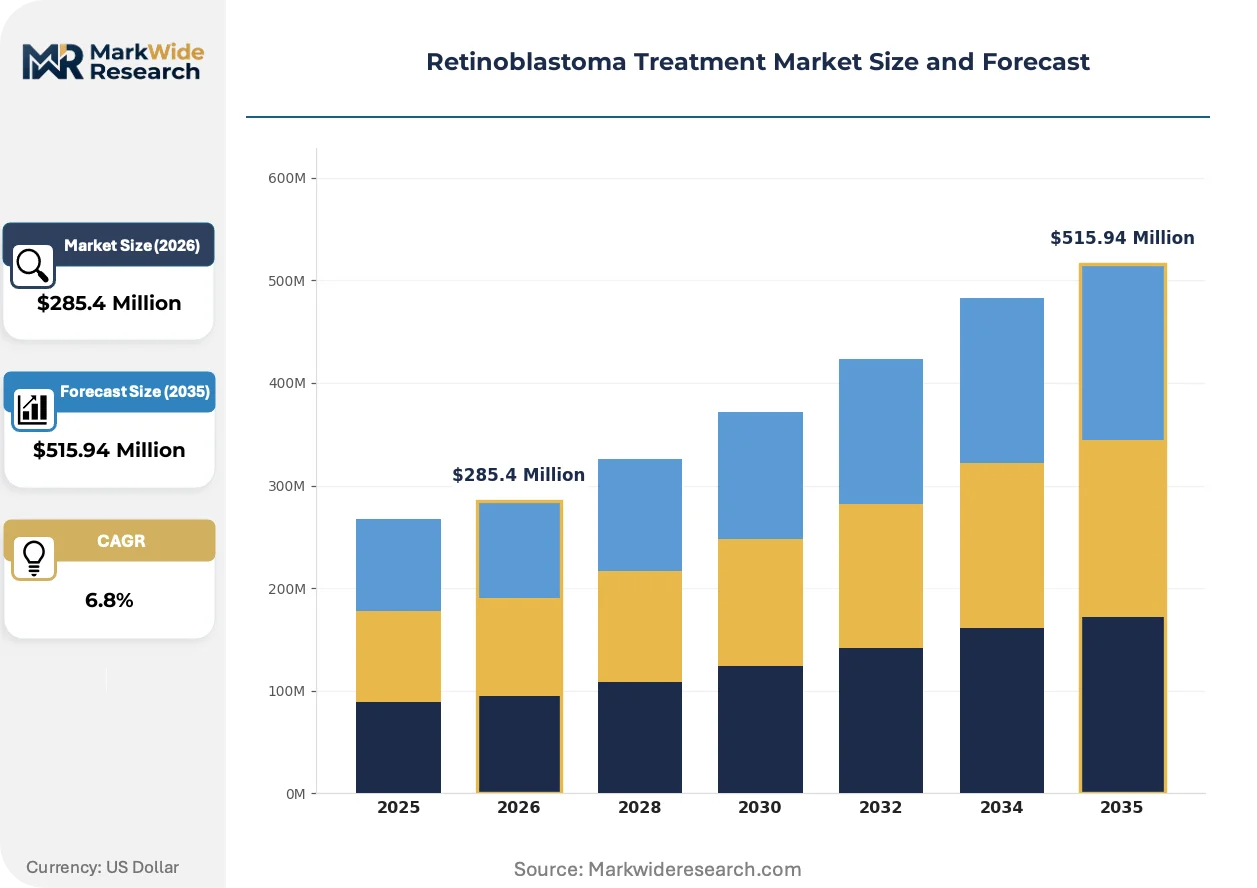
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Laser Therapy, Cryotherapy Delivery Mode: Intravitreal Injection, Intravascular Injection, Oral Administration, Topical Application End User: Pediatric Clinics, Cancer Hospitals, Research Laboratories, Specialty Clinics Treatment Stage: Initial Phase, Advanced Phase, Recurrent Phase, Maintenance Phase |
| Companies Covered | Novartis, Merck & Co., Baxter International, Theriva Biologics, Bristol-Myers Squibb Company, Pfizer, GlaxoSmithKline, Advancium Health, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinoblastoma Treatment Market Strategic Shifts & Innovations
Retinoblastoma care is bifurcating between organ-sparing intensity-modulated protocols and definitive genetic interventions, with delivery technology and regulatory science racing to match biological understanding.
Intravitreal melphalan injection systems are integrating nanofilter sterilization and real-time particle detection into closed-loop compounding workflows. Pediatric ocular oncology units at specialized children's hospitals adopt these platforms to reduce per-dose preparation variability. The technology is integrating quality assurance standards that previously governed commercial manufacturing into point-of-care pharmacy operations.
EMA's pediatric investigation plan requirements now mandate ocular pharmacokinetic substudies for all systemic oncology candidates with retinal penetration potential. Pharmaceutical sponsors must demonstrate juvenile toxicity profiles and dosing algorithms before adult approval. European trial sites consequently capture disproportionate enrollment in international retinoblastoma protocols, shifting clinical research gravity toward EMA-aligned regulatory strategies.
Parental demand for fertility-preserving alternatives to alkylating agents is compressing treatment decision timelines and elevating consultation requirements. Families now present with pre-negotiated preferences for globe-salvage sequences, displacing traditional physician-directed protocol selection. This pattern concentrates in United States metropolitan centers where second-opinion access and patient advocacy organization density are highest.
Retinoblastoma Treatment Market Segmentation
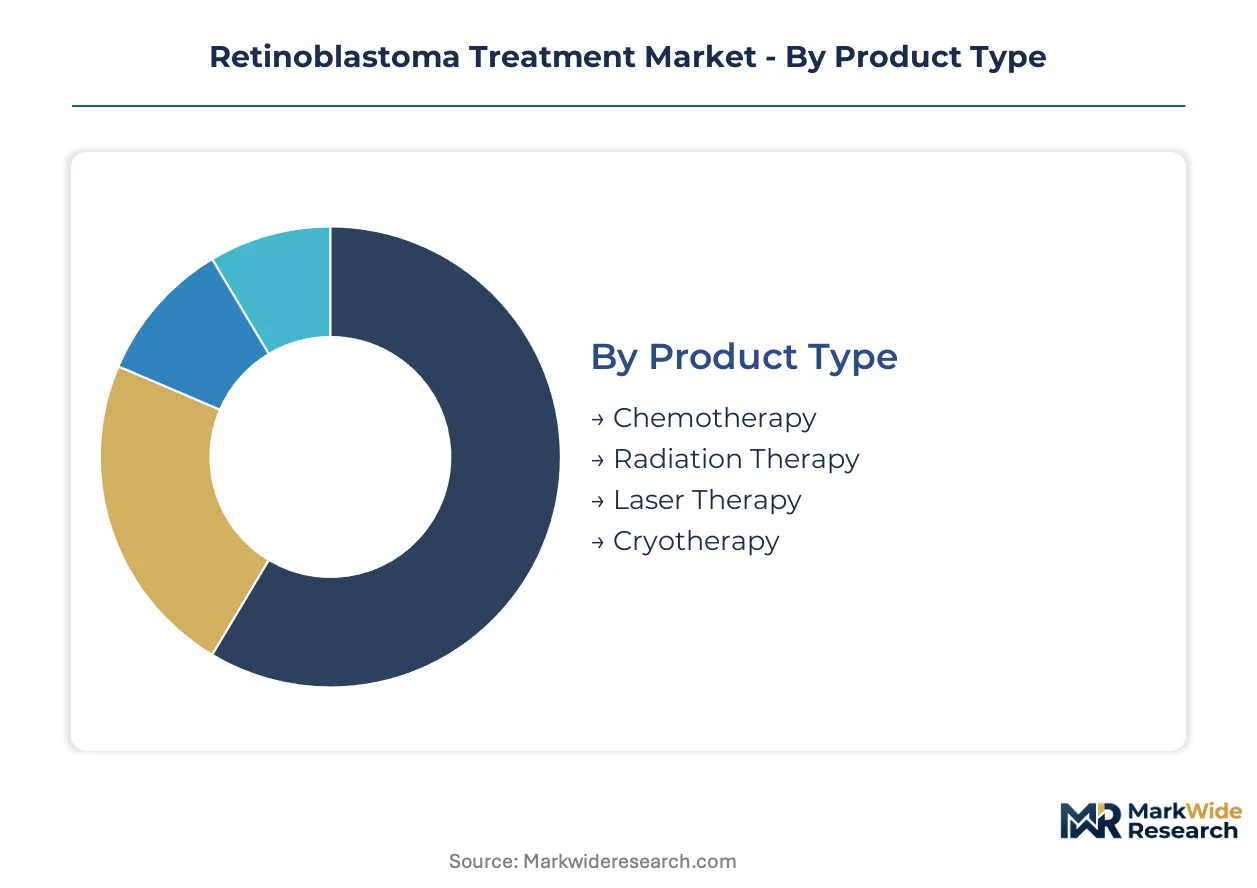
Retinoblastoma treatment modalities fragment across intervention intensity, anatomical delivery precision, and care setting specialization. Each segmentation axis reveals distinct procurement patterns, reimbursement pathways, and compounding infrastructure requirements that shape commercial strategy.
Product Type:
Chemotherapy dominates as the embedded backbone of multimodal protocols, while laser and cryotherapy function as standalone margin-preserving options for early-stage disease.
- Chemotherapy:Systemic and intraocular alkylating agents—melphalan, carboplatin, topotecan—form the structural core of first-line treatment sequences. Demand concentrates in metropolitan pediatric oncology centers where sterile compounding infrastructure supports intravitreal preparation protocols.
- Laser Therapy:Transpupillary thermotherapy and photocoagulation deliver targeted thermal destruction of small tumors without systemic exposure. Adoption clusters in specialized retinoblastoma units within children's hospitals in the United States and Germany, driven by parental preference for organ-sparing interventions.
- Radiation Therapy:External beam and plaque brachyface modalities face accelerating displacement from chemo-reduction protocols due to secondary malignancy risks.
- Cryotherapy:Trans-scleral freezing applications retain niche utility for anterior segment tumors and salvage after failed primary interventions.
Chemotherapy leads volumes today; laser therapy is gaining share fastest in early-stage presentations.
Delivery Mode:
Route selection determines hospitalization intensity, toxicity profile, and pharmacy infrastructure investment, with direct ocular delivery commanding premium positioning over systemic alternatives.
- Intravitreal Injection:Direct melphalan or topotecan instillation into the vitreous cavity achieves localized tumor control with minimal systemic absorption. United States children's hospitals and German university clinics drive adoption, constrained by specialized sterile compounding requirements.
- Intravascular Injection:Ophthalmic artery chemosurgery delivers superselective chemotherapy infusion via femoral catheterization. Demand concentrates in high-volume retinoblastoma centers in New York, Philadelphia, and London where interventional neuroradiology and pediatric anesthesia capabilities co-locate.
- Oral Administration:Systemic carboplatin, etoposide, and vincristine combinations retain utility for bilateral disease and extraocular extension.
- Topical Application:Periocular formulations provide limited penetration and occupy marginal positioning in contemporary protocols.
Intravitreal injection anchors revenue per patient; intra-arterial delivery is climbing the fastest in bilateral advanced disease.
End User:
Care setting determines reimbursement tier, protocol complexity, and specialist density, with dedicated pediatric institutions capturing the highest-acuity cases.
- Cancer Hospitals:Comprehensive pediatric oncology departments integrate retinoblastoma care within broader solid tumor programs. Major metropolitan centers in the United States—Memorial Sloan Kettering, Children's Hospital of Philadelphia, St. Jude—concentrate patient volumes that justify dedicated ocular oncology pharmacy investments.
- Specialty Clinics:Dedicated ophthalmic oncology practices deliver focused expertise with streamlined referral pathways. Adoption is expanding in Germany and the United Kingdom where centralized national health systems concentrate rare disease expertise.
- Pediatric Clinics:General pediatric settings primarily handle initial suspicion and referral coordination rather than definitive therapy.
- Research Laboratories:Academic medical centers with active clinical trial portfolios capture protocol-driven treatment assignments and biomarker collection mandates.
Cancer hospitals command the highest procedure volumes; specialty clinics are expanding most quickly as standalone ophthalmic oncology networks proliferate.
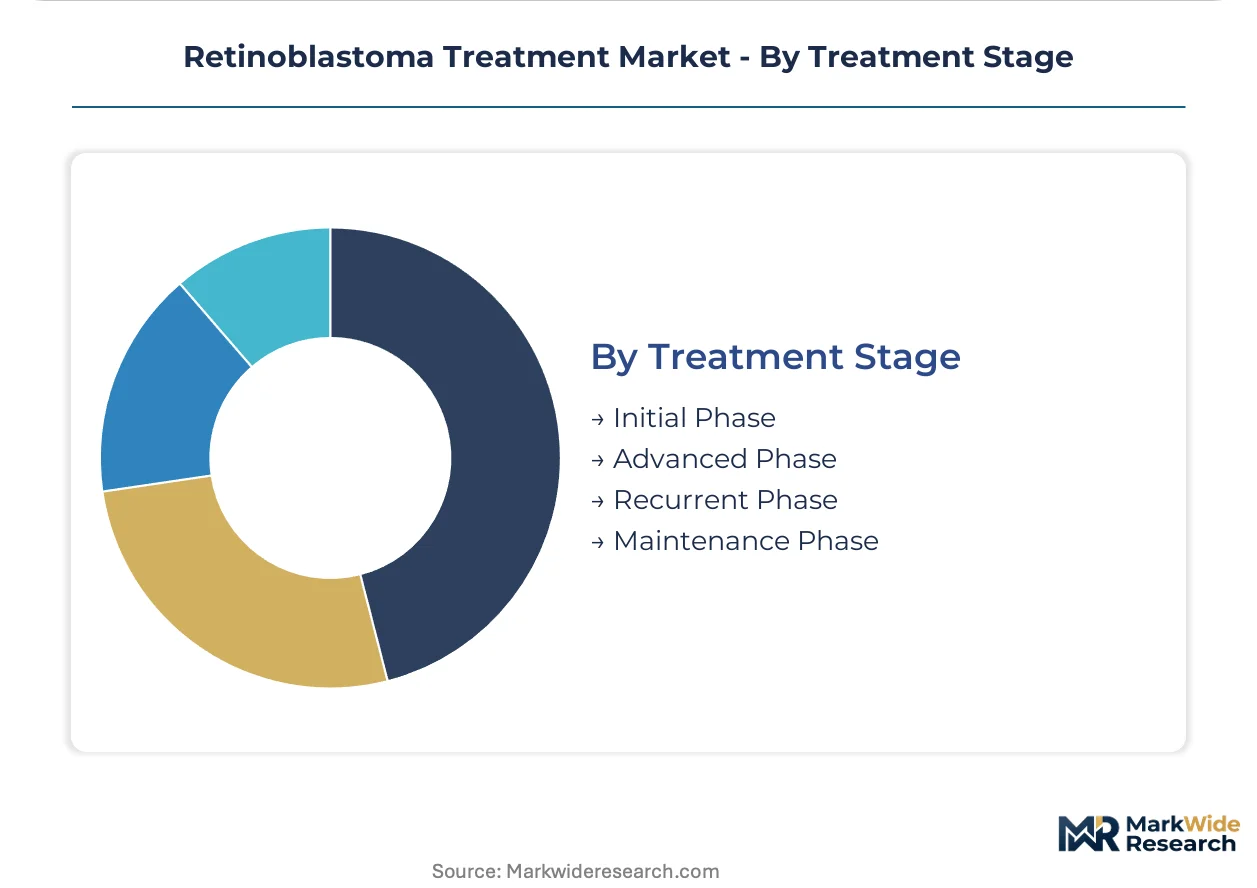
Treatment Stage:
Stage-based segmentation dictates intervention intensity, salvage sequencing, and enucleation counseling requirements across the care continuum.
- Initial Phase:Chemo-reduction combined with focal consolidation targets globe preservation in treatment-naive patients. Demand concentrates in screening-dense populations where red reflex photography enables early detection—primarily the United States, Western Europe, and urban centers in Japan.
- Advanced Phase:Intensive multi-agent protocols and external beam alternatives address massive subretinal seeding and optic nerve involvement. Cases cluster in regions with delayed presentation patterns including sub-Saharan Africa and South Asia.
- Recurrent Phase:Salvage intravitreal injections, re-irradiation, or enucleation decisions follow failed primary interventions.
- Maintenance Phase:Surveillance protocols with examination under anesthesia extend through childhood to detect second primary tumors and trilateral disease.
Initial phase procedures dominate absolute volumes; recurrent phase interventions carry the steepest per-patient cost trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where retinoblastoma therapy development concentrates, with the United States and European Union offering accelerated pathways that offset higher compliance costs against faster commercialization timelines.
United States
Specialized pediatric oncology centers in New York, Philadelphia, and Houston drive intravitreal chemotherapy adoption through dedicated ocular pharmacy investments. The FDA's orphan drug designation compresses clinical trial timelines for rare pediatric indications. Memorial Sloan Kettering and Children's Hospital of Philadelphia anchor high-volume treatment networks that justify sterile compounding infrastructure.
Germany
University clinics in Heidelberg and Essen concentrate ophthalmic artery chemosurgery expertise alongside interventional neuroradiology capabilities. EMA pediatric investigation plans mandate ocular pharmacokinetic substudies that attract international trial sponsorship. The country's centralized rare disease referral system funnels bilateral cases into specialized units with integrated pediatric anesthesia services.
United Kingdom
London's Royal London Hospital and Birmingham Children's Hospital coordinate national retinoblastoma screening through the National Health Service's centralized pathology network. NICE technology appraisals determine reimbursement for novel delivery systems across England and Wales. The cluster at Great Ormond Street Hospital integrates gene therapy trials within standard-of-care pathways.
Japan
PMDA's sakigake designation accelerates review for pediatric ocular oncology innovations, drawing sponsors to Tokyo and Osaka trial sites. The country's neonatal screening expansion via red reflex photography is compressing presentation-stage severity. Keio University Hospital and National Center for Child Health and Development anchor specialized fellowship training that feeds regional center expansion.
India
Delayed presentation patterns in rural regions sustain demand for advanced-phase interventions at tertiary centers in Mumbai, Delhi, and Chennai. CDSCO's pediatric oncology guidelines are filtering which compounding technologies achieve hospital adoption. Tata Memorial Centre and Sankara Nethralaya are building regional screening networks to shift detection earlier in disease progression.
Retinoblastoma Treatment Market Key Industry Players
United States-based pharmaceutical conglomerates anchor one tier through integrated oncology platforms; Swiss and German specialists hold differentiated positions in rare disease biologics and precision delivery systems. Market structure tilts toward consolidated control at the development stage, with fragmentation emerging in sterile compounding and point-of-care pharmacy services. Three archetypes dominate: diversified oncology majors with pediatric divisions, rare disease biotechs with orphan drug focus, and hospital-affiliated compounding specialists. Competitive moves center on cell and gene therapy infrastructure acquisitions and strategic partnerships with specialized children's hospital networks.
Within the diversified oncology tier, Novartis and Pfizer represent contrasting strategic positions—Novartis through cell and gene therapy infrastructure anchoring advanced intervention supply, Pfizer through hospital distribution network integration extending from clinical development. Merck & Co. occupies a position exemplifying immunotherapy platform extension into pediatric indications. Bristol-Myers Squibb Company and Johnson & Johnson sit within the same archetype, leveraging broad oncology portfolios to capture retinoblastoma as part of rare pediatric cancer strategies. The specialist tier includes Theriva Biologics and Advancium Health, which exemplify rare disease biotechs pursuing orphan drug pathways with targeted mechanism approaches.
| Leading Market Players |
|---|
| Novartis |
| Merck & Co. |
| Baxter International |
| Theriva Biologics |
| Bristol-Myers Squibb Company |
| Pfizer |
| GlaxoSmithKline |
| Advancium Health |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Alkylating agent API spot prices cascade through sterile compounding infrastructure investments into three-tier pricing stratification across academic medical centers, community hospital networks, and ambulatory specialty clinics. Cost absorption capacity at each tier determines protocol accessibility and compounding technology adoption velocity.
Pricing Analysis
Hospital pharmacy markup layers dominate final treatment pricing, with direct-to-manufacturer purchasing agreements compressing distributor margins at high-volume retinoblastoma centers. Price differentiation separates FDA-designated orphan drug formulations from standard chemotherapy equivalents, with certification-driven premiums widening as sterility assurance requirements intensify. Cost compression in intravitreal preparation runs through specialized cleanroom facility amortization schedules. Pediatric oncology departments at academic medical centers exhibit lowest price sensitivity; rural referral hospitals face acute budget constraints.
Supply Chain Analysis
Dual-sourcing mandates for melphalan and topotecan APIs compel hospital pharmacies to qualify multiple sterile compounding vendors, fragmenting procurement leverage. Active pharmaceutical ingredient production concentrates in India, Switzerland, and the United States, with Swiss manufacturers anchoring high-purity oncology-grade supply. Finished formulation relies on isolator technology, borosilicate vials, and nanofilter membranes. Single-source vulnerability in isotope-dependent quality control testing creates bottleneck exposure. Distribution runs through cold-chain logistics specialists serving metropolitan pediatric oncology clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retinoblastoma treatment has matured into a quality-differentiated market where parental demand for globe-preserving protocols shifts procurement toward premium intravitreal delivery systems. This preference compression elevates sterile compounding capabilities from cost center to strategic differentiator.
For Market Incumbents: Deepen vertical integration into point-of-care pharmacy infrastructure to defend against emerging compounding specialists. Secure exclusive supply agreements with high-volume children's hospital networks in the United States and Germany. Anchor capacity investments in metropolitan treatment hubs where patient concentration justifies dedicated ocular oncology pharmacy buildouts. Lock in EMA pediatric investigation plan partnerships to capture European trial enrollment gravity. For New Entrants and Emerging Players: FDA orphan drug designation in the United States opens a window for rare disease biotechs to capture accelerated approval timelines and extended exclusivity premiums. Target sub-Saharan Africa screening network buildouts as the most penetrable geography, where delayed presentation patterns sustain demand for salvage intervention innovation. Pursue gene therapy platform development as the go-to-market angle, positioning beyond chemo-reduction paradigms toward definitive RB1 correction protocols. For Investors and Strategic Acquirers: Asymmetric upside sits with cell and gene therapy infrastructure plays that can anchor CRISPR-based retinoblastoma pipelines. Five-to-ten year viability hinges on clinical translation velocity rather than near-term revenue capture. Prioritize acquisition targets possessing adeno-associated viral vector manufacturing capabilities and pediatric ocular oncology specialist relationships. Watch PMDA sakigake designation adoption rates as the inflection signal for Asia-Pacific regulatory pathway maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA accelerated approval compresses development timelines for rare pediatric indications. |
| Intravitreal Compounding Infrastructure | Sterile pharmacy investments at Memorial Sloan Kettering anchor premium positioning. |
| EMA Pediatric Investigation Alignment | Mandated ocular pharmacokinetic substudies shift trial gravity toward European sites. |
| Gene Therapy Platform Development | CRISPR-RB1 correction protocols promise definitive intervention beyond chemotherapy. |
| Sub-Saharan Screening Network Deployment | Red reflex photography expansion creates early detection pipelines in underserved regions. |
Research Approach
Multiple input streams — primary interviews with pediatric ocular oncologists, hospital pharmacy directors, and regulatory affairs specialists; secondary validation through FDA orphan drug filings, EMA pediatric investigation plan submissions, and ClinicalTrials.gov protocol registries; plus customs data on alkylating agent API trade flows — were reconciled through bottom-up patient-volume modeling and top-down pharmaceutical expenditure triangulation.
Historical treatment pattern analysis cross-referenced against expert panel input on intravitreal adoption velocity shaped the projection framework across the analysis window. Segmentation dimensions encompassed treatment modality, delivery route, end-user facility type, and disease stage severity. CAGRs were derived from compounding infrastructure investment trajectories and regulatory pathway timeline compression effects. Forecast inputs incorporated parental preference survey data on globe-salvage prioritization and specialist fellowship training pipeline constraints.
Revisions become necessary when FDA pediatric oncology guidance shifts, EMA investigation plan requirements expand, or gene therapy clinical readouts accelerate regulatory pathway competition materially. Deviation in sterile compounding technology standardization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Conjunctivitis Treatment Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Retinal Disorder Treatment Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Age-Related Macular Degeneration Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Dacryocystitis Market