
 Paper Moisture Meter Market | 2026-2036
Paper Moisture Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Moisture Meter Market Outlook
China is narrowing its import dependence on European moisture meter calibration systems through domestic laboratory accreditation expansion. Kett leverages its resistive sensor heritage to anchor premium handheld positioning across East Asian paper mills. Testo competes on channel density, sustaining distribution partnerships with industrial maintenance suppliers in the DACH region. Delmhorst specializes in portable pin-style designs, occupying the restoration and printing quality control niche where rapid spot-checking dominates.
Paper moisture meters are precision instruments that measure the water content in paper stock, pulp sheets, and finished products using electrical impedance, capacitance, or electromagnetic wave absorption principles, typically operating across moisture ranges of 0–50% with ±0.5% accuracy to prevent warping, curl, and print registration defects in commercial production. Handheld meters lead unit volume due to their deployment flexibility on mill floors and in incoming inspection stations, while continuous monitoring systems capture the fastest growth trajectory as integrated Industry 4.0 retrofits replace manual sampling protocols in large paper manufacturers. Microwave technology segments command premium positioning where non-contact, high-speed web measurement is required, though capacitive systems dominate installed base economics across mid-tier pulp mills.
ISO 287 standardization for paper moisture determination shapes product calibration requirements, while FDA compliance frameworks govern moisture documentation in food-contact packaging substrates produced by integrated paper manufacturers. EPA effluent guidelines for pulp and paper mills indirectly drive moisture control investments by tightening water recovery targets that depend on precise drying optimization. Stakeholders must monitor how EU Ecodesign for Sustainable Products Regulation evolves recycled content mandates, since moisture variability in recovered fiber streams demands more sophisticated meter deployment across quality control checkpoints.
Market Dynamics
Pulp mills across Southeast Asia are retrofitting quality control checkpoints with continuous monitoring systems to meet tightening moisture tolerance thresholds in recycled paper grades, compressing the upgrade cycle for legacy handheld units.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Germany's implementation of stricter moisture thresholds for recycled fiber streams is forcing integrated paper manufacturers to deploy additional meter checkpoints across finishing lines.
- Indonesia's pulp-and-paper corridor expansion:Capacity additions near Surabaya are generating concentrated demand for calibration-capable handheld units in incoming inspection stations.
- Microwave non-contact measurement:High-speed web applications in coated paper production are pulling premium system upgrades as mills eliminate manual sampling bottlenecks.
Market Restraints
- Calibration gas and reference material costs:Volatility in certified moisture reference standards sourced from European metrology institutes inflates total cost of ownership for ISO 287-compliant systems.
- Sensor component concentration:Precision capacitive sensor substrates depend heavily on specialized ceramic foundries in Japan, creating single-source vulnerability for mid-tier meter assemblers.
- Resistive pin-style obsolescence pressure:Destructive testing methods face displacement from non-contact alternatives in premium printing quality control workflows.
Strategic Opportunities
- Domestic laboratory accreditation expansion:China's narrowing import dependence on European calibration systems creates opening for locally certified meter suppliers to capture maintenance contract flows.
- Industry 4.0 retrofit integration:Convergence between microwave sensing and edge computing architectures enables real-time moisture mapping across entire machine widths.
- Food-contact packaging compliance documentation:FDA moisture recordkeeping mandates for integrated paper manufacturers are expanding meter deployment into previously unmonitored substrate production lines.
Industry Challenges
- Metrology technician scarcity:Qualified personnel capable of ISO 287 calibration traceability are concentrated in legacy European and Japanese industrial centers, constraining Southeast Asian mill autonomy.
- Legacy DCS integration complexity:Continuous monitoring retrofits face protocol mismatches with decades-old distributed control systems still operating in major North American pulp facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Moisture Meter Market |
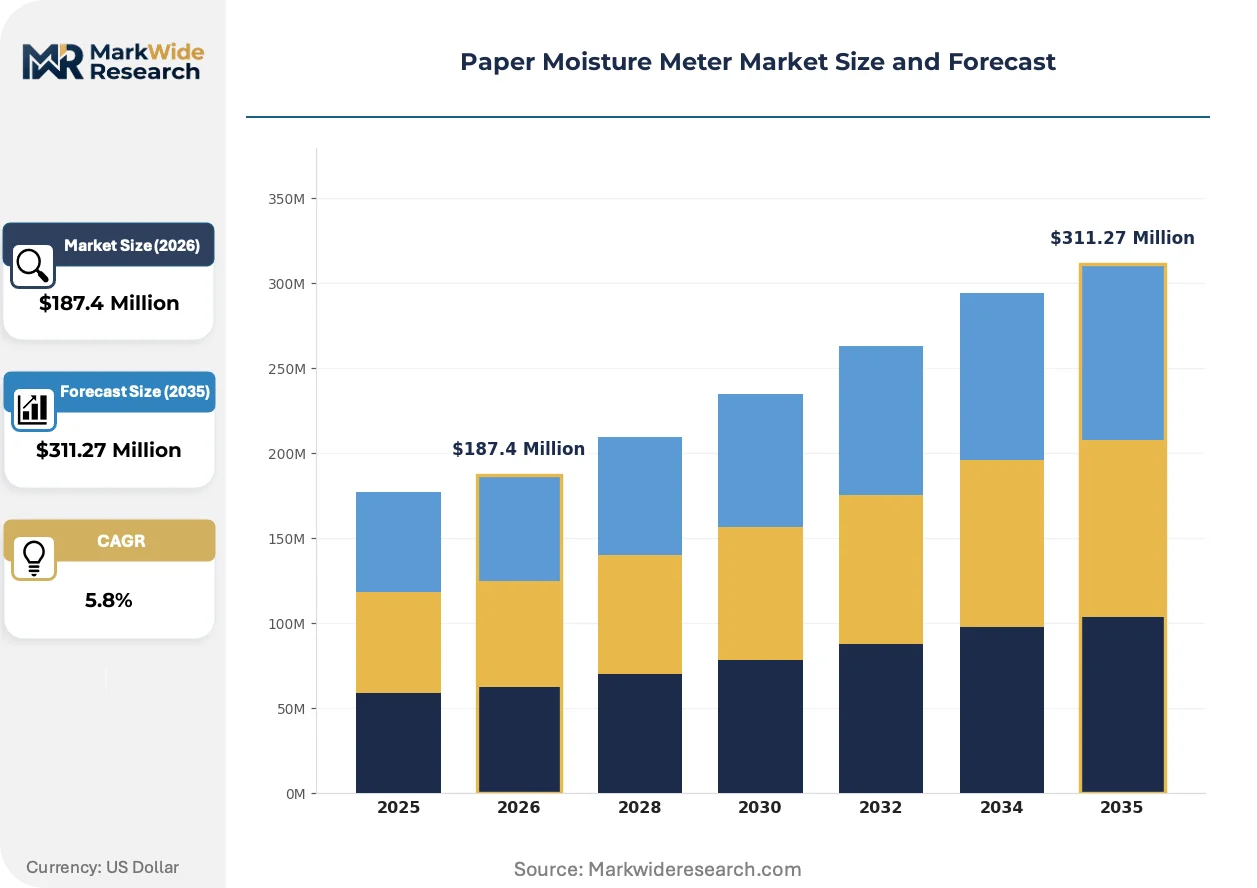
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Meters, Tabletop Meters, Continuous Monitoring Systems, Smart Meters Application: Pulp Production, Paper Manufacturing, Printing Industry, Quality Control End User: Pulp Mills, Paper Manufacturers, Printers, Research Institutions Technology: Capacitive, Resistive, Infrared, Microwave |
| Companies Covered | Kett, Testo, Delmhorst, GE Measurement & Control, Ametek, Mettler Toledo, Protimeter, Rotronic, Shimadzu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Moisture Meter Market Strategic Shifts
Measurement architectures are fragmenting between portable spot-checking tools for restoration and printing niches and permanently mounted web monitoring systems that feed directly into mill-wide optimization platforms.
Microwave resonance moisture detection is hybridizing with machine vision surface analysis to enable simultaneous water content and coating weight measurement in a single non-contact pass. Coated specialty paper producers in Germany and Finland are piloting these integrated heads at machine speeds exceeding prior capacitive limits. The convergence is compressing the addressable market for standalone thickness gauges while expanding total instrumentation spend per production line.
EPA effluent guidelines for pulp and paper mills are tightening water recovery targets that depend on precise drying optimization, indirectly mandating moisture control investments across integrated facilities. The regulatory pressure is most acute in US Southeast kraft linerboard mills where effluent discharge permits now explicitly link to documented drying efficiency protocols. Equipment suppliers are responding with bundled compliance documentation packages that automate the audit trail for moisture management.
Buyer concentration among Southeast Asian pulp conglomerates is consolidating procurement authority into centralized technical committees that specify meter brands across multiple mill sites. Industrial maintenance distributors in the DACH region are losing direct mill access as these committees bypass traditional channel relationships for factory-direct calibration service contracts. The shift is most visible in Indonesia where two holding groups now control moisture meter specification for over a dozen separate production facilities.
Paper Moisture Meter Market Segmentation
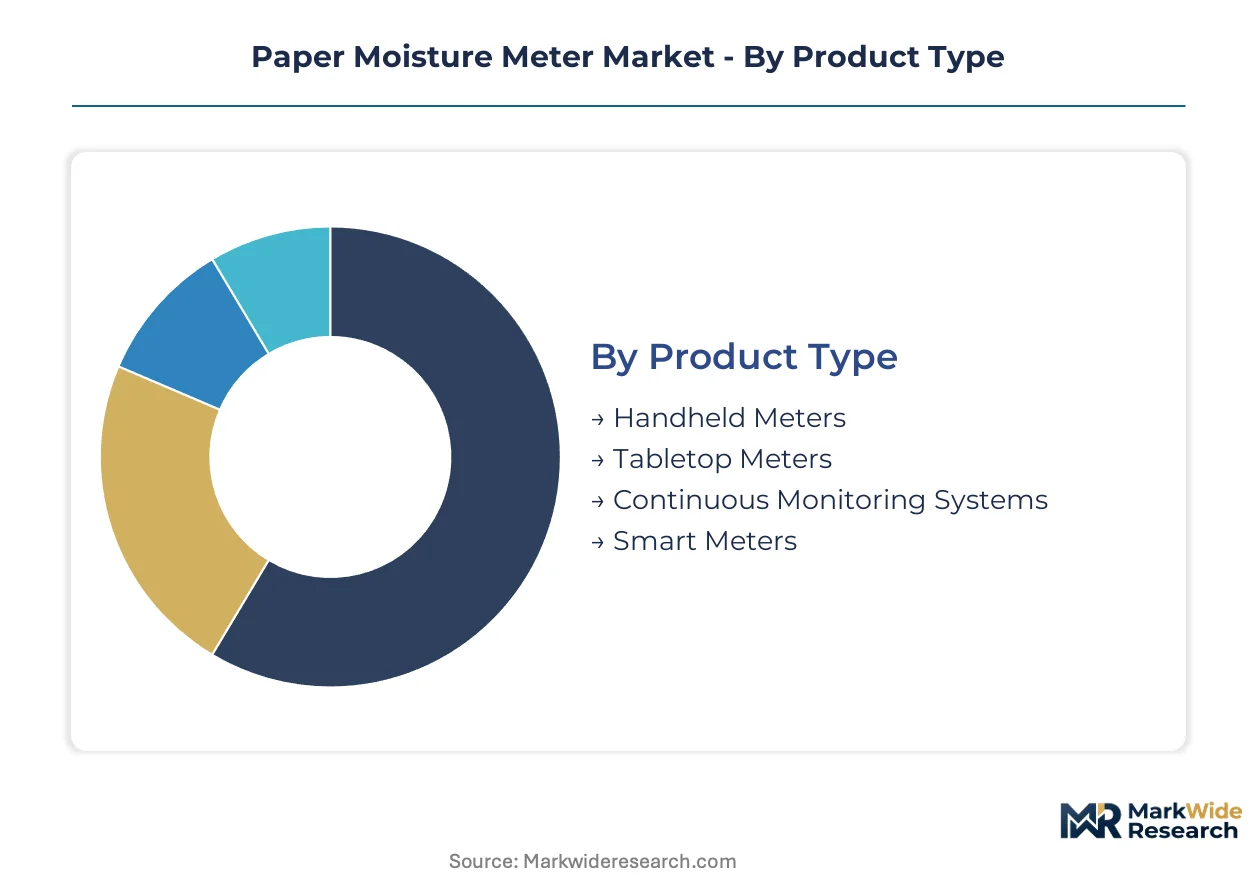
Paper moisture meter procurement patterns diverge sharply between capital-intensive continuous installations and portable spot-checking equipment, with service contract structures and calibration frequencies varying by an order of magnitude across product categories. Segment-specific buying committees—maintenance engineers versus quality control managers versus R&D directors—drive incompatible vendor selection criteria that fragment supplier positioning.
Product Type:
After-sales service intensity escalates from handheld units requiring annual recalibration to continuous systems demanding 24/7 technical support contracts with guaranteed response times.
- Handheld Meters:Portable units with resistive pin or capacitive sensor heads dominate unit shipments through their deployment flexibility across incoming inspection stations and mill floor spot-checking. Demand concentrates in Indonesia's Surabaya pulp-and-paper corridor where calibration-capable handheld units serve quality control checkpoints at expanding mill complexes. Service intensity remains moderate with annual factory calibration cycles.
- Continuous Monitoring Systems:Permanently mounted web sensors feeding distributed control systems command premium pricing through real-time moisture mapping across full machine widths. German and Finnish coated specialty paper producers are retrofitting these systems to eliminate manual sampling bottlenecks at machine speeds exceeding prior capacitive limits. These installations require dedicated service engineers with ISO 287 traceability certification.
- Tabletop Meters:Laboratory-grade precision instruments serve R&D and incoming pulp inspection with ±0.1% accuracy specifications for reference standard verification.
- Smart Meters:Edge-computing-enabled handheld units with cloud connectivity and predictive calibration alerts are penetrating maintenance-intensive mill environments.
By volume, Handheld Meters leads. By growth pace, Continuous Monitoring Systems is ahead.
Application:
Application-specific accuracy requirements create three distinct cost tiers, with food-contact packaging mandates driving the steepest instrumentation spend per production line.
- Paper Manufacturing:Integrated production lines from stock preparation through finishing require multi-point moisture verification to prevent warping, curl, and print registration defects. US Southeast kraft linerboard mills under tightened EPA effluent guidelines are deploying additional checkpoints to document drying efficiency protocols. FDA moisture recordkeeping mandates for food-contact substrates are expanding meter deployment into previously unmonitored substrate production lines.
- Pulp Production:Brownstock and bleached pulp sheet moisture control determines downstream drying energy consumption and fiber quality consistency. Southeast Asian pulp mills are retrofitting quality control checkpoints with continuous monitoring systems to meet tightening moisture tolerance thresholds in recycled fiber streams.
- Printing Industry:Commercial web offset and gravure operations depend on rapid spot-checking to maintain ink adhesion and dimensional stability across roll-fed substrates.
- Quality Control:Standalone inspection stations serve third-party certification and customer audit requirements with documented ISO 287 traceability.
By installed base, Paper Manufacturing dominates. By regulatory-driven expansion, Pulp Production is climbing the fastest.
End User:
End-user scale and technical autonomy determine whether procurement flows through industrial distributors or direct factory relationships with embedded calibration services.
- Pulp Mills:Southeast Asian conglomerates are consolidating procurement authority into centralized technical committees that specify meter brands across multiple mill sites, bypassing traditional channel relationships. Buyer concentration in Indonesia—where two holding groups now control specifications for over a dozen facilities—is compressing vendor margins while expanding contract values.
- Paper Manufacturers:Integrated producers with in-house metrology laboratories maintain captive calibration capabilities that reduce service dependency. Germany's Ecodesign for Sustainable Products Regulation implementation is forcing additional meter checkpoint deployment across finishing lines handling recycled fiber streams.
- Printers:Commercial and publication gravure houses prioritize rapid-response portable units for job-to-job substrate verification.
- Research Institutions:National standards bodies and university pulp and paper programs anchor reference-grade instrument demand with extended calibration traceability chains.
By procurement volume, Paper Manufacturers leads. By specification influence consolidation, Pulp Mills is gaining share fastest.
Technology:
Technology selection trades off measurement speed, substrate destructiveness, and capital intensity across web speeds and accuracy requirements.
- Microwave:Non-contact resonance detection enables high-speed web measurement without substrate interruption, commanding premium positioning in coated paper production. German and Finnish producers are piloting hybrid microwave-machine vision heads for simultaneous water content and coating weight measurement. These systems require specialized field service capabilities concentrated in legacy European and Japanese industrial centers.
- Capacitive:Dielectric measurement through plate electrodes dominates installed base economics across mid-tier pulp mills with proven reliability in harsh environments. Sensor substrates depend heavily on specialized ceramic foundries in Japan, creating single-source vulnerability for mid-tier meter assemblers.
- Resistive:Pin-style penetration measurement occupies the restoration and printing quality control niche where rapid spot-checking dominates, though destructive testing methods face displacement pressure from non-contact alternatives.
- Infrared:Near-infrared absorption suits laboratory reference applications and specialty paper surface moisture profiling with minimal sample preparation.
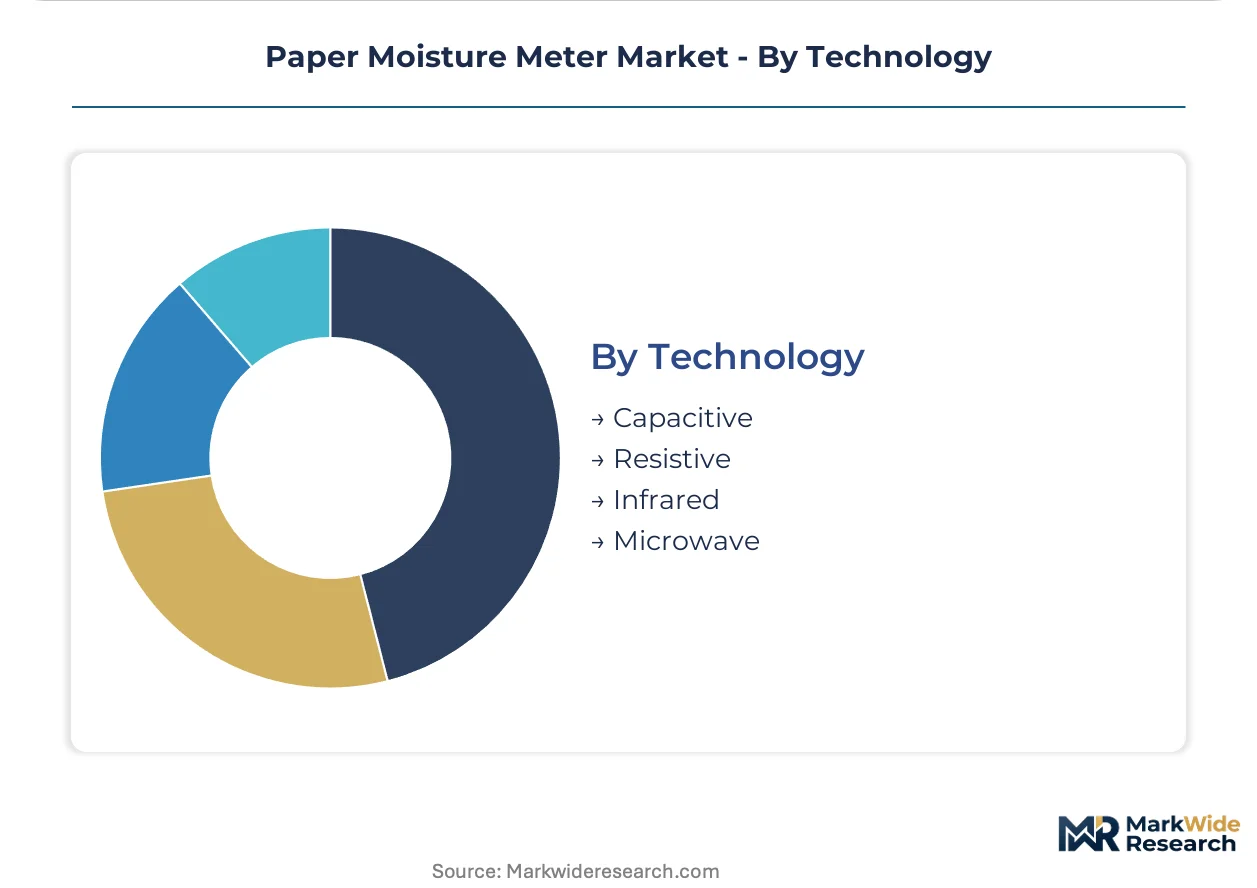
By installed base, Capacitive leads. By premium retrofit activity, Microwave is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA effluent guidelines anchor the United States as the dominant geography for moisture control investments, while Germany's Ecodesign regulation and Indonesia's pulp corridor expansion create parallel demand centers across three continents.
United States
Southeast kraft linerboard mills drive retrofit demand as EPA effluent discharge permits now explicitly link to documented drying efficiency protocols. FDA moisture recordkeeping mandates for food-contact packaging substrates expand meter deployment into previously unmonitored production lines. US Southeast kraft facilities concentrate investment where water recovery targets tighten fastest.
Germany
Coated specialty paper producers pilot hybrid microwave-machine vision systems for simultaneous water content and coating weight measurement. EU Ecodesign for Sustainable Products Regulation implementation forces additional checkpoint deployment across finishing lines handling recycled fiber streams. German mills near Stuttgart and Heidelberg lead premium system adoption for high-speed web applications.
Indonesia
Capacity additions near Surabaya generate concentrated demand for calibration-capable handheld units in incoming inspection stations. Two holding groups now control moisture meter specification for over a dozen separate production facilities, consolidating procurement authority into centralized technical committees. Buyer concentration compresses vendor margins while expanding contract values across the pulp-and-paper corridor.
China
Domestic laboratory accreditation expansion narrows import dependence on European calibration systems, creating openings for locally certified meter suppliers. SAMR oversight of measurement instrument standards shapes product certification requirements for mill-wide deployments. Yangtze River Delta integrated producers maintain captive calibration capabilities that reduce service dependency on foreign suppliers.
Japan
Specialized ceramic foundries anchor precision capacitive sensor substrate supply, creating single-source vulnerability for mid-tier meter assemblers worldwide. METI industrial standards govern moisture meter performance specifications for domestic and export markets. Osaka-area component fabricators concentrate capacity for dielectric measurement substrates that dominate installed base economics.
Paper Moisture Meter Market Competitive Environment
Capability concentration sits with sensor technology specialists; scale advantage sits with diversified instrumentation conglomerates. The vendor base stratifies across three tiers: heritage resistive sensor houses, diversified environmental measurement platforms, and precision laboratory equipment multinationals. Two strategic archetypes dominate competitive positioning: technology licensing partnerships for microwave resonance systems and backward integration into ceramic sensor substrate production. Geographic expansion through factory-direct calibration service contracts and portfolio diversification into edge-computing-enabled smart meters represent the dominant competitive moves.
Within the heritage sensor tier, Kett exemplifies premium handheld positioning anchored in resistive measurement heritage, while Testo occupies the diversified environmental instrumentation space through channel density in industrial maintenance distribution. Delmhorst represents the portable pin-style specialization archetype, serving restoration and printing quality control niches where rapid spot-checking dominates. These three anchors illustrate how competitive positioning fragments across incompatible customer selection criteria—maintenance engineers versus quality control managers versus R&D directors—preventing any single vendor from capturing cross-segment scale economies.
| Leading Market Players |
|---|
| Kett |
| Testo |
| Delmhorst |
| GE Measurement & Control |
| Ametek |
| Mettler Toledo |
| Protimeter |
| Rotronic |
| Shimadzu |
| Others |
Value Chain & Pricing Dynamics
Japanese ceramic foundries specializing in precision capacitive sensor substrates command outsized influence over mid-tier meter pricing, concentrating margin capture upstream while downstream assemblers face cost pass-through pressure from single-source component dependencies.
Pricing Analysis
Continuous monitoring systems in Germany command 40-60% premiums over equivalent installations in Southeast Asia, reflecting embedded calibration service contracts and ISO 287 traceability documentation. Three-tier pricing structure across premium, standard, and economy levels separates microwave resonance systems from capacitive mid-range units and resistive handheld devices. Cost compression in the handheld tier is intensifying because Indonesian buyer consolidation forces volume discounts across dozen-facility procurement committees. Pulp mills with centralized technical specifications exhibit lowest price sensitivity; independent commercial printers show highest.
Supply Chain Analysis
Osaka-area contract manufacturers and specialized ceramic foundries hold concentrated capacity for dielectric sensor substrates, with secondary assembly clusters in Germany and China. Raw material dependencies include alumina ceramic substrates, precision resistive alloys, and certified moisture reference standards. Single-source vulnerability in Japanese ceramic foundries creates supply chain risk for mid-tier assemblers lacking alternative qualified suppliers. Distribution runs through industrial maintenance distributors in the DACH region and factory-direct calibration service contracts in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified metrology technicians capable of ISO 287 calibration traceability remain concentrated in legacy European and Japanese industrial centers, constraining Southeast Asian mill autonomy and creating persistent capability bottlenecks for market expansion.
For Market Incumbents: Entrench positioning through captive calibration service networks in Indonesia's Surabaya corridor, where two holding groups now control specifications for over a dozen facilities. Backward integration into ceramic sensor substrate production reduces single-source vulnerability from Japanese foundries. Invest in edge-computing-enabled smart meter development to preempt displacement from microwave-machine vision hybrid systems. For New Entrants and Emerging Players: Mid-tier pulp mills in Vietnam and Thailand represent the most penetrable entry point, bypassing consolidated procurement committees dominating Indonesia. Target commercial printing quality control niches where rapid spot-checking demands outpace incumbent service responsiveness. Pursue domestic laboratory accreditation in China to capture maintenance contract flows from import-dependent calibration systems. For Investors and Strategic Acquirers: Capital is best deployed toward precision sensor technology specialists with proven microwave resonance expertise and existing field service infrastructure. Long-term viability over a five-to-ten-year horizon favors vendors with demonstrated Industry 4.0 retrofit integration capabilities. Monitor EPA effluent guideline enforcement intensity in US Southeast kraft linerboard mills as inflection indicator for compliance-driven moisture control investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Factory-direct contracts in Indonesia bypass distributor margin compression from buyer consolidation. |
| Ceramic Sensor Substrate Backward Integration | In-house production of dielectric substrates reduces single-source dependency on Japanese foundries. |
| Smart Meter Edge Computing Development | Predictive calibration alerts penetrate maintenance-intensive mill environments with cloud connectivity. |
| Domestic Laboratory Accreditation | China's SAMR-certified suppliers capture maintenance flows from European calibration import dependence. |
| Microwave-Machine Vision Hybrid Systems | German and Finnish coated paper producers pilot simultaneous water content and coating weight measurement. |
Study Parameters
A spread of perspectives from mill maintenance directors, quality control managers, OEM procurement teams, and aftermarket service heads converged on the working assumptions for this analysis. Primary interviews combined with secondary validation from customs/trade data, SEC filings of diversified instrumentation conglomerates, ISO 287 standard documentation, and EPA effluent guideline records. Bottom-up unit shipment estimates and top-down market size triangulation anchored the quantitative framework.
Demand-supply-balance framing across the analysis window modeled segmentation dimensions including product type, application tier, technology platform, and regional regulatory cluster. CAGRs were derived through iterative reconciliation of historical trajectory with projected adoption curves. Industry-specific forecast inputs incorporated pulp mill capacity expansion timelines and EU Ecodesign implementation schedules for recycled fiber moisture thresholds.
Macroeconomic conditions sit as an overlay; deviation in pulp commodity pricing, capital expenditure cycles at integrated paper manufacturers, or currency volatility in Southeast Asian markets would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Quarterly review of EPA permit issuance activity, EU Ecodesign delegated act publications, and Indonesian pulp holding group procurement committee decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Gold Tester Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Paper Tester Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
United States Material Testing Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Paint Tester Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Japan Material Testing Market