
 Global Analytical Standards Market | 2026-2036
Global Analytical Standards Market Size, Share, and Industry Trends Forecast 2026-2036
Global Analytical Standards Market Foresight
Contract research organizations and third-party testing laboratories are reorganizing procurement priorities around certified reference materials with ISO 17034 accreditation. Merck KGaA leverages its Darmstadt manufacturing base to dominate European distribution of pharmaceutical-grade standards. Agilent Technologies sustains technology leadership through co-development of instrument-specific calibration kits that lock in recurring standards demand. Waters Corporation specializes in mass spectrometry reference libraries that anchor its competitive position in environmental and food safety applications.
Analytical standards are highly characterized substances with certified purity values, established metrological traceability, and documented uncertainty parameters used to calibrate instruments, validate methods, and qualify laboratory performance. Manufacturers synthesize these materials through gravimetric preparation, quantitative nuclear magnetic resonance, or comparative chromatographic assays against primary reference materials, with lot-specific certificates detailing expiration dates and storage conditions. Reference standards command the largest revenue pool due to mandatory regulatory compliance in pharmaceutical release testing, while environmental testing applications represent the fastest-expanding segment as PFAS and microplastic monitoring protocols multiply across jurisdictions. Calibration standards retain mature, predictable demand tied to instrument installation and preventive maintenance cycles.
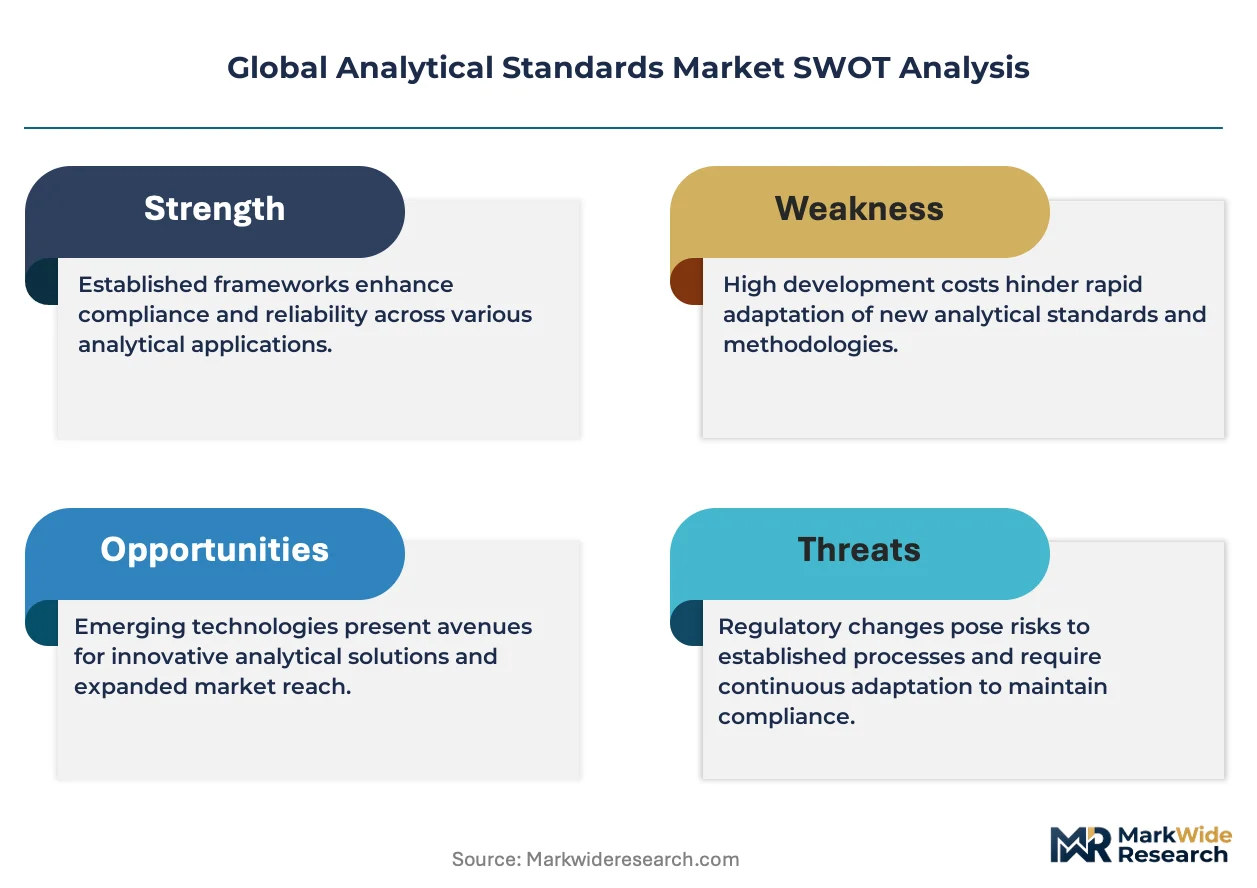
FDA's current good manufacturing practice guidelines, EMA's ICH Q7 specifications, and ISO 17034 general requirements for reference material producers collectively shape product specifications, accreditation burdens, and market access thresholds for analytical standards suppliers. EPA Method 1633 for PFAS analysis and the EU Green Deal's chemical sustainability targets are forcing laboratories to retool with new certified reference materials at accelerated cadences. Stakeholders must monitor how regulatory expansion into emerging contaminants reshapes portfolio priorities and certification investments.
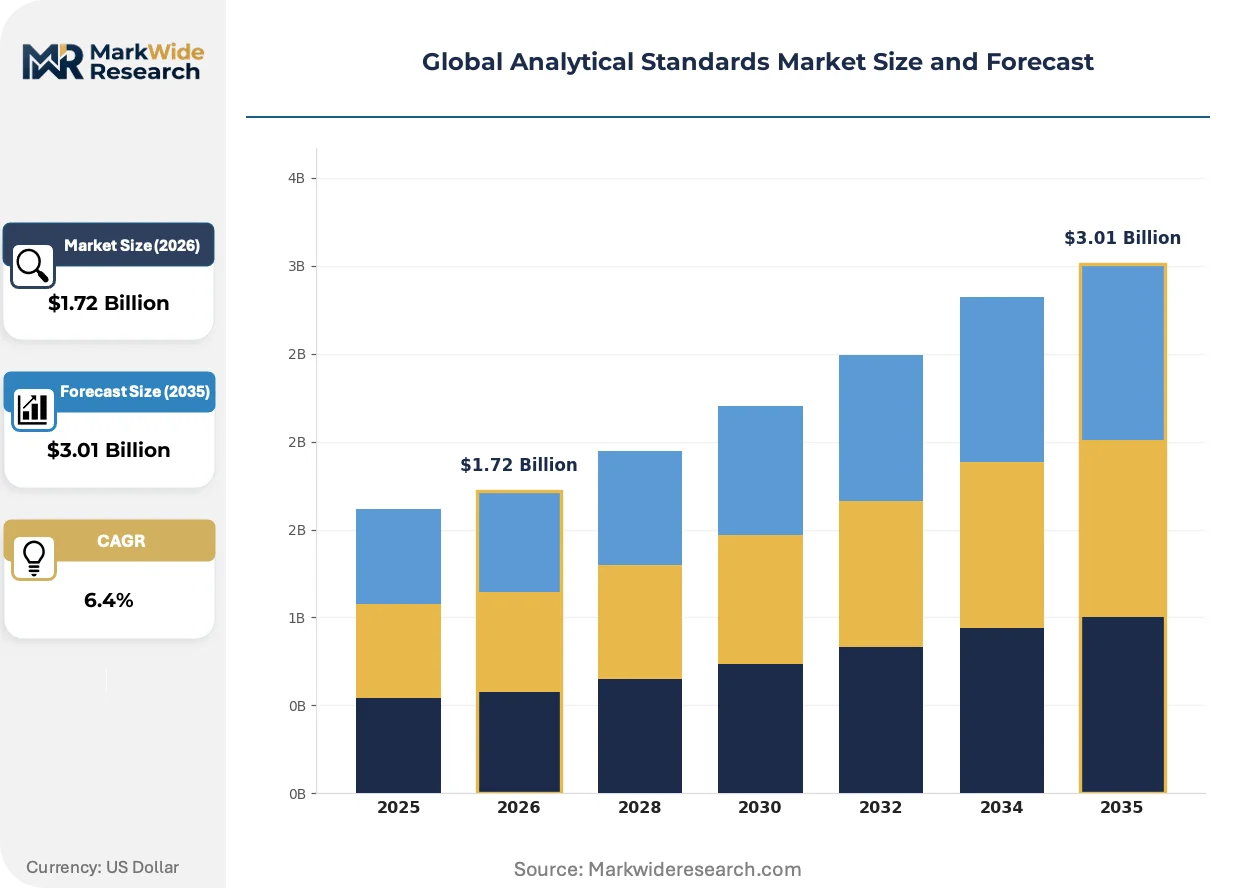
Market Dynamics
Mass spectrometry-based multi-residue testing is compressing specification tolerances and forcing laboratories to recalibrate procurement around certified reference materials with documented metrological traceability.
Growth Catalysts
- EPA Method 1633:PFAS monitoring mandates across US environmental laboratories are generating sustained demand for per- and polyfluoroalkyl substance certified reference materials with isotopically labeled internal standards.
- Pharmaceutical release testing:FDA current good manufacturing practice guidelines and EMA ICH Q7 specifications require certified reference materials for impurity profiling and assay validation in drug substance batches.
- EU Green Deal chemical sustainability targets:Accelerated retooling of analytical protocols for emerging contaminants is expanding the addressable market for environmental testing-grade standards.
Market Restraints
- High-purity precursor scarcity:Synthesis of pharmaceutical-grade standards depends on limited suppliers of ultra-pure starting materials with documented chain of custody.
- ISO 17034 accreditation concentration:European supply chains anchor on German and UK reference material producers, creating geographic vulnerability in certified reference material availability.
- Gravimetric preparation bottlenecks:Primary reference material production requires specialized balance calibration and environmental controls that constrain batch throughput.
Strategic Opportunities
- Microplastic monitoring protocols:Fragmented jurisdictional standards across EU member states create first-mover advantage for suppliers developing polymer particle certified reference materials.
- Biologics biosimilar expansion:N-glycan and host cell protein reference standards represent underdeveloped product categories with limited accredited suppliers.
- Digital certificate integration:Blockchain-anchored lot documentation and automated expiration alerting can differentiate supplier value propositions for contract research organizations.
Industry Challenges
- Comparative chromatographic assay expertise:Quantitative nuclear magnetic resonance competency gaps constrain in-house reference material qualification capabilities at mid-size testing laboratories.
- Preventive maintenance cycle synchronization:Calibration standard demand fluctuates unpredictably with instrument installation schedules and laboratory audit timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Analytical Standards Market |
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reference Standards, Calibration Standards, Internal Standards, Secondary Standards Application: Pharmaceutical Analysis, Environmental Testing, Food Safety, Chemical Research, Forensic Analysis End Use Industry: Pharma Manufacturing, Environmental Agencies, Food Processing, Chemical Production, Crime Labs Packaging Type: Vials, Ampoules, Bottles, Sealed Tubes, Dropper Bottles |
| Companies Covered | Merck KGaA, Agilent Technologies, Waters Corporation, LGC Standards, PerkinElmer, Thermo Fisher Scientific, Restek Corporation, SPEX CertiPrep, US Pharmacopeial Convention, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Analytical Standards Market Shifts & Advancements
Synthetic methodology advances and regulatory protocol proliferation are fragmenting demand patterns across instrument-specific calibration kits, isotopically labeled internal standards, and matrix-matched certified reference materials.
Quantitative nuclear magnetic resonance is bifurcating the primary reference material production landscape. Pharmaceutical manufacturers and national metrology institutes adopt qNMR for direct purity assignment without chromatographic comparison. This technology is compressing the traditional hierarchy between primary and secondary reference materials, enabling faster lot release and reducing dependency on gravimetric preparation facilities.
REACH authorization requirements and the EU F-Gas Regulation are forcing reformulation of solvent-based standard solutions. Laboratories across Germany, France, and the Netherlands face mandatory transitions to alternative carrier matrices for volatile organic compound standards. Environmental testing applications bear the highest compliance burden, with suppliers accelerating development of aqueous and solid-phase microextraction-compatible formulations.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships at multi-site pharmaceutical and food safety testing networks. Third-party testing laboratories in North America and Western Europe increasingly delegate standards sourcing to specialized distributors with ISO 17034-accredited warehousing. This channel shift concentrates volume with intermediaries possessing cold chain logistics and certificate management capabilities.
Global Analytical Standards Market Segmentation
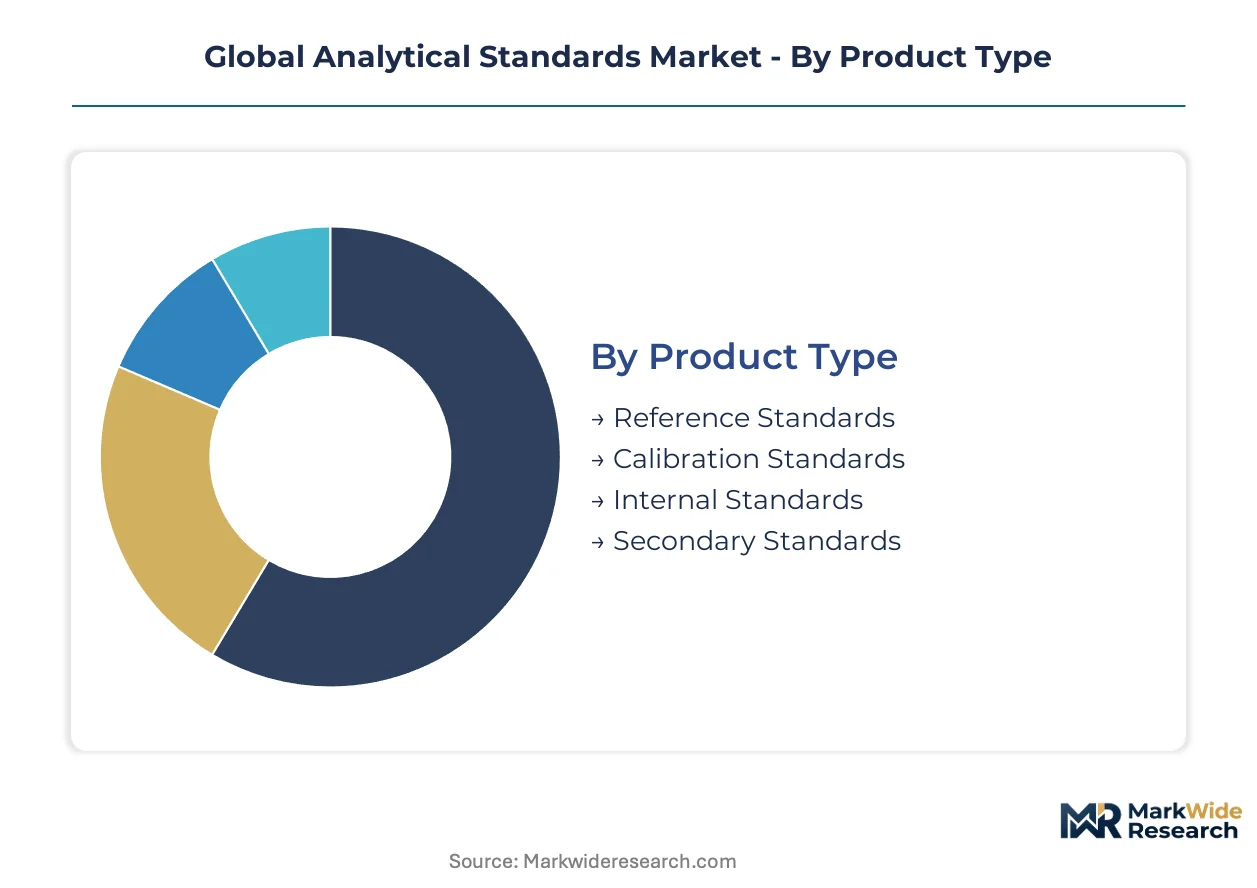
Segmentation in analytical standards reflects divergent certification requirements across regulated industries. Product purity grades, packaging integrity, and end-use protocols create distinct commercial tiers with non-substitutable specifications.
Product Type:
Reference standards dominate export flows to pharmaceutical manufacturers seeking FDA and EMA compliance, while calibration standards serve domestic laboratory maintenance cycles.
- Reference Standards:Certified materials with documented metrological traceability and uncertainty parameters assigned through gravimetric preparation or quantitative nuclear magnetic resonance. Demand concentrates in Germany and Switzerland where Merck KGaA and LGC Standards anchor European supply chains for chromatography-grade materials serving pharmaceutical release testing.
- Calibration Standards:Instrument-specific formulations used to establish measurement baselines during installation and preventive maintenance. Procurement patterns track Agilent Technologies and Waters Corporation instrument deployment schedules across North American and Western European contract research organizations.
- Internal Standards:Isotopically labeled analogs added to samples for quantitative recovery correction in mass spectrometry workflows.
- Secondary Standards:Materials qualified against primary reference materials for routine quality control applications in mid-size testing laboratories.
Reference standards hold the largest share; momentum sits with internal standards as PFAS and multi-residue testing protocols multiply.
Application:
Environmental testing commands premium pricing for matrix-matched certified reference materials, while pharmaceutical analysis drives volume through recurring batch release requirements.
- Pharmaceutical Analysis:Impurity profiling, assay validation, and dissolution testing applications requiring ICH Q7-compliant materials with documented chain of custody. FDA current good manufacturing practice guidelines mandate certified reference materials for every drug substance batch release, creating predictable demand concentration at multi-site manufacturing networks.
- Environmental Testing:PFAS monitoring under EPA Method 1633 and emerging contaminant protocols across EU member states. EPA and ECHA regulatory expansion into per- and polyfluoroalkyl substances is forcing accelerated retooling with isotopically labeled internal standards at US and German environmental laboratories.
- Food Safety:Pesticide residue and veterinary drug testing applications requiring multi-residue standard mixtures.
- Chemical Research:Method development and validation activities at academic and industrial R&D facilities.
- Forensic Analysis:Toxicology and controlled substance reference materials for crime laboratory accreditation.
Pharmaceutical analysis generates the highest revenue concentration; environmental testing is climbing the fastest on regulatory protocol proliferation.
End Use Industry:
Pharma manufacturing sources through consolidated procurement channels with ISO 17034-accredited distributors, while environmental agencies maintain direct manufacturer relationships for specialized formulations.
- Pharma Manufacturing:Multi-site networks requiring lot-specific certificates with blockchain-anchored documentation and automated expiration alerting for audit readiness.
- Environmental Agencies:Federal and state laboratories implementing EPA Method 1633 for PFAS analysis with mandatory transitions to aqueous carrier matrices under EU F-Gas Regulation compliance timelines.
- Food Processing:Third-party testing laboratories procuring through group purchasing organizations with cold chain logistics requirements.
- Chemical Production:In-house quality control and customer certification support applications.
- Crime Labs:Forensic toxicology facilities requiring DEA-controlled substance scheduling compliance for reference materials.
Pharma manufacturing dominates procurement volume; environmental agencies are expanding most quickly on monitoring mandate expansion.
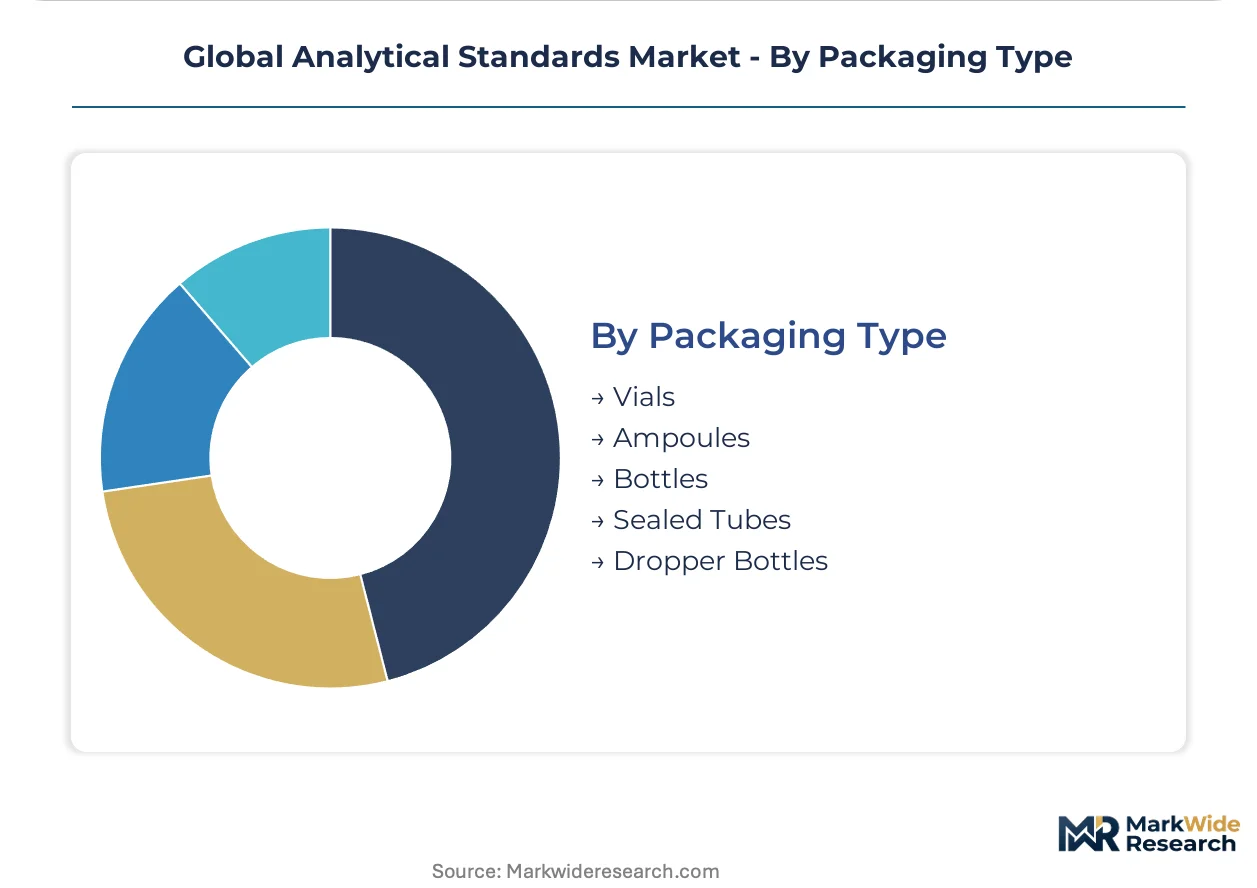
Packaging Type:
Ampoules and sealed tubes command premium positioning for air-sensitive and volatile compound stability, while vials serve high-throughput routine applications.
- Vials:Borosilicate glass containers with screw-cap closures for non-volatile standard solutions in chromatography workflows. High-throughput pharmaceutical quality control laboratories in the United States and Germany favor 2 mL amber vial formats compatible with autosampler trays.
- Ampoules:Hermetically sealed glass containers preserving anhydrous and oxygen-sensitive materials through flame-sealed neck construction. European suppliers including Merck KGaA maintain Darmstadt manufacturing capacity for ampoule-formatted pharmaceutical-grade standards requiring inert atmosphere protection.
- Bottles:Larger-volume containers for calibration standard preparation and dilution series workflows.
- Sealed Tubes:Polymer or metal-sealed formats for solid-phase microextraction-compatible formulations.
- Dropper Bottles:Convenience packaging for educational and method development applications.
Vials capture the highest unit volume; ampoules deliver the steepest margin expansion on stability-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified reference material production clusters in Germany and Switzerland, with Merck KGaA's Darmstadt facility and LGC Standards anchoring European supply chains for pharmaceutical-grade chromatography materials.
United States
EPA Method 1633 implementation across environmental laboratories drives PFAS-certified reference material demand. FDA current good manufacturing practice guidelines mandate certified reference materials for every drug substance batch release. Boston-Cambridge biopharma clusters and Research Triangle Park analytical facilities source through ISO 17034-accredited distributors with cold chain logistics.
Germany
Merck KGaA's Darmstadt manufacturing base dominates European distribution of pharmaceutical-grade standards. EMA ICH Q7 specifications and REACH authorization requirements shape product specifications for impurity profiling. Rhine-Main and Bavarian chemical clusters maintain direct manufacturer relationships for specialized aqueous carrier matrix formulations under EU F-Gas Regulation timelines.
China
NMPA pharmaceutical quality standards and expanding biosimilar production drive reference standard imports for method validation. Dual carbon goals and MEE environmental monitoring mandates accelerate retooling for emerging contaminant protocols. Shanghai and Suzhou pharmaceutical manufacturing networks consolidate procurement through group purchasing organizations.
Switzerland
Swissmedic pharmaceutical regulations and precision manufacturing heritage sustain premium positioning for gravimetric preparation facilities. Basel and Zurich analytical clusters specialize in isotopically labeled internal standards for mass spectrometry workflows. National metrology institutes adopt quantitative nuclear magnetic resonance for direct purity assignment without chromatographic comparison.
United Kingdom
LGC Standards anchors reference material distribution from Teddington and Manchester facilities serving EMA-aligned specifications post-Brexit. UKAS accreditation requirements and Environment Agency emerging contaminant protocols expand demand for matrix-matched certified reference materials. Oxford-Cambridge life science clusters source through specialized distributors with blockchain-anchored lot documentation.
Global Analytical Standards Market Competitive Landscape
Concentration sits with diversified life science conglomerates possessing ISO 17034-accredited manufacturing and established metrological traceability capabilities. Three archetypes dominate: integrated analytical instrument manufacturers bundling instrument-specific calibration kits; specialized reference material producers with gravimetric preparation expertise; and national metrology institutes supplying primary reference materials. Competitive moves center on co-development partnerships locking in recurring standards demand and geographic expansion of accredited warehousing capacity.
Among German and Swiss reference material specialists, Merck KGaA and LGC Standards exemplify the integrated production-distribution archetype with Darmstadt and Teddington manufacturing anchors. Agilent Technologies occupies a position within the instrument-manufacturer tier, sustaining technology leadership through co-developed calibration kits. These three entities represent the concentration of accredited supply chain control across European pharmaceutical and environmental testing markets.
| Leading Market Players |
|---|
| Merck KGaA |
| Agilent Technologies |
| Waters Corporation |
| LGC Standards |
| PerkinElmer |
| Thermo Fisher Scientific |
| Restek Corporation |
| SPEX CertiPrep |
| US Pharmacopeial Convention |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between pharmaceutical manufacturers and ISO 17034-accredited suppliers lock in multi-year supply access while stabilizing price visibility against raw material volatility. These arrangements concentrate procurement power with Merck KGaA and LGC Standards, compressing margins for mid-tier distributors lacking gravimetric preparation capabilities.
Pricing Analysis
FDA current good manufacturing practice guidelines dictate the pricing tier structure across pharmaceutical-grade reference materials. Three-tier pricing structure across pharmaceutical-grade, environmental-grade, and research-use-only levels separates certified materials with full metrological traceability from routine quality control grades. Price differentiation rests on ISO 17034 accreditation status and documented chain of custody depth. Cost compression in research-use tiers is intensifying because contract research organizations consolidate procurement through group purchasing organizations. Environmental testing laboratories exhibit highest price sensitivity due to aqueous carrier matrix reformulation costs under EU F-Gas Regulation timelines.
Supply Chain Analysis
Gravimetric preparation facility accreditation bottlenecks in Germany and Switzerland constrain certified reference material throughput. Production draws from ultra-pure precursor suppliers in Switzerland and the United Kingdom, with isotopically labeled internal standards anchored in Basel and Zurich analytical clusters. Single-source vulnerability concentrates at Darmstadt manufacturing bases dependent on flame-sealed ampoule production lines. Distribution runs through ISO 17034-accredited warehousing intermediaries with cold chain logistics serving North American and Western European contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified reference material supply functions as a service-attach opportunity where digital certificate integration and automated expiration alerting expand recurring revenue faster than instrument hardware sales. Recurring standards demand locks in predictable procurement relationships with multi-site pharmaceutical networks.
For Market Incumbents: Secure ISO 17034 accreditation expansion into Chinese and Indian manufacturing corridors before NMPA and CDSCO mandate local sourcing requirements. Defend against qNMR-enabled national metrology institutes by deepening gravimetric preparation expertise and blockchain-anchored lot documentation capabilities. For New Entrants and Emerging Players: Anchor in biologics reference standards for N-glycan and host cell protein applications where accredited suppliers remain scarce. Target microplastic monitoring protocols across fragmented EU member state jurisdictions. Lead with polymer particle certified reference materials and aqueous carrier matrix formulations under REACH authorization timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among instrument-specific calibration kit developers with co-development partnerships locking in multi-year standards demand. Five-to-ten year viability favors specialized reference material producers with captive gravimetric preparation facilities. Monitor EPA Method 1633 expansion into additional per- and polyfluoroalkyl substance categories as inflection signal for PFAS-certified reference material demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17034 Accreditation Expansion | EMA ICH Q7 specifications and FDA guidelines mandate certified reference materials for batch release testing compliance. |
| Digital Certificate Integration | Blockchain-anchored lot documentation differentiates supplier value propositions for audit-ready contract research organizations. |
| Aqueous Carrier Matrix Development | EU F-Gas Regulation timelines force solvent-free standard solution reformulation for environmental testing applications. |
| Biologics Reference Standard Portfolio | N-glycan and host cell protein standards address underdeveloped categories with limited accredited supplier competition. |
| Microplastic Monitoring Protocol Development | Fragmented EU jurisdictional standards create first-mover advantage for polymer particle certified reference materials. |
Research Methodology
The analysis maps reference standards, calibration standards, internal standards, and secondary standards, each validated through quality control laboratory directors, regulatory affairs managers at pharmaceutical manufacturers, environmental testing procurement leads, and national metrology institute scientists. Primary fieldwork combined structured interviews with secondary validation against EPA Method 1633 implementation records, EMA ICH Q7 submission databases, ISO 17034 accreditation registries, and customs trade flows for high-purity precursor materials. Bottom-up segment sizing triangulated against top-down pharmaceutical manufacturing output and instrument installation base estimates.
Consistency checks validated volume and value outputs against external benchmarks including instrument manufacturer deployment schedules, group purchasing organization contract disclosures, and national metrology institute annual reports. The analytical framework modeled product type, application, end-use industry, and packaging format dimensions across the projection horizon. CAGRs derived from regulatory mandate expansion rates, instrument replacement cycles, and accredited supplier capacity additions. Forecast inputs incorporated PFAS monitoring protocol proliferation and biologics biosimilar production ramp timelines.
Material uncertainties — regulatory expansion into additional emerging contaminant categories, ISO 17034 accreditation processing delays, and qNMR technology adoption curves — sit outside the modeled envelope. Forecasts reflect assumptions about gravimetric preparation facility throughput and precursor material supply continuity. Practitioners should keep alternative scenarios live as EPA Method 1633 scope expansion and EU Green Deal chemical sustainability targets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
HPLC Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Pitting Machines Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Corrosion Testing Services Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
In Vitro Toxicity Testing Market