
 Chlorine Meter Market | 2026-2036
Chlorine Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorine Meter Market Analysis
Skilled field calibration technicians is reorganizing how chlorine meter vendors allocate service resources across installed bases. Thermo Fisher Scientific leverages its analytical instrumentation heritage to anchor premium laboratory meter positions in North American utilities. Hanna Instruments competes through aggressive channel control in the residential and light commercial pool segment. Endress+Hauser Group dominates process-critical online installations with its integrated liquid analysis platforms.
A chlorine meter is an analytical instrument that quantifies free, combined, or total chlorine concentration in aqueous samples, typically employing electrochemical cells with membraned amperometric sensors or colorimetric reagent-based photometric detection to achieve detection limits below 0.01 mg/L. These devices serve the essential industrial purpose of ensuring disinfectant residuals meet safety thresholds in potable water distribution, wastewater effluent discharge, and recreational aquatic environments. Online meters command the largest installed value pool due to continuous regulatory compliance requirements, while portable electrochemical units represent the fastest-expanding category as smaller municipalities replace laboratory-only workflows with point-of-use verification. The food industry application segment remains comparatively underpenetrated outside dairy and beverage processing, creating a margin opportunity for vendors with hygienic design certifications.
EPA Safe Drinking Water Act enforcement and the EU Drinking Water Directive's revised parametric values for disinfection byproducts are tightening residual chlorine monitoring mandates across municipal networks. FDA FSMA rules for process water in food facilities and ISO 9001-aligned quality systems in industrial plants further shape product certification requirements and procurement specifications. Stakeholders must track how emerging per- and polyfluoroalkyl substance regulations redirect capital from chlorine-based disinfection toward alternative oxidation technologies, with implications for meter demand trajectories in affected utility districts.
Market Dynamics
Municipal utilities are consolidating chlorine residual monitoring programs under unified SCADA architectures, compressing procurement cycles and favoring vendors with integrated liquid analysis platforms over standalone meter suppliers.
Growth Catalysts
- EPA Safe Drinking Water Act enforcement:Tightened residual chlorine mandates in US municipal networks are forcing distribution system upgrades and continuous monitoring installations.
- Membraned amperometric sensor advancement:Improved detection stability below 0.01 mg/L is expanding online meter deployment into secondary distribution points previously served by laboratory analysis.
- German utility network modernization:EU Drinking Water Directive parametric revisions are accelerating replacement of colorimetric benchtop systems with automated electrochemical stations.
Market Restraints
- Precious metal electrode cost volatility:Platinum and gold price swings in sensor manufacturing compress margins for mid-tier electrochemical meter producers.
- Single-source membrane supply concentration:Specialized ion-selective membrane production concentrates in German and Japanese specialty chemical suppliers, creating import dependency risks.
- Peracetic acid and UV substitution:Alternative oxidation technologies in food processing and pharmaceutical water systems are displacing chlorine-based disinfection in select utility districts.
Strategic Opportunities
- Indian municipal water expansion:Smart Cities Mission infrastructure investments are opening tender opportunities for online residual monitoring in secondary cities lacking laboratory capacity.
- IoT-integrated predictive maintenance:Cloud-connected chlorine meters with automated calibration alerts are creating recurring service revenue streams beyond hardware sales.
- FSMA process water rules:FDA food safety mandates are extending residual monitoring requirements into beverage and dairy processing facilities previously exempt from continuous verification.
Industry Challenges
- Field calibration technician scarcity:Specialized electrochemical sensor maintenance skills concentrate among aging utility workforces, constraining expansion of distributed monitoring networks.
- Legacy SCADA integration complexity:Proprietary communication protocols in existing plant control systems force costly middleware development for new meter installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorine Meter Market |
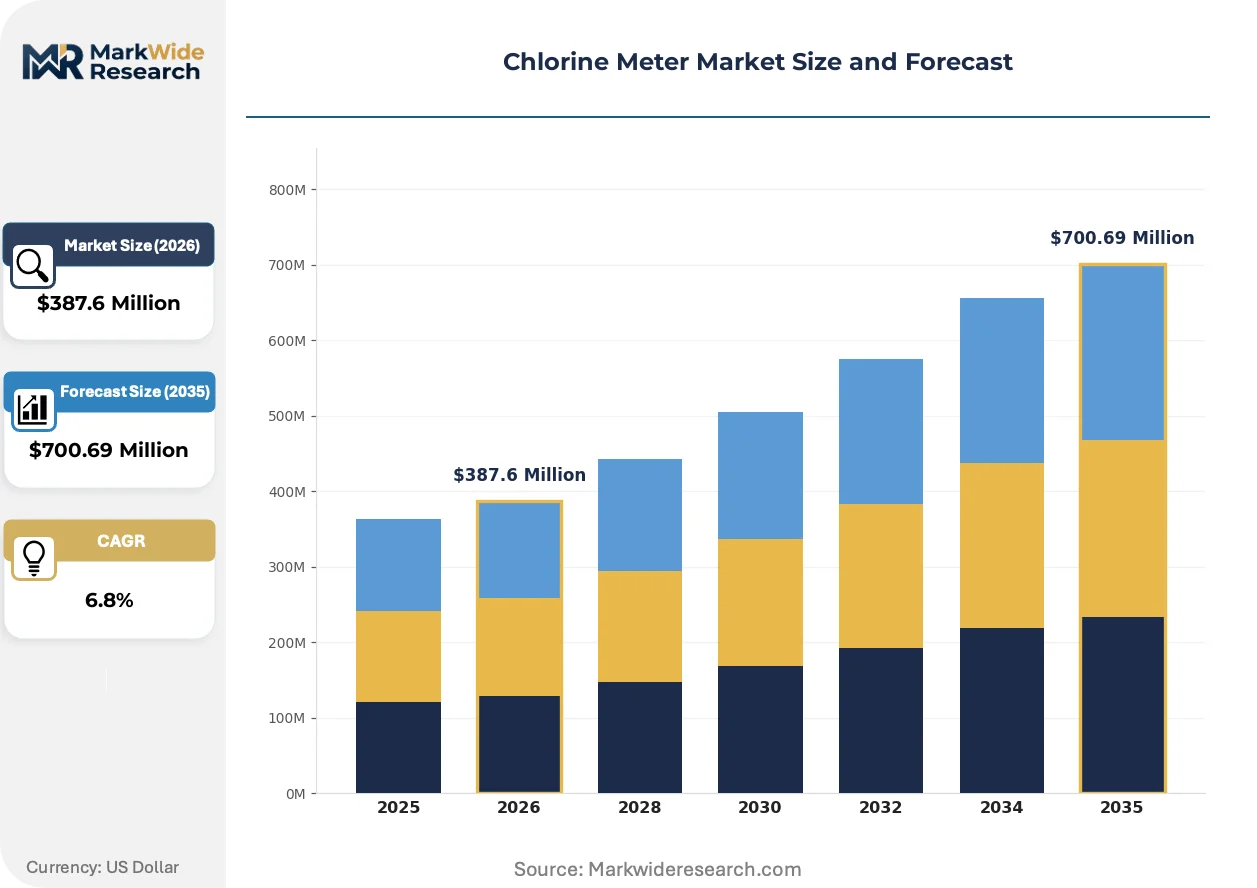
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Online Meters, Laboratory Meters, Handheld Meters Technology: Electrochemical, Colorimetric, Optical, Amperometric Application: Water Treatment, Wastewater Treatment, Pool Industry, Food Industry End User: Municipalities, Industrial Facilities, Aquaculture, Residential Users |
| Companies Covered | Thermo Fisher Scientific, Horiba Ltd., Emerson Electric Co., ABB Ltd., Xylem Inc., Endress+Hauser Group, Yokogawa Electric Corporation, Hanna Instruments, Hach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorine Meter Market Emerging Trajectories
Digital integration and sensor miniaturization are restructuring competitive advantage around data platforms rather than hardware accuracy alone, rewarding vendors with software capabilities and predictive analytics offerings.
Solid-state optical chlorine sensors are displacing traditional amperometric cells in portable meter applications. Water quality field technicians in US municipal departments are adopting handheld photometric units for point-of-use verification. This displacement is compressing the portable electrochemical segment and forcing incumbent vendors to develop hybrid sensing platforms.
EU Drinking Water Directive revisions on disinfection byproduct parametric values are tightening residual chlorine monitoring frequencies across German, French, and Dutch distribution networks. Municipal procurement specifications now mandate continuous online verification at network extremities. Small-scale utilities in Eastern Europe are responding with pooled purchasing cooperatives to access premium integrated systems.
After-sales service unbundling is fragmenting traditional meter-supplier relationships. Large US water utilities are separating hardware procurement from calibration service contracts, opening specialist maintenance providers. This pattern is most visible in California and Texas municipal systems with centralized asset management departments.
Chlorine Meter Market Segmentation
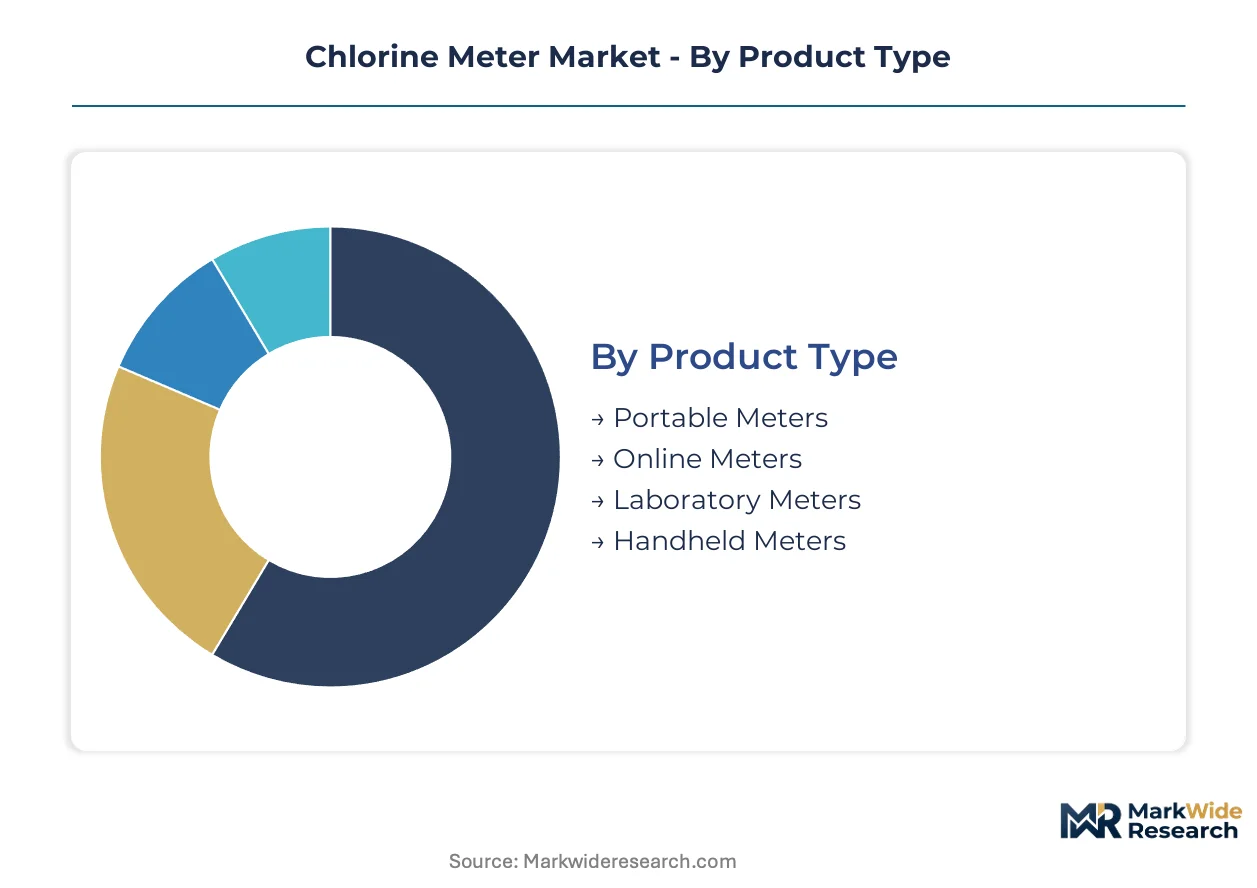
Segmentation in the chlorine meter market reveals divergent vulnerability profiles to substitute technologies and alternative disinfection methods. Product architecture, sensing modality, and end-use regulatory intensity collectively determine which categories face imminent displacement versus durable demand.
Product Type:
Substitution pressure concentrates most acutely on laboratory-bound systems as utilities shift toward distributed, real-time verification architectures.
- Portable Meters:Battery-powered electrochemical units with membraned amperometric sensors enable point-of-use residual verification at distribution network extremities. German and US municipal departments are deploying these for secondary monitoring points previously served by centralized laboratory analysis, driven by EU Drinking Water Directive enforcement tightening residual verification frequencies.
- Online Meters:Continuous-flow analyzers with automated calibration and SCADA integration dominate process-critical installations in municipal treatment plants. These systems anchor the largest installed value pool due to unbroken regulatory compliance requirements, though peracetic acid and UV substitution in select utility districts constrains expansion in disinfection-diversifying facilities.
- Laboratory Meters:Benchtop colorimetric and photometric systems retain positions in reference-grade verification and regulatory auditing workflows.
- Handheld Meters:Solid-state optical variants are displacing traditional amperometric cells in field technician toolkits for rapid spot-checking.
Online meters anchor the volume base while portable meters gain share at the steepest rate.
Technology:
Cost tier stratification separates premium sensing modalities from commodity alternatives, with electrode material costs compressing margins at the mid-market.
- Electrochemical:Membraned amperometric cells with platinum or gold electrodes achieve detection stability below 0.01 mg/L, serving regulatory mandates for trace-level residual monitoring. Precious metal price volatility constrains mid-tier producers while integrated platform vendors absorb fluctuations through service bundling.
- Amperometric:Direct current measurement without membrane separation offers lower unit costs but reduced selectivity in complex matrices. Industrial facilities with controlled influent chemistry favor these for continuous monitoring of process water loops.
- Colorimetric:Reagent-based photometric detection retains positions in laboratory reference methods and portable applications requiring minimal calibration infrastructure.
- Optical:Solid-state sensors eliminate consumable membranes and electrodes, reducing lifetime ownership costs for distributed monitoring networks.
Electrochemical technology commands the premium tier while optical sensing climbs the fastest as membrane-free architectures reduce field maintenance burdens.
Application:
Application maturity varies sharply, with underpenetrated segments presenting margin expansion opportunities for certified vendors.
- Water Treatment:Municipal potable water distribution networks generate the largest demand concentration, with EPA Safe Drinking Water Act enforcement and EU Drinking Water Directive revisions mandating continuous residual verification at network extremities. Smart Cities Mission infrastructure investments in India are extending this requirement to secondary cities lacking laboratory capacity.
- Wastewater Treatment:Effluent discharge permits with chlorine residual limits drive online meter deployment at treatment plant outfalls. Tightened receiving water quality standards in German and Dutch jurisdictions are accelerating replacement of grab-sample protocols with automated monitoring.
- Pool Industry:Residential and commercial aquatic facilities represent a price-sensitive volume segment with seasonal demand patterns.
- Food Industry:Dairy and beverage processing facilities dominate residual monitoring adoption, with FDA FSMA process water rules extending requirements into previously exempt operations. Hygienic design certifications create vendor differentiation in this comparatively underpenetrated segment.
Water treatment anchors the volume base while food industry applications expand most quickly as regulatory coverage broadens beyond dairy and beverage processing.
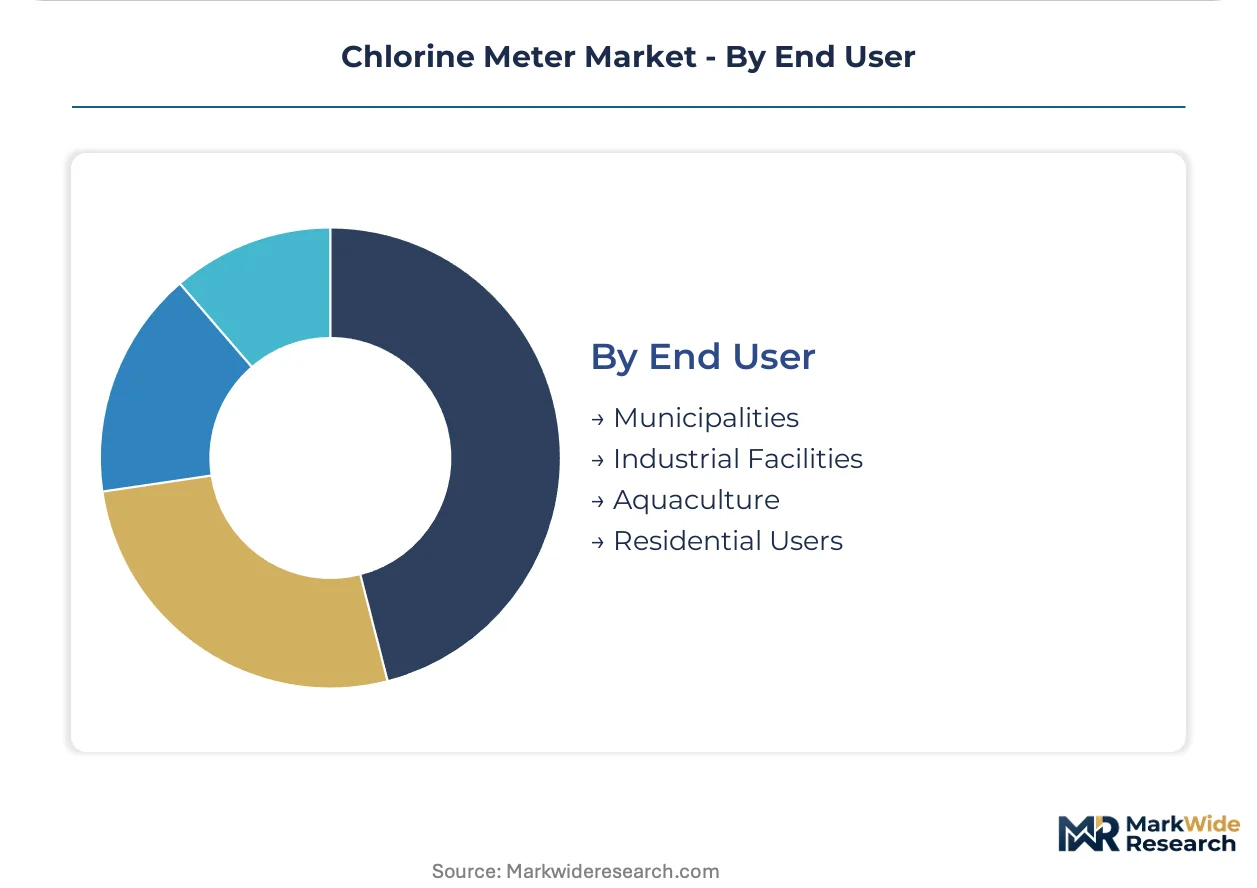
End User:
Customer type determines procurement sophistication, with centralized asset management departments unbundling hardware from service contracts.
- Municipalities:Consolidated SCADA architectures and unified procurement programs favor vendors with integrated liquid analysis platforms over standalone meter suppliers. California and Texas utilities with centralized asset management departments are separating hardware acquisition from calibration service contracts, opening specialist maintenance providers.
- Industrial Facilities:ISO 9001-aligned quality systems and FDA-regulated process water requirements shape certification-driven procurement specifications. Food and pharmaceutical plants face the strongest alternative oxidation substitution pressure as peracetic acid and UV systems displace chlorine-based disinfection.
- Aquaculture:Intensive farming operations require continuous dissolved gas monitoring including residual oxidants, with sensor fouling from organic loads driving demand for specialized membrane materials.
- Residential Users:Pool and spa owners represent a dispersed, price-sensitive segment served through retail and e-commerce channels with minimal technical support requirements.
Municipalities anchor the volume base while industrial facilities gain share at the steepest rate as FDA food safety mandates extend residual monitoring into new processing categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities command pricing premiums for integrated chlorine analysis platforms while Indian municipalities negotiate aggressively on portable electrochemical units. This asymmetry reflects divergent regulatory maturity and procurement sophistication across national water infrastructure programs.
United States
EPA Safe Drinking Water Act enforcement drives continuous residual monitoring mandates across distribution network extremities. California and Texas utilities with centralized asset management departments unbundle hardware procurement from calibration service contracts. Secondary cities in the Southwest deploy pooled purchasing cooperatives to access premium integrated systems.
Germany
EU Drinking Water Directive parametric revisions on disinfection byproducts accelerate replacement of colorimetric benchtop systems with automated electrochemical stations. Municipal procurement specifications now mandate continuous online verification at network extremities. The Ruhr industrial cluster hosts concentrated vendor service infrastructure supporting utility network modernization.
India
Smart Cities Mission infrastructure investments open tender opportunities for online residual monitoring in secondary cities lacking laboratory capacity. State-level urban development authorities specify cloud-connected meters with automated calibration alerts. Maharashtra and Gujarat municipal corporations lead deployment of point-of-use verification systems across rapidly expanding distribution networks.
China
GB standards for drinking water quality tighten residual chlorine monitoring frequencies in municipal treatment plants. Yangtze River Delta utilities consolidate SCADA architectures under unified procurement programs. Shanghai and Jiangsu province water bureaus favor integrated liquid analysis platforms over standalone meter suppliers for new treatment capacity.
Japan
METI industrial water quality guidelines extend residual monitoring requirements into food and beverage processing facilities. Osaka and Nagoya metropolitan utilities deploy membraned amperometric sensors with detection stability below 0.01 mg/L. Kansai region manufacturers specialize in ion-selective membrane production for regional and export markets.
Chlorine Meter Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the chlorine meter market structure. Integrated platform vendors dominate process-critical municipal installations while portable specialists capture residential and light commercial segments. Three archetypes define competitive positioning: analytical instrumentation heritage firms, integrated liquid analysis platform providers, and channel-optimized portable meter suppliers. M&A activity concentrates among water quality platform consolidators, while technology licensing agreements proliferate between sensor material specialists and meter assemblers.
Among analytical instrumentation heritage firms, Thermo Fisher Scientific anchors premium laboratory meter positions in North American utilities. Hanna Instruments exemplifies channel-controlled competition through aggressive positioning in residential and light commercial pool segments. Endress+Hauser Group occupies the integrated platform tier, dominating process-critical online installations with liquid analysis systems that unify multiple parameter monitoring under single procurement relationships.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Horiba Ltd. |
| Emerson Electric Co. |
| ABB Ltd. |
| Xylem Inc. |
| Endress+Hauser Group |
| Yokogawa Electric Corporation |
| Hanna Instruments |
| Hach |
| Others |
Supply Flow & Price Mechanics
EPA Safe Drinking Water Act certification gates both supplier qualification and price tiering in chlorine meter procurement, forcing vendors to absorb compliance costs into premium positioning while mid-tier competitors face margin compression from unbundled service contracts.
Pricing Analysis
German utilities pay 40-60% premiums for integrated chlorine analysis platforms versus Indian municipal tenders for portable electrochemical units. Three-tier pricing structure across premium, standard, and economy levels separates SCADA-integrated systems from standalone meters and handheld verification devices. Pricing pressure stems from precious metal electrode cost volatility in sensor manufacturing, squeezing mid-tier electrochemical producers. Residential pool segments exhibit highest price sensitivity, while process-critical municipal installations show inelastic demand for certified platforms.
Supply Chain Analysis
Specialized ion-selective membrane production concentrates in German and Japanese specialty chemical suppliers, creating single-source vulnerability for meter assemblers dependent on proprietary membrane formulations. Platinum and gold electrode materials draw from South African and Russian mining operations, exposing sensor manufacturers to commodity price swings. Distribution runs through authorized service networks for municipal utilities, while residential segments feed through retail and e-commerce channels with minimal technical support infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field calibration technician scarcity constrains expansion of distributed chlorine monitoring networks, creating durable competitive advantage for vendors with captive service capabilities or automated calibration technologies.
For Market Incumbents: Secure captive membrane supply agreements with German and Japanese specialty chemical producers to insulate margins from import dependency risks. Consolidate service infrastructure around predictive maintenance platforms with automated calibration alerts, countering unbundling trends in California and Texas municipal procurement. For New Entrants and Emerging Players: After-sales service fragmentation in large US water utilities opens specialist maintenance provider opportunities separate from hardware supply. Target food industry applications with hygienic design certifications, where FDA FSMA process water rules extend residual monitoring into previously exempt beverage and dairy operations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable electrochemical segments as solid-state optical sensors reduce field maintenance burdens and service contract dependencies. Sensor material specialists with proprietary membrane formulations present acquisition targets with durable moats. Watch peracetic acid and UV substitution rates in food processing and pharmaceutical water systems as demand trajectory inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Cloud-connected chlorine meters with predictive analytics create recurring service revenue beyond hardware sales. |
| Membrane Supply Agreement | Long-term contracts with German and Japanese specialty chemical producers reduce electrode cost volatility exposure. |
| Hygienic Design Certification | FDA FSMA compliance enables penetration of underexploited food processing segments beyond dairy and beverage. |
| Service Infrastructure Expansion | Field calibration technician networks defend against procurement unbundling in centralized asset management departments. |
| Optical Sensor Development | Solid-state architectures displace amperometric cells in portable applications, reducing lifetime ownership costs. |
Methodological Framework
A spread of perspectives from municipal utility procurement officers, field calibration technicians, liquid analysis platform engineers, and food processing plant managers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from EPA enforcement records, EU Drinking Water Directive implementation reports, FDA FSMA guidance documents, and municipal tender databases. Bottom-up unit economics triangulated against top-down regulatory mandate scaling across the analysis window.
Product type, sensing technology, application vertical, and end-user procurement sophistication shaped the segmentation dimensions modeled throughout the projection horizon. CAGRs derived from regulatory mandate trajectories, infrastructure investment pipelines, and substitution technology penetration curves. Membraned amperometric sensor advancement rates and SCADA integration adoption patterns provided chlorine meter-specific forecast inputs.
Forecasts assume regulatory continuity in EPA Safe Drinking Water Act enforcement and EU Drinking Water Directive parametric values; material policy shifts would require re-modeling residual monitoring mandate trajectories. Practitioners should keep alternative scenarios live as peracetic acid and UV substitution rates in food processing and pharmaceutical water systems evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Corrosion Testing Services Market
Testing Equipment
Global Chromatography Instrumentation Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Total Reflection X Ray Fluorescence (TXRF) Spectrometer Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Fugitive Emissions Detection and Quantification Test Systems Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Electrical Testing Equipment Market