
 Corrosion Testing Services Market | 2026-2036
Corrosion Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Corrosion Testing Services Market Outlook
Multi-source outsourcing of materials validation is recalibrating how capital-intensive industries manage asset integrity risk. SGS SA leverages its network of accredited laboratories across maritime and energy corridors to sustain geographic coverage advantages. Bureau Veritas anchors its competitive position through specialized pipeline assessment protocols aligned with North Sea and Gulf of Mexico regulatory requirements. Intertek Group differentiates via integrated inspection and testing workflows that compress project timelines for offshore platform operators.
Corrosion testing services encompass controlled exposure and electrochemical evaluation of metallic and coated substrates to quantify degradation rates, pitting susceptibility, and protective coating performance under simulated environmental stressors. Salt spray testing remains the most frequently requested protocol for qualifying protective coatings in automotive and marine supply chains, though electrochemical impedance spectroscopy is displacing it for real-time corrosion rate quantification in energy infrastructure. Pipeline assessment commands premium pricing due to regulatory-driven inspection intervals and the catastrophic cost of unplanned shutdowns, while microbial corrosion testing grows fastest as operators confront sour gas field complications and biogenic sulfide attack in waterflooding systems.
ASTM International, NACE International, and ISO standards collectively dictate laboratory accreditation requirements and test methodology acceptability across jurisdictional boundaries, with noncompliant reports risking rejection by insurance underwriters and regulatory inspectors. The US Environmental Protection Agency and Pipeline and Hazardous Materials Safety Administration enforce integrity management rules that mandate documented corrosion control programs for regulated pipelines, directly expanding third-party testing procurement. Stakeholders must monitor how hydrogen infrastructure material qualification protocols evolve, as emerging embrittlement testing standards will reshape service provider capability requirements and capital allocation priorities.
Market Dynamics
Electrochemical impedance spectroscopy is consolidating its position as the dominant protocol for real-time corrosion monitoring, displacing legacy salt spray methods across energy infrastructure and compressing project timelines for asset integrity programs.
Growth Catalysts
- PHMSA Integrity Management Rules:The Pipeline and Hazardous Materials Safety Administration mandates documented corrosion control programs for regulated pipelines, directly expanding third-party testing procurement across US transmission networks.
- Sour Gas Field Complications:Biogenic sulfide attack in waterflooding systems is accelerating demand for microbial corrosion testing protocols in mature petroleum provinces.
- Offshore Wind Expansion:Subsea cable and foundation corrosion assessment requirements are proliferating along the US Gulf Coast and North Sea development corridors.
Market Restraints
- Accreditation Capital Intensity:ISO 17025 laboratory certification and NACE International protocol compliance require substantial fixed investment in specialized electrochemical equipment.
- Skilled Technician Scarcity:Certified corrosion engineers capable of executing ASTM G106 and ASTM G61 protocols remain concentrated in established petrochemical clusters.
- Electrochemical Equipment Lead Times:Potentiostat and frequency response analyzer supply bottlenecks extend project initiation timelines for service providers.
Strategic Opportunities
- Hydrogen Infrastructure Qualification:Emerging embrittlement testing standards for high-pressure hydrogen storage and transport systems will reshape capability requirements and capital allocation priorities.
- Carbon Capture Pipeline Networks:CO2 transport infrastructure requires novel corrosion assessment protocols for impurity-induced cracking and degradation modes.
- Integrated Digital Reporting Platforms:Cloud-based data management systems are enabling remote witness testing and real-time client collaboration across distributed project sites.
Industry Challenges
- Multi-Standard Harmonization:Reconciling ASTM International, NACE International, and ISO methodology variations complicates report acceptance across jurisdictional boundaries.
- Electrochemical Technician Training Cycles:Developing proficiency in impedance spectroscopy interpretation requires 18-24 month apprenticeship periods that constrain workforce scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrosion Testing Services Market |
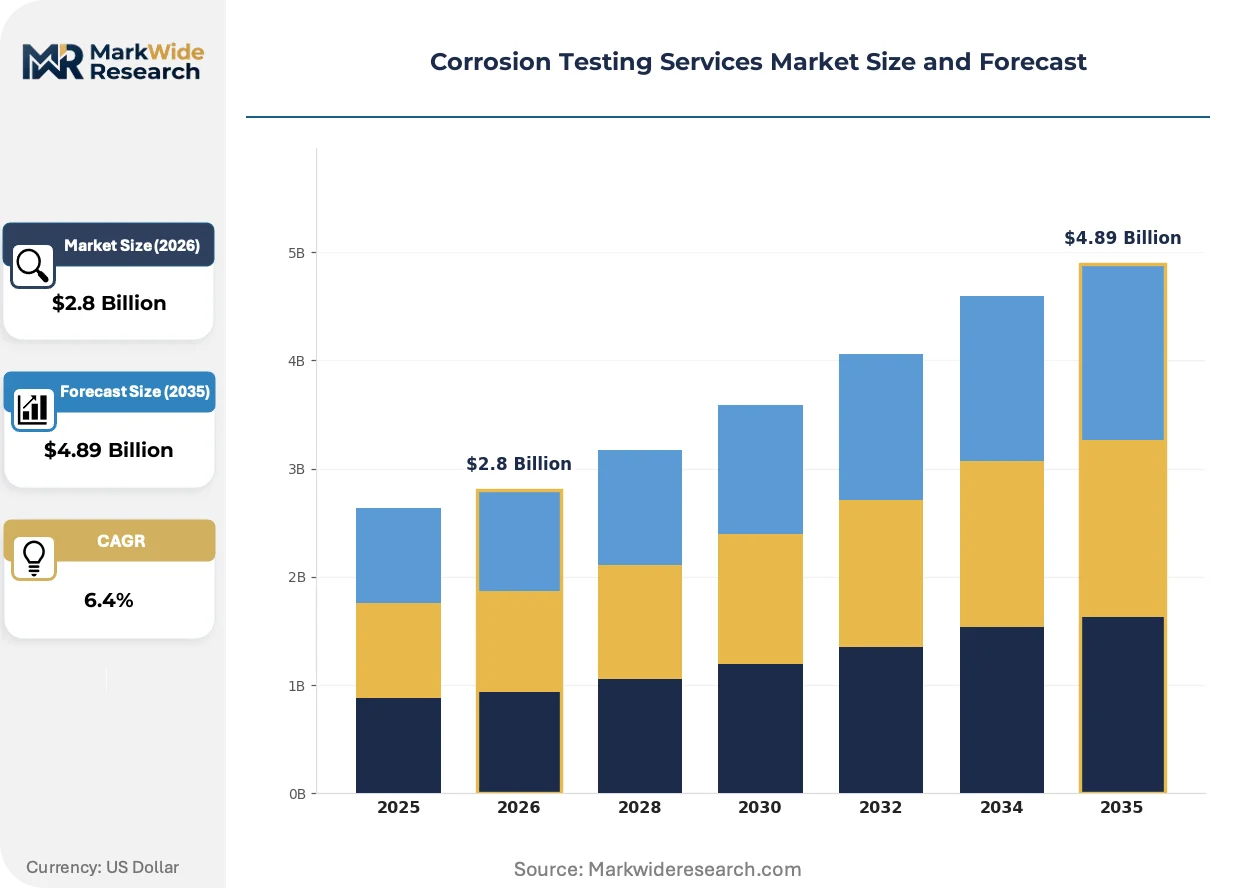
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Salt Spray Testing, Microbial Corrosion Testing, Electrochemical Testing, Pipeline Assessment Application: Aerospace, Oil & Gas, Marine, Automotive Material: Steel, Aluminum, Copper, Stainless Steel Industry: Construction, Manufacturing, Energy, Infrastructure |
| Companies Covered | Element Materials Technology, TÜV SÜD, SGS SA, Sigmatest, CorrTech, IMR Test Labs, Bureau Veritas, MISTRAS Group, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrosion Testing Services Market Strategic Shifts
Real-time monitoring technologies and predictive analytics are restructuring how corrosion data is generated, validated, and integrated into asset lifecycle management systems across capital-intensive industries.
Electrochemical impedance spectroscopy is consolidating its role as the preferred method for quantitative corrosion rate determination in energy infrastructure. Offshore platform operators and pipeline integrity managers are adopting multi-electrode array systems that enable spatially resolved degradation mapping. This consolidation is compressing the competitive position of traditional gravimetric and salt spray methods that require extended exposure durations.
ASTM International's accelerated revision cycle for G106 standard test methods is tightening electrochemical protocol requirements for laboratory accreditation. Industrial consequence includes mandatory requalification of existing test apparatus and personnel certification renewals. Pipeline assessment service providers in the United States are responding through strategic investment in automated potentiostat fleets and digital data acquisition systems.
Asset operators are unbundling inspection and testing workflows that were historically bundled within integrated maintenance contracts. Specialized corrosion testing laboratories are capturing discrete procurement slots previously held by generalist inspection firms. This pattern is most visible in the US Gulf Coast petrochemical corridor, where major operators now maintain separate vendor pools for electrochemical testing versus mechanical integrity assessment.
Corrosion Testing Services Market Segmentation
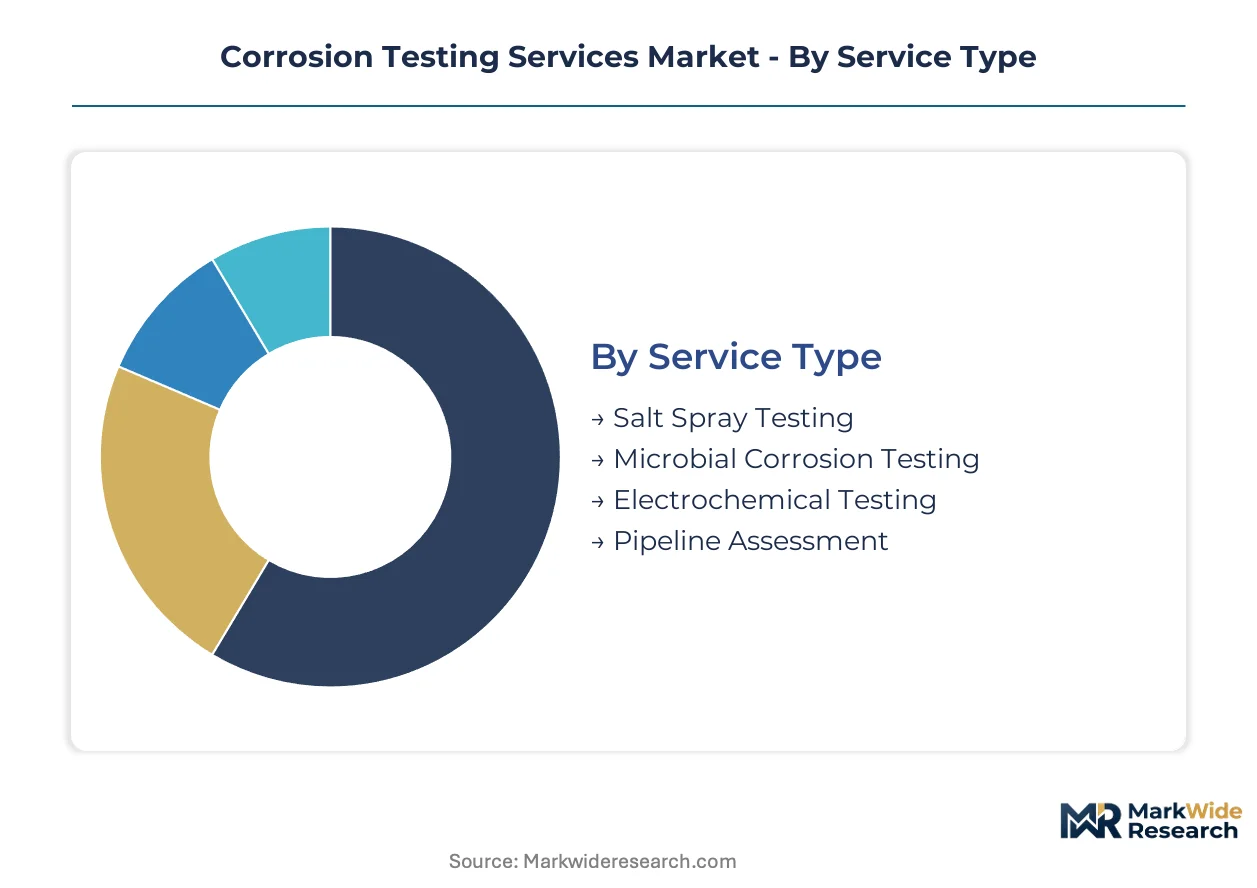
Service specialization in corrosion testing reflects divergent capital requirements across electrochemical equipment, biological containment systems, and field-deployable inspection assets. Procurement patterns vary sharply by whether clients prioritize rapid coating qualification, sour gas microbiological surveillance, or integrated pipeline integrity programs.
Service Type:
Capital intensity escalates from atmospheric exposure chambers through electrochemical workstations to fully equipped pipeline inspection spreads requiring mobilization logistics.
- Salt Spray Testing:Accelerated atmospheric corrosion simulation using standardized saline fog exposure in environmental chambers. Automotive OEMs in Michigan and marine coating suppliers in Hamburg sustain dense demand clusters for rapid qualification cycles.
- Microbial Corrosion Testing:Anaerobic cultivation and sulfide-producing bacteria enumeration to assess biogenic attack susceptibility in waterflooding systems. North Sea and Permian Basin operators are expanding procurement as sour gas production intensifies.
- Electrochemical Testing:Potentiodynamic polarization and impedance spectroscopy for quantitative degradation rate determination.
- Pipeline Assessment:Inline inspection validation and direct assessment protocols for regulated transmission systems.
Pipeline assessment absorbs the bulk of installed capacity; microbial corrosion testing is expanding most quickly.
Application:
End-use concentration determines pricing power, with offshore energy commanding premium rates and automotive emphasizing throughput volume.
- Oil & Gas:Subsea infrastructure, refinery equipment, and transmission pipeline integrity programs requiring NACE-compliant documentation. Gulf Coast petrochemical clusters and North Sea production platforms anchor procurement concentration.
- Marine:Ballast tank coating validation and hull cathodic protection assessment for commercial shipping and offshore wind installations.
- Aerospace:Airframe alloy qualification and protective coating performance under cyclic humidity exposure.
- Automotive:Chassis component and exhaust system corrosion resistance verification for OEM supply chain admission.
Oil and gas commands the dominant revenue share; marine applications are climbing the fastest on offshore wind foundation assessment demand.
Material:
Substrate chemistry dictates electrochemical protocol selection and electrode configuration complexity.
- Steel:Carbon and alloy grade assessment for infrastructure and energy applications representing the foundational test volume.
- Stainless Steel:Pitting and crevice corrosion susceptibility evaluation using ASTM G61 cyclic polarization methods.
- Aluminum:Galvanic couple and exfoliation corrosion testing for aerospace and automotive lightweighting programs.
- Copper:Dezincification and stress corrosion cracking protocols for plumbing and electrical conductivity applications.
Steel substrates dominate routine test volumes; stainless steel evaluation carries the steepest pricing premium due to specialized apparatus requirements.
Industry:
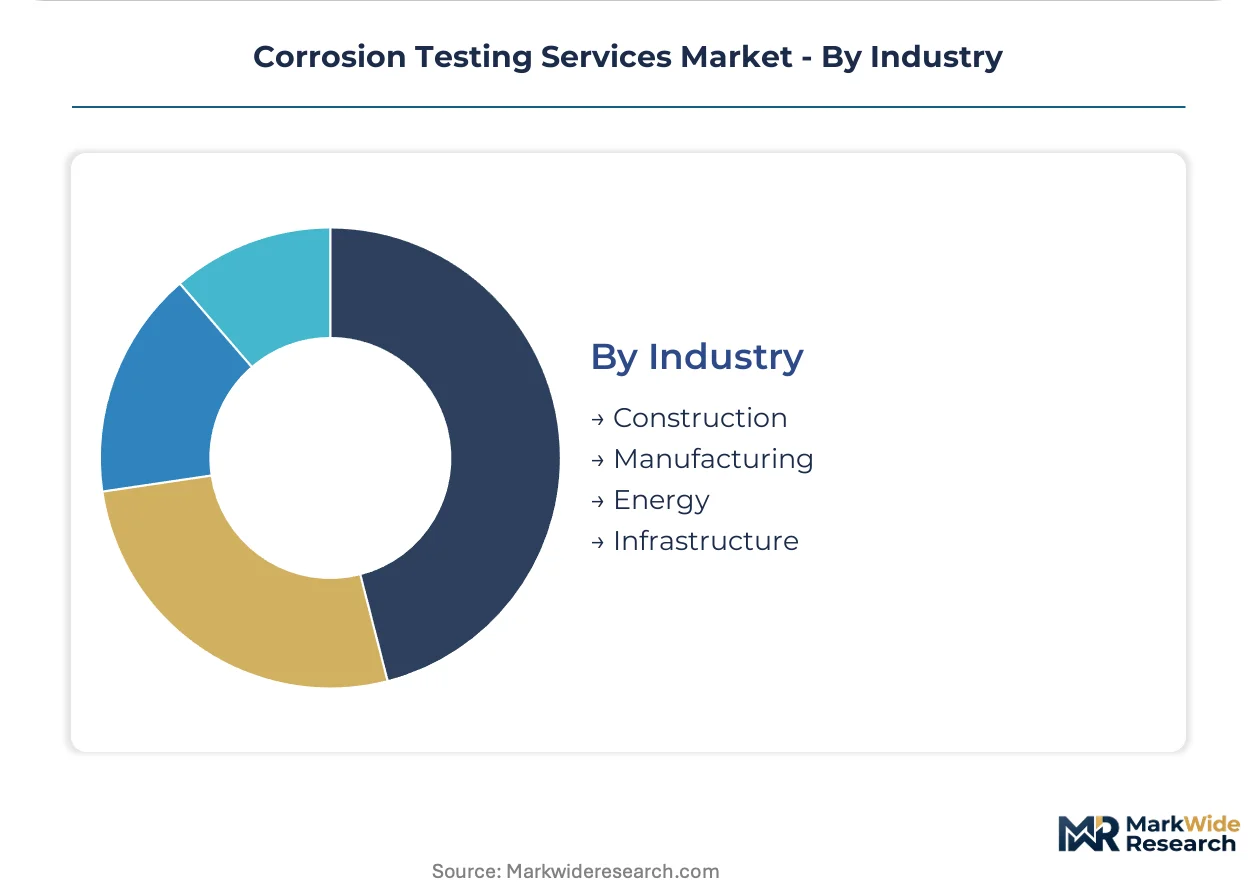
Regulatory inspection mandates and asset criticality stratify procurement sophistication across verticals.
- Energy:Power generation and oil and gas production facilities with PHMSA-driven integrity management obligations.
- Infrastructure:Bridge cable, tunnel lining, and water treatment asset corrosion monitoring for public authorities.
- Manufacturing:Industrial equipment and process vessel qualification for chemical and pharmaceutical production.
- Construction:Reinforcing bar and structural steel pre-qualification for commercial building projects.
Energy sector procurement absorbs the majority of specialized electrochemical capacity; infrastructure spending is gaining share fastest on transportation asset rehabilitation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum reserves and offshore wind development anchor corrosion testing demand across concentrated industrial corridors. Gulf Coast petrochemical clusters, North Sea production platforms, and East Asian shipbuilding centers generate disproportionate service procurement. Regulatory divergence across jurisdictions shapes where accredited laboratories concentrate capacity.
United States
PHMSA integrity management rules mandate documented corrosion control programs for regulated transmission pipelines. The Environmental Protection Agency enforces spill prevention requirements that expand third-party testing procurement. Houston and Corpus Christi petrochemical clusters sustain dense laboratory networks serving offshore platform operators.
Germany
REACH compliance obligations and industrial equipment certification drive materials validation demand for chemical process industries. The Federal Motor Transport Authority enforces stringent coating performance standards for automotive supply chains. Ruhr industrial corridor and Bavarian chemical parks concentrate accredited testing capacity.
United Kingdom
North Sea decommissioning timelines and offshore wind foundation installations accelerate subsea corrosion assessment procurement. The Health and Safety Executive mandates integrity management for aging oil and gas infrastructure. Aberdeen and Great Yarmouth marine service clusters specialize in cathodic protection validation.
China
Dual carbon goals and petrochemical capacity expansion drive pipeline integrity investment across state-owned energy enterprises. The Ministry of Ecology and Environment enforces emissions-linked equipment inspection regimes. Yangtze River Delta shipyards and Shandong refining complexes generate concentrated demand for coating qualification protocols.
Saudi Arabia
Sour gas field development and seawater injection systems intensify microbial corrosion surveillance requirements. The national oil company mandates NACE-compliant documentation for all critical production infrastructure. Eastern Province industrial cities anchor specialized laboratory capacity serving upstream operators.
Corrosion Testing Services Market Competitive Environment
Global majors compete with regional champions across accreditation standards and geographic coverage. The market structures around three tiers: diversified inspection conglomerates with laboratory networks, specialized corrosion engineering boutiques, and commodity coating qualification shops. Consolidation pressure favors players with integrated electrochemical capabilities and multi-jurisdictional accreditation portfolios. Dominant competitive moves include strategic laboratory acquisitions in energy corridors and technology licensing partnerships for hydrogen embrittlement protocols.
Among diversified testing conglomerates, SGS SA, Bureau Veritas, and Intertek Group exemplify the scale-driven archetype that dominates pipeline assessment and offshore platform contracts. These entities occupy positions defined by geographic footprint breadth and regulatory relationship depth rather than technical specialization alone. Regional specialists including Element Materials Technology and TÜV SÜD sit within technical accreditation tiers where NACE protocol mastery and ASTM compliance infrastructure create defensive moats against generalist competitors.
| Leading Market Players |
|---|
| Element Materials Technology |
| TÜV SÜD |
| SGS SA |
| Sigmatest |
| CorrTech |
| IMR Test Labs |
| Bureau Veritas |
| MISTRAS Group |
| Intertek Group |
| Others |
Value Chain & Pricing Dynamics
Certified corrosion engineers concentrated in Houston and Aberdeen drive labor-cost differentials that widen pricing-tier spreads between NACE-accredited specialists and commodity coating qualification shops.
Pricing Analysis
Warranty bundling separates premium pipeline assessment contracts from unbundled salt spray testing engagements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and geographic delivery cost. Price differentiation hinges on ASTM G106 protocol compliance and PHMSA documentation requirements. Cost compression in economy-tier coating qualification is intensifying because automotive OEMs are consolidating vendor pools. Midstream pipeline operators show the least price sensitivity due to regulatory-driven inspection mandates and catastrophic failure costs.
Supply Chain Analysis
Direct-to-energy-operator channels handle hyperscale integrity management demand from Gulf Coast petrochemical clusters and North Sea production platforms. Supply concentrates in the United States, Germany, and the United Kingdom where accredited laboratory networks cluster around regulatory enforcement corridors. Raw material dependencies include specialized potentiostats, frequency response analyzers, and reference electrode assemblies. Single-source vulnerability in electrochemical equipment manufacturing extends project initiation timelines for service providers. Distribution runs through integrated inspection contracts and discrete laboratory procurement slots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
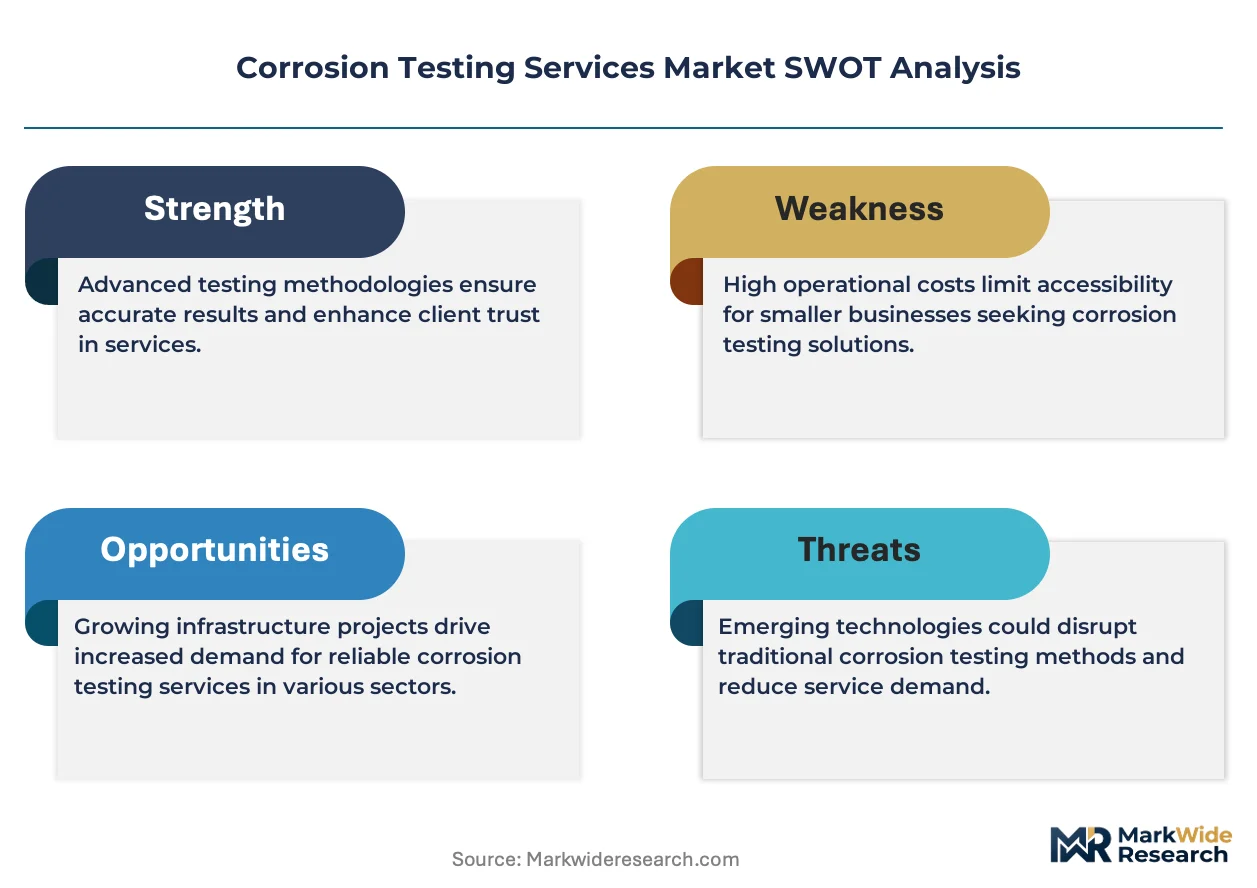
This market represents a consolidation play as ISO 17025 accreditation capital requirements force sub-scale coating shops toward exit or acquisition.
For Market Incumbents: Deploy automated potentiostat fleet expansion to compress project timelines and defend against specialized corrosion engineering boutiques capturing unbundled testing procurement. Anchor geographic coverage through laboratory acquisitions in maritime and energy corridors. Counter hydrogen embrittlement protocol competition through NACE International certification investment ahead of emerging standards. For New Entrants and Emerging Players: The premium-to-economy price-point gap in microbial corrosion testing offers entry traction. Target sour gas field operators in the Permian Basin and North Sea confronting biogenic sulfide attack complications. Pursue white-label partnerships with established pipeline inspection firms lacking in-house electrochemical capability. For Investors and Strategic Acquirers: Re-rating potential sits with NACE-accredited regional specialists given hydrogen infrastructure qualification protocol evolution. Five-to-ten year viability favors laboratories with multi-jurisdictional accreditation portfolios and digital reporting platform integration. Watch PHMSA enforcement intensity as inflection indicator for third-party testing procurement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Portfolio Expansion | ISO 17025 and NACE International compliance opens PHMSA-mandated pipeline contracts. |
| Hydrogen Embrittlement Capability Buildout | Anticipatory investment in high-pressure hydrogen testing secures emerging transport infrastructure qualification. |
| Digital Reporting Platform Integration | Cloud-based data management enables remote witness testing across distributed offshore project sites. |
| Specialized Laboratory Acquisition | Geographic coverage gaps in Gulf Coast and North Sea corridors close through targeted facility purchases. |
| Microbial Corrosion Protocol Development | Anaerobic cultivation expertise captures sour gas field surveillance demand from waterflooding operators. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with corrosion engineering directors, pipeline integrity managers, laboratory accreditation officers, and petrochemical procurement leads combined with ASTM International standard documentation, NACE International protocol filings, EPA enforcement records, and PHMSA incident reports. Bottom-up service provider capacity modeling and top-down energy infrastructure spending analysis enabled triangulation.
Segment-level modeling addressed service type, application, material substrate, and end-use industry across the analysis window. Electrochemical testing adoption curves, pipeline mileage under integrity management, and offshore wind foundation installation rates informed volume projections. CAGRs were derived from regression analysis against capital expenditure patterns in oil and gas and renewable energy infrastructure.
Inputs from laboratory accreditation databases and energy operator procurement disclosures were available through the study window; gaps in hydrogen infrastructure material qualification protocol development introduce uncertainty bands around emerging service category forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Fugitive Emissions Detection and Quantification Test Systems Market
Testing Equipment
China Material Testing Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Cyclic Corrosion Test Chamber Market
Testing Equipment
Rheology Controller Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Benchtop Density Meter for Solids Market