
 Micro Carbon Residue Tester Market | 2026-2036
Micro Carbon Residue Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Carbon Residue Tester Market Foresight
Petroleum chemist expertise is rotating toward automated thermal analysis systems as refineries phase out manual Conradson carbon residue methods. PAC leverages its instrumentation heritage to sustain dominance in North American laboratory markets. Koehler Instrument Company anchors its position through deep specialization in ASTM-compliant petroleum testing equipment. Anton Paar competes by extending its rheology and density portfolio into carbon residue measurement workflows.
A micro carbon residue tester quantifies the carbonaceous deposit remaining after pyrolysis of petroleum products under controlled thermal conditions, typically operating at 500°C with nitrogen purge to prevent oxidation. The instrument serves refineries and fuel blenders who require precise prediction of coke formation in engines and burners. Desktop configurations occupy the largest installed base due to permanent laboratory deployment, while portable units are gaining traction for field-based quality control at remote terminals. Gravimetric technology leads in regulatory compliance applications, though thermal analysis methods are displacing legacy approaches in high-throughput environments. Oil refineries represent the most concentrated end-user segment, with quality control departments driving replacement cycles as ISO 10370 precision tolerances tighten.
ASTM International and ISO shape product design through D4530 and 10370 standards that define allowable repeatability and reproducibility limits. The EPA's fuel quality enforcement indirectly expands tester deployment by mandating accurate characterization of residual fuel oils. Laboratories and equipment vendors must monitor evolving ASTM precision requirements and decide whether to retrofit existing gravimetric systems or migrate toward integrated thermal analysis platforms.
Market Dynamics
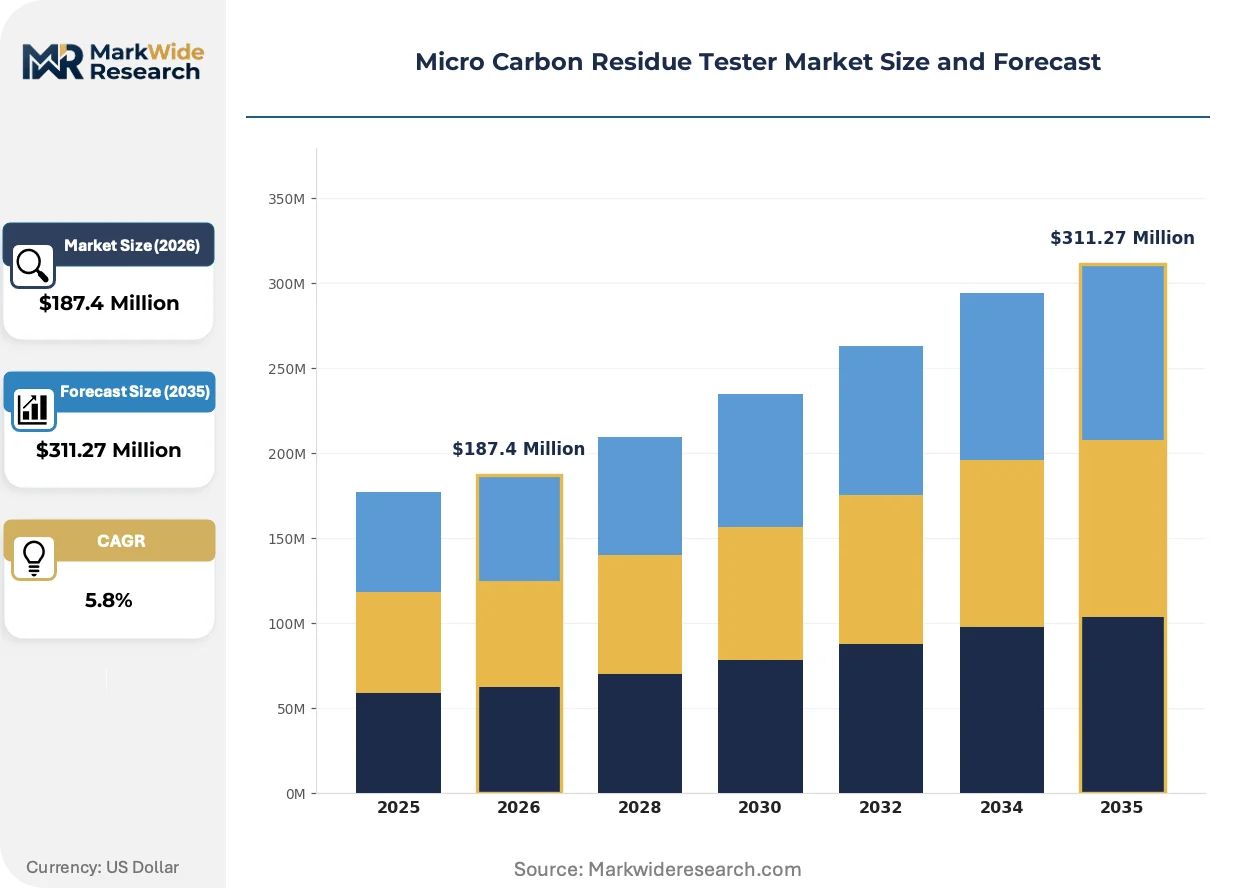
ASTM D4530 and ISO 10370 precision mandates are compressing legacy gravimetric workflows, forcing petroleum laboratories toward integrated thermal analysis platforms that automate pyrolysis measurement and reduce operator-dependent variability.
Growth Catalysts
- EPA fuel quality enforcement:Residual fuel oil characterization requirements expand tester deployment at US refineries and marine fuel terminals.
- Texas-Louisiana downstream clustering:Concentrated refining capacity in these states generates concentrated demand for automated carbon residue testing infrastructure.
- Pyrolysis automation:Thermal analysis platforms with nitrogen purge systems at 500°C replace manual Conradson methods, accelerating laboratory throughput.
Market Restraints
- Gravimetric system stranded assets:Laboratories face write-down pressure on legacy equipment as precision tolerances tighten under ASTM D4530.
- Specialized petroleum chemist scarcity:Expertise in manual carbon residue methods is retiring faster than thermal analysis training programs replenish talent pipelines.
- Capital intensity of platform migration:Integrated thermal analysis systems require substantial upfront investment compared to incremental gravimetric upgrades.
Strategic Opportunities
- Portable unit field deployment:Remote terminal quality control in Louisiana and Texas offshore logistics hubs creates demand for mobile pyrolysis testing.
- Dual-use thermal analysis convergence:Laboratories can consolidate carbon residue, rheology, and density workflows on single Anton Paar platforms.
- ISO 10370 precision tier differentiation:Equipment vendors can segment offerings between compliance-grade and research-grade thermal analysis specifications.
Industry Challenges
- ASTM precision timeline compression:Laboratories must complete gravimetric-to-thermal transitions before reproducibility windows narrow.
- Legacy data integration friction:Thermal analysis platforms require workflow reconfiguration to maintain historical carbon residue databases for regulatory audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Carbon Residue Tester Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop, Portable, Online, Off-line End User: Laboratories, Oil Refineries, Research Institutions, Quality Control Technology: Thermal Analysis, Spectroscopy, Chromatography, Gravimetric Application: Petroleum Industry, Chemical Manufacturing, Environmental Testing, Academic Research |
| Companies Covered | PAC, Koehler Instrument Company, Cannon Instrument Company, Tanaka Scientific, Stanhope-Seta, Anton Paar, Parkes Scientific, John Morris Scientific, Hoskin Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Carbon Residue Tester Market Shifts & Advancements
Petroleum testing instrumentation is pivoting from standalone residue measurement toward integrated thermal analysis ecosystems that consolidate multiple ASTM methods on unified hardware platforms.
Automated micro carbon residue testers is bifurcating the installed base between high-throughput refinery laboratories and smaller blenders. Major Gulf Coast refiners are adopting fully automated pyrolysis systems with robotic sample handling, while independent fuel terminals retain semi-automated configurations. This technology split is compressing margins for vendors who lack tiered automation portfolios.
ASTM International is tightening D4530 repeatability specifications, forcing equipment recalibration cycles to shorten from annual to quarterly intervals. This regulatory pressure is expanding the aftermarket service revenue pool for instrument vendors. Quality control departments in Texas refineries are responding by embedding predictive maintenance sensors directly into thermal analysis chambers.
Buyer procurement patterns are consolidating vendor relationships around full petroleum testing suites rather than point-solution carbon residue contracts. Refinery laboratories in Louisiana are bundling pyrolysis, distillation, and viscosity instrumentation into multi-year framework agreements. This consolidation is marginalizing specialized carbon residue vendors who lack adjacent testing capabilities.
Micro Carbon Residue Tester Market Segmentation
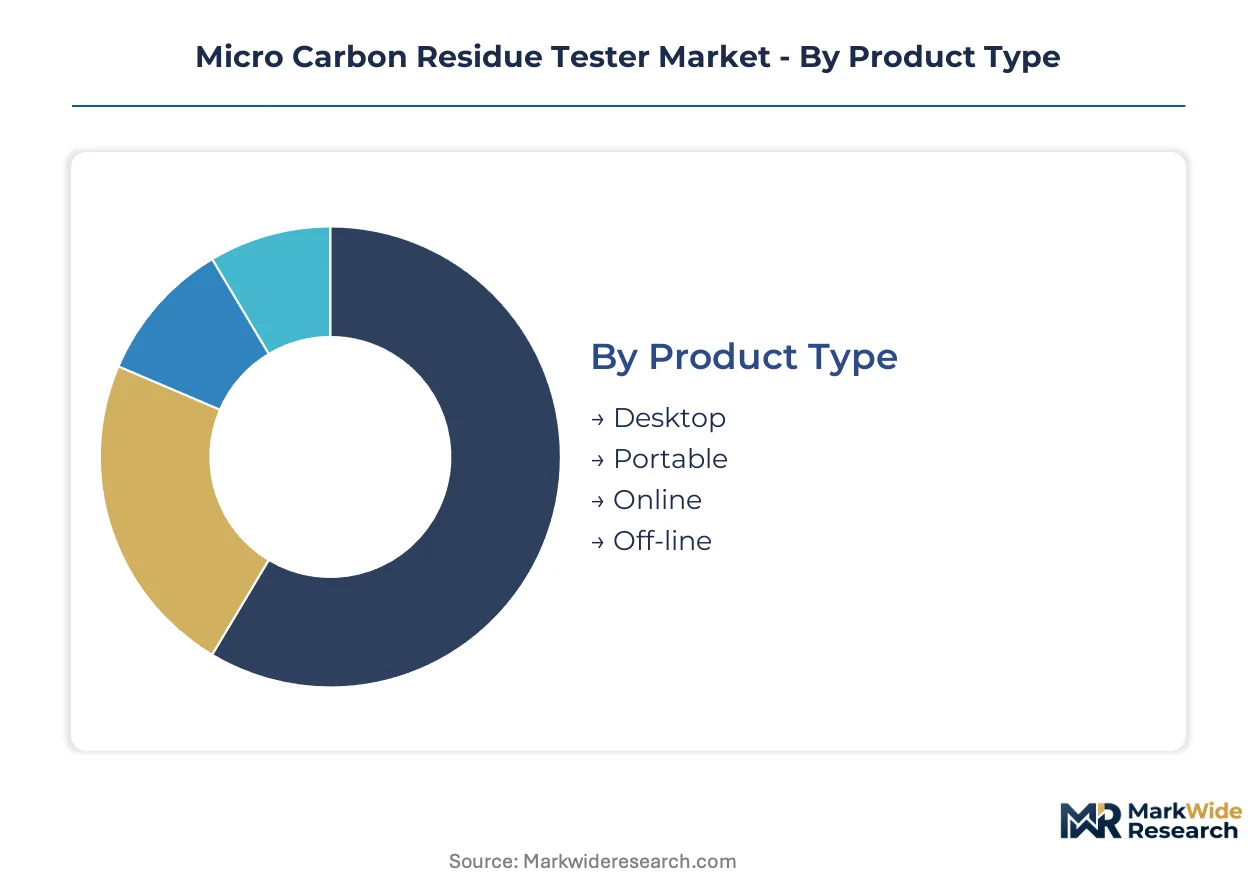
Micro carbon residue tester procurement patterns diverge sharply between permanent laboratory installations and field-deployable units. Equipment specifications must align with ASTM D4530 precision tiers and ISO 10370 repeatability windows that vary by end-use intensity.
Product Type:
Domestic demand concentrates in Texas and Louisiana refineries for permanent laboratory configurations, while export markets drive portable and online system development for remote terminal deployment.
- Desktop:Permanent laboratory installations at Gulf Coast refineries incorporate automated sample handling and nitrogen purge systems operating at 500°C. Texas quality control departments favor these units for high-throughput carbon residue measurement under tightening ASTM precision mandates.
- Portable:Battery-powered thermal analysis units with simplified pyrolysis chambers serve Louisiana offshore logistics hubs and marine fuel terminals. Field operators at remote blending facilities require rapid coke formation prediction without permanent infrastructure.
- Online:Continuous monitoring configurations integrate directly into refinery process control systems for real-time residual fuel characterization.
- Off-line:Batch sampling instruments support periodic compliance testing at smaller independent laboratories with lower sample volumes.
Desktop configurations command the established base. The steepest expansion runs through portable units.
End User:
Cost tier stratification separates high-capital refinery laboratories from budget-constrained academic facilities.
- Laboratories:Third-party petroleum testing facilities in Houston and Baton Rouge operate multiple thermal analysis platforms to serve independent fuel blenders. These operations face recalibration cycle compression from annual to quarterly intervals under evolving ASTM D4530 specifications.
- Oil Refineries:Integrated downstream operators deploy fully automated pyrolysis systems with robotic sample handling. Major Gulf Coast facilities are embedding predictive maintenance sensors directly into thermal analysis chambers to minimize unplanned downtime.
- Research Institutions:University petroleum engineering departments utilize semi-automated configurations for method development and student training.
- Quality Control:Mid-size fuel terminal operators balance precision requirements against capital constraints with tiered automation portfolios.
Oil refineries absorb the highest equipment expenditure per installation. Quality Control departments drive replacement velocity as tolerance windows narrow.
Technology:
Application intensity determines whether facilities adopt integrated thermal analysis platforms or retain legacy gravimetric workflows.
- Thermal Analysis:Automated pyrolysis with precise temperature ramp control and inert atmosphere management displaces manual Conradson methods. Louisiana laboratories prioritize these platforms for simultaneous carbon residue, rheology, and density workflow consolidation.
- Gravimetric:Traditional weighing-based measurement retains regulatory acceptance but faces write-down pressure as reproducibility requirements tighten. Texas facilities with recent gravimetric investments must decide between retrofit and full platform migration.
- Spectroscopy:Optical emission methods offer rapid screening for preliminary fuel quality assessment.
- Chromatography:Separation-based techniques serve specialized research applications requiring detailed hydrocarbon speciation.
Gravimetric technology holds the largest installed legacy base. Thermal analysis platforms are climbing the fastest among new procurements.
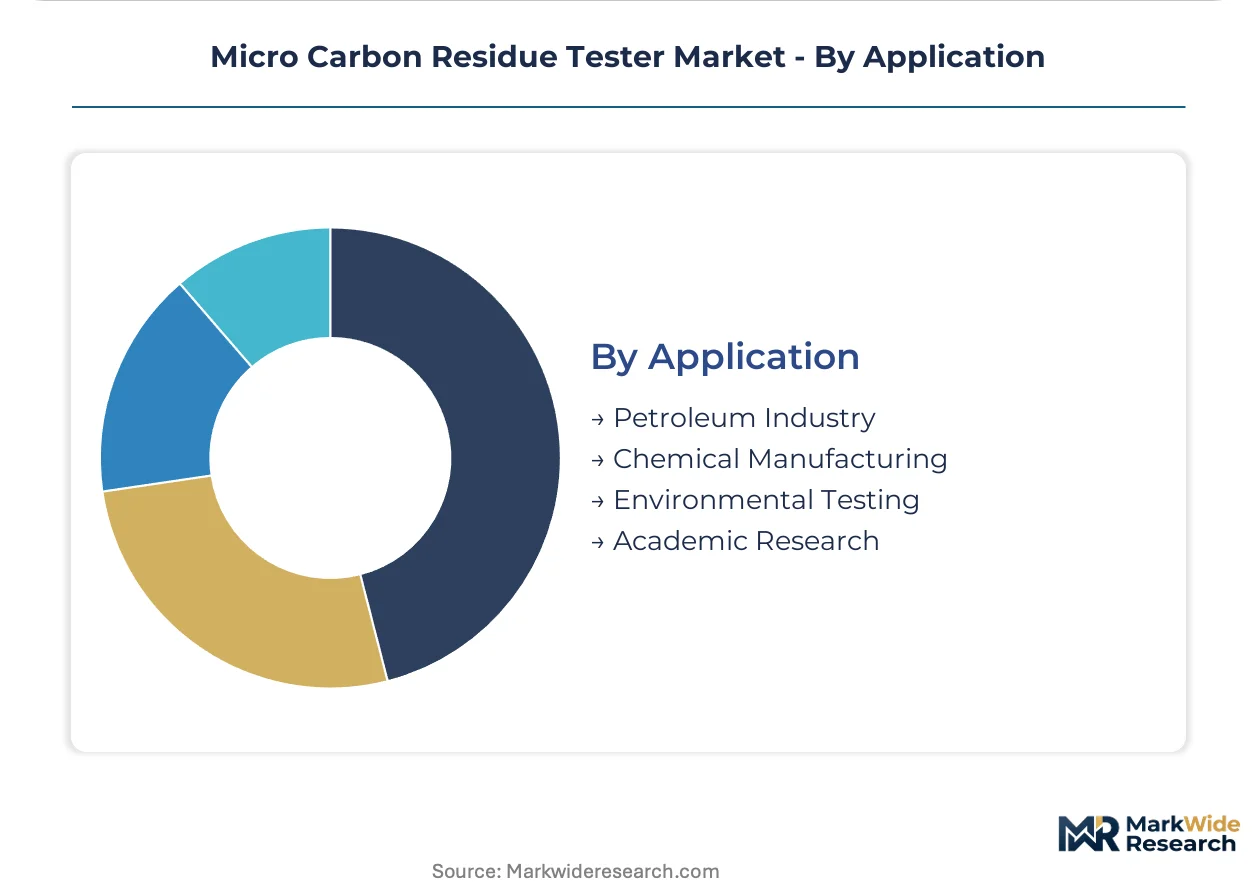
Application:
Customer maturity varies from standardized petroleum testing to emerging environmental compliance requirements.
- Petroleum Industry:Downstream operators and fuel blenders require precise coke formation prediction for engine and burner performance. EPA fuel quality enforcement expands tester deployment at US refineries and marine fuel terminals handling residual fuel oils.
- Chemical Manufacturing:Petrochemical producers utilize carbon residue data to optimize feedstock selection and coking unit operations.
- Environmental Testing:Regulatory laboratories analyze heavy fuel oil deposits for emissions compliance verification.
- Academic Research:University programs train petroleum chemists on automated thermal analysis systems as manual method expertise retires.
Petroleum Industry applications anchor current revenue. Environmental Testing represents the most rapid regulatory-driven expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Texas and Louisiana refineries while European laboratories absorb premium equipment costs under REACH compliance mandates. This asymmetry shapes procurement patterns across downstream oil testing infrastructure.
United States
EPA fuel quality enforcement drives tester deployment at Gulf Coast refineries and marine fuel terminals. ASTM D4530 precision mandates compress legacy gravimetric workflows toward automated thermal analysis platforms. Houston and Baton Rouge laboratories anchor concentrated demand for high-throughput pyrolysis systems with robotic sample handling.
Germany
REACH compliance requirements for residual fuel characterization expand laboratory testing infrastructure at petrochemical hubs. ECHA substance evaluation protocols tighten measurement traceability standards for carbon residue data. The Ruhr industrial cluster and Ludwigshafen chemical corridor prioritize integrated thermal analysis platforms consolidating multiple ASTM workflows.
China
GB standards alignment with ISO 10370 accelerates domestic equipment procurement at state-owned refinery laboratories. NMPA and MEE oversight of fuel quality enforcement expands third-party testing demand. Shandong Province and Yangtze River Delta refining complexes drive adoption of automated pyrolysis systems with nitrogen purge capabilities.
Japan
METI energy security policies prioritize precise fuel characterization for strategic petroleum reserve management. JIS standards harmonization with ASTM D4530 shapes equipment specification at domestic instrument manufacturers. Chubu and Kansai industrial regions concentrate thermal analysis platform deployment for coking unit optimization.
Saudi Arabia
SABIC and Aramco downstream integration creates demand for carbon residue testing at petrochemical export facilities. The country's national petroleum regulator mandates ISO 10370 compliance for residual fuel oil certification. Eastern Province refining complexes and Jubail industrial city anchor automated tester procurement for process control integration.
Micro Carbon Residue Tester Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics. European and North American instrumentation specialists dominate precision-grade thermal analysis platforms, while Asian manufacturers compete on automated gravimetric system cost structures. The market structure separates into three strategic archetypes: integrated petroleum testing suite vendors, specialized carbon residue equipment fabricators, and regional laboratory supply distributors. Dominant competitive moves include portfolio diversification into adjacent rheology and density workflows, plus strategic partnerships bundling pyrolysis instrumentation with predictive maintenance service contracts.
Among North American instrumentation specialists, PAC and Koehler Instrument Company occupy positions representing the integrated testing suite and specialized equipment archetypes respectively. Anton Paar exemplifies the European precision-instrument approach, anchoring thermal analysis convergence strategies that consolidate multiple measurement workflows on unified hardware platforms. These three companies illustrate how geographic origin and corporate structure shape competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| PAC |
| Koehler Instrument Company |
| Cannon Instrument Company |
| Tanaka Scientific |
| Stanhope-Seta |
| Anton Paar |
| Parkes Scientific |
| John Morris Scientific |
| Hoskin Scientific |
| Others |
Supply & Pricing Matrix
Multi-year framework agreements between Gulf Coast refineries and instrumentation vendors lock in supply access for automated thermal analysis platforms while providing price visibility across replacement cycles. These contracts bundle pyrolysis, distillation, and viscosity equipment into consolidated procurement structures that insulate buyers from spot-market volatility in precision instrumentation.
Pricing Analysis
Configured-to-order pricing for customized thermal analysis platforms commands a substantial premium over standard desktop configurations. The dominant pricing structure is project-based with tiered automation levels separating fully robotic systems from semi-automated units. Price differentiation stems from ASTM precision certification grade and after-sales service bundling. Cost compression in mid-tier equipment is intensifying because Asian manufacturers are entering automated gravimetric segments. Independent fuel terminals exhibit highest price sensitivity while integrated oil refineries prioritize precision compliance over capital outlay.
Supply Chain Analysis
Germany and the United States anchor precision thermal analysis platform manufacturing for petroleum testing instrumentation. Critical component inputs include nitrogen purge system valves, high-temperature ceramic crucibles, and precision temperature control modules. Supply chain risk centers on single-source vulnerability for specialized pyrolysis chamber assemblies sourced from European specialty ceramics producers. Distribution runs through authorized laboratory equipment distributors serving refinery clusters in Texas and Louisiana.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against portable spectroscopic screening methods that threaten to displace laboratory-based pyrolysis for preliminary fuel quality assessment.
For Market Incumbents: Fortify installed base retention through predictive maintenance service contracts that embed vendor sensors directly into thermal analysis chambers. Deepen backward integration into nitrogen purge system components to secure supply continuity. Defend against Anton Paar's workflow convergence strategy by accelerating API development for laboratory information management system integration. For New Entrants and Emerging Players: Lead with battery-powered portable units targeting Louisiana offshore logistics hubs where permanent laboratory infrastructure is absent. The most penetrable segment is independent marine fuel terminals requiring rapid coke formation prediction without capital-intensive platform installation. A field-service-first go-to-market angle bypasses entrenched distributor relationships dominating refinery procurement. For Investors and Strategic Acquirers: Specialized carbon residue equipment fabricators with deep ASTM compliance expertise represent the most attractive acquisition archetype. Long-term viability hinges on thermal analysis platform migration completion before precision tolerance windows narrow further. Watch for quarterly recalibration mandate announcements from ASTM International as the critical inflection signal for aftermarket service revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Sample Handling Integration | Accelerates laboratory throughput for Texas refinery quality control departments facing tightening precision mandates. |
| Predictive Maintenance Sensor Deployment | Captures recurring service revenue from EPA-driven tester expansion at marine fuel terminals. |
| Workflow Convergence Platform Development | Consolidates carbon residue, rheology, and density measurement on single Anton Paar thermal analysis hardware. |
| Portable Unit Battery Optimization | Enables field deployment at remote Louisiana blending facilities without permanent infrastructure investment. |
| ASTM Precision Tier Certification | Differentiates offerings between compliance-grade and research-grade specifications under evolving D4530 requirements. |
Research Methodology
The analysis maps thermal analysis platform configurations, gravimetric system retrofits, and portable unit specifications, each validated through petroleum chemists, refinery quality control managers, and laboratory equipment procurement officers. Primary interviews with ASTM committee members and thermal analysis chamber manufacturers combined with secondary validation from EPA fuel quality enforcement documentation, ISO 10370 precision standard archives, and SEC filings from publicly traded instrumentation vendors. Bottom-up equipment shipment data triangulated against top-down refinery capital expenditure surveys.
Consistency checks validated volume and value outputs against third-party petroleum testing service revenue disclosures and regional refinery capacity utilization benchmarks. The analytical framework models procurement across product type, automation tier, end-user intensity, and technology platform across the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles and forward-looking precision mandate implementation schedules. Industry-specific forecast inputs include ASTM recalibration cycle compression rates and Texas-Louisiana downstream clustering intensity.
Forecasts assume regulatory continuity in EPA fuel quality enforcement and ASTM D4530 precision timelines; material policy shifts would require re-modeling of laboratory equipment procurement trajectories. Specific risks that could revise projections include accelerated gravimetric phase-out mandates or supply disruption in European specialty ceramics for pyrolysis chambers. Recalibration cycles align with material shifts in ASTM precision specifications and EPA residual fuel oil characterization requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Global Residue Testing Market
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Particle Size Analysis Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Chromatography Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Cone Calorimeter Market