
 Material Testing Market | 2026-2036
Material Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Material Testing Market Intelligence
The divergence in capital investment between high-throughput automated testing and specialized analytical services is reorganizing the market structure. Element Materials Technology leverages its global network of accredited labs to serve multinational clients. Instron differentiates through its focus on designing and manufacturing universal testing machines and instrumentation. MTS Systems Corporation occupies a high-end niche, providing test systems and simulation software for automotive and aerospace.
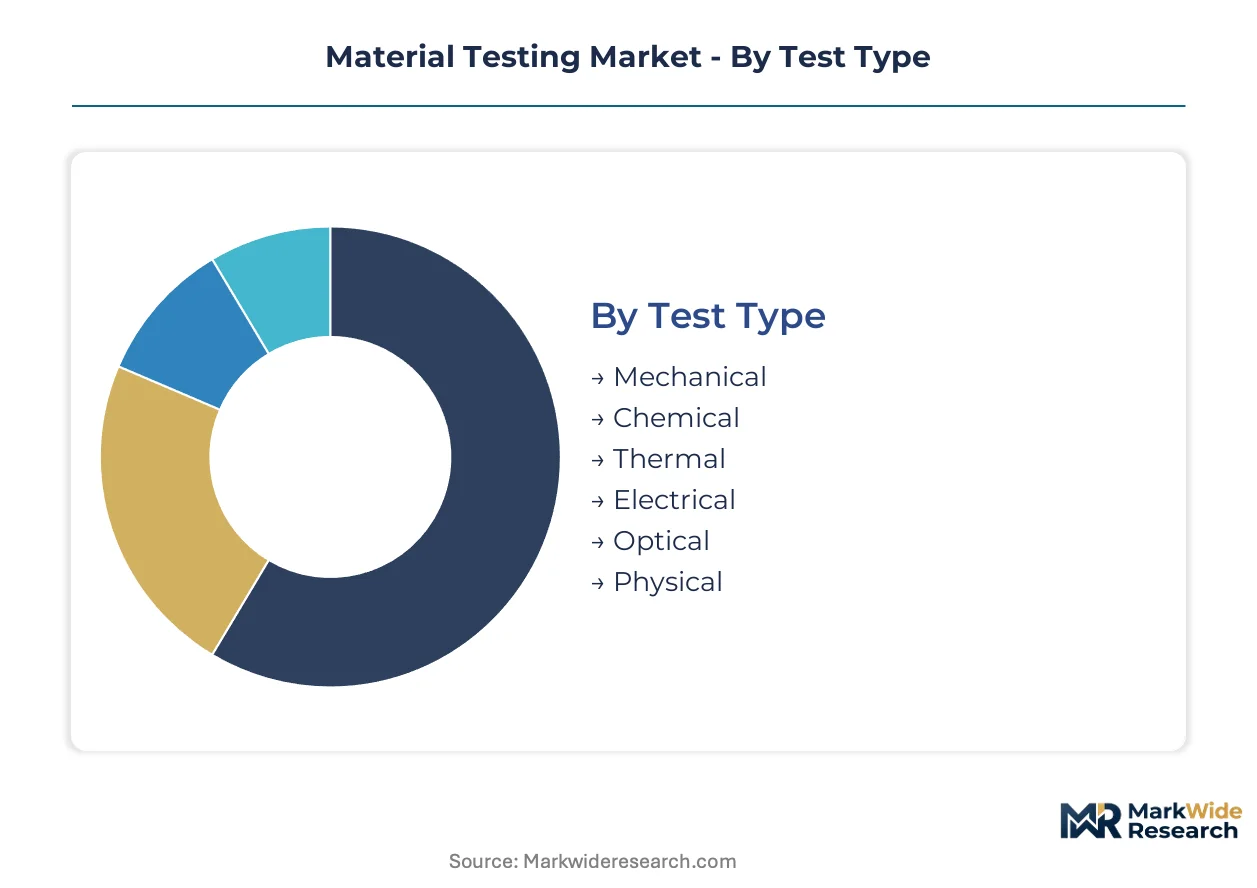
Material testing encompasses a suite of destructive and non-destructive techniques used to determine the physical and mechanical properties of a substance. These methods measure characteristics like tensile strength, hardness, and thermal conductivity to ensure materials meet design specifications and safety standards. Mechanical tests, performed on universal testing machines, remain the largest test type by volume. However, demand for advanced chemical and thermal analysis is growing fastest, driven by new material development in the polymers and aerospace components sectors.
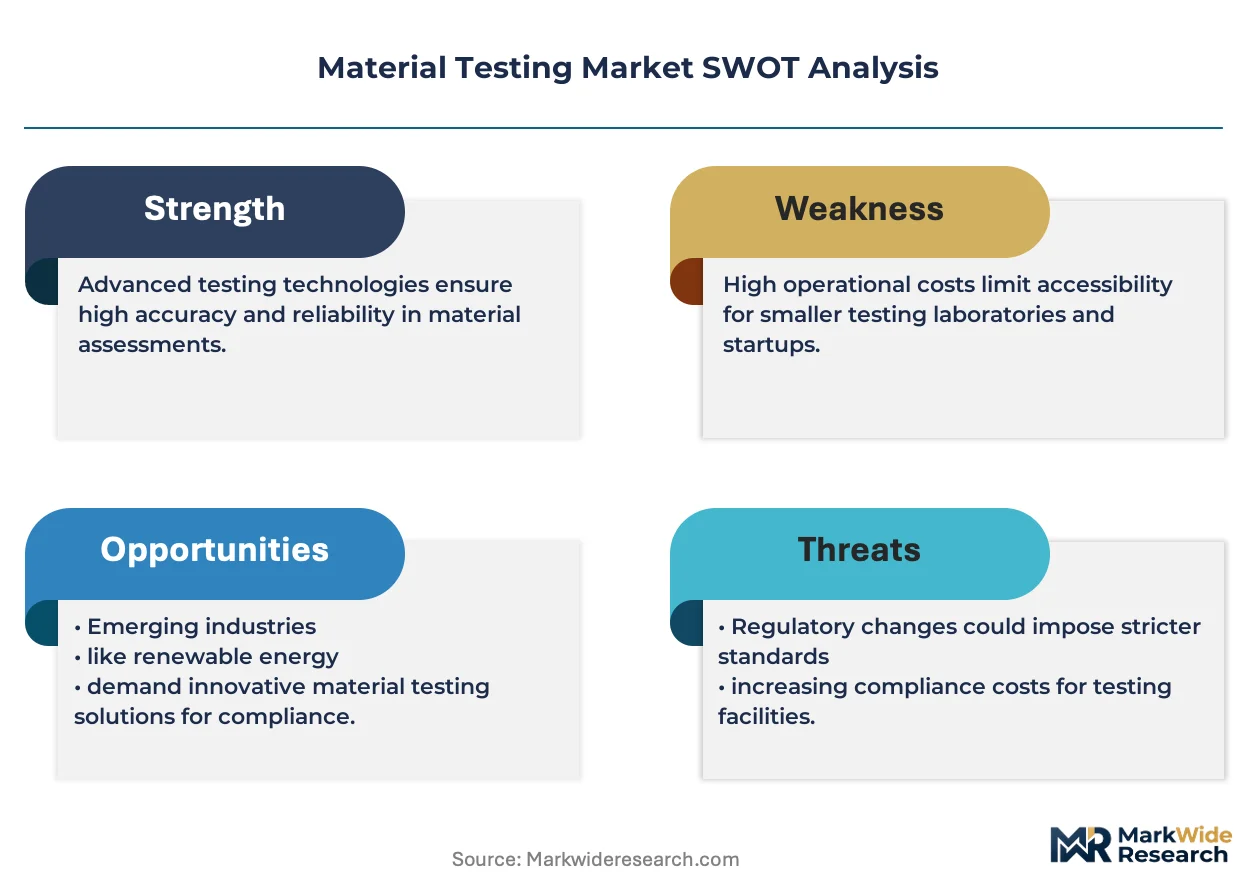
Regulations from bodies like the US FDA and the EU's ECHA under REACH mandate rigorous material testing for medical devices and chemical substances. Compliance with ISO standards, such as ISO/IEC 17025 for testing and calibration laboratories, is also critical for market access. The key decision for service providers is whether to invest in broad, high-volume capabilities or specialize in niche, high-margin analytical techniques.
Market Dynamics
The material testing market's structure is defined by the regulatory imperative for material traceability and performance validation. Mandates from bodies like the EU's ECHA and the US FDA, coupled with the complexity of advanced materials, are forcing a move beyond simple compliance checks toward predictive materials science.
Growth Catalysts
- Advanced Composites in Aerospace:The increasing use of carbon fiber and other lightweight composites in aircraft manufacturing requires extensive non-destructive and mechanical testing to validate structural integrity and fatigue life, driving service volume.
- Regulatory Scrutiny:The EU's REACH framework mandates rigorous testing for all chemical substances, creating a continuous demand pipeline for chemical analysis and toxicology services to ensure market access within Europe.
- Automotive Electrification:China's rapid shift to electric vehicles necessitates new testing protocols for battery materials, thermal management systems, and lightweight alloys used in vehicle body structures to enhance range and safety.
Market Restraints
- High Capital Investment:The significant cost of acquiring, calibrating, and maintaining universal testing machines, thermal analyzers, and spectrometry equipment creates a high barrier to entry for new service providers.
- Standardization Gaps:A lack of universally accepted testing standards for novel materials, such as those used in additive manufacturing, can lead to inconsistent results and disputes between suppliers and customers.
- Accreditation Complexity:The lengthy and resource-intensive process for laboratories to achieve and maintain ISO/IEC 17025 accreditation can delay the introduction of new testing services to the market.
Strategic Opportunities
- Additive Manufacturing Materials:A growing opportunity exists in providing specialized testing for 3D printing powders and finished components, focusing on density, porosity, and anisotropic mechanical properties.
- Digitalization and Simulation:Developing software and digital twin models that simulate material behavior can reduce reliance on physical destructive testing, offering a high-margin, value-added service for clients.
- Medical Device Materials:Expanding biocompatibility and extractables/leachables testing services for medical-grade polymers and metals addresses stringent regulatory requirements from the FDA and under the EU's MDR.
Industry Challenges
- Talent Scarcity:A shortage of qualified materials scientists and metrology technicians who can operate sophisticated analytical equipment and accurately interpret test data limits the capacity of testing laboratories.
- Data Integration:Integrating test results from multiple instruments and locations into a single, secure, and traceable digital record for compliance and analysis remains a significant operational hurdle for many labs.
- Pace of Standardization:The development of new ISO and ASTM standards often lags behind the rapid pace of innovation in materials science, creating uncertainty for testing new classes of polymers and composites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Material Testing Market |
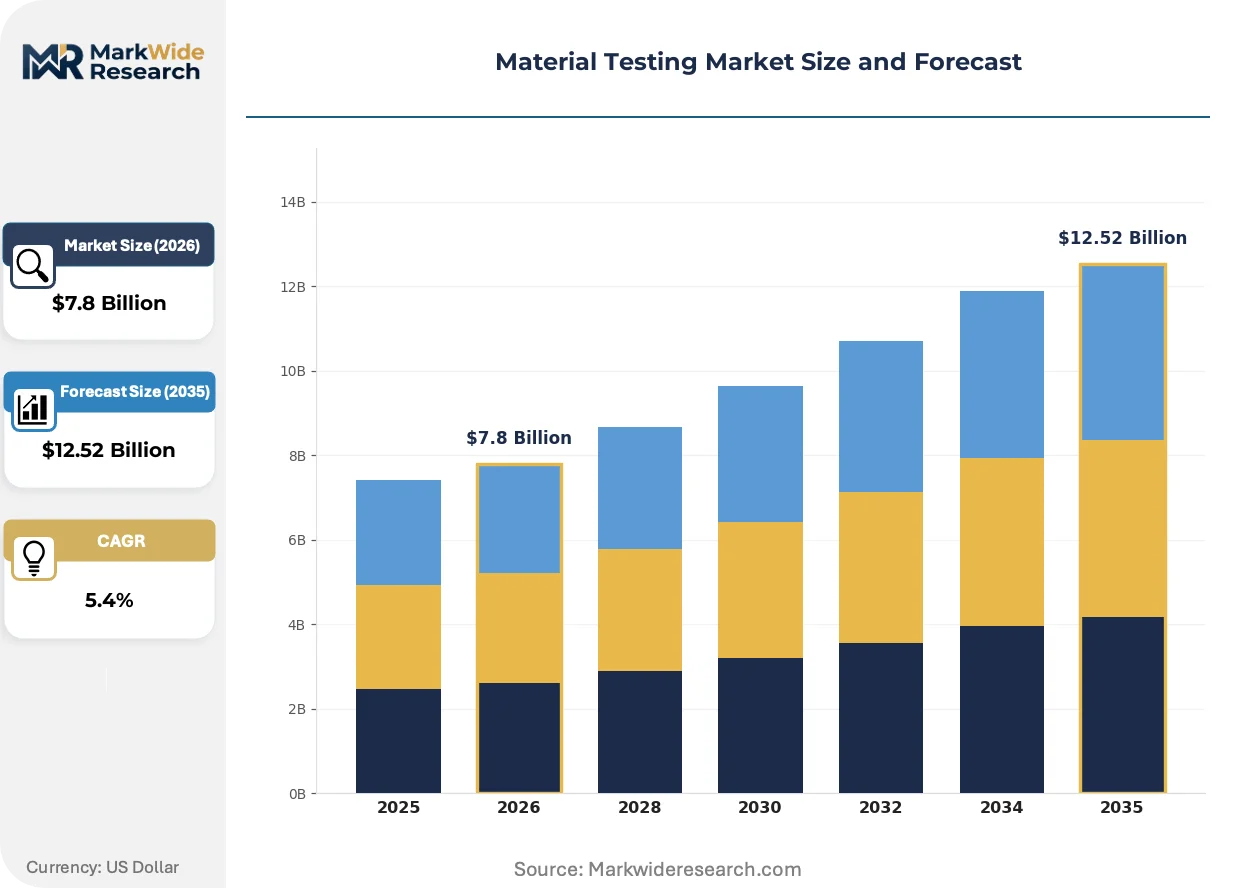
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Mechanical, Chemical, Thermal, Electrical, Optical, Physical Equipment Type: Universal Testing Machines, Spectrometers, Microscopes, Hardness Testers, Calorimeters, Rheometers Application: Metallurgy, Aerospace Components, Civil Engineering Materials, Packaging Materials, Electronics, Polymers End User: Research Laboratories, Quality Control Units, Industrial Manufacturers, Academic Institutions, Testing Services Providers, Certification Bodies |
| Companies Covered | MTS Systems Corporation, Thermo Fisher Scientific, AMETEK, Inc., Element Materials Technology, Bruker Corporation, Instron, Shimadzu Corporation, Laboratory Testing Inc., Zwick Roell Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Testing Market Strategic Shifts & Innovations
The evolution of material testing is marked by a shift from discrete, post-production quality checks to integrated, real-time materials intelligence. This transition is driven by the convergence of advanced sensors, data analytics, and the need for predictive modeling in high-performance applications.
In-situ testing, which uses embedded sensors or advanced imaging, provides real-time data on material performance under actual operational stress. Aerospace and automotive R&D departments are early adopters, using this method to observe failure mechanisms as they happen. This real-time feedback loop is displacing conventional post-mortem destructive testing for certain failure analysis and validation protocols, offering a more complete picture of material behavior.
New regulations from bodies like the US FDA are tightening requirements for material traceability and characterization in medical devices. This pressure compels manufacturers to document the full chemical and mechanical profile of every component, from raw material to finished product. The medical polymers and implantable metals segments are most affected, increasing their reliance on accredited third-party labs to meet compliance burdens for market entry.
A notable behavioral shift involves end-users preferring subscription-based access or outcome-based contracts for testing services over large capital equipment purchases. This model lowers the entry barrier for startups and smaller research labs, disrupting the traditional equipment sales channel dominated by upfront sales. This trend is particularly evident in European research consortiums focused on advanced materials, where shared access to state-of-the-art facilities is common.
Material Testing Market Segmentation
The material testing market requires granular segmentation to understand diverse technological requirements and regulatory landscapes. This analysis reveals specific demand patterns, capital investment priorities, and compliance challenges across various industries. It helps stakeholders identify growth pockets and specialized service needs.
Test Type:
Regulatory frameworks from the US FDA and EU's ECHA often dictate specific test types, driving distinct demand profiles within this segment.
- Mechanical:Mechanical tests evaluate a material's response to applied forces like tensile strength and fatigue resistance. Aerospace components manufacturing demands these for structural integrity and safety certification.
- Chemical:Chemical analysis identifies material composition, purity, and trace elements via spectroscopy. Regulatory mandates like REACH in Europe drive continuous demand for new chemical substances seeking market entry.
- Thermal:Thermal testing measures material behavior under temperature variations, crucial for polymers and composites.
- Electrical:Electrical tests assess conductivity and dielectric strength, essential for electronics and battery materials.
- Optical:Optical testing examines properties like transparency and refractive index, important for packaging and displays.
- Physical:Physical tests determine properties such as density and porosity, relevant for additive manufacturing components.
Mechanical testing handles the majority of throughput; Chemical testing is the fastest mover on share.
Equipment Type:
The capital intensity of material testing is evident in the specialized equipment required, with instruments catering to specific analytical needs.
- Universal Testing Machines:Universal Testing Machines (UTMs) apply controlled tensile, compression, and flexural forces to evaluate mechanical properties. Industrial manufacturers in automotive and construction rely on UTMs for quality control and material characterization.
- Spectrometers:Spectrometers analyze material composition by measuring light absorption or emission across wavelengths. The pharmaceutical sector and environmental monitoring use spectrometers for substance identification.
- Microscopes:Microscopes provide magnified views for microstructural analysis and defect identification.
- Hardness Testers:Hardness testers measure a material's resistance to permanent deformation, critical for metals and alloys.
- Calorimeters:Calorimeters quantify heat flow and thermal transitions, vital for polymer and composite development.
- Rheometers:Rheometers characterize the flow and deformation of liquids and semi-solids, essential for paints and food products.
Universal Testing Machines represent the core infrastructure for high-volume mechanical tests, while Spectrometers are expanding most quickly due to advanced chemical analysis needs.
Application:
Material testing applications are tied to industry-specific performance requirements and safety standards, dictating validation processes.
- Aerospace Components:Testing for aerospace components includes extensive fatigue, stress, and non-destructive evaluation. Manufacturers in the US and Europe demand stringent validation for structural integrity and aviation safety compliance.
- Polymers:Polymers testing assesses mechanical strength, thermal stability, and chemical resistance for plastic materials. The medical device industry and packaging sector require rigorous characterization for product specifications and biocompatibility.
- Metallurgy:Metallurgy applications test mechanical properties, corrosion resistance, and microstructure of metal alloys.
- Civil Engineering Materials:Civil engineering materials testing ensures strength, durability, and safety of concrete, asphalt, and structural steel.
- Packaging Materials:Packaging materials testing verifies barrier properties, seal integrity, and shelf-life performance.
- Electronics:Electronics testing focuses on material conductivity, thermal management, and reliability under stress.
Aerospace Components testing commands premium pricing due to stringent requirements, while Polymers testing exhibits the steepest expansion trajectory driven by new material innovations.
End User:
The end-user landscape ranges from internal corporate departments to specialized third-party service providers, each with distinct testing volumes and demands.
- Industrial Manufacturers:Industrial manufacturers integrate material testing into production for quality control and new product development. Automotive companies in China and Germany conduct extensive in-house testing for components and batteries.
- Testing Services Providers:Testing services providers offer specialized analytical capabilities and accredited certifications to clients lacking in-house resources. Element Materials Technology serves multinational clients needing compliance with diverse international standards.
- Research Laboratories:Research laboratories focus on fundamental material science, exploring novel properties and advanced characterization.
- Quality Control Units:Quality control units perform routine checks to ensure manufactured products meet specified material standards.
- Academic Institutions:Academic institutions conduct basic and applied research, contributing to new material discoveries and methodologies.
- Certification Bodies:Certification bodies provide independent verification that materials and products comply with national and international standards.
Industrial Manufacturers represent the largest volume of internal testing, with Testing Services Providers demonstrating the most dynamic growth in outsourced analytical demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global material testing market exhibits a complex interplay of material import and export dynamics, necessitating robust testing infrastructure across diverse geographies. Countries with significant manufacturing bases require extensive in-house and third-party testing to validate materials for domestic consumption and international trade. Conversely, nations specializing in advanced materials development drive demand for specialized analytical services that support global innovation pipelines.
United States
Aerospace and medical device manufacturing drive significant demand for material testing services in the United States. Regulations from the US FDA mandate rigorous testing for biocompatibility and material traceability in medical devices. Major industrial hubs like Seattle and Wichita focus on advanced composite testing for aircraft components, ensuring structural integrity and safety standards.
China
China's rapid expansion in electric vehicle production and advanced manufacturing fuels substantial material testing requirements. The country's GB standards ensure material quality and safety across various industrial sectors. Automotive clusters in Shanghai and Guangzhou are particularly active in testing battery materials and lightweight alloys for new energy vehicles.
Germany
Germany's strong automotive and industrial machinery sectors generate consistent demand for mechanical and metallurgical testing. Compliance with EU regulations like REACH ensures chemical substance safety and market access. The Rhine-Ruhr region, a major industrial heartland, sees extensive testing for high-performance metals and polymers used in precision engineering.
Japan
Advanced materials research and electronics manufacturing characterize Japan's material testing landscape. JIS standards provide comprehensive guidelines for material properties and testing methodologies. The Tokyo-Yokohama industrial area is a hub for R&D in novel polymers and semiconductor materials, requiring sophisticated thermal and electrical analysis.
India
India's growing infrastructure development and pharmaceutical industry contribute to rising material testing demand. The Bureau of Indian Standards (BIS) sets quality benchmarks for construction materials and manufactured goods. Chennai and Pune, key automotive and manufacturing centers, focus on testing steel, concrete, and automotive components for durability and performance.
Material Testing Market Key Industry Players
Concentration sits with established equipment manufacturers and large, accredited testing service providers, while niche analytical firms offer specialized expertise. The market structure features a tiered landscape, with global players providing broad service portfolios and regional specialists addressing specific industry needs. Dominant competitive moves include geographic expansion into emerging manufacturing hubs and portfolio diversification to cover new material types.
Within the full-service testing provider archetype, Element Materials Technology exemplifies a global network approach, serving multinational clients with diverse compliance needs. Instron occupies a position as a leading equipment manufacturer, specializing in universal testing machines used across various industrial sectors. Meanwhile, Shimadzu Corporation, a Japan-based entity, anchors the market for advanced analytical instrumentation, particularly spectrometers, catering to detailed chemical and thermal analysis.
| Leading Market Players |
|---|
| MTS Systems Corporation |
| Thermo Fisher Scientific |
| AMETEK, Inc. |
| Element Materials Technology |
| Bruker Corporation |
| Instron |
| Shimadzu Corporation |
| Laboratory Testing Inc. |
| Zwick Roell Group |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized testing equipment directly influence supply chain planning, impacting service delivery timelines and the pricing power of advanced analytical capabilities. This interplay shapes market responsiveness and investment cycles.
Pricing Analysis
The customization-premium spread differentiates pricing for highly configured analytical services from standardized, high-volume mechanical tests. Project-based pricing dominates for complex material characterization, while subscription models gain traction for data analytics platforms. Quality grade and specific regulatory certifications, such as ISO/IEC 17025, drive significant price differentiation. Pricing softness in basic mechanical testing reflects intense competition among service providers. Industrial manufacturers remain highly price-sensitive for routine quality control, contrasted by aerospace and medical device clients prioritizing validated outcomes over cost.
Supply Chain Analysis
Equipment acquisition lead times for advanced spectrometers and universal testing machines often exceed six months, creating inventory challenges for service expansion. Geographic supply of critical testing equipment concentrates in Germany, Japan, and the United States, which host major manufacturers. Raw material dependencies include specialized alloys for testing fixtures and rare earth elements for advanced sensors. Single-source vulnerability for proprietary analytical software represents a structural risk. Distribution runs through direct sales channels for high-value instruments and regional distributors for consumables and standard equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The material testing market operates as a defensive moat story, characterized by high switching costs from accredited service providers due to stringent regulatory compliance requirements and the capital intensity of specialized equipment.
For Market Incumbents: Shield existing market share by aggressively pursuing new accreditations under evolving frameworks like the EU's MDR for medical devices. Acquire niche analytical firms specializing in additive manufacturing materials to counter the threat of inconsistent testing standards. Invest in global network expansion, particularly in emerging manufacturing hubs, to leverage economies of scale in testing volume. Develop proprietary data integration platforms to enhance client stickiness.
For New Entrants and Emerging Players: A service-layer gap in real-time, in-situ testing presents a significant white-space opportunity for digital-first providers. Target under-served segments requiring rapid turnaround times for novel material characterization in polymers and composites. Focus on developing simulation software and digital twin models, offering a high-margin, value-added service. A go-to-market angle emphasizing predictive materials intelligence over post-mortem analysis can disrupt traditional models.
For Investors and Strategic Acquirers: Carve-out targets emerge from large industrial conglomerates divesting non-core testing divisions seeking specialized investment. The long-term viability of the market is anchored in continuous material innovation and evolving regulatory mandates over a 5-10 year window. Acquisition archetypes include highly specialized analytical labs with unique certifications or software companies developing AI-driven material prediction tools. The signal to watch is an increase in M&A activity within the software-defined testing and data analytics segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Accreditation | Ensures compliance with stringent regulations from bodies like the US FDA and EU's ECHA. |
| Develop Digital Twin Platforms | Reduces reliance on physical destructive testing for aerospace and automotive R&D clients. |
| Geographic Expansion in Asia | Captures growing demand from China's electric vehicle and advanced manufacturing sectors. |
| Acquire Niche Analytical Labs | Expands service portfolio into high-margin areas like additive manufacturing and medical devices. |
| Standardize Data Integration Solutions | Addresses operational hurdles for labs and enhances traceability for multinational clients. |
Research Approach
A spread of perspectives from materials scientists, R&D directors, quality assurance managers, and regulatory compliance officers converged on the working assumptions for this analysis. This primary research was rigorously validated against secondary data from ISO/IEC 17025 standards, EU REACH filings, US FDA guidance documents, and industry association reports. Bottom-up and top-down triangulation ensured consistency across market sizing and growth projections.
The segmentation dimensions modeled include test type, equipment type, application, end-user, and regional regulatory stringency across the analysis window. Compound annual growth rates were derived by analyzing historical growth trends, technological adoption curves, and future demand drivers. Industry-specific forecast inputs included new material development cycles in aerospace and the enforcement trends of environmental regulations.
Forecasts assume regulatory continuity in EU, US, and Chinese regimes; material policy shifts would require re-modeling. The analysis reflects current market dynamics and anticipated technological advancements. Revision becomes warranted when significant regulatory framework changes or major economic downturns cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Rheology Controller Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Material Tester Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Chromatography Accessories and Consumables Market