
 Global Asbestos Testing Market | 2026-2036
Global Asbestos Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asbestos Testing Market Foresight
ISO/IEC 17025 accreditation is rotating as the primary gatekeeper for laboratory market access, filtering out uncredentialed competitors across high-stakes jurisdictions. ALS leverages its multi-country laboratory footprint to sustain contract flows from government remediation tenders. EMSL Analytical anchors North American demand through dense service center coverage and rapid turnaround protocols. Lucion Services differentiates via integrated risk management bundling that extends beyond standalone testing into compliance advisory.
Asbestos testing encompasses the qualitative and quantitative detection of asbestos fibers in environmental and bulk material samples, employing optical and electron microscopy techniques that resolve fibers down to 0.25 micrometers in width. Its primary purpose is to verify regulatory compliance and protect human health before disturbance, demolition, or occupancy of contaminated structures. Polarized Light Microscopy dominates routine bulk analysis due to cost efficiency, while Transmission Electron Microscopy captures premium pricing for airborne fiber litigation support where legal defensibility demands highest resolution. Environmental Monitoring applications show the steepest growth trajectory as continuous ambient surveillance expands around brownfield redevelopment zones.
EPA asbestos NESHAP mandates pre-demolition inspection, OSHA enforces worker exposure limits through periodic air monitoring, and ISO/IEC 17025 governs laboratory competence standards that buyers now require in procurement specifications. These frameworks collectively shift market power toward accredited laboratories with documented quality systems and defensible chain-of-custody protocols. Stakeholders must monitor evolving EPA renovation, repair, and painting rule expansions that could trigger mandatory testing in previously exempt residential structures.
Market Dynamics
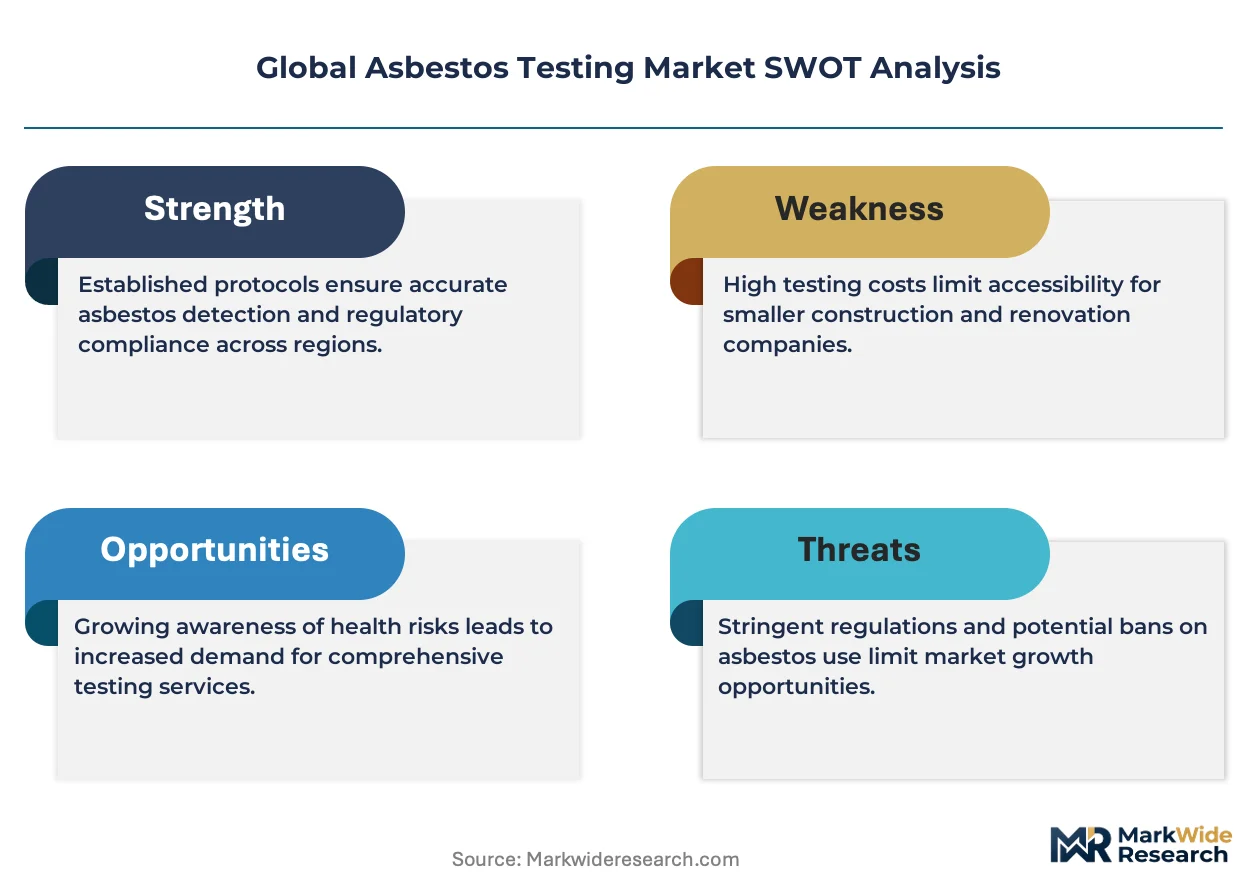
ISO/IEC 17025 accreditation requirements are compressing laboratory supply into credentialed operators, filtering out uncertified competitors across high-stakes jurisdictions where chain-of-custody defensibility determines contract awards.
Growth Catalysts
- EPA NESHAP pre-demolition mandates:Mandatory inspection protocols before commercial building demolition sustain certified laboratory demand across the United States.
- Aging building stock concentration:Legacy structures exceeding fifty years of age in Australia and the United Kingdom drive continuous bulk material sampling requirements.
- Transmission Electron Microscopy resolution standards:Litigation-grade airborne fiber detection protocols command premium pricing for legal defensibility in occupational exposure disputes.
Market Restraints
- Electron microscopy capital intensity:Transmission Electron Microscopy equipment procurement and maintenance costs constrain mid-tier laboratory expansion.
- Accreditation timeline friction:ISO/IEC 17025 certification cycles extending twelve to eighteen months delay new entrant market access.
- Polarized Light Microscopy substitution ceiling:Cost-efficient bulk analysis methods cap pricing power for high-resolution airborne fiber testing in routine applications.
Strategic Opportunities
- Environmental Monitoring application expansion:Continuous ambient surveillance deployment around brownfield redevelopment zones in the United Kingdom creates new contract streams.
- Integrated risk management bundling:Testing-advisory combinations extend laboratory relationships beyond transactional sampling into recurring compliance retainers.
- OSHA periodic air monitoring mandates:Worker exposure limit enforcement generates recurring industrial hygiene contract volume across manufacturing facilities.
Industry Challenges
- Microscopist certification scarcity:Qualified asbestos fiber identification specialists require extended training in refractive index determination and morphology classification.
- Sample chain-of-custody complexity:Defensible documentation protocols demand specialized logistics infrastructure that smaller laboratories struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asbestos Testing Market |
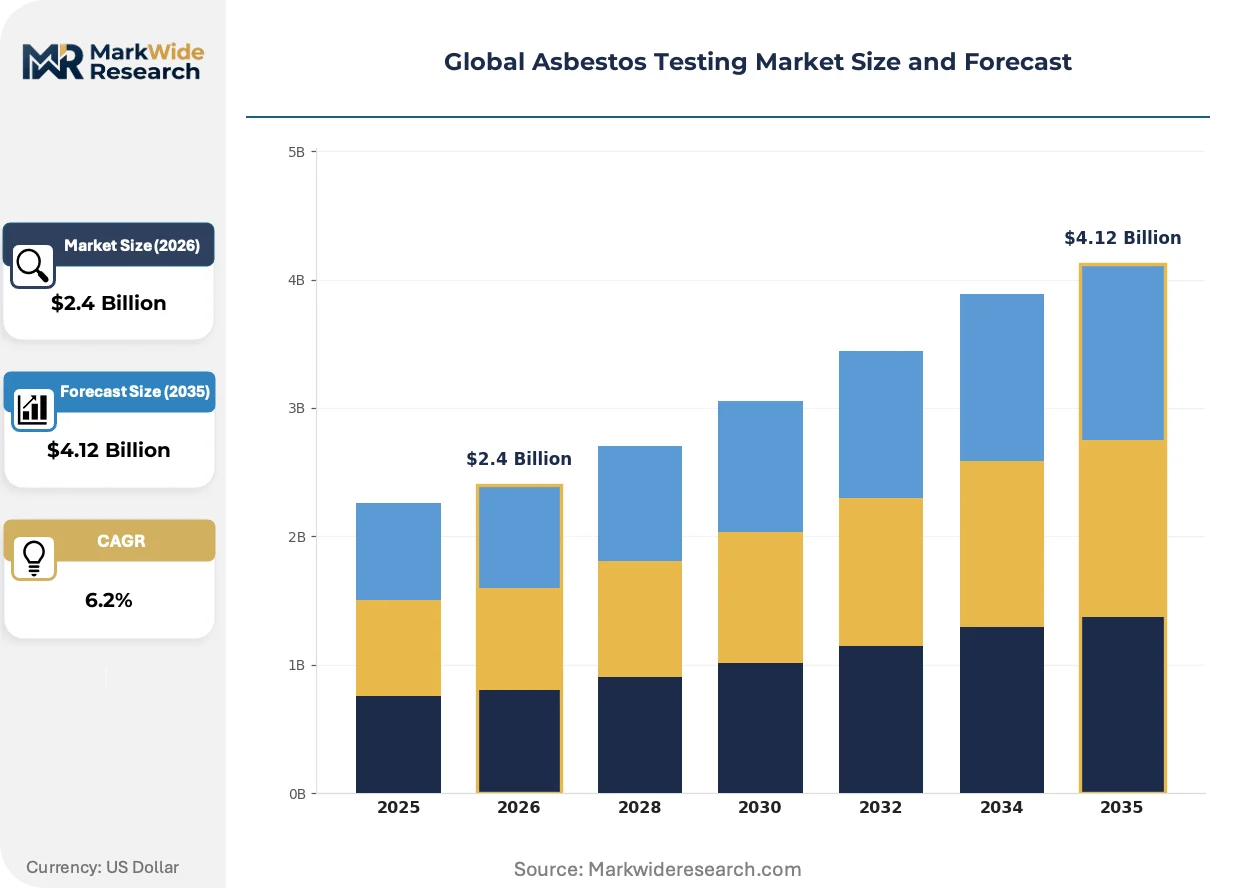
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Polarized Light Microscopy, Transmission Electron Microscopy, Phase Contrast Microscopy, X-Ray Diffraction Sample Type: Soil, Air, Water, Bulk Materials Application Sector: Construction Assessment, Environmental Monitoring, Occupational Safety, Demolition Projects End User: Inspection Agencies, Environmental Consultants, Industrial Facilities, Government Bodies |
| Companies Covered | ALS, AIH Laboratory, LCS Laboratory, Lucion Services, EMSL Analytical, Bradley Environmental, EMET Environmeteo Services, EnviroTest, Scientific Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asbestos Testing Market Shifts & Advancements
Digital imaging and automated fiber counting systems are compressing analytical turnaround times while elevating data reproducibility standards across accredited laboratories.
Scanning Electron Microscopy with Energy Dispersive X-ray Spectroscopy is fragmenting the high-resolution detection segment. Commercial laboratories in Australia are adopting this hybrid approach for simultaneous fiber morphology and elemental composition verification. The technology is fragmenting premium service tiers previously monopolized by Transmission Electron Microscopy, enabling mid-cap laboratories to contest litigation-support contracts.
EPA renovation, repair, and painting rule expansions are extending mandatory testing obligations into residential structures previously exempt from commercial-grade inspection protocols. Property management firms and homeowner associations now face compliance obligations that drive demand for rapid-turnaround bulk analysis services. United States multi-family housing operators are responding by pre-qualifying accredited laboratories for recurring maintenance-triggered testing.
Buyer concentration around large-scale remediation contractors is compressing procurement cycles and demanding integrated reporting platforms. Government tender processes in the United Kingdom now require digital data portals that link field sampling, laboratory analysis, and risk assessment documentation. Tier-one environmental consultancies are consolidating vendor relationships to reduce administrative overhead across multi-site asbestos management programs.
Global Asbestos Testing Market Segmentation
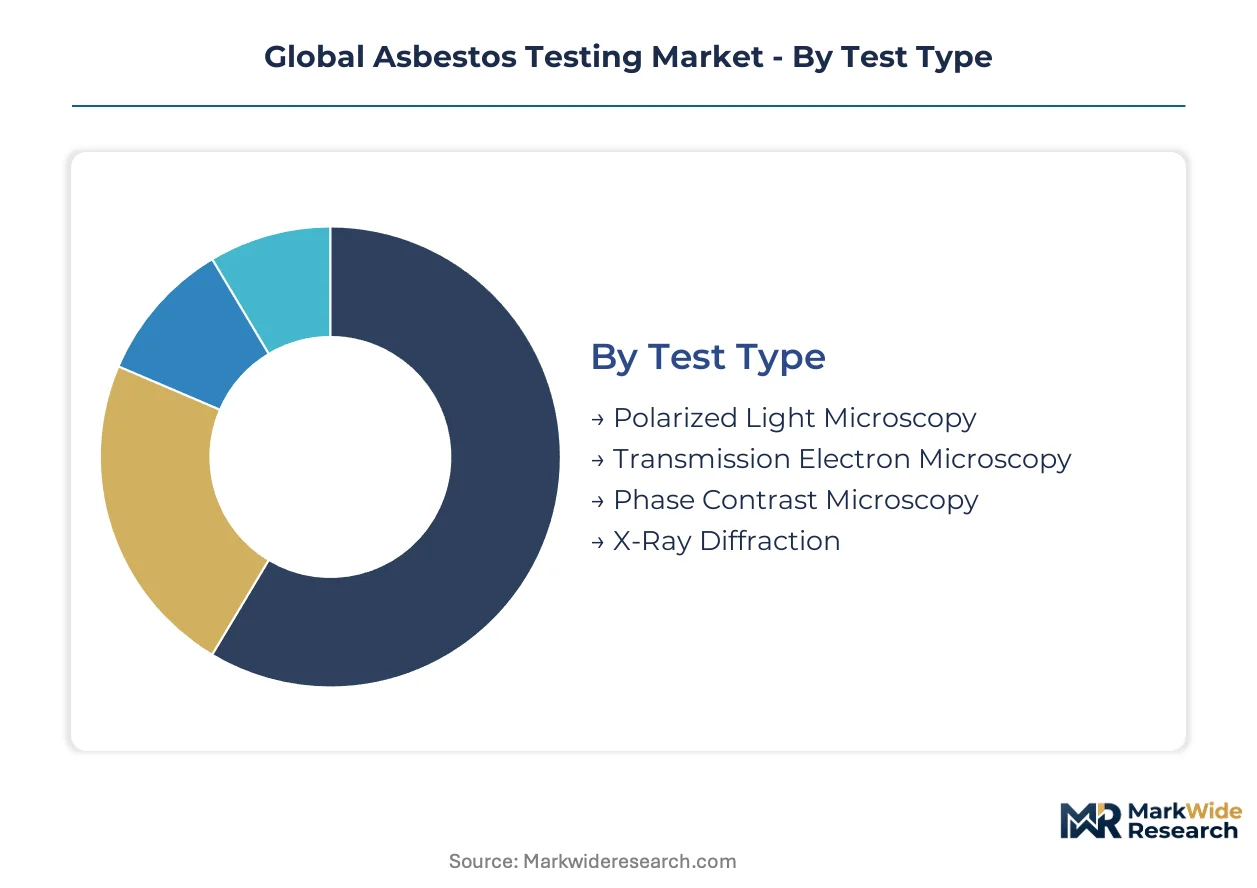
Segmentation in asbestos testing reflects divergent technical requirements across regulatory frameworks. Channel dynamics vary sharply between routine bulk analysis and litigation-grade airborne fiber detection. Procurement patterns concentrate high-volume contracts around accredited laboratories with multi-technique capabilities.
Test Type:
Channel distribution splits between high-throughput routine services and premium forensic offerings. Government tenders and industrial facilities favor cost-optimized bulk methods. Law firms and insurance carriers drive demand for electron microscopy through specialized forensic channels.
- Polarized Light Microscopy:Optical technique employing refractive index matching for asbestos fiber identification in bulk construction materials. Demand concentrates in United States commercial renovation contracts where OSHA and EPA NESHAP compliance mandates routine pre-disturbance screening. Cost efficiency sustains dominant market share despite resolution limitations below 0.25 micrometers.
- Transmission Electron Microscopy:Electron beam resolution enables definitive fiber morphology and selected area electron diffraction analysis for airborne samples. United Kingdom occupational exposure litigation drives premium pricing where legal defensibility requirements exclude optical alternatives. Capital intensity restricts service provision to tier-one accredited laboratories.
- Phase Contrast Microscopy:Differential interference contrast technique applied to airborne fiber counting in industrial hygiene monitoring.
- X-Ray Diffraction:Crystallographic identification method for bulk material mineralogy determination in geological and construction samples.
Polarized Light Microscopy dominates installed base. Transmission Electron Microscopy is where expansion concentrates.
Sample Type:
Cost tier stratification separates high-frequency environmental screening from capital-intensive forensic analysis. Routine bulk and air sampling flow through high-volume service centers. Soil and water matrices command specialized preparation protocols and extended turnaround pricing.
- Soil:Acid digestion and heavy liquid separation protocols prepare contaminated land samples for microscopic analysis. Brownfield redevelopment projects in Australia generate recurring contract volume where state environmental protection agencies mandate pre-development assessment.
- Air:Membrane filter collection and fiber counting protocols for occupational and ambient exposure assessment. OSHA periodic monitoring mandates across United States manufacturing facilities sustain recurring industrial hygiene demand with standardized volume pricing.
- Water:Aqueous sample preparation for asbestos fiber detection in potable and wastewater matrices.
- Bulk Materials:Construction material sampling including insulation, flooring, and cementitious products for pre-renovation compliance.
Bulk Materials dominates installed base. Soil is where expansion concentrates.
Application Sector:
Customer type segmentation distinguishes transactional project work from recurring compliance retainers. Property developers and facility managers drive construction-related demand. Regulatory enforcement patterns shape environmental and occupational safety contract stability.
- Construction Assessment:Pre-renovation and pre-occupancy bulk material surveys in commercial and residential buildings. Aging building stock exceeding fifty years in the United Kingdom sustains continuous demand where landlord certification requirements trigger mandatory inspection.
- Environmental Monitoring:Continuous ambient surveillance and brownfield redevelopment zone assessment. United States EPA enforcement expansion around residential renovation rules is accelerating contract growth in previously exempt multi-family housing segments.
- Occupational Safety:Workplace air monitoring and exposure limit compliance verification.
- Demolition Projects:Pre-demolition inspection and clearance air monitoring for structural removal.
Construction Assessment dominates installed base. Environmental Monitoring is climbing the fastest.
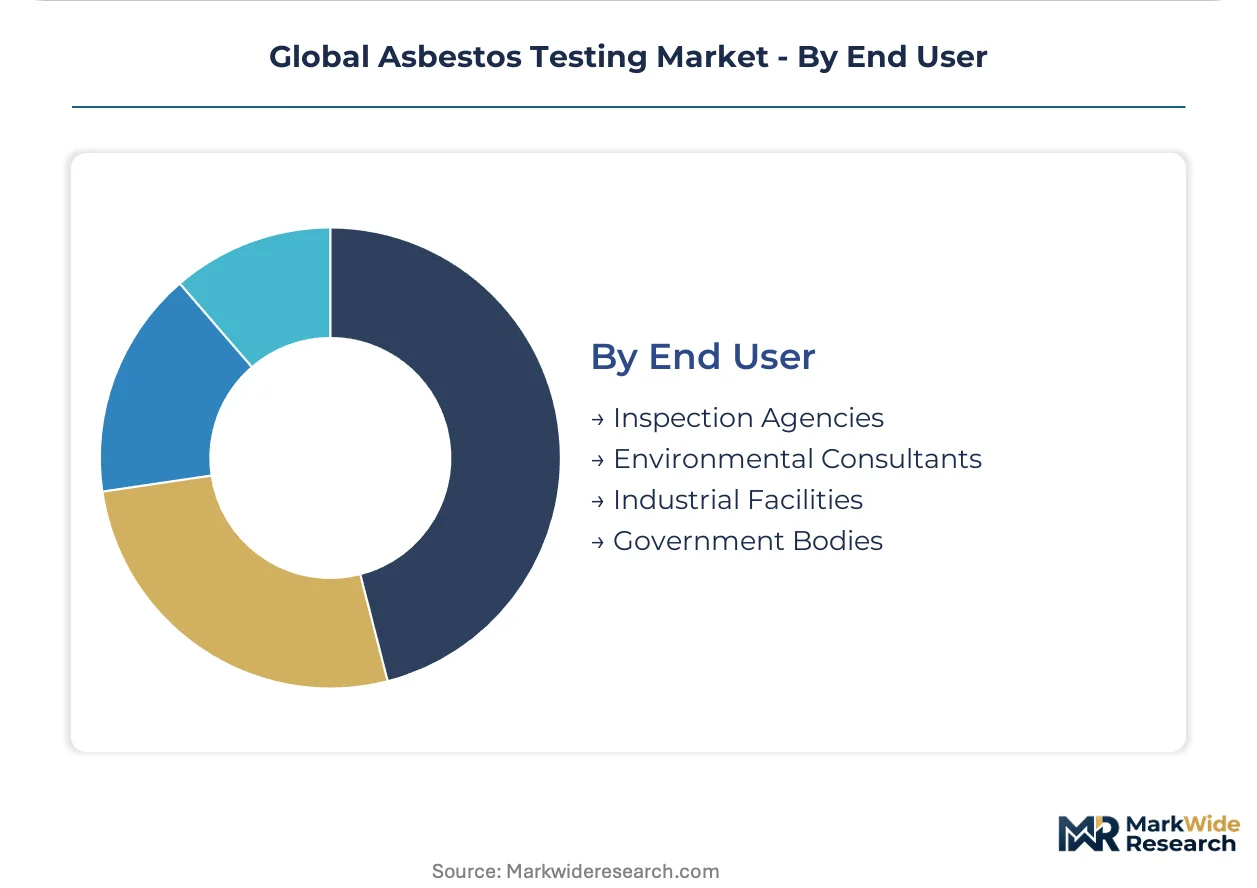
End User:
Supply concentration varies across procurement sophistication levels. Government tenders demand comprehensive quality systems and digital reporting platforms. Industrial direct procurement favors rapid turnaround and geographic proximity.
- Inspection Agencies:Specialized firms conducting field sampling and preliminary assessment for client referral to analytical laboratories. United States multi-site property management firms are consolidating preferred vendor relationships to standardize documentation across portfolios.
- Environmental Consultants:Full-service advisory practices bundling risk assessment with testing procurement. United Kingdom government remediation tenders now require integrated digital portals linking field sampling, laboratory analysis, and compliance documentation.
- Industrial Facilities:Manufacturing and processing plants conducting in-house or contracted monitoring for worker protection.
- Government Bodies:Regulatory agencies and public works departments managing contaminated public assets.
Environmental Consultants dominates installed base. Inspection Agencies is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA asbestos NESHAP enforcement and tightening OSHA permissible exposure limits are reshaping laboratory demand across high-income economies with legacy building stock exceeding fifty years. National regulators in Australia, the United Kingdom, and the United States are mandating pre-demolition inspection and continuous ambient surveillance around brownfield zones.
United States
Commercial renovation activity in aging office buildings and multi-family housing sustains certified inspection demand. EPA renovation, repair, and painting rule expansions extend mandatory testing into previously exempt residential structures. Property management firms in Chicago and New York Metro are pre-qualifying accredited laboratories for recurring maintenance-triggered bulk analysis.
Australia
State environmental protection agencies mandate pre-development soil assessment for brownfield redevelopment projects. The country's national workplace safety regulator enforces strict asbestos management protocols in construction and demolition. Sydney and Melbourne laboratories are expanding transmission electron microscopy capacity to meet litigation-grade airborne fiber detection requirements.
United Kingdom
Landlord certification requirements trigger mandatory inspection in structures exceeding fifty years of age. Government remediation tenders now require integrated digital portals linking field sampling, laboratory analysis, and risk assessment documentation. London-based environmental consultancies are consolidating vendor relationships across multi-site asbestos management programs.
Germany
REACH regulation and occupational exposure limit enforcement sustain demand for workplace air monitoring in manufacturing facilities. The country's national chemical regulator maintains stringent bulk material screening protocols for imported construction products. Industrial laboratories in North Rhine-Westphalia and Bavaria are bundling testing with compliance advisory services.
Canada
Health Canada guidelines and provincial workplace safety codes mandate pre-renovation inspection in public buildings and schools. Federal infrastructure stimulus programs accelerate demand for environmental monitoring around aging government asset portfolios. Toronto and Vancouver service centers are deploying rapid-turnaround protocols for construction sector contracts.
Global Asbestos Testing Market Competitive Landscape
Player mix skews toward multi-country laboratory networks and specialized environmental consultancies with accredited analytical capabilities. Market structure concentrates contract awards around tier-one operators with ISO/IEC 17025 accreditation and documented quality systems. Three strategic archetypes dominate: dense service center networks optimizing geographic proximity, integrated risk management bundlers extending beyond transactional testing, and litigation-support specialists commanding premium pricing for electron microscopy defensibility. Competitive moves center on accreditation-driven capacity expansion and digital platform integration for chain-of-custody documentation.
Within the multi-country network tier, ALS leverages its laboratory footprint across Australia, the United States, and the United Kingdom to sustain government remediation tender flows. Lucion Services occupies a position exemplifying integrated risk management bundling, extending relationships beyond standalone testing into recurring compliance retainers. EMSL Analytical anchors North American demand through service center density and rapid-turnaround protocols, representing the geographic proximity archetype in high-volume commercial renovation markets.
| Leading Market Players |
|---|
| ALS |
| AIH Laboratory |
| LCS Laboratory |
| Lucion Services |
| EMSL Analytical |
| Bradley Environmental |
| EMET Environmeteo Services |
| EnviroTest |
| Scientific Services |
| Others |
Supply & Pricing Matrix
Polarized Light Microscopy substitution for routine bulk analysis is redistributing contract volume toward mid-tier laboratories in the United States and Australia, compressing pricing premiums for Transmission Electron Microscopy while elevating throughput economics for accredited service centers with multi-technique capability.
Pricing Analysis
Certification level (ISO/IEC 17025-grade) creates the primary spread between premium litigation-support contracts and routine compliance screening. Three-tier pricing structure across litigation-grade, accredited-standard, and non-accredited economy levels segments buyer archetypes, with law firms and insurance carriers absorbing premium electron microscopy rates while property developers drive volume at standardized bulk analysis pricing. Cost compression in the mid-tier is intensifying because Scanning Electron Microscopy with Energy Dispersive X-ray Spectroscopy enables mid-cap laboratories to contest previously monopolized premium segments. Government remediation contractors exhibit lowest price sensitivity due to defensibility requirements, whereas residential renovation clients prioritize turnaround speed over resolution specifications.
Supply Chain Analysis
Port congestion on trans-Pacific lanes elevates inbound logistics costs for electron microscopy equipment sourced from Japan and Germany, extending capital deployment timelines for laboratory expansion projects. Equipment manufacturing concentrates in Japan, Germany, and the Netherlands for high-resolution microscopy systems, while consumable filter membranes and calibration standards draw from United States and United Kingdom specialty chemical suppliers. Single-source vulnerability in electron microscope column manufacturing creates procurement risk for tier-two laboratories seeking litigation-grade capability. Distribution runs through manufacturer-authorized service networks with regional technical support hubs, constraining rapid capacity scaling outside established metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around large-scale remediation contractors and multi-site property management firms, compressing vendor lists and demanding integrated digital reporting platforms that favor accredited laboratory networks with documented quality systems.
For Market Incumbents: Shield market position by accelerating ISO/IEC 17025 accreditation expansion into secondary United Kingdom and Australian metropolitan markets before twelve-to-eighteen-month certification cycles delay competitor entry. Deepen backward integration into field sampling logistics to control chain-of-custody documentation quality against emerging digital platform competitors. Prioritize transmission electron microscopy capacity additions in Sydney and Melbourne where litigation-grade airborne fiber detection faces supply constraints. For New Entrants and Emerging Players: Lead with rapid-turnaround Polarized Light Microscopy services targeting United States multi-family housing operators responding to EPA renovation rule expansions. Environmental Monitoring applications around brownfield redevelopment zones in the United Kingdom present the most penetrable white space, with continuous ambient surveillance contracts requiring less capital intensity than litigation-grade electron microscopy. Pursue accreditation partnerships with established tier-one laboratories to bypass direct ISO/IEC 17025 certification timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated risk management bundlers over standalone testing operators. Long-term viability over the next decade hinges on recurring compliance retainer relationships rather than transactional project volume. Acquisition targets should display digital platform integration capabilities linking field sampling, laboratory analysis, and risk assessment documentation. Watch EPA residential renovation rule enforcement intensity as the primary inflection indicator for volume acceleration in previously exempt market segments.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 17025 Accreditation Expansion | United States and United Kingdom government tenders now mandate documented laboratory competence standards for contract eligibility. |
| Digital Platform Integration | United Kingdom remediation contractors require linked field sampling, laboratory analysis, and compliance documentation portals. |
| Transmission Electron Microscopy Capacity Addition | Sydney and Melbourne litigation-grade airborne fiber detection faces supply constraints from qualified microscopist scarcity. |
| Integrated Risk Management Bundling | Environmental consultancies in London are consolidating vendor relationships across multi-site asbestos management programs. |
| Rapid-Turnaround Service Center Deployment | Chicago and New York Metro property management firms are pre-qualifying accredited laboratories for maintenance-triggered testing. |
Research Methodology
Cross-validation between regulatory filing analysis and laboratory accreditation database records anchors the qualitative findings across the asbestos testing sector. Primary interviews with certified asbestos microscopists, environmental consultancy procurement directors, government remediation tender officers, and industrial hygiene managers combined with secondary validation from EPA enforcement action records, OSHA compliance directive databases, ISO/IEC 17025 accreditation registries, and United Kingdom Health and Safety Executive inspection reports. Bottom-up service center capacity estimates and top-down contract value triangulation establish market sizing boundaries.
Sensitivity analysis around EPA rule expansion timing and electron microscopy equipment lead times shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include test type resolution tier, sample matrix complexity, application sector regulatory intensity, and end-user procurement sophistication. CAGRs derive from accredited laboratory capacity expansion trajectories correlated with enforcement action velocity and brownfield redevelopment project pipelines. Forecast inputs incorporate microscopist certification training pipeline constraints and digital platform adoption curves among tier-one environmental consultancies.
Underlying assumptions cover sustained EPA NESHAP enforcement intensity and OSHA permissible exposure limit maintenance, with deviation risk concentrated in regulatory rulemaking delays or acceleration of residential renovation mandates. Practitioners should keep alternative scenarios live as EPA renovation, repair, and painting rule coverage expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Hydrocarbon Tester Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Micro Carbon Residue Tester Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Piping Hydro Testing Market
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Dynamic Light Scattering (DLS) Measure Instrument Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Supercritical Fluid Chromatography Market