
 Abrasion Tester Market | 2026-2036
Abrasion Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Abrasion Tester Market Analysis
Polyurethane foam laminates is decoupling from traditional vinyl substrates in automotive seating applications, forcing recalibration of abrasion protocols across OEM labs. Taber Industries leverages its rotary platform heritage to anchor North American calibration standards. James Heal competes through specialized textile-focused configurations, while Qinsun Instruments extends cost-engineered digital variants across Asian manufacturing hubs.
An abrasion tester quantifies surface wear resistance through controlled mechanical friction cycles, typically applying specified loads against standardized abradants to measure mass loss, gloss reduction, or thread breakage. The instrument serves industrial quality assurance by validating material endurance before commercial deployment. Taber rotary devices dominate legacy certification workflows, whereas automated digital systems represent the fastest-expanding technology segment as laboratories replace manual operators. Martindale configurations sustain margin concentration in European textile compliance, while rub testers occupy niche packaging film validation.
REACH substance restrictions and the EU Green Deal's material circularity mandates compel European manufacturers to verify abrasion performance across recycled-content formulations. China's SAMR enforces updated GB standards for automotive interior durability, while the US EPA's VOC guidelines indirectly shape coating abrasion requirements through formulation constraints. Stakeholders must monitor divergence between regional test protocols when configuring multi-market certification strategies.
Market Dynamics
Automotive OEMs are recalibrating entire testing workflows as polyurethane foam laminates displace vinyl substrates in seating applications, forcing simultaneous protocol updates across interior trim, dashboard, and door panel validation suites.
Growth Catalysts
- REACH substance restrictions:ECHA mandates are compelling European manufacturers to verify abrasion performance across recycled-content formulations, expanding testing volumes for reformulated polymers.
- China's GB standards tightening:SAMR enforcement of updated automotive interior durability benchmarks is accelerating replacement cycles for obsolete testing equipment in domestic labs.
- Polyurethane foam migration:The material's decoupling from traditional vinyl substrates in automotive seating is creating parallel demand for recalibrated abrasion protocols across OEM certification workflows.
Market Restraints
- Calibration consumables concentration:Specialized abradant supply chains cluster in Germany and Japan, exposing buyers to input cost volatility and extended lead times.
- Taber rotary platform lock-in:Decades of legacy certification workflows around this specific geometry create technical switching costs for laboratories considering alternative test configurations.
- Skilled operator scarcity:Manual abrasion testing expertise is concentrating among retiring technician cohorts, constraining throughput expansion for non-automated facilities.
Strategic Opportunities
- India's PLI scheme for textiles:Domestic manufacturing incentives are attracting technical textile investments that will require localized Martindale and rotary testing capacity.
- Digital twin integration:Convergence of physical abrasion testing with predictive wear modeling is enabling remote certification workflows for distributed supply chains.
- EU Green Deal circularity mandates:Material recyclability verification requirements are creating new test categories for post-consumer content performance validation.
Industry Challenges
- Multi-protocol certification complexity:Laboratories serving both automotive and textile verticals must maintain simultaneous compliance with ASTM, ISO, and GB standard variants, stretching technical staff bandwidth.
- Legacy system integration friction:Automated digital abrasion systems face interoperability barriers with existing LIMS and ERP infrastructure in established testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abrasion Tester Market |
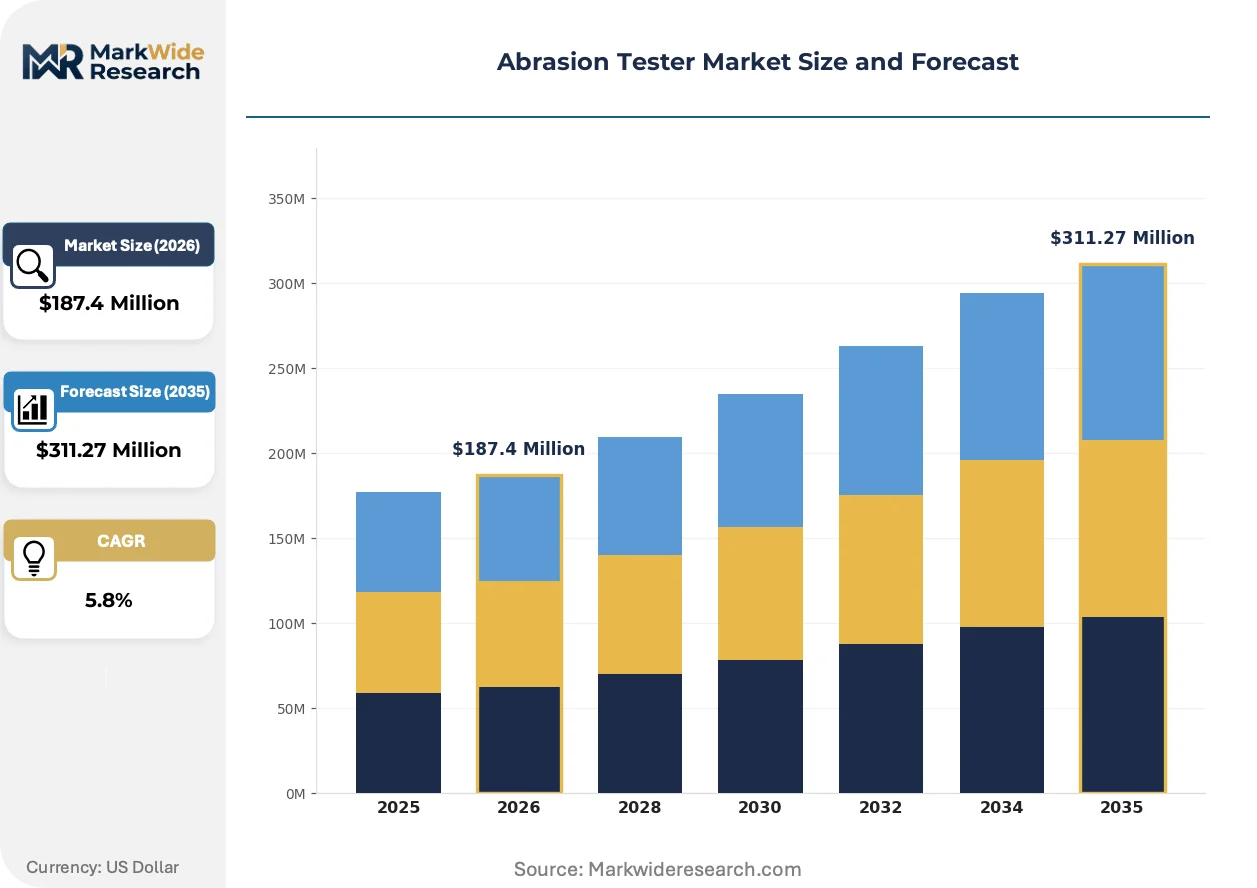
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Taber, Martindale, Wyzenbeek, Rub Tester Technology: Mechanical, Digital, Automated, Manual End User: Textiles, Automotive, Packaging, Electronics Application: Quality Control, Research, Production Testing, Standards Compliance |
| Companies Covered | Taber Industries, Benz, PRESTO, Presto Group, AML Instruments, Humboldt Mfg, Qinsun Instruments, James Heal, IGT Testing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abrasion Tester Market Emerging Trajectories
Digital automation is compressing operator-dependent variability out of certification workflows while regulatory fragmentation across major economies forces equipment vendors to engineer multi-protocol flexibility into single platforms.
Automated digital abrasion systems is rewriting how laboratories execute certification workflows. These platforms eliminate operator-dependent variability in load application and cycle counting. Tier-1 automotive suppliers in Germany and Japan are adopting them at accelerated pace to meet compressed OEM validation timelines. The technology is rewriting competitive requirements for testing service providers by making 24-hour unattended operation a baseline expectation rather than premium capability.
REACH substance restrictions and the EU Green Deal's material circularity mandates are tightening verification requirements for recycled-content formulations across European manufacturing. Industrial consequence includes expanded test matrices covering batch-to-batch variability in post-consumer polymer feedstocks. Automotive interior suppliers in Stuttgart and Wolfsburg corridors are responding by consolidating testing relationships with laboratories holding multi-standard accreditation.
Buyer concentration among automotive OEMs is compressing switching cycles for testing equipment vendors. Tier-1 suppliers now expect equipment lifecycle support extending 15-20 years with firmware upgrade pathways. This pattern is most visible in Germany's automotive testing corridor, where consolidated procurement functions at major OEMs are unbundling after-sales service contracts from initial capital purchases.
Abrasion Tester Market Segmentation
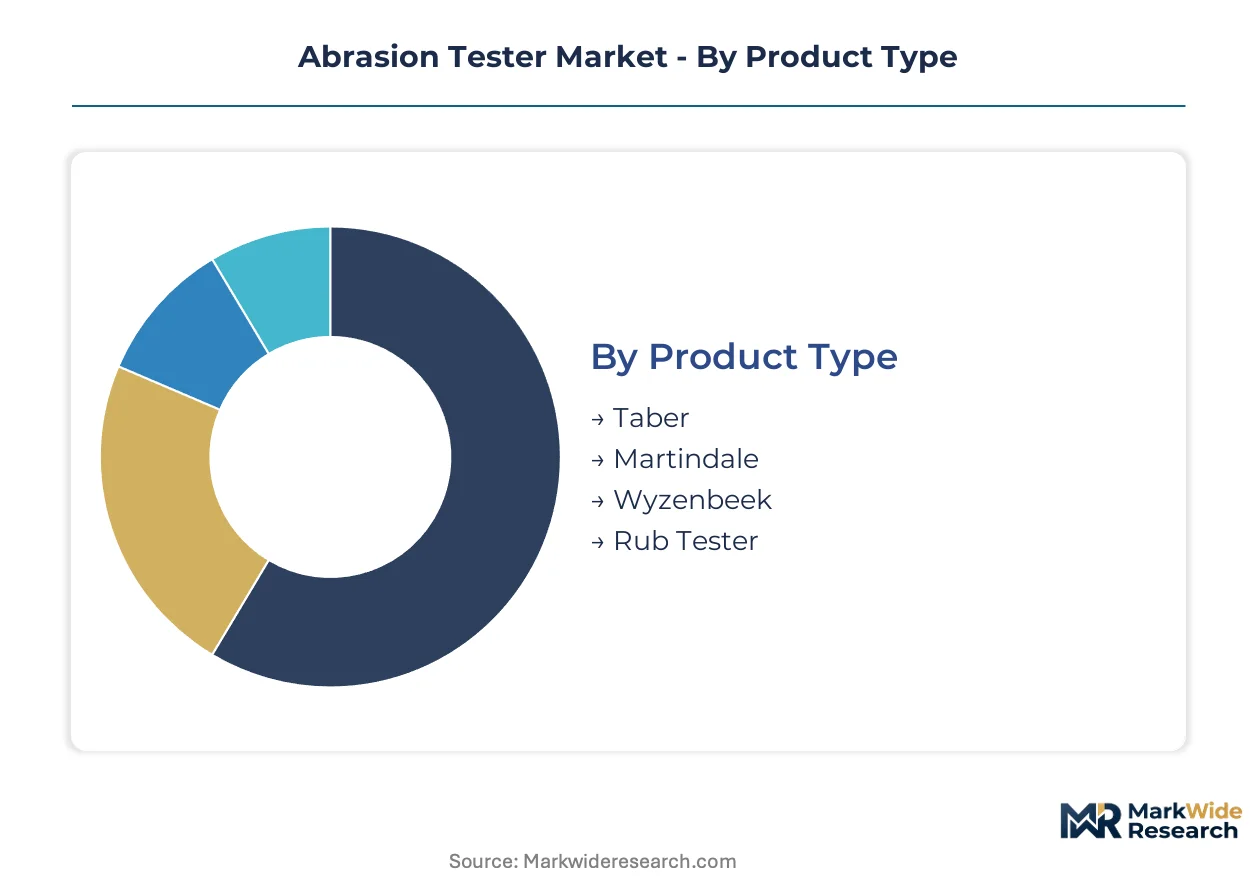
Equipment upgrade cycles vary dramatically across abrasion testing modalities, with legacy rotary platforms requiring 15-20 year replacement timelines while digital automated systems compress refresh intervals to 7-10 years. Procurement decisions increasingly hinge on multi-protocol flexibility rather than single-standard specialization.
Product Type:
Replacement cycles diverge sharply between established rotary architectures and emerging digital platforms, creating asymmetric competitive dynamics among equipment vendors.
- Taber:Rotary platform geometry dominates legacy certification workflows across North American automotive labs. Equipment refresh concentrates in Tier-1 supplier facilities around Detroit and Stuttgart as OEMs mandate protocol standardization.
- Martindale:Circular abrasion motion with Lissajous pattern serves European textile compliance requirements. Demand clusters in northern England technical textile corridors and Italian upholstery manufacturing zones.
- Wyzenbeek:Oscillatory cylinder method validates woven fabric durability for contract furniture specifications.
- Rub Tester:Linear reciprocating motion addresses packaging film and printed substrate validation needs.
Volume placements concentrate in Taber configurations; the faster expansion belongs to Martindale systems as Asian textile investments accelerate.
Technology:
Cost stratification separates premium automated installations from economy manual alternatives, with mid-tier digital hybrids capturing laboratory budget constraints.
- Mechanical:Cam-driven load application and mechanical cycle counters persist in budget-constrained facilities. Procurement concentrates in Indian technical textile startups and Southeast Asian packaging converters where labor arbitrage sustains operator-dependent workflows.
- Digital:Sensor-equipped platforms capture real-time wear progression data for predictive modeling integration. Adoption accelerates in German automotive OEM central labs pursuing digital twin convergence.
- Automated:Robotic sample handling and unattended multi-station operation eliminate operator variability. Premium positioning targets Japanese electronics material suppliers facing compressed validation timelines.
- Manual:Hand-cranked or simple motor-driven units serve educational institutions and small-batch certification needs.
Manual systems retain volume leadership in emerging economies; automated configurations climb the fastest as 24-hour throughput becomes baseline expectation.
End User:
Customer maturity varies from standardized automotive procurement to fragmented textile laboratory networks, shaping vendor sales motion and service attachment strategies.
- Textiles:Technical fabric mills and apparel certification bodies drive Martindale and Wyzenbeek demand. Investment concentrates in India's PLI-supported technical textile zones and Bangladesh garment testing expansion.
- Automotive:OEM central labs and Tier-1 supplier quality departments mandate multi-protocol equipment flexibility. Procurement clusters in Germany's Stuttgart-Wolfsburg corridor and Japanese Nagoya-Toyota supplier networks.
- Packaging:Film converters and flexible packaging printers validate printed layer adhesion and surface durability.
- Electronics:Connector housing and device enclosure manufacturers verify coating and material wear resistance.
Automotive buyers command largest individual order values; textile end users represent the steepest expansion trajectory as manufacturing migrates to South Asia.
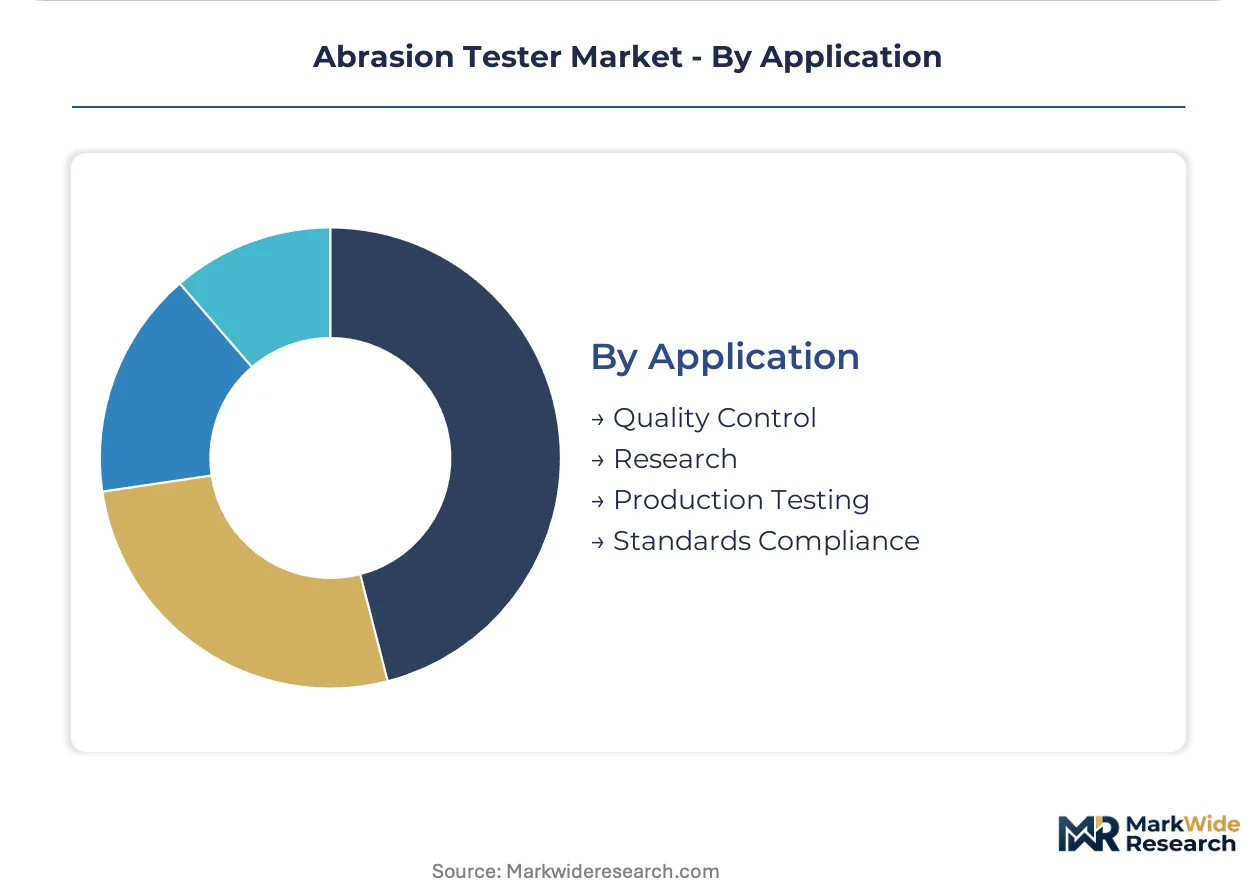
Application:
Margin structure separates high-value research instrumentation from standardized production testing equipment, with compliance verification occupying intermediate value capture.
- Quality Control:In-line and near-line testing validates batch consistency before customer shipment. Deployment concentrates in Chinese automotive interior supplier parks serving domestic OEMs.
- Research:Materials development labs require configurable load parameters and custom abradant compatibility. Demand clusters in polymer science departments at German technical universities and Japanese corporate R&D centers.
- Production Testing:High-throughput validation of finished goods before release to distribution channels.
- Standards Compliance:Third-party certification bodies maintain accredited testing capacity for supplier audit requirements.
Production testing captures highest unit volumes; research applications deliver premium pricing and longest equipment lifecycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany and Japan command the largest equipment procurement budgets, while textile manufacturing migration to South Asia is redistributing demand toward India and Bangladesh certification infrastructure.
Germany
OEM central labs in Stuttgart and Wolfsburg drive multi-protocol equipment specifications for interior trim validation. ECHA's REACH substance restrictions compel batch-to-batch testing of recycled-content polymers. Testing service providers in Baden-Württemberg are consolidating accreditations to capture Tier-1 supplier outsourcing.
China
Domestic automotive interior suppliers around Shanghai and Guangzhou are expanding in-house testing capacity. SAMR enforcement of updated GB standards for wear resistance accelerates equipment replacement cycles. Certification bodies in the Yangtze River Delta are adding Martindale configurations to serve export textile manufacturers.
United States
Detroit-based Tier-1 suppliers maintain legacy Taber rotary workflows for OEM protocol compliance. EPA VOC guidelines indirectly constrain coating formulation choices that affect abrasion testing parameters. Independent laboratories in Michigan are unbundling service contracts from capital purchases under consolidated procurement functions.
India
Technical textile investments under the PLI scheme are creating localized demand for Martindale and rotary testing capacity. BIS certification requirements for automotive components extend to interior material durability verification. Manufacturing clusters in Gujarat and Tamil Nadu are attracting testing equipment distributors.
Japan
Electronics material suppliers in the Nagoya-Toyota corridor face compressed validation timelines favoring automated systems. METI's quality infrastructure programs support laboratory modernization grants. Connector housing manufacturers are verifying coating wear resistance through expanded test matrices.
Abrasion Tester Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with rotary platform heritage anchoring North American procurement while textile-focused configurations sustain European positioning. The vendor base clusters around three strategic archetypes: legacy calibration standard holders, digital automation specialists, and cost-engineered Asian fabricators. M&A activity concentrates on digital workflow capabilities, while geographic expansion targets South Asian textile certification growth.
Among heritage calibration specialists, Taber Industries exemplifies the rotary platform standard-holder archetype through decades of North American automotive lab penetration. James Heal occupies a parallel position in European textile compliance through specialized Martindale configurations. Qinsun Instruments represents the cost-engineered digital variant segment extending across Asian manufacturing hubs. These three anchors illustrate how competitive positioning fragments across geography and end-use vertical rather than consolidating around unified technology platforms.
| Leading Market Players |
|---|
| Taber Industries |
| Benz |
| PRESTO |
| Presto Group |
| AML Instruments |
| Humboldt Mfg |
| Qinsun Instruments |
| James Heal |
| IGT Testing Systems |
| Others |
Supply Flow & Price Mechanics
OEM mandates for 15-20 year equipment lifecycle support with firmware upgrade pathways are forcing supply chain reconfiguration toward long-term service bundling, compressing upfront capital margins while expanding recurring revenue capture.
Pricing Analysis
Volume placements concentrate in mechanical and manual configurations serving budget-constrained laboratories; margins concentrate in automated digital systems commanding premium positioning. Price differentiation hinges on certification grade (ISO/IEC 17025 accredited configurations vs. non-accredited units) and after-sales service bundling. Cost compression in economy tiers is intensifying because Asian fabricators are scaling cost-engineered digital variants. Small-batch textile certification bodies exhibit highest price sensitivity; Japanese electronics material suppliers facing compressed validation timelines exhibit lowest.
Supply Chain Analysis
India's PLI scheme for technical textiles and China's SAMR enforcement of updated GB standards are reshaping sourcing toward localized Martindale and rotary testing capacity in South Asia. Specialized abradant supply chains draw from Germany and Japan, creating input dependencies for standardized test consumables. Single-source vulnerability concentrates in precision load cell and sensor modules tethered to Japanese and German component suppliers. Distribution runs through equipment distributors with captive service networks in manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around laboratories holding multi-standard accreditation as REACH substance restrictions and GB standards tightening force smaller testing facilities into outsourcing relationships.
For Market Incumbents: Extend firmware upgrade pathways and lifecycle support contracts to anchor 15-20 year customer retention against emerging digital automation specialists. Secure backward integration into specialized abradant manufacturing to defend margin position from input cost volatility. Consolidate testing relationships with Stuttgart and Wolfsburg corridor Tier-1 suppliers responding to ECHA mandates. For New Entrants and Emerging Players: Enter via India's PLI-supported technical textile zones where localized Martindale testing capacity lags manufacturing investment. Target Bangladesh garment testing expansion and Gujarat manufacturing clusters where BIS certification requirements are extending to interior material durability. Pursue cost-engineered digital variants with robotic sample handling as the go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with digital automation specialists given convergence of physical abrasion testing with predictive wear modeling enabling remote certification workflows. Long-term viability favors vendors with multi-protocol flexibility engineering and established accreditation relationships. Watch for inflection when OEM procurement functions unbundle after-sales service contracts from initial capital purchases.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Platform Development | Engineering single-platform flexibility for ASTM, ISO, and GB variants captures laboratory consolidation demand. |
| Digital Twin Integration | Convergence with predictive wear modeling enables remote certification workflows for distributed automotive supply chains. |
| Backward Integration into Abradants | In-house production of specialized consumables defends margins from German and Japanese supply concentration. |
| Service Contract Unbundling | Separating lifecycle support from capital purchases aligns with consolidated procurement functions at major OEMs. |
| Accreditation Consolidation | Multi-standard laboratory certification captures Tier-1 supplier outsourcing from REACH and GB compliance pressures. |
Methodological Framework
Independent corroboration across equipment vendor sales directors, laboratory quality managers, and automotive Tier-1 procurement leads underwrites the qualitative findings. Primary interviews with textile certification body technical directors, polymer R&D scientists at German technical universities, and aftermarket service heads at established distributors combined with secondary validation from customs/trade data, SEC filings of listed testing equipment manufacturers, and SAMR GB standards documentation. Bottom-up equipment placement estimates and top-down market sizing triangulate across the analysis window.
Rate-of-change decomposition separates volume expansion in manual configurations from value capture in automated digital systems across product type, technology tier, end-use vertical, and application purpose dimensions. CAGRs derive from modeled replacement cycle compression and technology migration curves. Forecast inputs incorporate polyurethane foam laminate protocol recalibration timelines and India's PLI scheme disbursement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden REACH substance restriction amendments or abrupt GB standards revision. Forecasts reflect assumptions regarding OEM validation timeline compression and technician cohort retirement rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Water Test Kits Market
Testing Equipment
Fugitive Emissions Detection and Quantification Test Systems Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Water Testing Equipment Market
Testing Equipment
China Material Testing Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Pitting Machines Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
Electrical Testing Equipment Market
Testing Equipment
Stack Emissions Real-Time Speciation and Compliance Test Systems Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Chemical Testing Services Market