
 Drop Weight Tear Tester Market | 2026-2036
Drop Weight Tear Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Drop Weight Tear Tester Market Foresight
Automotive chassis validation is recalibrating demand patterns for drop weight tear testers as OEMs shift toward advanced high-strength steel grades. MTS Systems Corporation leverages electromechanical platform expertise to dominate North American automotive testing lanes. ZwickRoell anchors European demand through precision instrumentation aligned with DIN EN ISO 148-1 protocols. Instron competes across research institutions with modular frame configurations suited to multi-material programs.
A drop weight tear tester measures fracture toughness by subjecting a notched specimen to impact from a falling mass, typically recording energy absorption in joules at specified temperatures. The device operates through a guided tup assembly with striker velocities calibrated to standards such as API RP 5L3, generating shear area percentages that determine pipeline steel qualification. Automated product types lead capital expenditure flows as laboratories pursue throughput gains and operator-repeatability improvements. Electromechanical technology occupies the fastest-expanding segment, displacing hydraulic alternatives in facilities prioritizing energy efficiency and reduced maintenance cycles. Compliance testing applications sustain premium pricing due to mandatory third-party verification requirements in oil and gas infrastructure procurement.
The American Petroleum Institute governs fracture toughness protocols for line pipe steels through API 5L3, directly conditioning tester specifications purchased by US-based energy service companies. ISO standards, including ISO 3183 and ISO 148-1, shape European and Asian procurement templates, creating certification barriers for equipment lacking accredited calibration traceability. ASTM E436 governs drop weight test methods for ferritic steels in North American laboratories, influencing instrument configuration requirements. Stakeholders must monitor evolving API and ISO harmonization discussions, as divergence between regional standards would fragment equipment compatibility and complicate multinational testing operations.
Market Dynamics
The transition from hydraulic to electromechanical testing platforms is restructuring capital allocation across materials laboratories, compressing maintenance budgets while elevating throughput requirements.
Growth Catalysts
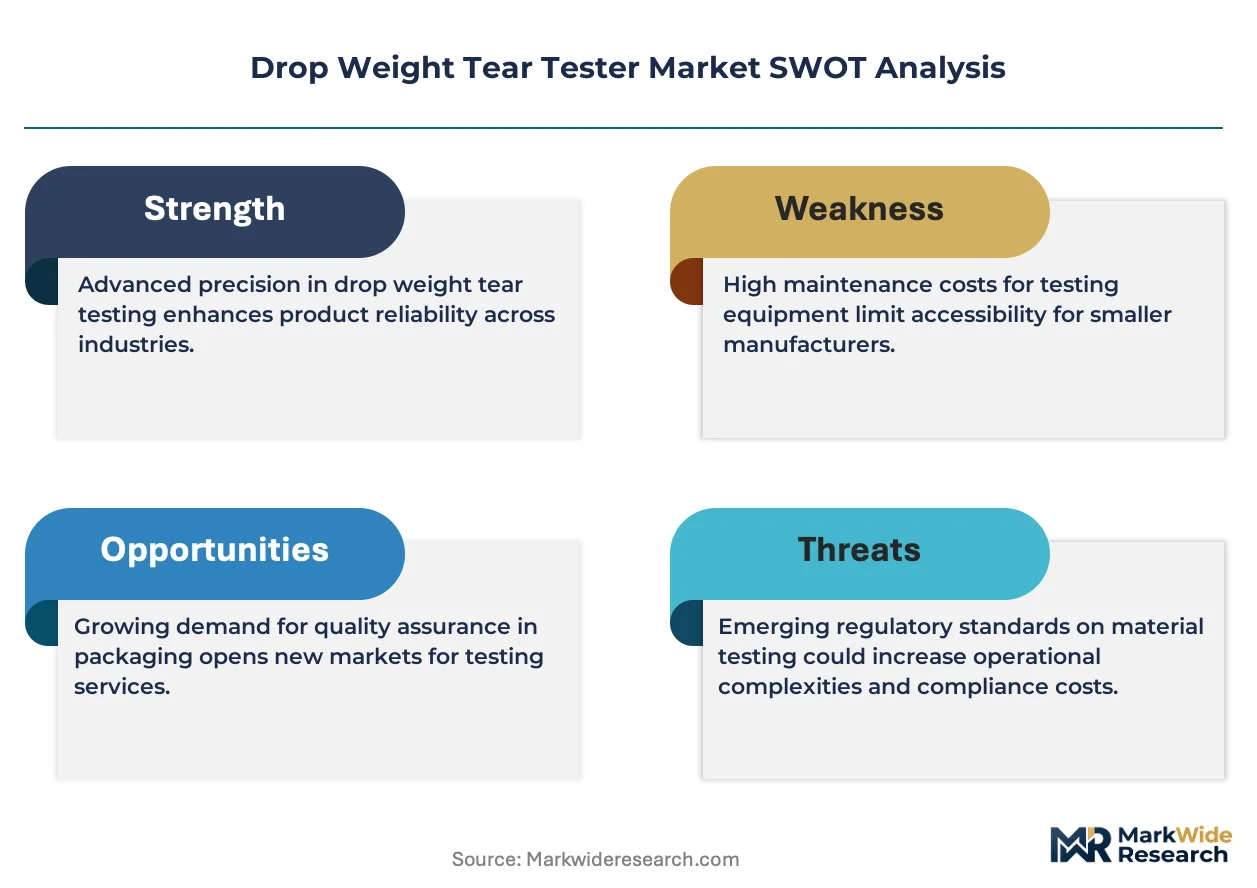
- API 5L3 Pipeline Mandates:Fracture toughness verification requirements for line pipe steels in US energy infrastructure are expanding testing volumes at third-party certification facilities.
- Automotive Lightweighting:OEM chassis programs deploying advanced high-strength steels require validated shear-area data for crashworthiness compliance.
- China:Domestic steel producers scaling API-grade line pipe exports are importing calibrated drop weight systems to meet international buyer audit requirements.
Market Restraints
- Electromechanical Component Costs:Precision load cells and servo motors carry 40-60% premium over hydraulic equivalents, extending payback periods for mid-size laboratories.
- German Precision Instrument Concentration:Critical sensor and calibration source supply chains cluster in Baden-Württemberg and Bavaria, creating single-region exposure.
- Charpy Test Substitution:Simpler pendulum impact methods retain preference in low-specification construction steel screening, limiting addressable market expansion.
Strategic Opportunities
- India:BIS certification expansion for structural steels in infrastructure projects is generating first-time demand from domestic metallurgical laboratories.
- Battery Housing Materials:EV manufacturers require fracture toughness validation for aluminum-steel hybrid enclosures, opening adjacent testing protocols.
- ISO 148-1 Harmonization:Convergence with DIN EN standards is reducing equipment re-certification costs for multi-national laboratory networks.
Industry Challenges
- Metallurgical Technician Scarcity:Specialized skills for specimen preparation and shear-area interpretation are concentrating in aging workforce cohorts across US Gulf Coast energy corridors.
- Multi-Standard Calibration Burden:Simultaneous API 5L3, ISO 3183, and ASTM E436 compliance requires redundant verification cycles, consuming 15-20% of annual equipment uptime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drop Weight Tear Tester Market |
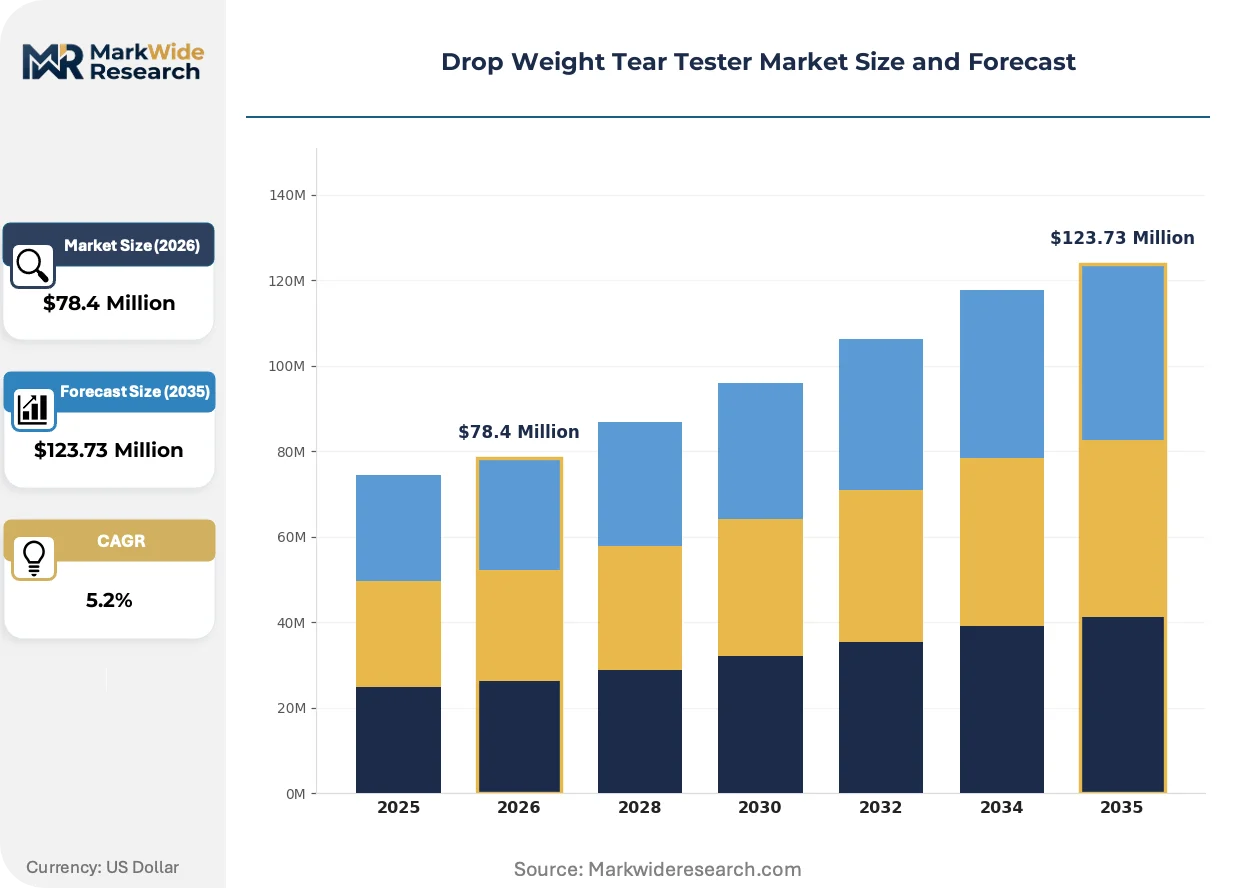
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $123.73 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automated, Digital, Hybrid End User: Plastics Industry, Aerospace, Automotive, Research Institutions Technology: Electromechanical, Pneumatic, Hydraulic, Mechanical Application: Material Testing, Quality Control, Product Development, Compliance Testing |
| Companies Covered | MTS Systems Corporation, Qualitest, Torontech, Imatek, Tinius Olsen, HUALONG, TÜV Rheinland, Instron, ZwickRoell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drop Weight Tear Tester Market Shifts & Advancements
Instrumentation architecture is pivoting toward integrated data ecosystems, collapsing the boundary between raw impact measurement and predictive material modeling.
Electromechanical tup assemblies with real-time velocity feedback are electrifying laboratory workflows, replacing hydraulic power units with brushless servo drives. Tier-1 automotive suppliers in Germany and Japan are adopting these platforms for 24-hour validation cycles. The shift is compressing facility energy footprints by half while eliminating hydraulic fluid handling protocols.
REACH substance restrictions on legacy hydraulic fluids are accelerating equipment replacement timelines across European testing facilities. The regulation forces retirement of oil-based systems ahead of technical obsolescence. Laboratories in the Netherlands and Belgium are prioritizing electromechanical platforms to preempt compliance deadlines.
Consolidated procurement by multi-site steel producers is disintermediating traditional distributor channels. ArcelorMittal and POSCO are negotiating direct service contracts with equipment manufacturers, bundling calibration and software updates across national laboratory networks. This concentration is most pronounced in South Korea and eastern China, where integrated steel complexes operate captive testing facilities.
Drop Weight Tear Tester Market Segmentation
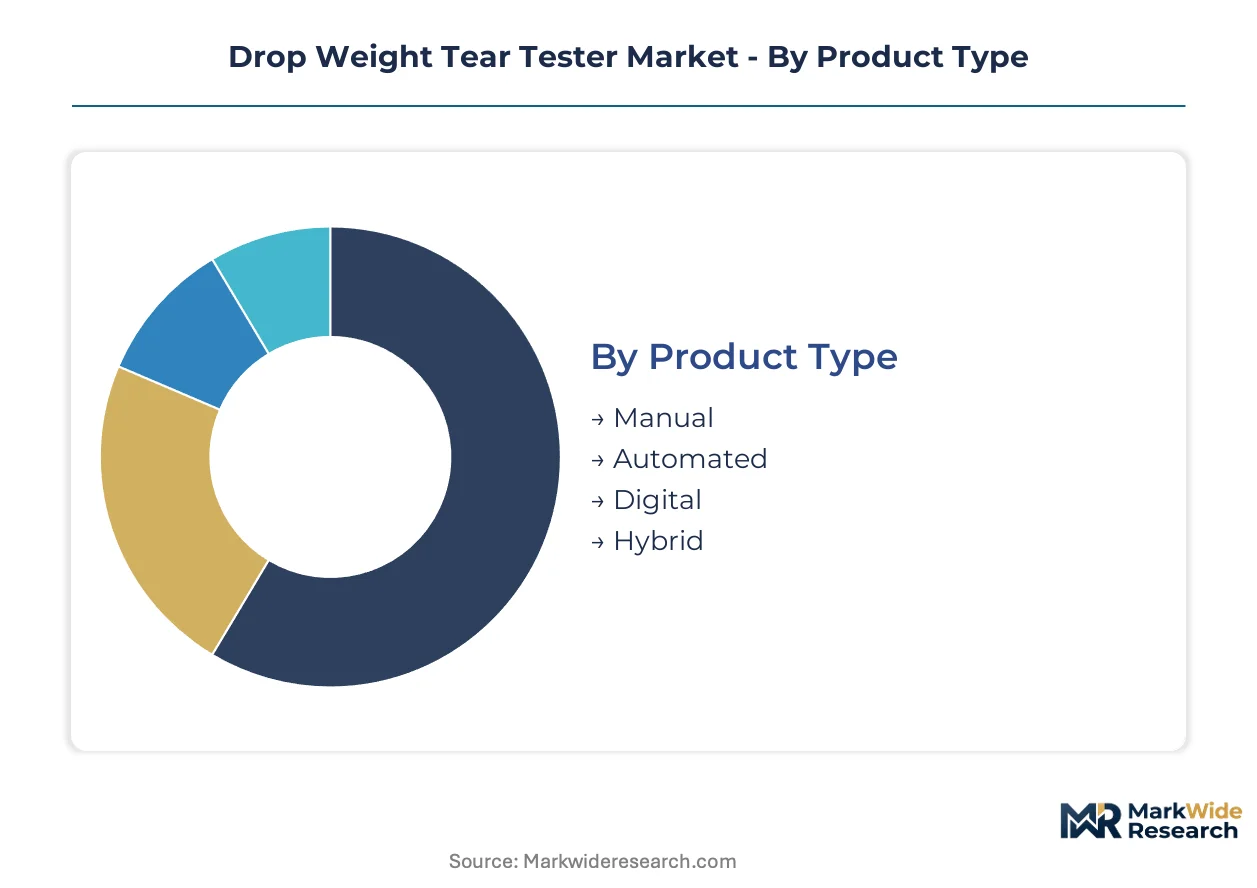
Drop weight tear tester procurement patterns diverge sharply across product configurations and end-use requirements. Laboratory capital budgets, regulatory compliance mandates, and throughput demands create distinct segment boundaries that reshape vendor positioning.
Product Type:
Equipment replacement cycles now favor platforms that reduce operator dependency and compress certification turnaround times.
- Automated:Robotic specimen handling and integrated shear-area calculation software eliminate manual measurement variability. Demand clusters at third-party certification laboratories serving US pipeline operators under API 5L3 mandates.
- Digital:Real-time data acquisition with cloud-connected calibration logging satisfies multinational steel producers auditing distributed laboratory networks. POSCO and ArcelorMittal specify these platforms for cross-facility standardization.
- Manual:Entry-level configurations persist in academic metallurgy departments with constrained capital allocations.
- Hybrid:Semi-automated systems blend pneumatic specimen clamping with manual tup release for mid-size testing volumes.
Volume placements concentrate in Automated; the faster expansion belongs to Digital.
End User:
Customer technical sophistication and regulatory exposure determine pricing tolerance and service contract structures.
- Automotive:OEM chassis validation programs require shear-area data at multiple temperatures for advanced high-strength steel qualification. German and Japanese Tier-1 suppliers operate 24-hour testing cycles.
- Research Institutions:Modular frame configurations accommodate multi-material programs spanning steels, aluminum alloys, and polymer composites. Instron dominates this segment with reconfigurable instrumentation.
- Plastics Industry:Polymer pipe manufacturers adopt modified drop weight protocols for impact resistance screening.
- Aerospace:Titanium and aluminum-lithium fracture toughness programs at US and French airframe suppliers generate specialized high-velocity tup requirements.
Automotive generates the highest equipment throughput; Research Institutions show the steepest expansion trajectory as materials science funding diversifies.
Technology:
Energy efficiency regulations and maintenance cost pressures are restructuring platform preferences across laboratory networks.
- Electromechanical:Brushless servo drives with real-time velocity feedback displace hydraulic alternatives. REACH substance restrictions on legacy hydraulic fluids accelerate European replacement timelines in the Netherlands and Belgium.
- Hydraulic:High-energy applications for thick-walled pipeline steels retain installed base in US Gulf Coast energy corridors.
- Pneumatic:Specimen clamping and release mechanisms supplement primary drive systems in hybrid configurations.
- Mechanical:Gravity-driven systems with fixed mass assemblies persist in educational settings.
Electromechanical platforms command premium positioning; Hydraulic maintains residual share in energy-sector captive laboratories.
Application:
Regulatory verification requirements create non-discretionary demand streams that sustain pricing power through economic cycles.
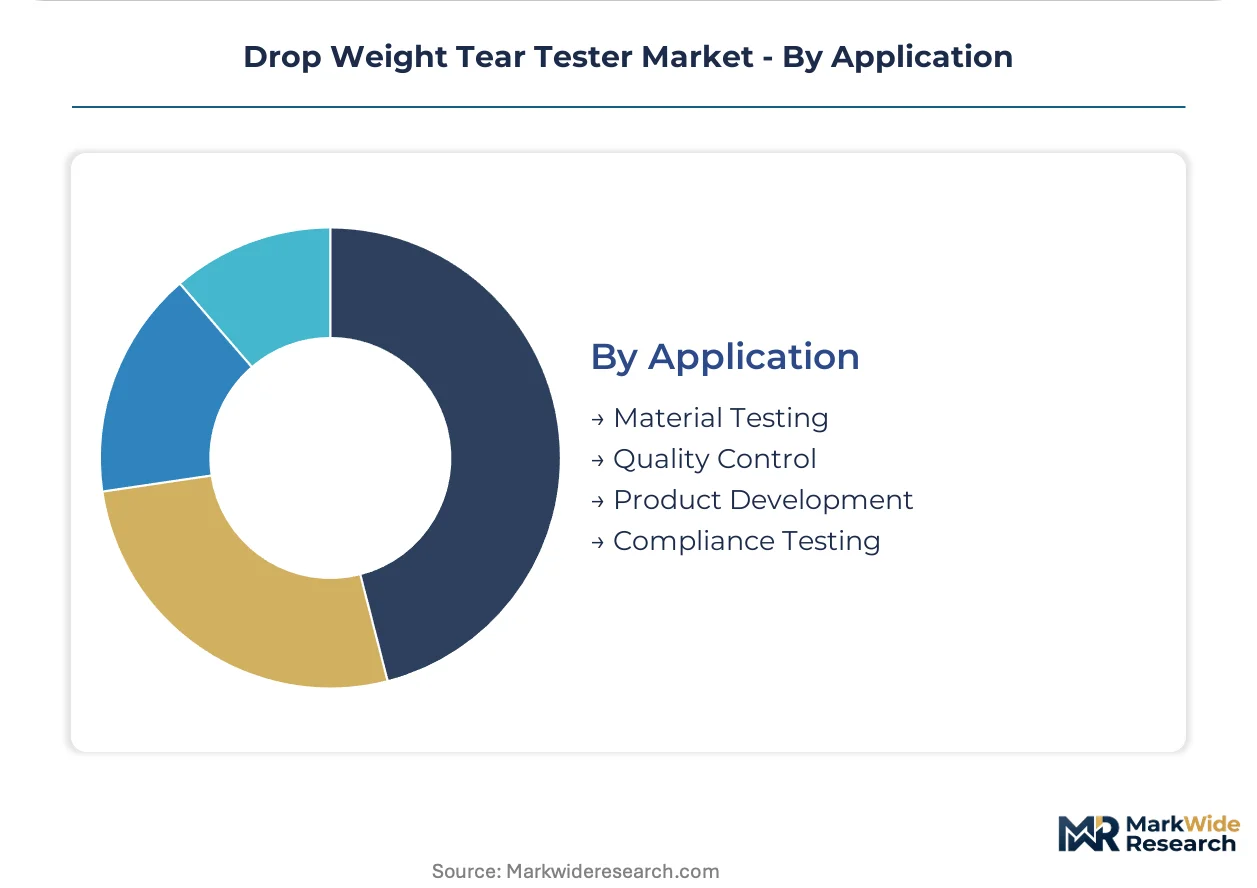
- Compliance Testing:Mandatory third-party verification for API 5L3 and ISO 3183 pipeline steel procurement sustains premium equipment configurations. US energy infrastructure expansion elevates testing volumes at accredited facilities.
- Quality Control:Integrated steel complexes in South Korea and eastern China operate captive laboratories with direct manufacturer service contracts.
- Material Testing:Standardized fracture toughness characterization supports alloy development programs.
- Product Development:EV battery housing manufacturers require fracture validation for aluminum-steel hybrid enclosures.
Compliance Testing anchors revenue stability; Product Development is gaining share fastest as automotive electrification accelerates materials qualification demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and China, while consumption concentrates in US energy corridors and Japanese automotive testing lanes. This geographic split creates equipment trade flows calibrated to divergent regulatory specifications.
United States
API 5L3 pipeline mandates drive third-party certification demand at Gulf Coast testing facilities. FERC infrastructure approvals require fracture toughness verification for line pipe steels. Houston and New Orleans host concentrated laboratory networks serving Permian Basin operators.
Germany
Automotive OEM chassis programs require shear-area validation for advanced high-strength steels. REACH substance restrictions accelerate hydraulic system replacement in Baden-Württemberg laboratories. Stuttgart and Munich anchor precision instrumentation supply chains for European markets.
China
Domestic steel producers scaling API-grade exports import calibrated systems for international buyer audits. GB standards alignment with ISO 3183 shapes procurement templates. Shanghai and eastern steel complexes operate captive testing facilities with direct manufacturer contracts.
Japan
METI industrial standards govern fracture toughness protocols for automotive and pipeline applications. Tier-1 suppliers operate 24-hour validation cycles for high-strength steel qualification. Nagoya and Osaka industrial corridors concentrate electromechanical platform adoption.
South Korea
POSCO and integrated steel producers negotiate direct service contracts across national laboratory networks. MFDS-equivalent industrial standards shape equipment specifications. Busan-Ulsan steel complexes drive consolidated procurement for multi-site standardization.
Drop Weight Tear Tester Market Competitive Landscape
Top-tier vendors anchor premium instrumentation tiers, while regional fabricators and certification service providers occupy mid-market and service-overlay positions. The structure consolidates around electromechanical platform expertise and accredited calibration capabilities. Strategic archetypes include precision instrumentation specialists, integrated testing service conglomerates, and emerging Asian equipment fabricators. Dominant competitive moves encompass direct manufacturer contracting with multi-site steel producers and technology licensing for servo-drive architectures.
Among US-based precision instrumentation developers, MTS Systems Corporation and Instron occupy positions exemplifying electromechanical platform dominance. German GmbH-structured specialists ZwickRoell and TÜV Rheinland represent European precision and certification service archetypes respectively. Chinese Co., Ltd. fabricators including HUALONG exemplify cost-competitive positioning for emerging market laboratory procurement.
| Leading Market Players |
|---|
| MTS Systems Corporation |
| Qualitest |
| Torontech |
| Imatek |
| Tinius Olsen |
| HUALONG |
| TÜV Rheinland |
| Instron |
| ZwickRoell |
| Others |
Supply & Pricing Matrix
Precision load cells and servo motors from Baden-Württemberg suppliers cascade through three distinct pricing tiers, with electromechanical platform costs determining downstream equipment quotations for laboratories in Houston, Stuttgart, and Shanghai.
Pricing Analysis
Margin tightening in mid-size laboratory equipment traces to electromechanical component premiums that extend payback periods against hydraulic alternatives. Three-tier pricing structure across premium, standard, and economy levels separates API 5L3-certified automated platforms from digital configurations and manual academic units. Certification grade and after-sales service bundling drive price differentiation. Cost compression in economy tiers accelerates because Chinese fabricators enter with calibrated systems for domestic steel export audits. Academic metallurgy departments exhibit highest price sensitivity; third-party certification facilities serving FERC-mandated pipeline testing show lowest.
Supply Chain Analysis
Refurbishment flows for hydraulic power units are accelerating in European facilities ahead of REACH substance restriction deadlines, creating secondary equipment channels that compete with new electromechanical platforms. Component manufacturing concentrates in Germany, China, and Japan. Brushless servo drives and precision load cells draw from specialized machine shops in Stuttgart and Munich, while frame fabrication feeds from Chinese steel complexes. Single-source vulnerability in Baden-Württemberg sensor supply creates concentration risk. Distribution runs through direct manufacturer contracts with multi-site steel producers, disintermediating traditional laboratory equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH regulations and API 5L3 calibration requirements force smaller fabricators toward exit or acquisition.
For Market Incumbents: Deepen backward integration into precision load cell manufacturing to reduce exposure to Baden-Württemberg supply concentration. Anchor certification investment in multi-standard calibration capabilities spanning API 5L3, ISO 3183, and ASTM E436 to defend against emerging Asian competitors with single-standard offerings. Charpy test substitution in construction steel screening remains a persistent threat to addressable market expansion. For New Entrants and Emerging Players: Begin with battery housing materials testing for EV manufacturers, where fracture toughness validation for aluminum-steel hybrid enclosures remains underpenetrated. Target Indian metallurgical laboratories facing first-time BIS certification requirements for structural steels. A calibration-service-first go-to-market angle bypasses capital-intensive equipment manufacturing while building accredited laboratory relationships. For Investors and Strategic Acquirers: Direct manufacturer contracting announcements from POSCO or ArcelorMittal are the leading indicator that multi-site standardization demand is accelerating consolidation timing. Long-term viability favors precision instrumentation specialists with accredited calibration traceability and electromechanical platform expertise over hydraulic legacy holders. Target acquisition archetype: mid-cap European firms with DIN EN ISO 148-1 certification depth and established automotive OEM relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Platform Migration | REACH substance restrictions on hydraulic fluids force accelerated replacement timelines across European testing facilities. |
| Multi-Standard Calibration Investment | Simultaneous API 5L3, ISO 3183, and ASTM E436 compliance reduces redundant verification cycles consuming equipment uptime. |
| Direct Manufacturer Contracting | ArcelorMittal and POSCO negotiate bundled service agreements across national laboratory networks, disintermediating distributors. |
| Battery Housing Materials Protocol Development | EV manufacturers require fracture toughness validation for aluminum-steel hybrid enclosures, opening adjacent testing applications. |
| Indian BIS Certification Expansion | Domestic metallurgical laboratories generate first-time demand for structural steel testing infrastructure. |
Research Methodology
Document review covered API 5L3 and ISO 3183 regulatory filings, ASTM E436 test method documentation, and steel producer procurement disclosures, complemented by interviews with laboratory directors at third-party certification facilities, maintenance directors at integrated steel complexes, OEM platform engineers at Tier 1 automotive suppliers, and aftermarket service heads at precision instrumentation vendors. Secondary validation drew from FERC infrastructure approval records, REACH substance restriction updates, and customs data on electromechanical component trade flows. Bottom-up equipment shipment analysis triangulated against top-down steel production and pipeline construction forecasts.
Historical electromechanical adoption curves were cross-referenced against panel input from equipment procurement officers to model technology transition timing across the analysis window. Segmentation dimensions included product type automation level, end-user industry vertical, technology platform, and application purpose. CAGRs were derived from installed base replacement cycles and new facility commissioning rates. Industry-specific inputs incorporated API-grade line pipe export volumes and automotive high-strength steel content trajectories.
Underlying measurement precision varies by segment; automated and digital configurations carry tighter precision than manual academic units due to standardized calibration protocols. Forecasts reflect assumptions about regulatory harmonization progress and electromechanical cost curve trajectories. Practitioners should monitor REACH enforcement timelines and API-ISO standard convergence discussions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
Material Testing Market
Testing Equipment
Durometers Market