
 Combustion Testing Equipment Market | 2026-2036
Combustion Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Combustion Testing Equipment Market Analysis
Direct-to-plant distribution is rewriting how combustion testing equipment reaches end users. Emerson Electric leverages its field service network to sustain long-term calibration contracts with power utilities. ABB Measurement & Analytics anchors European demand through its gas analyzer portfolio. Testo competes on portable instrument specialization for HVAC and industrial maintenance crews.
Combustion testing equipment encompasses instruments that measure flue gas composition, thermal efficiency, and pollutant concentrations using electrochemical cells, infrared absorption, or chemiluminescence detectors to ensure safe and compliant fuel-burning processes. Gas analyzers occupy the largest product category due to universal deployment across boiler and engine applications. Infrared technology leads the technology segment for its non-dispersive measurement stability, while mass spectrometry commands premium positioning in research laboratory settings. Environmental agencies represent a concentrated end-user segment where compliance monitoring mandates drive replacement cycles.
EPA emission standards and EU Green Deal carbon reduction frameworks shape product certification requirements across North America and Europe. China's MEE enforces parallel GB standards for stationary source monitoring, creating a three-zone regulatory map for manufacturers. Stakeholders must track evolving mercury and particulate matter thresholds to align R&D roadmaps with enforcement timelines.
Market Dynamics
EPA emission standards and EU Green Deal carbon reduction frameworks are compressing replacement cycles for combustion testing equipment as utilities face mandatory upgrades to meet tightening mercury and particulate matter thresholds.
Growth Catalysts
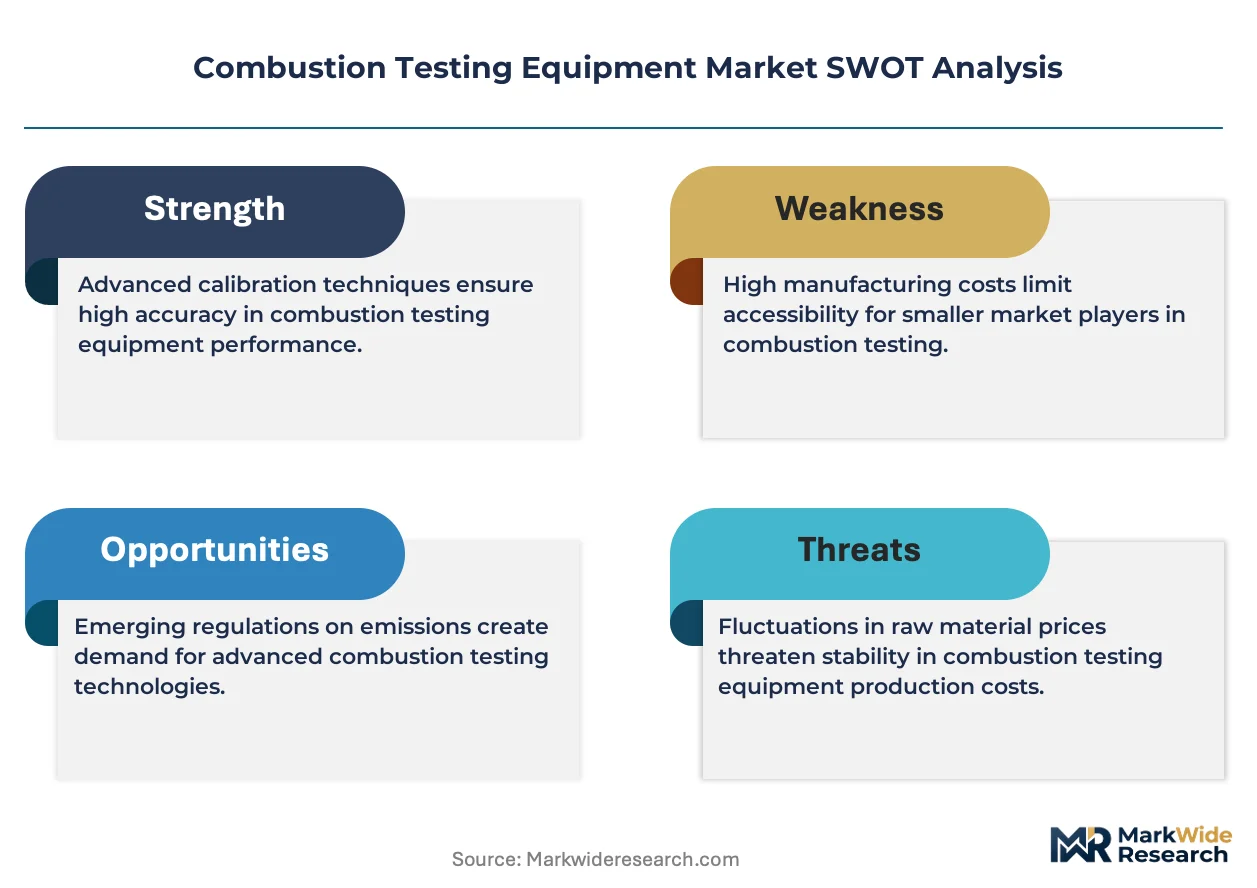
- EPA Stationary Source Monitoring:US power utilities must deploy continuous emissions monitoring systems under Clean Air Act amendments, forcing systematic analyzer procurement.
- Industrial Boiler Efficiency Mandates:China's GB standards for thermal efficiency testing drive replacement of legacy flue gas analyzers in manufacturing clusters.
- Infrared Absorption Technology:Non-dispersive infrared measurement stability reduces calibration frequency, lowering total cost of ownership for plant operators.
Market Restraints
- Sensor Material Cost Volatility:Electrochemical cell production depends on platinum group metal supply concentrated in South Africa and Russia.
- Technical Limitation in High-Temperature Sampling:Probe degradation above 600°C restricts direct measurement in cement kiln and glass furnace applications.
- REACH Compliance Burden:EU chemical substance registration requirements extend certification timelines for new analyzer chemistries by 12-18 months.
Strategic Opportunities
- Hydrogen Fuel Testing Infrastructure:Ammonia and hydrogen co-firing trials in Japanese power plants create demand for modified gas analyzer configurations.
- Remote Calibration Services:Cloud-connected analyzer networks enable predictive maintenance contracts, shifting revenue from hardware to recurring service streams.
- EU Carbon Border Adjustment Mechanism:Import emissions verification requirements extend combustion testing demand to steel and aluminum exporters outside Europe.
Industry Challenges
- Cross-Disciplinary Skill Scarcity:Field service engineers must combine combustion chemistry knowledge with IoT diagnostics training.
- Multi-Jurisdiction Certification Complexity:Simultaneous EPA, TÜV, and MEE approval processes fragment R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combustion Testing Equipment Market |
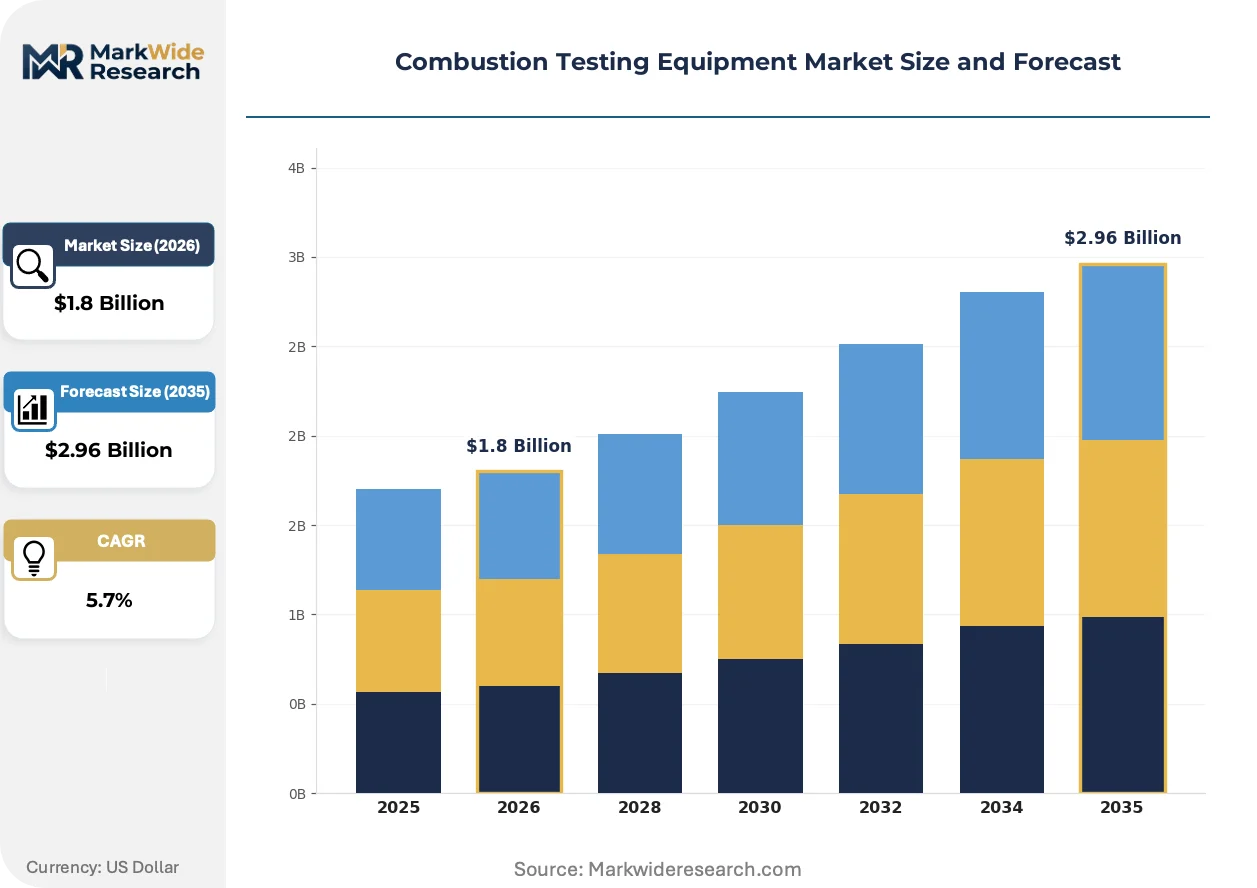
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Analyzers, Emissions Monitors, Test Chambers, Calorimeters Technology: Infrared, Chemiluminescence, Mass Spectrometry, Thermogravimetric End User: Research Laboratories, Manufacturing Plants, Environmental Agencies, Automotive Industry Application: Fuel Analysis, Emissions Testing, Performance Assessment, Compliance Monitoring |
| Companies Covered | General Electric, AMETEK Process Instruments, Emerson Electric, Drägerwerk, ABB Measurement & Analytics, Testo, Honeywell International, Bacharach, Nova Analytical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combustion Testing Equipment Market Emerging Trajectories
Digital twin architectures and predictive analytics are rewriting how combustion testing data generates value, shifting equipment vendors toward software-anchored service models.
Digital twin platforms for combustion system modeling are virtualizing traditional stack testing protocols. Power generation operators deploy virtual sensors to interpolate between physical analyzer readings, reducing probe count in large boiler arrays. Equipment suppliers now bundle simulation licenses with hardware contracts, compressing the addressable market for standalone portable analyzers.
EU F-Gas Regulation phase-down schedules are accelerating infrared detector technology transitions. Manufacturers must eliminate sulfur hexafluoride and perfluorocarbon reference gases from calibration procedures. Gas analyzer product lines face redesign cycles to accommodate nitrogen-filled or evacuated optical benches, with German TÜV certification becoming the de facto gate for European market access.
Power utility procurement departments now unbundle calibration service contracts from initial equipment purchases. Third-party metrology laboratories compete directly with manufacturer service networks for annual recertification business. This pattern concentrates in the United States where independent stack testing firms hold EPA contractor qualifications that plant operators trust for regulatory defense documentation.
Combustion Testing Equipment Market Segmentation
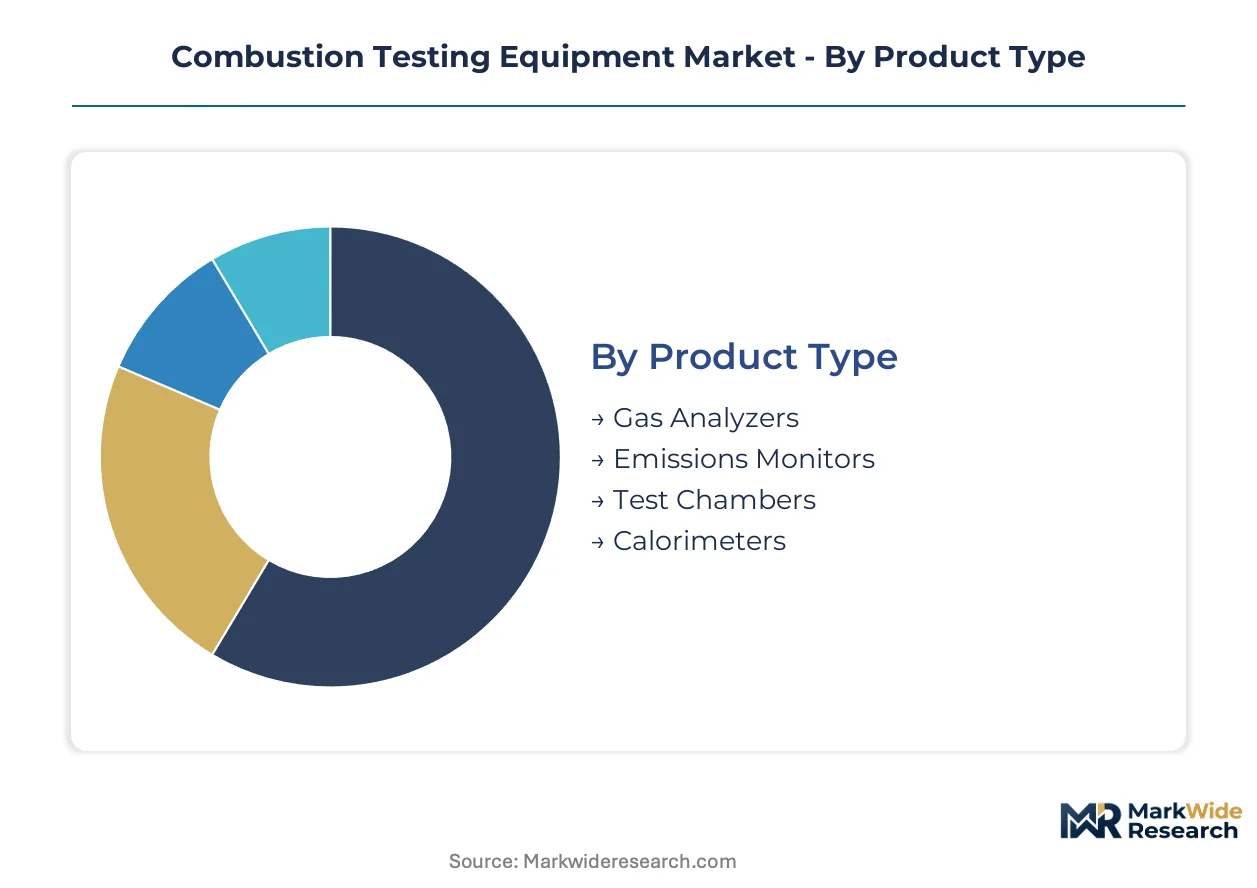
Segmentation in combustion testing equipment reveals how regulatory pressure and fuel diversification reshape procurement priorities across distinct technical and operational contexts. Equipment specifications diverge sharply between continuous stack monitoring and intermittent laboratory validation.
Product Type:
End-use spectrum spans permanent installation at power stations through portable field diagnostics for maintenance crews.
- Gas Analyzers:These instruments measure flue gas composition through electrochemical cells or optical benches to quantify oxygen, carbon monoxide, and nitrogen oxide concentrations. Power generation utilities in the United States deploy them under EPA Clean Air Act mandates for continuous emissions monitoring. Procurement concentrates where regulatory enforcement is strictest.
- Emissions Monitors:Stationary systems integrate multiple sensor technologies to track particulate matter, mercury, and sulfur dioxide outputs from industrial combustion sources. Manufacturing plants in Germany face EU Green Deal thresholds that compress replacement cycles for legacy analyzer installations.
- Test Chambers:Controlled-environment enclosures simulate combustion conditions for R&D validation and quality assurance protocols.
- Calorimeters:Precision instruments quantify heat release rates during fuel characterization and thermal efficiency certification.
The dominant share belongs to Gas Analyzers, while Emissions Monitors is closing the gap fastest.
Technology:
Cost-to-accuracy ratios separate laboratory-grade precision from field-deployable durability.
- Infrared:Non-dispersive infrared absorption delivers measurement stability with reduced calibration frequency, lowering total cost of ownership for plant operators running continuous monitoring programs. Cement and steel producers favor this technology for its tolerance of particulate-laden sample streams.
- Chemiluminescence:Nitric oxide detection through ozone reaction achieves parts-per-billion sensitivity required for ultra-low emissions verification. Research laboratories in Japan deploy these analyzers for hydrogen co-firing trial validation.
- Mass Spectrometry:High-resolution molecular identification commands premium positioning in academic and government research settings.
- Thermogravimetric:Combined thermal and gravimetric analysis supports fuel characterization and catalyst degradation studies.
Infrared holds the installed base advantage, though Chemiluminescence is expanding most quickly as mercury and NOx thresholds tighten.
End User:
Customer type determines specification rigor, procurement volume, and service contract structure.
- Research Laboratories:Academic and government facilities demand multi-species detection capability and traceable calibration chains for peer-reviewed publication standards. China's national research institutes drive demand for mass spectrometry configurations aligned with GB standard development.
- Manufacturing Plants:Industrial boiler operators prioritize ruggedized portable units for periodic efficiency audits and troubleshooting. Procurement in the United States favors third-party calibration services unbundled from hardware purchases.
- Environmental Agencies:Regulatory enforcement bodies specify reference-grade instrumentation for compliance verification and penalty documentation.
- Automotive Industry:Engine test cell operators require rapid-response analyzers for development-cycle emissions mapping.
Manufacturing Plants command the volume lead, while Environmental Agencies are gaining share fastest as enforcement staffing expands.
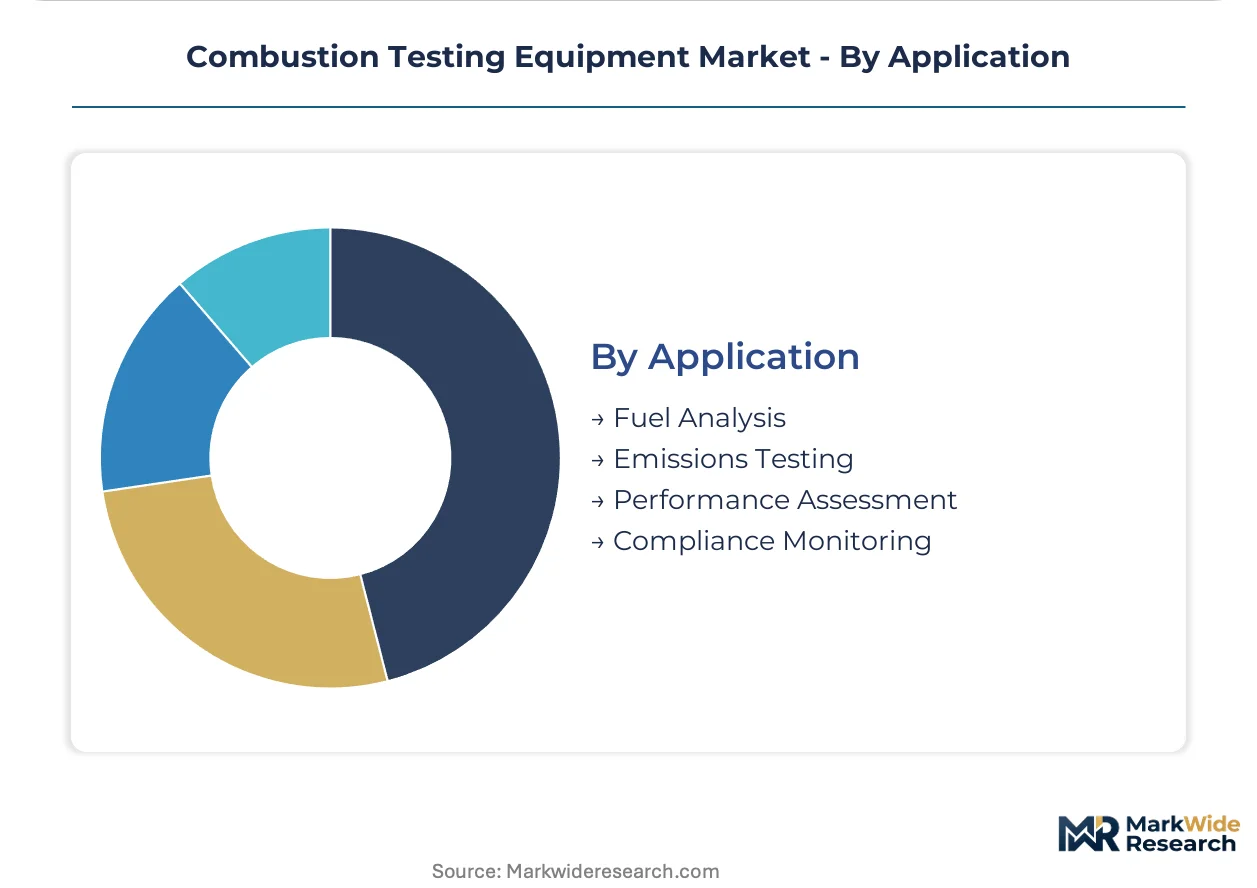
Application:
Functional purpose segments align with distinct regulatory timelines and technical performance requirements.
- Fuel Analysis:Characterization of heating value, ash content, and combustion kinetics supports procurement decisions and burner tuning. Ammonia and hydrogen co-firing trials in Japanese power plants create demand for modified analyzer configurations handling non-traditional fuel matrices.
- Emissions Testing:Quantification of regulated pollutants against permit limits drives replacement of pre-2015 analyzer generations. China's MEE enforcement of stationary source standards accelerates upgrades in manufacturing clusters.
- Performance Assessment:Thermal efficiency measurement and heat rate optimization support operational cost reduction initiatives.
- Compliance Monitoring:Continuous regulatory reporting systems require hardened installations with automated data transmission to enforcement databases.
Emissions Testing anchors current revenue, yet Fuel Analysis is climbing the fastest as hydrogen infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central European distribution efficiency for combustion testing equipment manufacturers serving thermal power and industrial boiler operators across the continent.
United States
Power utility procurement of continuous emissions monitoring systems concentrates in the Ohio River Valley and Texas Gulf Coast refining corridors. EPA Clean Air Act amendments mandate systematic analyzer upgrades at coal and natural gas facilities. Houston and Pittsburgh host dense clusters of stack testing contractors holding federal contractor qualifications for regulatory defense documentation.
Germany
Industrial boiler operators in the Ruhr manufacturing belt face compressed replacement cycles under EU Green Deal mercury and particulate thresholds. TÜV certification serves as the de facto gate for European market access. Stuttgart and Munich anchor demand for portable flue gas analyzers serving automotive supplier foundries and HVAC maintenance networks.
China
Manufacturing clusters in the Yangtze River Delta and Pearl River Delta drive thermal efficiency testing equipment procurement under GB standards enforcement. MEE stationary source monitoring mandates accelerate upgrades in Jiangsu and Guangdong provinces. Shanghai and Shenzhen host calibration service networks supporting third-party metrology competition.
Japan
Ammonia and hydrogen co-firing trials at thermal power stations in the Keihin industrial corridor create demand for modified gas analyzer configurations. METI funding for decarbonization pilot programs supports research laboratory instrumentation procurement. Nagoya and Osaka anchor automotive test cell operations requiring rapid-response emissions mapping capabilities.
India
Cement and steel producers in the Delhi-Mumbai Industrial Corridor deploy particulate-tolerant infrared analyzers for continuous stack monitoring. CEA thermal efficiency mandates for captive power plants drive flue gas analyzer replacement in Gujarat and Maharashtra. Ahmedabad and Mumbai host expanding third-party calibration service providers competing with manufacturer networks.
Combustion Testing Equipment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors and optical benches to multiple downstream brands. The vendor base stratifies across three tiers: diversified industrial conglomerates with field service networks, measurement technology pure-plays with calibration recurring revenue, and regional fabricators competing on portable instrument portability. Two dominant competitive moves are reshaping positioning: unbundling of calibration service contracts from hardware purchases, and bundling of digital twin simulation licenses with analyzer hardware contracts.
Among diversified industrial technology conglomerates, General Electric and Emerson Electric exemplify the platform-integrator archetype with sustained utility relationships. ABB Measurement & Analytics occupies a position anchoring European demand through gas analyzer portfolio breadth. Testo represents the portable-specialist archetype competing on field-deployable instrument form factors for HVAC and industrial maintenance crews.
| Leading Market Players |
|---|
| General Electric |
| AMETEK Process Instruments |
| Emerson Electric |
| Drägerwerk |
| ABB Measurement & Analytics |
| Testo |
| Honeywell International |
| Bacharach |
| Nova Analytical Systems |
| Others |
Supply Flow & Price Mechanics
The Ruhr industrial belt anchors platinum group metal refining capacity for electrochemical cell production, concentrating sensor material supply in a corridor where downstream pricing power shifts with South African and Russian export dynamics. Equipment manufacturers face margin compression when palladium and rhodium spot markets tighten, forcing tiered pricing adjustments across portable and stationary analyzer lines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates TÜV-certified reference-grade systems from field-portable units and unbundled sensor modules. Price differentiation hinges on calibration traceability chains and EPA contractor qualification status. Cost compression in the economy tier is intensifying because third-party metrology laboratories undercut manufacturer service networks for annual recertification contracts. Environmental agencies exhibit the lowest price sensitivity due to penalty documentation requirements, while HVAC maintenance crews in the United States drive volume through price-competitive portable instrument procurement.
Supply Chain Analysis
Supplier-financing facilities extended by German optical bench manufacturers ease working capital burdens for mid-tier analyzer assemblers facing 90-day payment cycles from power utility procurement departments. Component sourcing draws from China for infrared detector substrates, Germany for precision optical assemblies, and South Africa for platinum group metal feedstock. Single-source vulnerability concentrates in electrochemical cell membranes where patent-protected polymer formulations limit qualified suppliers. Distribution runs through direct-to-plant field service networks for continuous monitoring systems and industrial distributors for portable maintenance instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combustion testing equipment sits in early-cycle expansion as hydrogen co-firing trials across Japanese and European power stations create instrumentation retrofit demand before regulatory mandates harden. Penetration remains shallow in ammonia fuel testing configurations where modified analyzer specifications are still stabilizing.
For Market Incumbents: Harden calibration service contract retention against third-party metrology competition by embedding predictive maintenance algorithms that remote diagnostics enable. Deepen backward integration into electrochemical cell production to buffer platinum group metal cost volatility. Secure TÜV and MEE certification pre-approval for hydrogen-ready analyzer configurations before threshold tightening accelerates replacement cycles.
For New Entrants and Emerging Players: Establish a beachhead in portable flue gas analyzers for industrial boiler maintenance crews where brand loyalty to incumbents remains weakest. Target India's cement and steel corridor where CEA thermal efficiency mandates drive first-time analyzer procurement and local calibration infrastructure gaps create service attach opportunities. Lead with particulate-tolerant infrared technology priced below German imports.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates where combustion testing equipment represents non-core revenue within broader automation portfolios. The five-to-ten year viability window favors measurement technology pure-plays with recurring calibration revenue streams over hardware-only fabricators. Watch hydrogen infrastructure deployment rates in power generation as the inflection signal for modified analyzer configuration demand scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Remote Calibration Service Platform | Cloud-connected analyzer networks enable predictive maintenance contracts shifting revenue from hardware to recurring service streams. |
| Hydrogen-Ready Analyzer Certification | TÜV pre-approval for modified gas analyzer configurations positions vendors ahead of ammonia co-firing regulatory mandates. |
| Backward Integration into Sensor Production | In-house electrochemical cell manufacturing buffers margin pressure from platinum group metal supply concentration in South Africa. |
| Third-Party Metrology Acquisition | EPA-qualified stack testing firms in Houston and Pittsburgh provide regulatory defense documentation capabilities trusted by utility procurement. |
| Digital Twin Simulation Bundling | Virtual sensor licensing packaged with hardware contracts compresses the addressable market for standalone portable analyzers. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with plant engineers, maintenance directors, environmental compliance officers, and aftermarket service heads; and secondary validation through EPA enforcement databases, EU ETS emissions verification records, customs trade data for analyzer imports, and SEC filings from listed industrial technology conglomerates. Bottom-up and top-down triangulation cross-checked equipment shipment volumes against utility capital expenditure disclosures and manufacturing cluster emissions monitoring mandates.
Forecast inputs considered technology transitions across infrared, chemiluminescence, and mass spectrometry platforms; regulatory enforcement staffing expansion at environmental agencies; and hydrogen infrastructure deployment timelines across power generation applications. Segmentation dimensions modeled include product type, measurement technology, end-user category, and application purpose across the projection horizon. CAGRs were derived from replacement cycle compression analysis tied to mercury and particulate threshold tightening schedules.
Sensitivities concentrate around platinum group metal price volatility, REACH compliance timeline extensions for new analyzer chemistries, and hydrogen co-firing trial outcomes that could accelerate or delay modified configuration demand. Forecasts reflect assumptions about regulatory enforcement continuity and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Flammability Tester Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Corrosion Testing Services Market