
 Global Adsorption Equipment Market | 2026-2036
Global Adsorption Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adsorption Equipment Market Foresight
Buyer concentration across petrochemical facilities is restructuring procurement patterns for large-capacity adsorption systems. Evoqua leverages its installed base in water treatment to sustain recurring service revenue streams. Dürr AG anchors its position through deep specialization in solvent recovery applications for automotive coating operations. Munters competes in humidity-controlled environments where silica gel systems dominate pharmaceutical and food processing demand.
Adsorption equipment encompasses vessels engineered to separate target molecules from fluid streams using solid media with high surface area, typically operating at pressures from near-vacuum to elevated bar ranges depending on the swing cycle employed. The equipment serves primarily to capture contaminants, recover valuable solvents, or purify process streams in continuous industrial operations. Pressure swing adsorbers occupy the largest installed base due to decades of proven deployment in air separation and hydrogen purification, while metal-organic frameworks represent the fastest-growing technology category as material science advances unlock selective capture at lower energy intensity. Fixed bed adsorbers remain the mature workhorse for water treatment applications where activated carbon regeneration cycles align with predictable contaminant loading profiles.
The EPA enforces Maximum Achievable Control Technology standards that mandate adsorption-based volatile organic compound capture at major emitting facilities, while the EU F-Gas Regulation drives fluorinated gas recovery investments across European chemical plants. China's MEE implements increasingly stringent emission permits that require continuous monitoring and treatment upgrades at industrial zones in Jiangsu and Shandong provinces. Stakeholders must track how evolving carbon border adjustment mechanisms in the European Union and emerging clean production standards in India reshape equipment specification requirements and supplier qualification criteria.
Market Dynamics
The EPA's Maximum Achievable Control Technology standards and the EU F-Gas Regulation are forcing simultaneous equipment upgrades across petrochemical, automotive coating, and semiconductor fabrication facilities, compressing replacement cycles and elevating specification complexity for adsorption system vendors.
Growth Catalysts
- EPA MACT Standards:Tightened volatile organic compound emission limits under the Clean Air Act mandate adsorption-based capture systems at major emitting facilities, creating immediate replacement demand across US chemical plants and coating operations.
- Metal-Organic Frameworks:Advanced porous materials with tunable pore geometries are unlocking selective gas separation at reduced energy intensity, displacing conventional zeolites in hydrogen purification and carbon capture applications.
- Jiangsu and Shandong Clusters:China's Ministry of Ecology and Environment is implementing continuous emission monitoring mandates at industrial zones, compelling treatment infrastructure modernization across these concentrated manufacturing regions.
Market Restraints
- Activated Carbon Supply Concentration:High-quality coconut shell and coal-based activated carbon production concentrates in Southeast Asian and Chinese suppliers, exposing procurement to regional supply disruptions and input cost volatility.
- Zeolite Manufacturing Bottlenecks:Synthetic zeolite synthesis requires specialized aluminosilicate precursors and controlled thermal processing, limiting qualified supplier pools and extending lead times for pressure swing adsorber media replacement.
- Membrane Separation Substitution:Polymeric and ceramic membrane systems are capturing share in nitrogen generation and biogas upgrading applications where moderate purity requirements reduce the energy advantage of adsorption cycling.
Strategic Opportunities
- India's PLI-Linked Clean Production:Production-linked incentive schemes for specialty chemicals and pharmaceuticals are attracting capacity investments that require solvent recovery and emission control infrastructure at greenfield sites.
- Carbon Border Adjustment Mechanism:The EU's phased implementation of carbon tariffs on imported goods is pressuring exporters to document embedded emissions, creating demand for on-site carbon capture and verification-grade purification equipment.
- Modular Skid Packaging:Pre-engineered, containerized adsorption units are reducing field installation complexity and enabling rental or lease-based commercial models for mid-scale industrial gas users.
Industry Challenges
- Adsorbent Regeneration Expertise:Thermal and pressure swing regeneration protocols require specialized process engineering knowledge that remains scarce in regional service networks, constraining aftermarket revenue capture.
- Legacy Control System Integration:Brownfield facilities operate distributed control systems from prior decades, complicating digital instrumentation retrofits and real-time performance monitoring for predictive maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adsorption Equipment Market |
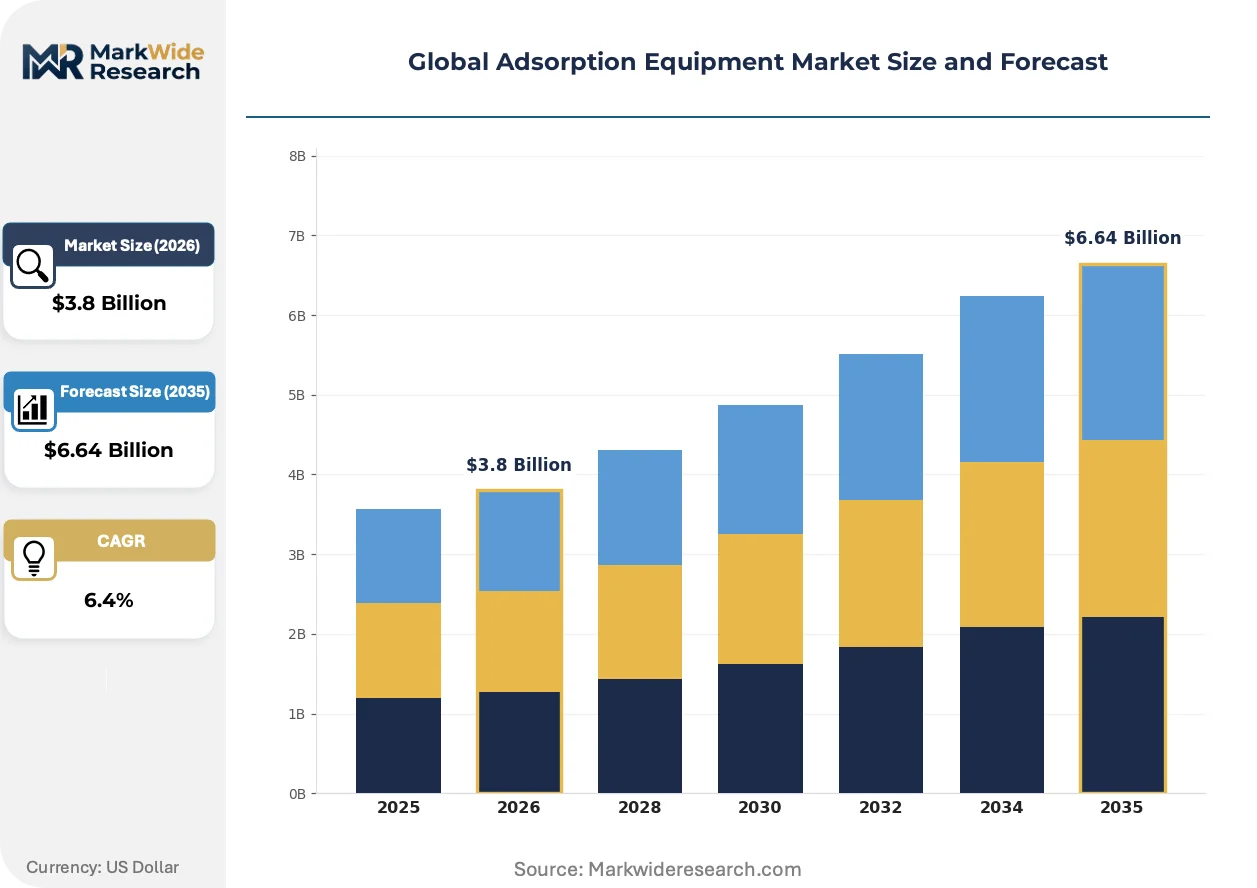
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Swing Adsorbers, Thermal Swing Adsorbers, Vacuum Swing Adsorbers, Hybrid Adsorbers, Fixed Bed Adsorbers Technology: Activated Carbon, Zeolites, Silica Gel, Polymer Adsorbents, Metal-Organic Frameworks Application: Water Treatment, Gas Purification, Pharmaceutical Purification, Air Separation, Food & Beverage Processing End User: Chemical Plants, Petrochemical Facilities, Semiconductor Manufacturing, Waste Management Firms, Power Generation Plants |
| Companies Covered | Calgon Carbon, Evoqua, CECO Environmental, Dürr AG, Munters, TIGG, Bry-Air, General Carbon, Taikisha Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adsorption Equipment Market Shifts & Advancements
Material science breakthroughs and regulatory precision are compressing equipment form factors while expanding application scope. Three developments are restructuring competitive advantage.
Metal-organic framework assemblies are modularizing gas separation infrastructure. These crystalline coordination polymers with programmable pore apertures enable kinetic separations previously requiring multi-stage pressure swing cycles. Pharmaceutical and electronics-grade gas producers in Germany and Japan are piloting MOF-based hydrogen purifiers and solvent recovery units. The technology is modularizing system architecture by collapsing multi-vessel trains into compact, single-bed configurations with reduced footprint and utility demand.
REACH authorization procedures and the EU F-Gas Regulation phase-down schedule are accelerating fluorinated solvent recovery investments. Chemical formulators face restricted access to high-global-warming-potential process solvents, compelling closed-loop purification and reclamation. Automotive coating lines in Germany and Benelux operations are retrofitting activated carbon recovery systems with real-time emission verification to maintain operating permits under tightening national implementation.
Equipment-as-a-service contracts are displacing capital purchase models among mid-scale chemical processors. Vendors retain asset ownership and absorb regeneration, media replacement, and compliance documentation burdens in exchange for per-unit-processed fees. This arrangement concentrates in North American specialty chemical and coating operations where balance sheet constraints and environmental liability concerns elevate operational expenditure preference over capital deployment.
Global Adsorption Equipment Market Segmentation
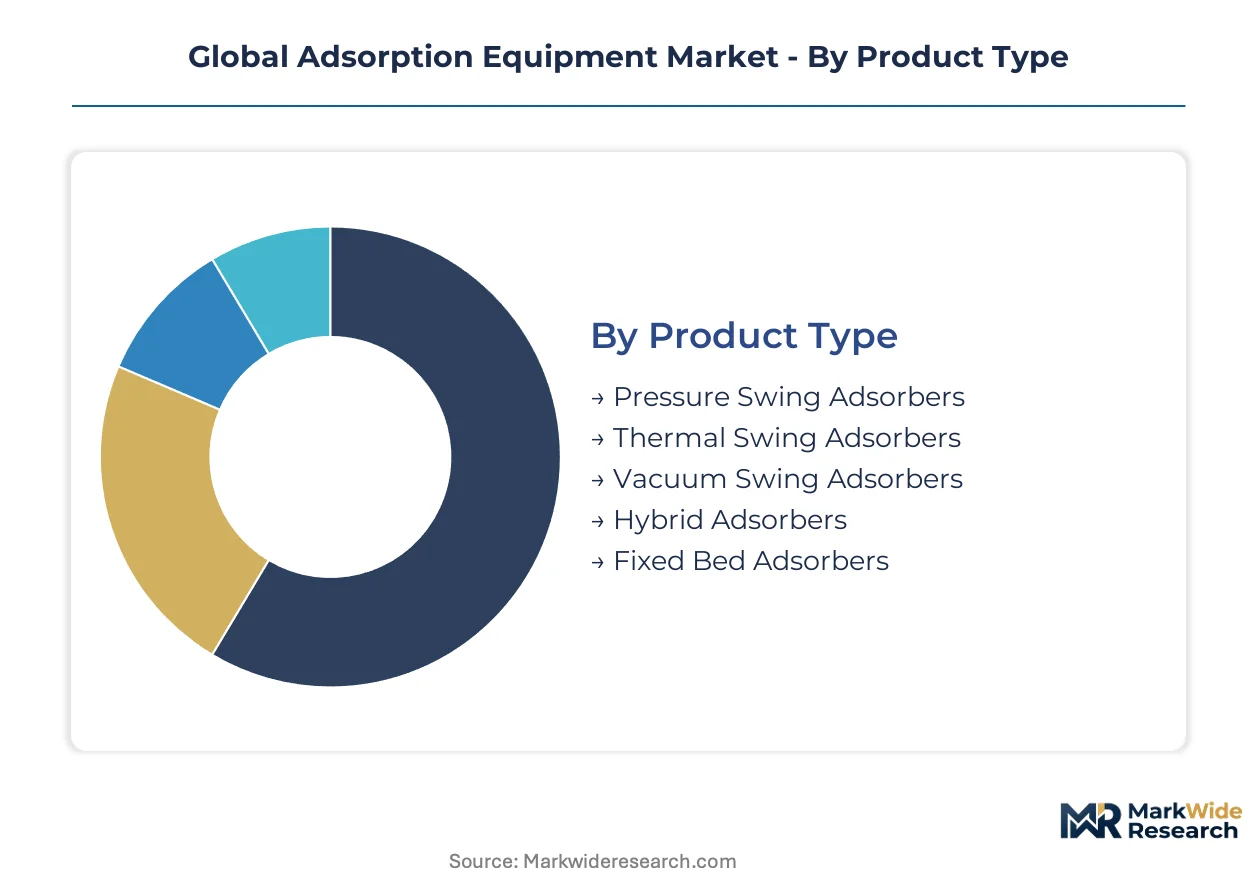
Equipment specification varies sharply across process conditions, with pressure ratings and regeneration protocols determining fit for specific contaminant profiles. Segment boundaries are blurring as hybrid systems combine swing cycles and advanced materials capture share from single-technology installations.
Product Type:
Replacement cycles differ materially across swing technologies, with pressure-based systems requiring more frequent media changeouts than thermal alternatives in high-duty applications.
- Pressure Swing Adsorbers:Cyclic operation between elevated and near-atmospheric pressures separates target gases using selective adsorbent media. Petrochemical facilities in Germany and the United States are expanding installed capacity for hydrogen purification and air separation as throughput requirements climb.
- Thermal Swing Adsorbers:Temperature variation drives adsorption and desorption phases, enabling solvent recovery from dilute vapor streams. Automotive coating operations across the US Midwest are retrofitting thermal systems to meet EPA MACT volatile organic compound capture mandates.
- Vacuum Swing Adsorbers:Sub-atmospheric desorption reduces energy intensity for oxygen production and carbon capture applications.
- Hybrid Adsorbers:Combined pressure-temperature cycles optimize for complex gas mixtures where single-swing economics falter.
- Fixed Bed Adsorbers:Continuous-flow vessels with periodic media replacement dominate water treatment where contaminant loading profiles are predictable.
Pressure Swing Adsorbers sits at the top of the volume ranking, with Hybrid Adsorbers climbing the fastest.
Technology:
Material selection directly determines regeneration frequency, energy consumption, and capture selectivity for specific molecule classes.
- Metal-Organic Frameworks:Crystalline coordination polymers with programmable pore apertures enable kinetic separations at reduced energy intensity. Electronics-grade gas producers in Japan and pharmaceutical manufacturers in Germany are piloting MOF-based purifiers for hydrogen and solvent recovery applications.
- Activated Carbon:High-surface-area amorphous carbon derived from coconut shell or coal precursors captures organic vapors and aqueous contaminants. Water treatment utilities across the United States and chemical plants in China's Jiangsu province are expanding procurement despite supply concentration risks in Southeast Asian feedstock markets.
- Zeolites:Microporous aluminosilicate minerals with uniform pore dimensions separate molecules by size exclusion in pressure swing applications.
- Silica Gel:Amorphous silicon dioxide adsorbents control humidity in pharmaceutical packaging and food processing environments.
- Polymer Adsorbents:Synthetic resins with tailored functional groups target specific ionic or polar contaminants in specialized purification.
Activated Carbon commands the largest installed base, while Metal-Organic Frameworks are gaining share fastest.
Application:
Process stream characteristics dictate vessel sizing, adsorbent selection, and regeneration infrastructure requirements.
- Water Treatment:Activated carbon and ion exchange media remove dissolved organics, chlorine, and heavy metals from municipal and industrial effluent. US municipal utilities and Chinese industrial parks are upgrading granular activated carbon systems as per- and polyfluoroalkyl substance regulations tighten.
- Gas Purification:Pressure and thermal swing systems remove contaminants from hydrogen, natural gas, and process streams. Petrochemical facilities in the US Gulf Coast and Germany's Ruhr region are expanding purification trains for polymer-grade feedstock production.
- Pharmaceutical Purification:High-purity solvent recovery and active ingredient separation require validated adsorption skids with full traceability.
- Air Separation:Pressure swing adsorbers produce nitrogen and oxygen for industrial processes and medical applications.
- Food & Beverage Processing:Decolorization, deodorization, and contaminant removal protect product quality in edible oil and sugar refining.
Water Treatment leads by unit volume, with Gas Purification showing the steepest expansion trajectory.
End User:
Capital intensity and environmental liability exposure vary dramatically across customer categories, shaping procurement preferences for ownership versus service-based models.
- Chemical Plants:Diverse solvent recovery and emission control requirements span batch and continuous operations. Specialty chemical manufacturers in the US Northeast and India's Gujarat state are adopting equipment-as-a-service contracts to transfer regeneration and compliance documentation burdens to vendors.
- Petrochemical Facilities:Large-scale hydrogen purification and olefin separation demand high-capacity pressure swing trains. Integrated complexes in Germany's Ludwigshafen cluster and China's Ningbo-Zhoushan port zone are expanding adsorption capacity for polymer production and refinery integration.
- Semiconductor Manufacturing:Ultra-high-purity gas requirements drive specification stringency for trace contaminant removal.
- Waste Management Firms:Landfill gas upgrading and leachate treatment utilize thermal swing and fixed bed systems.
- Power Generation Plants:Flue gas treatment and hydrogen cooling applications require specialized adsorption skids.
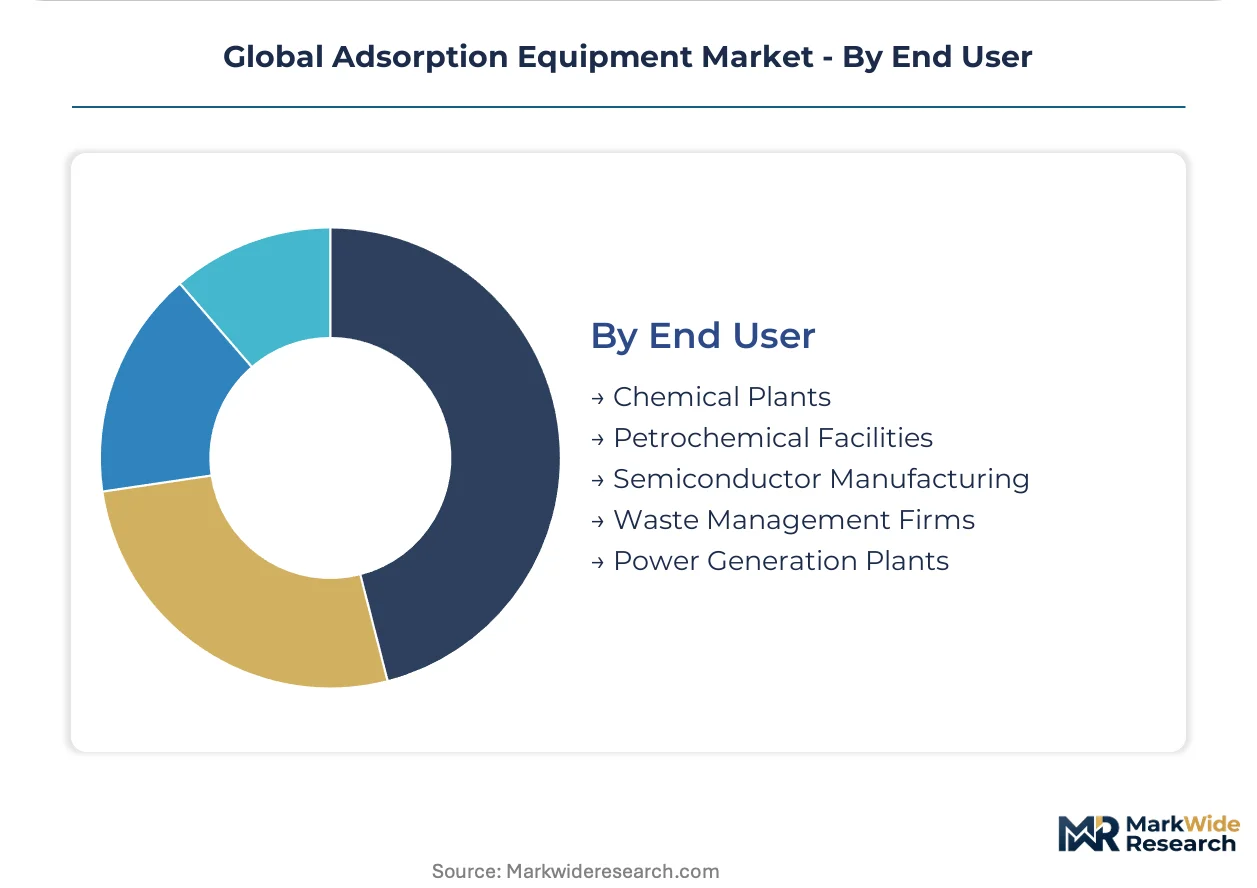
Petrochemical Facilities anchor demand by value, with Chemical Plants expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States command the highest equipment specification intensity for adsorption systems, while China's Jiangsu and Shandong provinces are compressing procurement timelines through centralized environmental enforcement.
United States
Petrochemical facilities along the Gulf Coast are expanding pressure swing adsorber capacity for hydrogen purification and olefin separation. EPA Maximum Achievable Control Technology standards mandate volatile organic compound capture at major emitting facilities, compelling coating operations across the US Midwest to retrofit thermal swing systems. Specialty chemical manufacturers in the Northeast are adopting equipment-as-a-service contracts to transfer regeneration burdens to vendors.
Germany
Automotive coating lines in the Ruhr region and Benelux-adjacent operations are retrofitting activated carbon recovery systems with real-time emission verification. The EU F-Gas Regulation phase-down schedule restricts access to high-global-warming-potential process solvents, driving closed-loop purification investments. Electronics-grade gas producers in Bavaria are piloting metal-organic framework purifiers for hydrogen applications.
China
Integrated petrochemical complexes in Ningbo-Zhoushan and manufacturing zones in Jiangsu and Shandong provinces are modernizing treatment infrastructure under continuous emission monitoring mandates from the Ministry of Ecology and Environment. Chemical plants are expanding procurement of pressure swing adsorbers despite activated carbon supply concentration risks in Southeast Asian feedstock markets.
India
Production-linked incentive schemes for specialty chemicals and pharmaceuticals are attracting greenfield capacity investments requiring solvent recovery infrastructure. The Bureau of Indian Standards is implementing increasingly stringent emission norms for industrial clusters. Gujarat-based specialty chemical manufacturers are adopting service-based procurement models to manage compliance documentation burdens.
Japan
Electronics-grade gas producers are piloting metal-organic framework assemblies for compact hydrogen purification systems. METI clean production incentives support carbon capture verification equipment at export-oriented manufacturing facilities. Pharmaceutical manufacturers in the Osaka-Kobe industrial corridor are deploying validated adsorption skids with full traceability requirements.
Global Adsorption Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment categories. The vendor base spans water treatment specialists, environmental engineering firms, and industrial gas equipment fabricators with varying degrees of vertical integration. Three archetypes dominate: integrated environmental service providers, specialized adsorption system fabricators, and diversified industrial equipment conglomerates. Competitive moves concentrate on modular skid packaging capabilities and equipment-as-a-service contract structures.
Among US-based environmental service providers, Evoqua and CECO Environmental exemplify the integrated service archetype. Dürr AG anchors the specialized fabricator tier with deep exposure to automotive coating applications. Calgon Carbon represents the activated carbon and media-focused segment with concentrated exposure to water treatment and vapor phase applications.
| Leading Market Players |
|---|
| Calgon Carbon |
| Evoqua |
| CECO Environmental |
| Dürr AG |
| Munters |
| TIGG |
| Bry-Air |
| General Carbon |
| Taikisha Ltd. |
| Others |
Supply & Pricing Matrix
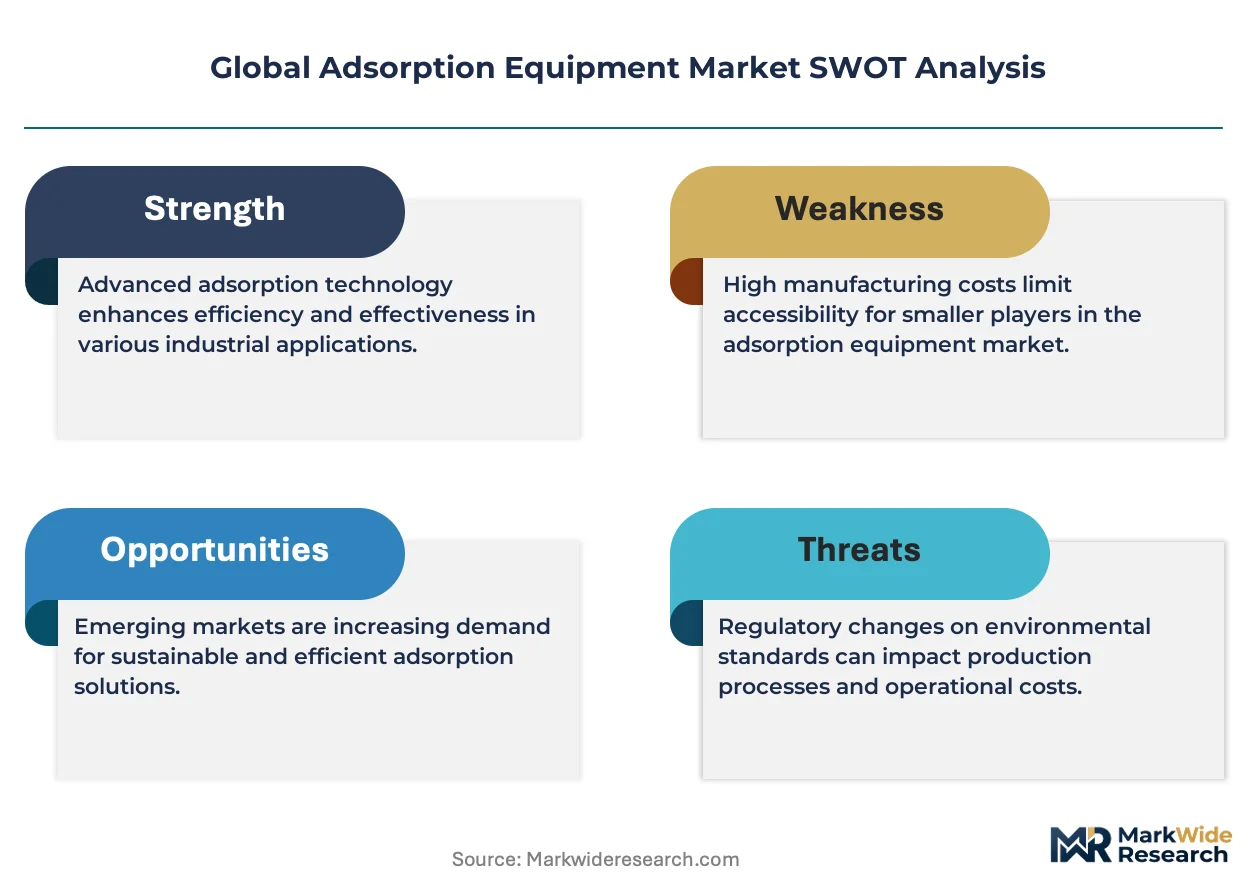
Process engineering talent concentration in Germany's Ruhr region and the US Gulf Coast creates labor-cost differentials that widen pricing-tier spreads between premium validated systems and standard skid-mounted units.
Pricing Analysis
Capacity additions in China's Jiangsu province are reshaping price floors for standard pressure swing adsorbers. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by ASME certification grade and after-sales service bundling. Pricing pressure stems from membrane separation substitution in nitrogen generation applications. Mid-scale chemical processors show highest price sensitivity; semiconductor fabs show least.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian coconut shell activated carbon feedstock. Supply draws from Indonesia, Philippines, and Sri Lanka for high-surface-area carbon media. Synthetic zeolite precursors and specialized aluminosilicates create raw material dependencies. Tariff exposure on Chinese-manufactured pressure vessels elevates procurement risk. Distribution runs through regional environmental engineering integrators and direct OEM channels to large petrochemical facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal-organic framework cost-down curves and premium-tier shift toward electronics-grade gas purification create margin-expansion headroom for specialized vendors.
For Market Incumbents: To counter membrane separation substitution in biogas upgrading, deepen backward integration into synthetic zeolite manufacturing and anchor channel control through equipment-as-a-service contract structures at US specialty chemical facilities. For New Entrants and Emerging Players: Launch via modular skid packaging and rental-based commercial models targeting India's Gujarat specialty chemical cluster under PLI-linked clean production incentives, where solvent recovery infrastructure demand outpaces established vendor coverage. For Investors and Strategic Acquirers: Industrial gas equipment conglomerates are the most active acquirer in this space. Five-to-ten-year viability centers on MOF technology access and regeneration service network density. Watch for EPA MACT enforcement intensity as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adsorbent Media | Captive zeolite supply secures margin capture at Dürr AG's automotive coating system deployments. |
| Equipment-as-a-Service Contract Expansion | Recurring revenue models transfer EPA compliance documentation burdens from US chemical plant balance sheets. |
| Metal-Organic Framework Pilot Scale-Up | Electronics-grade hydrogen purification in Bavaria validates MOF displacement of conventional PSA trains. |
| Modular Skid Packaging Standardization | Containerized units reduce field installation complexity for mid-scale nitrogen users in India's industrial corridors. |
| Regeneration Service Network Densification | Aftermarket capture constraints from scarce thermal swing expertise open franchise opportunities in regional markets. |
Research Methodology
Multiple input streams — plant engineer interviews, procurement lead surveys, customs trade records, and EPA enforcement databases — were reconciled across bottom-up and top-down triangulation. Primary engagement spanned maintenance directors at petrochemical facilities, OEM procurement teams, aftermarket service heads, and technical R&D directors at adsorbent manufacturers. Secondary validation drew from ECHA REACH filings, USITC trade data, SEC 10-K equipment disclosures, and MEE emission permit records.
Segment-level projections across product type, technology, application, and end-user dimensions were reconciled against regional production hub clustering throughout the forecast period. CAGRs were derived from installed base turnover modeling and regulatory mandate timing. Forecast inputs incorporated MOF technology cost curves, activated carbon feedstock price indices, and EPA MACT enforcement probability weightings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH authorization withdrawals or Southeast Asian supply disruptions. Projections reflect documented assumptions on regulatory implementation pacing and material science advancement rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Nitrogen Tester Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Fibrin Degradation Product (Fndp) Assays Market
Testing Equipment
Chemical Detection Equipment Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Europe Process Analytics Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
Sample Preparation Market
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Laboratory Ware Market