
 Composites Testing Market | 2026-2036
Composites Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Composites Testing Market Analysis
German materials laboratories is consolidating around polymer matrix qualification for automotive OEMs. Element Materials Technology leverages its European accreditation network to anchor aerospace certification workflows. Intertek Group competes through destructive testing capacity in North American wind blade supply chains. Mistras Group specializes in ultrasonic phased-array inspection for oil and gas composite pressure vessels.
Composites testing encompasses mechanical, thermal, and non-destructive evaluation protocols applied to fiber-reinforced materials to verify tensile strength, interlaminar shear resistance, and glass transition temperature against application-specific load cases. Tensile and compression test types dominate volume due to mandatory airframe qualification cycles, while dynamic mechanical analysis commands premium pricing for high-temperature polymer matrix characterization in propulsion systems. Non-destructive testing technology leads growth trajectory as wind turbine blade manufacturers shift from periodic strip-down to in-service phased-array monitoring.
FAA airworthiness standards under 14 CFR Part 25 and EASA CS-25 mandate traceable mechanical test data for primary aircraft structure certification, forcing laboratories to maintain Nadcap and ISO 17025 accreditation. REACH compliance in Europe restricts certain resin chemistries, redirecting R&D toward halogen-free thermoset formulations that require updated thermal analysis baselines. Stakeholders must weigh accreditation investment against regional certification reciprocity as Brazil's ANVISA and China's NMPA develop composite-specific medical device and civil aviation test protocols.
Market Dynamics
Phased-array ultrasonic testing is compressing inspection cycles from weeks to hours, forcing laboratories to retool capital bases while aerospace OEMs demand real-time data integration into digital thread workflows.
Growth Catalysts
- EASA CS-25 airworthiness mandates:European aerospace manufacturers now require continuous mechanical validation for carbon-fiber-reinforced polymer primary structures, expanding qualification protocols across the Toulouse-Blagnac supply basin.
- Wind turbine blade manufacturers:Operators are abandoning periodic strip-down inspections for in-service phased-array monitoring, creating pull for non-destructive testing capacity in blade supply chains.
- Halogen-free thermoset formulations:REACH compliance restrictions on legacy resin chemistries are redirecting R&D investment toward updated thermal analysis baselines for polymer matrix qualification.
Market Restraints
- Capital intensity of accreditation:Nadcap and ISO 17025 compliance requires sustained investment in calibrated equipment and audit trails, creating barriers for mid-scale laboratories.
- Input concentration in Bavaria:German aerospace clusters dominate polymer matrix qualification capacity, creating geographic supply risk for Tier-1 suppliers requiring rapid turnaround.
- Reciprocity fragmentation:Brazil's ANVISA and China's NMPA are developing non-harmonized composite-specific test protocols, forcing redundant certification investments.
Strategic Opportunities
- Medical device composites:China's NMPA is establishing dedicated pathways for carbon-fiber orthopedic implant validation, opening white space beyond aerospace and wind.
- Digital twin integration:Convergence of non-destructive testing data with predictive maintenance platforms is enabling subscription-based inspection services for offshore wind assets.
- India's PLI scheme:Production-linked incentives for advanced materials are attracting testing infrastructure investment to serve domestic aerospace and defense programs.
Industry Challenges
- Phased-array technician scarcity:Specialized ultrasonic inspection skills require months of certification training, constraining laboratory expansion timelines.
- Legacy equipment integration:Analog mechanical testing systems lack digital output compatibility with modern quality management platforms, forcing parallel workflow maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composites Testing Market |
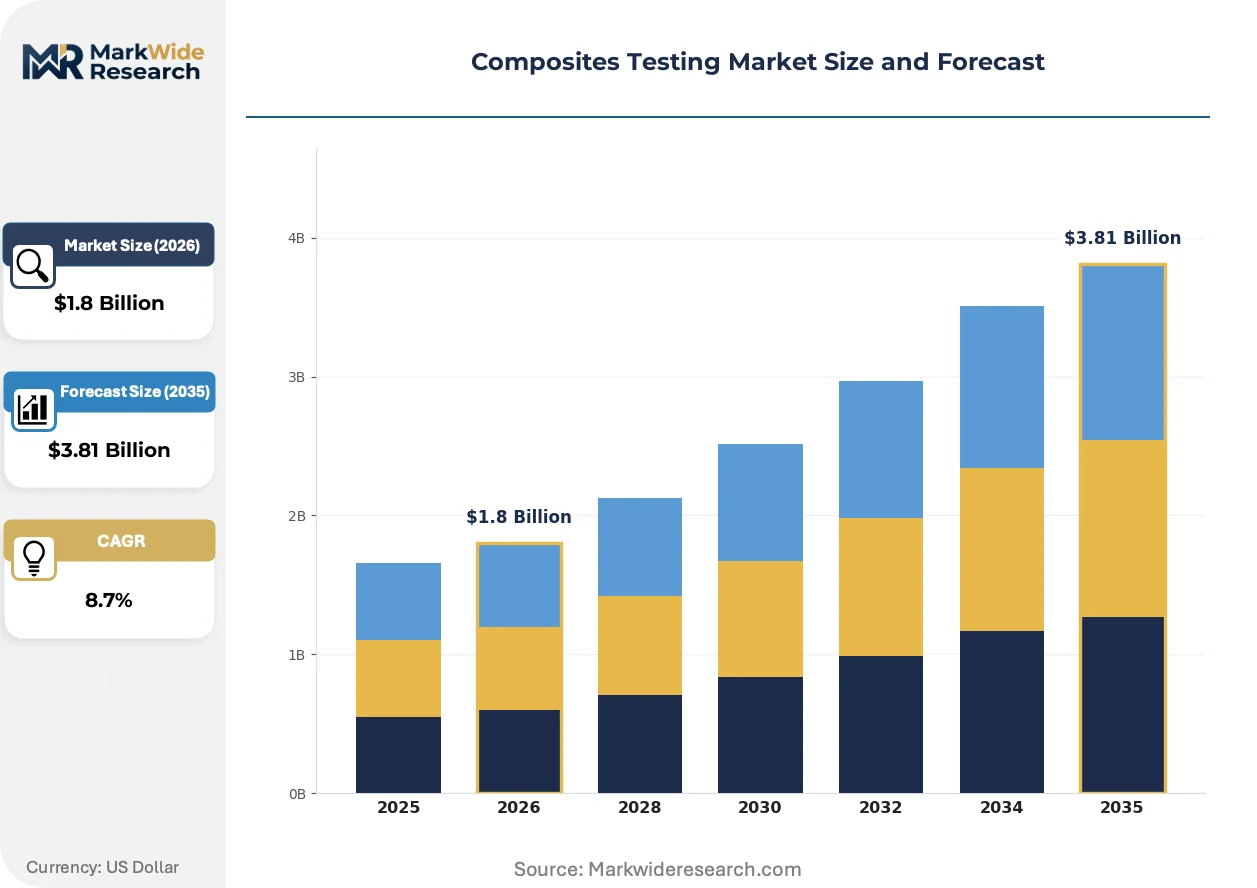
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Tensile, Compression, Flexural, Impact Material Type: Polymer Matrix, Metal Matrix, Ceramic Matrix, Hybrid Composites End User: Aerospace, Automotive, Construction, Marine Technology: Non-Destructive Testing, Destructive Testing, Thermal Analysis, Dynamic Mechanical Analysis |
| Companies Covered | Element Materials Technology, Intertek Group, Mistras Group, Henkel AG & Co. KGaA, Westmoreland Mechanical Testing & Research, Instron, ETIM Composites Testing Laboratory, Composites Testing Laboratory, Matrix Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composites Testing Market Emerging Trajectories
Real-time data streaming from inspection equipment is collapsing the gap between testing and certification decisions, compressing program timelines and reshaping laboratory service models.
Automated robotic scanning systems for large-scale composite structures is decentralizing inspection capacity from centralized laboratories to production line floors. Aerospace manufacturers in Germany are deploying these systems for wing skin qualification. The technology is compressing logistics costs and turnaround times for Tier-1 suppliers.
REACH restrictions on halogenated flame retardants are forcing reformulation of aerospace-grade prepregs. European laboratories must establish new thermal analysis baselines for glass transition temperature validation. Wind blade manufacturers adopting these materials face extended qualification cycles during the transition.
Buyers are unbundling after-sales calibration and maintenance contracts from initial equipment procurement. Testing laboratories in North American wind supply chains now compete on service response metrics rather than capital equipment specifications. This shift favors regional service density over national coverage footprints.
Composites Testing Market Segmentation
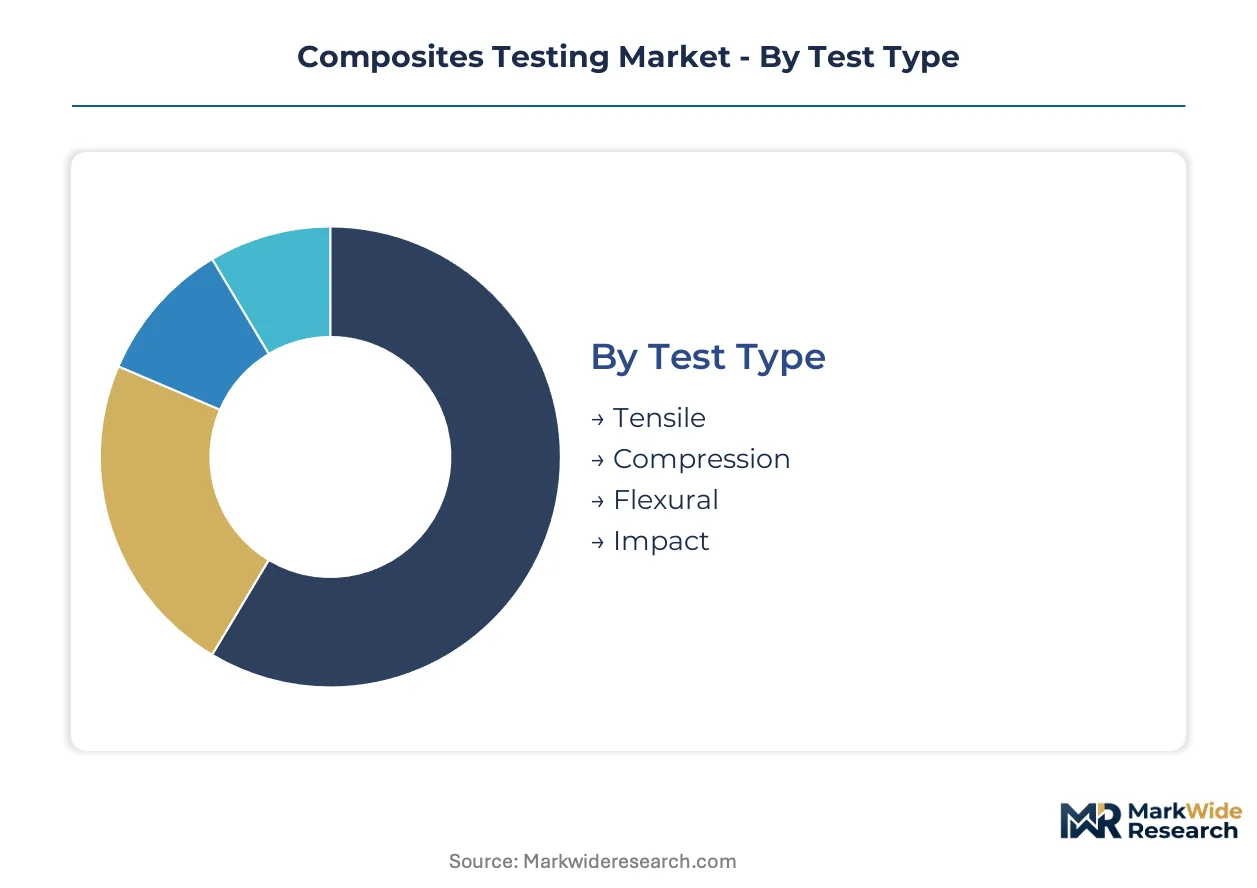
Composites testing segments reflect divergent technical requirements across airframe qualification cycles, automotive crashworthiness protocols, and wind blade structural health monitoring. Laboratories must calibrate equipment portfolios against distinct accreditation standards and turnaround expectations that vary sharply by end-use.
Test Type:
Tensile and compression protocols dominate aerospace certification workflows due to CS-25 mandates for primary structure validation.
- Tensile:Uniaxial loading tests measure fiber-dominated strength and modulus for laminate qualification. Bavarian aerospace clusters consume capacity for carbon-fiber-reinforced polymer airframe panels under EASA traceability requirements. Nadcap-accredited laboratories in Munich and Augsburg report 6-8 week backlogs for primary structure campaigns.
- Compression:Fixture-stabilized testing evaluates fiber microbuckling and kink-band formation in thick laminates. Toulouse-Blagnac suppliers require continuous compression validation for wing skin qualification under Airbus qualification protocols. Fixture design complexity drives premium pricing relative to tensile equivalents.
- Flexural:Three-point and four-point bending tests screen interlaminar shear strength for automotive structural components. German OEMs specify flexural validation for polymer matrix crash structures under KBA homologation.
- Impact:Drop-weight and ballistic methods assess damage tolerance for military armor and aerospace leading edges. French defense procurement directs impact testing for helicopter rotor blade certification.
Tensile testing leads on scale; compression testing leads on momentum as thick-section airframe applications expand.
Material Type:
Matrix chemistry determines thermal analysis baselines and accreditation renewal cycles for laboratory portfolios.
- Polymer Matrix:Thermoset and thermoplastic composites account for the majority of commercial testing volume. Epoxy-based prepregs dominate aerospace qualification in Germany and France. REACH restrictions on halogenated flame retardants force reformulation and re-baselining of glass transition temperature protocols.
- Metal Matrix:Aluminum and titanium matrix systems serve propulsion and thermal management applications. Ceramic fiber reinforcements in these systems require specialized furnace capacity for elevated-temperature mechanical testing.
- Ceramic Matrix:Silicon carbide and oxide-oxide composites enable turbine hot-section components above polymer limits. Limited commercial testing infrastructure concentrates in national aerospace laboratories.
- Hybrid Composites:Multi-material laminates combining polymer, metal, or natural fiber layers complicate failure mode prediction. Automotive OEMs in Stuttgart specify hybrid validation for lightweight body-in-white structures.
Polymer matrix testing leads on scale; hybrid composites testing leads on momentum as multi-material vehicle architectures proliferate.
End User:
Industry-specific load cases and regulatory frameworks shape laboratory service line investments.
- Aerospace:Primary structure certification under FAA 14 CFR Part 25 and EASA CS-25 mandates traceable mechanical test data. German and French manufacturers drive demand for continuous qualification of carbon-fiber-reinforced polymer airframes.
- Automotive:Crashworthiness and durability validation for polymer matrix structural components. OEMs consolidate testing around polymer matrix qualification as electric vehicle platforms expand.
- Construction:Pultruded profiles and fiber-reinforced polymer rebar require long-term creep and environmental aging validation. Infrastructure applications lag aerospace in standardization maturity.
- Marine:Hull and superstructure testing for fiberglass and carbon-fiber craft. Classification society rules from Lloyd's Register and DNV drive destructive testing protocols for racing yacht composites.
Aerospace leads on scale; automotive leads on momentum as OEMs accelerate polymer matrix adoption for lightweighting targets.
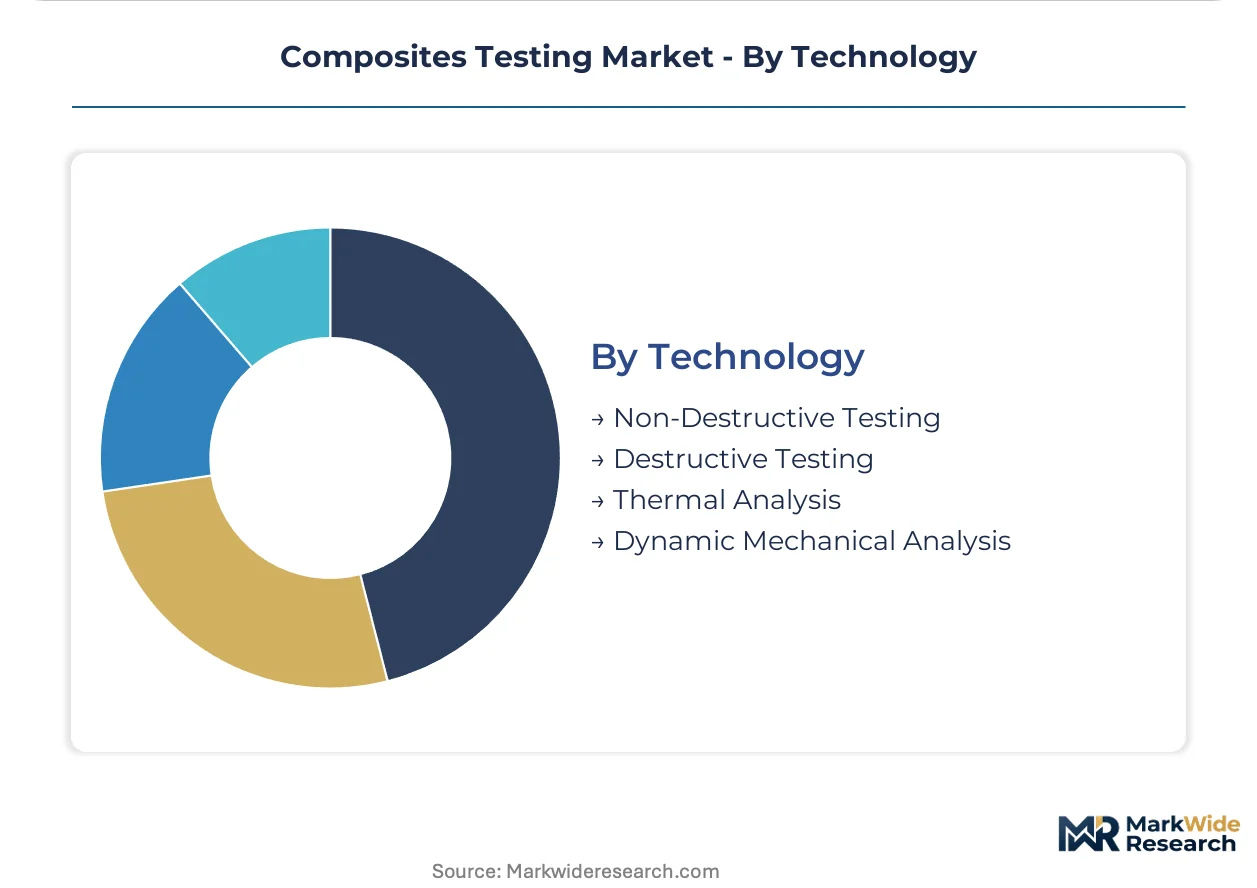
Technology:
Inspection modality selection hinges on damage tolerance philosophy and production integration requirements.
- Non-Destructive Testing:Ultrasonic phased-array and radiographic methods enable in-service structural health monitoring. Wind turbine blade manufacturers shift from periodic strip-down to continuous monitoring, compressing inspection cycles from weeks to hours.
- Destructive Testing:Mechanical coupon extraction and failure analysis provide ground-truth validation for certification. Aerospace OEMs demand destructive testing for primary structure qualification despite cost and schedule impact.
- Thermal Analysis:Differential scanning calorimetry and thermomechanical analysis establish glass transition and cure state baselines. REACH-driven resin reformulation forces laboratory re-accreditation for halogen-free thermoset characterization.
- Dynamic Mechanical Analysis:Viscoelastic property measurement across temperature and frequency ranges commands premium pricing for high-temperature polymer matrix validation in propulsion systems.
Destructive testing leads on scale; non-destructive testing leads on momentum as in-service monitoring replaces periodic inspection regimes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates polymer matrix qualification capacity while the United States fragments across aerospace and wind energy testing corridors. France anchors European airframe certification workflows through Toulouse-Blagnac supplier mandates. China's NMPA is establishing composite-specific medical device pathways. India's PLI scheme for advanced materials attracts testing infrastructure investment. Brazil's ANVISA develops non-harmonized protocols that force redundant certification spending.
United States
Wind turbine blade manufacturers and aerospace OEMs drive destructive and non-destructive testing demand across multiple supply chains. FAA 14 CFR Part 25 mandates traceable mechanical test data for primary aircraft structure certification. Testing capacity concentrates in Pacific Northwest wind corridors and Southeast aerospace clusters where Tier-1 suppliers require rapid turnaround.
Germany
Automotive OEMs and aerospace manufacturers consume capacity for polymer matrix crash structures and carbon-fiber-reinforced polymer airframe panels. KBA homologation specifies flexural validation requirements for structural components. Bavarian laboratories in Munich and Augsburg report extended backlogs for primary structure qualification campaigns under EASA traceability requirements.
France
Airbus qualification protocols and defense procurement directives sustain continuous compression validation demand for wing skins and helicopter rotor blades. EASA CS-25 airworthiness mandates expand qualification protocols across the Toulouse-Blagnac supply basin. French defense procurement directs impact testing certification for military composite applications.
China
Domestic aerospace programs and emerging medical device composites create dual demand vectors for testing infrastructure. NMPA establishes dedicated pathways for carbon-fiber orthopedic implant validation beyond traditional aerospace applications. Production-linked incentives attract laboratory investment to serve regional OEM qualification requirements.
India
Domestic aerospace and defense programs under the PLI scheme for advanced materials pull testing capacity expansion. The country's national aviation regulator develops composite-specific civil aviation test protocols alongside existing frameworks. Regional industrial corridors attract infrastructure investment to serve localized supplier qualification needs.
Composites Testing Market Vendor Landscape
German and British producers anchor the accreditation-intensive tier; North American specialists hold destructive testing capacity for wind blade supply chains. The vendor base stratifies across three tiers: Nadcap-accredited aerospace certifiers, regional automotive qualification laboratories, and equipment-integrated service providers. Two competitive moves dominate: European players extend accreditation networks across EASA jurisdictions, while North American laboratories compete on service response metrics through unbundled maintenance contracts.
Among European-based certifiers, Element Materials Technology and Intertek Group exemplify the accreditation-network archetype, leveraging multi-jurisdictional laboratory footprints to anchor aerospace certification workflows. Mistras Group occupies a position among North American specialists focused on non-destructive inspection modalities. These three entities represent contrasting strategic positions: European network density versus North American service velocity, with each archetype commanding distinct procurement relationships based on turnaround requirements and regulatory scope.
| Leading Market Players |
|---|
| Element Materials Technology |
| Intertek Group |
| Mistras Group |
| Henkel AG & Co. KGaA |
| Westmoreland Mechanical Testing & Research |
| Instron |
| ETIM Composites Testing Laboratory |
| Composites Testing Laboratory |
| Matrix Composites |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up testing specialists have consolidated regional laboratory networks across Germany and France, concentrating accreditation assets that command premium pricing for EASA-mandated airframe qualification while compressing margins for mid-scale competitors lacking Nadcap scope.
Pricing Analysis
Capacity additions in India's advanced materials corridors are reshaping price floors for polymer matrix qualification services. Three-tier pricing structure across premium, standard, and economy levels separates Nadcap-accredited aerospace certifiers from regional automotive laboratories and equipment-integrated service providers. Price differentiation hinges on certification tier and geographic delivery density, with Bavarian clusters extracting premiums for rapid-turnaround primary structure campaigns. Cost compression in North American wind supply chains intensifies as buyers unbundle after-sales contracts from equipment procurement, favoring regional service density over national coverage footprints. Tier-1 aerospace suppliers exhibit lowest price sensitivity due to program risk exposure, while automotive OEMs negotiate aggressively on volume-scale flexural validation contracts.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's NMPA pathways are reshaping sourcing patterns for testing infrastructure investment. Geographic supply concentration centers on Germany, France, and the United States, with Bavarian laboratories and Toulouse-Blagnac suppliers anchoring polymer matrix qualification capacity. Raw material dependencies rest on calibrated load frames, ultrasonic phased-array transducers, and certified reference materials for thermal analysis baselines. Single-source vulnerability concentrates in specialized technician training pipelines for phased-array certification, constraining laboratory expansion timelines. Distribution runs through direct contractual relationships between Tier-1 suppliers and accredited laboratories, with equipment-integrated service providers penetrating mid-market automotive segments through unbundled maintenance offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composites testing functions as a stable compounder underpinned by regulatory ratchet effects—EASA CS-25 and FAA 14 CFR Part 25 mandates perpetually expand qualification protocol scope, embedding recurring revenue streams for accredited laboratories.
For Market Incumbents: Deepen vertical integration into robotic scanning systems for production-line deployment, defending against equipment-integrated service providers penetrating aerospace workflows. Anchor accreditation network expansion across emerging EASA jurisdictions before regional laboratories achieve Nadcap scope, consolidating procurement relationships with Airbus and Boeing Tier-1 suppliers through co-located inspection capacity. For New Entrants and Emerging Players: Capture white space in China's NMPA medical device composite pathways and India's PLI-scheme aerospace corridors, where domestic qualification infrastructure lags program growth. Target carbon-fiber orthopedic implant validation as the most penetrable segment, leveraging partnerships with domestic OEMs seeking localized certification alternatives to European laboratory dependence. For Investors and Strategic Acquirers: Valuations sit cheapest among regional automotive qualification laboratories lacking aerospace accreditation scope, presenting consolidation platforms for capability extension. Long-term viability rests on regulatory reciprocity expansion and digital twin integration subscription models. The signal to watch is phased-array technician certification throughput rates as a leading indicator of laboratory capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Network Expansion | Element Materials Technology extends EASA scope across Eastern European aerospace clusters. |
| Robotic Inspection Deployment | Automated scanning systems compress logistics costs for German wing skin qualification campaigns. |
| Digital Twin Integration | Convergence with predictive maintenance platforms enables subscription revenue for offshore wind assets. |
| Medical Device Pathway Development | NMPA carbon-fiber orthopedic protocols open validation revenue beyond traditional aerospace verticals. |
| Regional Service Density Buildout | Unbundled maintenance contracts favor North American laboratories competing on response metrics. |
Methodological Framework
Bottom-up aerospace and automotive modeling reconciled against top-down laboratory capacity tracking forms the analytical core of this study. Primary interviews with Nadcap laboratory directors, Tier-1 supplier procurement managers, EASA certification engineers, and wind blade operations heads combined with secondary validation from EASA CS-25 amendment filings, FAA airworthiness directives, customs trade data for testing equipment imports, and SEC disclosures from listed testing services providers. Triangulation between end-use demand segmentation and supply-side accreditation registry analysis ensures cross-verified volume estimates.
Input-output matrices map test type demand against laboratory equipment portfolios across the projection horizon, segmenting by mechanical, thermal, and non-destructive modalities alongside end-use industry and material matrix chemistry. CAGRs derive from regression analysis of historical accreditation expansion rates correlated with airframe production forecasts and wind turbine installation pipelines. Industry-specific forecast inputs include EASA mandate implementation timelines and REACH-driven resin reformulation cycles affecting thermal analysis baseline renewal frequency.
Regulatory reciprocity fragmentation, phased-array technician training bottlenecks, and raw material supply constraints for certified reference materials are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding accreditation harmonization progress and OEM qualification protocol stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Isostatic Graphite Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Green Composites Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Hybrid Composites Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
CFRTP Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
High Frequency High Speed Copper Clad Laminate CCL Market
Composite Materials
PCR Laminates Market
Composite Materials
Laminar Composites Market
Composite Materials
Global Closed Molding Composites Market