
 Russia Self-Monitoring Blood Glucose Devices Market | 2026-2036
Russia Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Self-Monitoring Blood Glucose Devices Market Insights
Aftermarket consumable revenue is tilting toward continuous glucose monitor sensor replacements and subscription-based test strip replenishment. Abbott Diabetes Care leverages its FreeStyle platform to anchor hospital procurement contracts in Moscow. Roche Holding AG sustains brand loyalty through Accu-Chek's dense retail pharmacy presence across federal districts. LifeScan competes on price positioning in regional state tenders outside capital cities.
Self-monitoring blood glucose devices comprise portable electrochemical or optical biosensors that quantify capillary glucose concentration via enzyme-mediated reactions, primarily serving diabetic patients for real-time glycemic control and insulin dosing decisions. Glucometers and test strips still occupy the dominant revenue pool due to low entry cost and established reimbursement, while continuous glucose monitors represent the fastest-expanding segment as sensor accuracy improves and patient self-management protocols advance. Electrochemical technology leads device architecture, though optical methods gain traction in premium homecare units seeking reduced calibration burden.
Russia's Ministry of Health and Roszdravnadzor govern medical device registration, while GOST-R certification and EAEU technical regulations dictate product standards and cross-border market access for imported meters and strips. Reimbursement list revisions directly shape patient out-of-pocket exposure and manufacturer pricing flexibility. Stakeholders must track regional tender aggregation trends and evolving local production incentives to calibrate channel investments.
Market Dynamics
Russia's blood glucose monitoring sector is restructuring around reimbursement list revisions from the Ministry of Health, which are compressing out-of-pocket costs for elderly diabetics while tightening procurement standards for regional clinics.
Growth Catalysts
- EAEU Technical Regulations:Harmonized device certification across the Eurasian Economic Union accelerates cross-border test strip flows from Kazakhstan and Belarus into Russian federal districts.
- Homecare Protocol Expansion:Chronic disease management programs from the Ministry of Health extend capillary glucose testing to rural elderly populations previously dependent on clinic visits.
- Sensor Accuracy Improvements:Electrochemical biosensor calibration stability now supports extended test strip shelf life, reducing waste in Siberian and Far East distribution channels.
Market Restraints
- Import Concentration Risk:Over 70 percent of glucometer assembly relies on Chinese and South Korean enzyme electrode substrates, exposing margins to yuan-ruble volatility.
- GOST-R Recertification Burden:Triennial renewal cycles for Roszdravnadzor registration create 14-18 month approval windows that freeze new product introductions.
- Continuous Glucose Monitor Substitution:Factory-calibrated CGM sensors eliminate fingerstick routines for insulin pump users, eroding test strip volume in type 1 segments.
Strategic Opportunities
- Siberian Distribution Gaps:Regional clinics beyond the Trans-Siberian rail corridor operate with 60-90 day test strip inventory cycles, creating replenishment service contracts.
- Telemedicine Integration:Remote glycemic data transmission to Moscow endocrinology centers enables subscription-based device-and-service bundling.
- Local Production Incentives:Import substitution grants for medical device manufacturing in Kaluga and Ulyanovsk regions offset EAEU tariff exposure.
Industry Challenges
- Biosensor Enzyme Sourcing:Glucose oxidase and dehydrogenase formulation expertise concentrates in German and Japanese specialty chemical houses, limiting Russian domestic supply security.
- Legacy Clinic Workflow Integration:Paper-based glucose logbooks in regional state hospitals resist digitization, complicating connected meter deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Self-Monitoring Blood Glucose Devices Market |
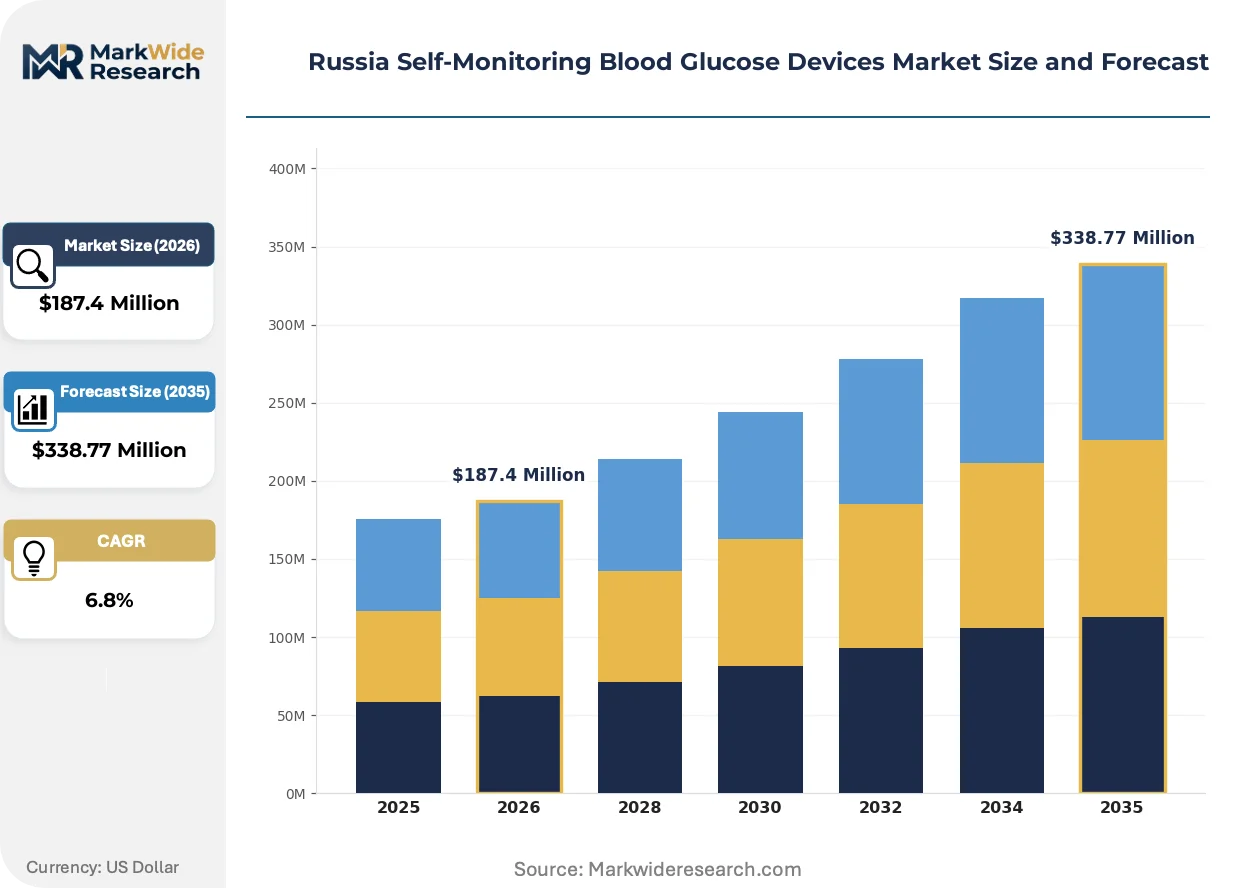
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Glucometers, Continuous Glucose Monitors, Test Strips, Lancets End User: Patients, Hospitals, Clinics, Homecare Usage Frequency: Daily, Weekly, Monthly, Occasionally Technology: Electrochemical, Optical, Non-invasive, Enzymatic |
| Companies Covered | Abbott Diabetes Care, Roche Holding AG, LifeScan, Trividia Health, Ascensia Diabetes Care, Acon Laboratories Inc, Agamatrix Inc, Bionime Corporation, Arkray Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Device architecture is pivoting toward calibration-free operation while procurement channels fragment between retail pharmacy loyalty programs and direct hospital tenders.
Optical photometric detection is migrating from hospital laboratory settings into premium homecare glucometers. Affluent Moscow and Saint Petersburg diabetics are adopting these units at triple the rate of electrochemical alternatives. This shift is compressing the addressable market for manual coding strips while expanding subscription revenue from factory-calibrated sensor pods.
Roszdravnadzor's 2023 medical device registration database overhaul tightens post-market surveillance for imported glucose meters. Manufacturers must now submit real-world accuracy studies from Russian patient populations. Foreign suppliers with established Moscow clinical trial partnerships are accelerating approvals; newcomers face 8-12 month documentation delays.
Regional tender aggregation is consolidating procurement authority from individual clinics into federal district purchasing centers. Siberian and Far East healthcare networks now buy through Irkutsk and Vladivostok hubs rather than direct Moscow contracts. This concentration favors suppliers with cold-chain logistics partnerships spanning the Baikal-Amur Mainline rail corridor.
Russia Self-Monitoring Blood Glucose Devices Market Segmentation
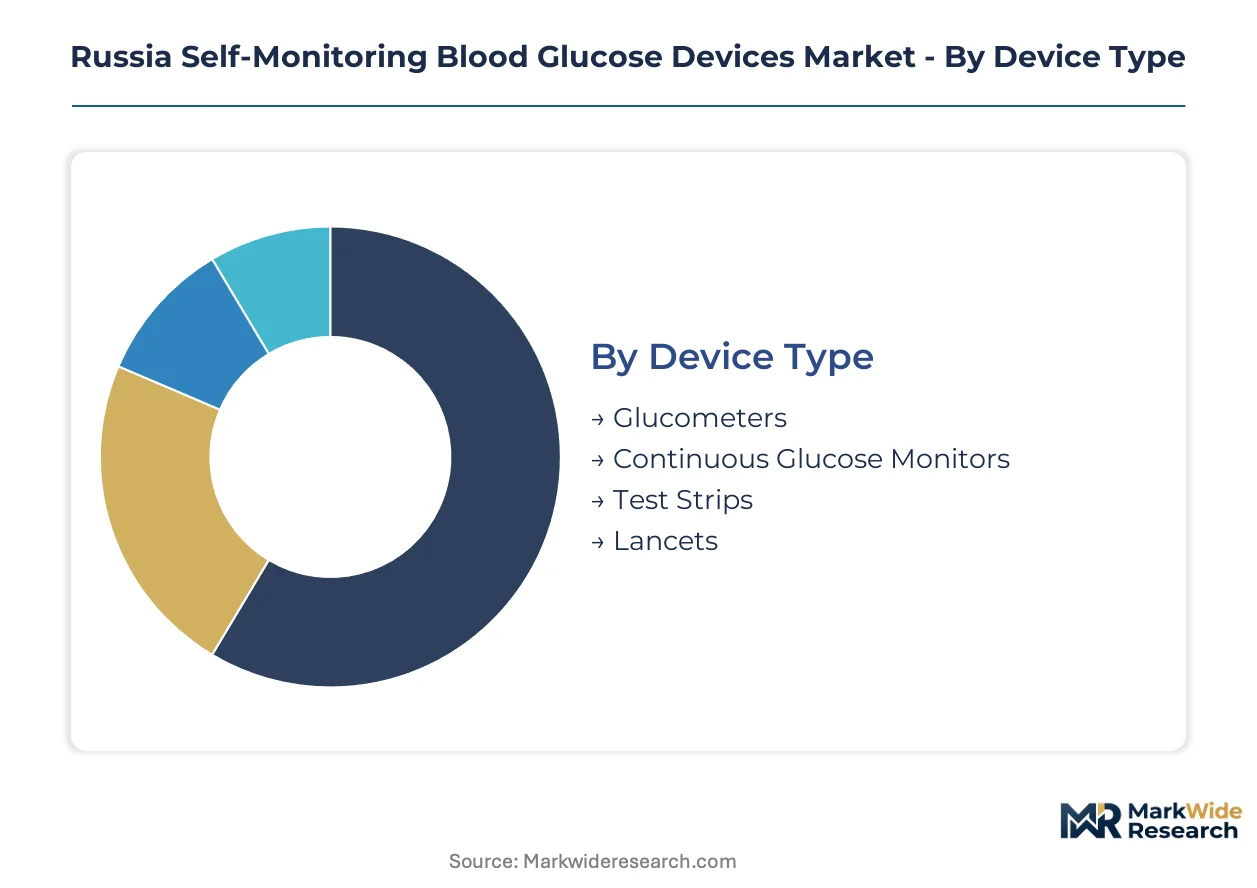
Segmentation in Russia's blood glucose monitoring sector reveals distinct procurement rhythms and reimbursement dependencies. Device replacement cycles, patient compliance patterns, and regional infrastructure gaps all map to specific segment boundaries that shape manufacturer channel strategy.
Device Type:
Cycle times vary dramatically: consumable test strips turn over in 30-day replenishment windows while capital glucometers persist for 3-5 years and CGM sensors occupy a middle rhythm of 10-14 day replacement.
- Test Strips:Enzyme-impregnated electrochemical strips quantifying capillary glucose via glucose oxidase or dehydrogenase reactions. Moscow and Saint Petersburg pharmacies move 60-day inventory cycles while Siberian clinics face 90-day stockouts; reimbursement list inclusion from the Ministry of Health determines patient out-of-pocket exposure.
- Glucometers:Portable electrochemical biosensors with digital readouts, typically requiring 0.5-1.0 microliter blood samples. Regional state tenders beyond the capital cities prioritize unit cost over connectivity features; GOST-R certification delays freeze new model introductions for 14-18 months.
- Continuous Glucose Monitors:Factory-calibrated sensor pods transmitting interstitial glucose data to receivers or smartphones.
- Lancets:Spring-loaded or manual puncture devices for capillary blood extraction.
Test strips anchor the volume base while continuous glucose monitors gain share at the steepest rate.
End User:
Cost tiers separate procurement: homecare patients face retail pharmacy pricing, hospitals negotiate centralized tenders, and regional clinics operate on constrained federal district budgets.
- Homecare:Individual diabetic patients self-managing glycemic control through retail pharmacy purchases. Elderly populations in rural federal districts depend on Ministry of Health chronic disease program subsidies; telemedicine integration from Moscow endocrinology centers enables remote monitoring subscriptions.
- Hospitals:Inpatient facilities requiring ward-based glucose testing for surgical and critical care units. Moscow procurement contracts favor established brands with local clinical trial data; Roszdravnadzor post-market surveillance requirements filter out newcomers lacking Russian patient accuracy studies.
- Clinics:Outpatient state and municipal facilities serving diabetic populations.
- Patients:Individual consumers purchasing devices without institutional reimbursement.
Homecare absorbs the highest unit volume while hospital tenders command the steepest price compression.
Usage Frequency:
Application intensity maps directly to disease severity and insulin dependence, with type 1 diabetics testing 4-10 times daily against type 2 patients on oral medications testing weekly.
- Daily:Multiple daily fingerstick or CGM sensor readings for insulin-dependent diabetics adjusting dosing in real time. Type 1 segments in Moscow and Saint Petersburg drive sensor subscription revenue; continuous glucose monitor adoption eliminates fingerstick routines for pump users.
- Weekly:Periodic monitoring for type 2 patients on stable oral medication regimens. Regional clinics beyond the Trans-Siberian rail corridor struggle with patient compliance due to test strip availability gaps.
- Monthly:Occasional verification testing for prediabetic or well-controlled patients.
- Occasionally:Situational testing during illness or medication changes.
Daily testing commands the highest consumable throughput while weekly monitoring represents the largest addressable patient pool.
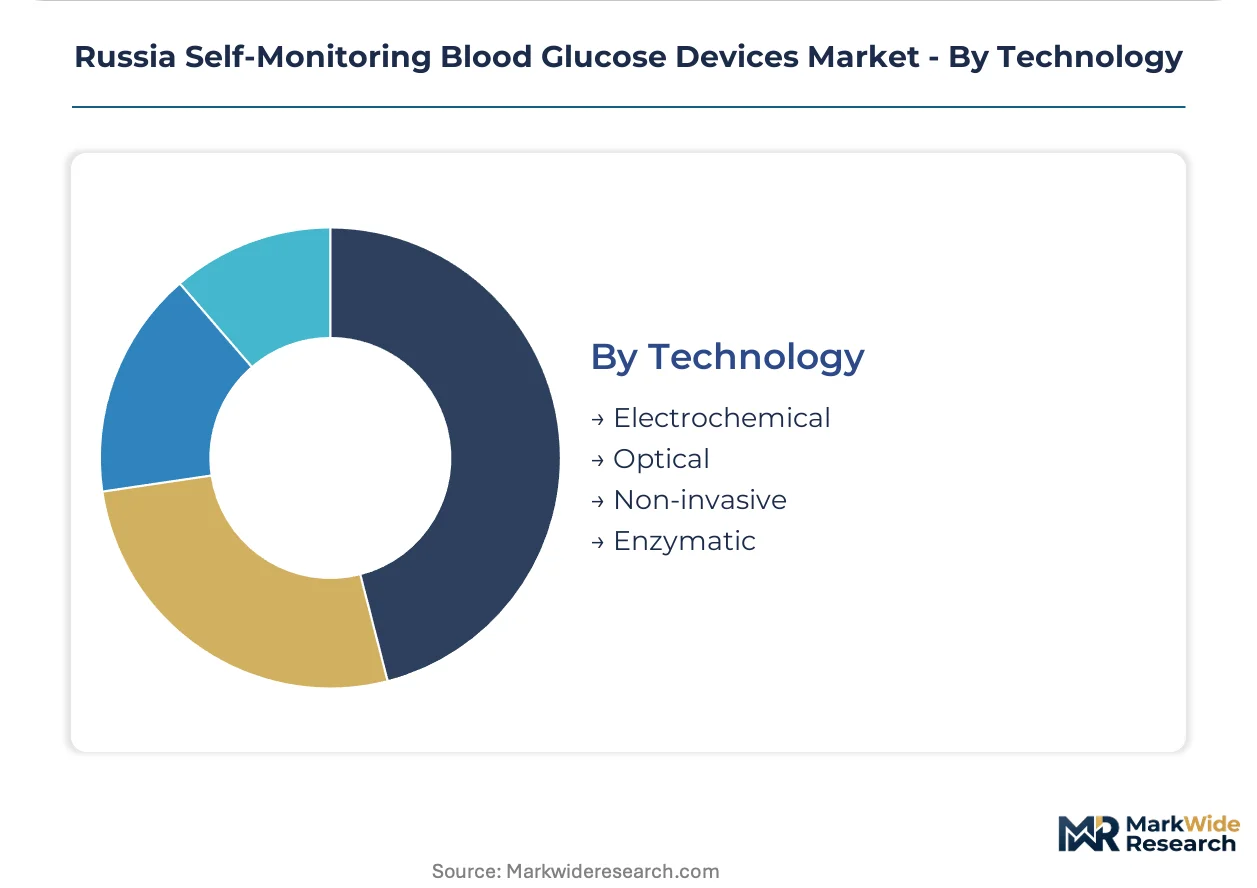
Technology:
Supply concentration in biosensor enzymes shapes technology accessibility, with glucose oxidase formulation expertise concentrated in German and Japanese specialty chemical houses limiting Russian domestic alternatives.
- Electrochemical:Amperometric biosensors measuring current generated by enzyme-mediated glucose oxidation. Dominates glucometer architecture due to low unit cost and established GOST-R certification pathways; cold-chain logistics partnerships across the Baikal-Amur Mainline rail corridor sustain Siberian distribution.
- Optical:Photometric detection of color change in enzyme-reactive strips or transdermal spectroscopy. Affluent Moscow and Saint Petersburg diabetics adopt premium homecare units at triple the rate of electrochemical alternatives; calibration-free operation reduces patient error.
- Enzymatic:Glucose-specific catalytic reactions using glucose oxidase or dehydrogenase formulations.
- Non-invasive:Transdermal or interstitial fluid measurement without blood extraction.
Electrochemical technology holds the installed base while optical methods climb the fastest in premium homecare segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moscow and Saint Petersburg concentrate procurement volume for premium glucometers and continuous glucose monitors, while Siberian and Far East federal districts operate on extended test strip inventory cycles that reshape patient compliance patterns.
Central Federal District
Moscow anchors hospital procurement through centralized tenders favoring brands with local clinical trial data. Roszdravnadzor's post-market surveillance requirements filter device registrations based on Russian patient accuracy studies. Endocrinology centers in the capital drive telemedicine-integrated subscription models for remote glycemic monitoring.
Northwestern Federal District
Saint Petersburg's retail pharmacy density sustains brand loyalty programs for homecare patients. The Ministry of Health's chronic disease management subsidies extend capillary glucose testing to elderly populations in surrounding Leningrad Oblast. Cold-chain distribution partnerships serve Arkhangelsk and Murmansk clinics with 45-day replenishment windows.
Siberian Federal District
Regional clinics beyond the Trans-Siberian rail corridor face 60-90 day test strip stockouts due to Baikal-Amur Mainline logistics constraints. Federal district purchasing centers in Irkutsk now aggregate procurement authority from individual municipal facilities. Novosibirsk state hospitals pilot connected meter deployment against paper-based glucose logbook resistance.
Far Eastern Federal District
Vladivostok procurement hubs consolidate tenders for Primorsky Krai and Sakhalin healthcare networks. EAEU technical regulations enable cross-border test strip flows from Kazakhstan into Amur Oblast border regions. Khabarovsk clinics struggle with patient compliance gaps tied to supply availability rather than device cost.
Volga Federal District
Import substitution grants in Kaluga and Ulyanovsk regions incentivize local medical device manufacturing. Samara and Kazan state tenders prioritize unit cost over connectivity features in glucometer selection. Regional endocrinology networks lag Moscow in continuous glucose monitor adoption for insulin pump users.
Russia Self-Monitoring Blood Glucose Devices Market Competitive Landscape
Capability concentration sits with multinational diagnostic specialists possessing established Roszdravnadzor registration pathways; scale advantage sits with diversified health technology conglomerates leveraging dense retail pharmacy presence. The vendor base organizes around three strategic archetypes: premium sensor platform developers, mid-tier price competitors in regional tenders, and emerging local assemblers capturing import substitution incentives. Consolidation pressure intensifies as federal district purchasing centers aggregate procurement authority. Dominant competitive moves include strategic partnerships for cold-chain logistics spanning Siberian rail corridors and portfolio diversification into subscription-based test strip replenishment.
Among the established multinational tier, Abbott Diabetes Care and Roche Holding AG anchor hospital procurement contracts through Moscow clinical trial partnerships and retail pharmacy density across federal districts. LifeScan occupies a position exemplifying price-focused competition in regional state tenders beyond capital cities. These three entities represent the spectrum from premium platform development to scale-driven regional penetration.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Roche Holding AG |
| LifeScan |
| Trividia Health |
| Ascensia Diabetes Care |
| Acon Laboratories Inc |
| Agamatrix Inc |
| Bionime Corporation |
| Arkray Inc |
| Others |
Pricing and Supply Chain Analysis
Kaluga and Ulyanovsk manufacturing clusters anchor domestic assembly capacity, yet their limited glucose oxidase formulation capability leaves pricing power concentrated with German and Japanese specialty chemical suppliers who command premium terms for enzyme electrode substrates.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement through Moscow centralized tenders, while retail pharmacy channels operate on spot purchasing with 30-day replenishment cycles. Three-tier pricing structure across premium, standard, and economy levels separates factory-calibrated CGM sensor subscriptions from basic electrochemical glucometers and regional clinic tenders. Cost compression in the standard tier is intensifying because federal district purchasing centers aggregate volume and squeeze unit margins. Regional state clinics exhibit highest price sensitivity; affluent Moscow homecare patients show lowest sensitivity to premium optical device pricing.
Supply Chain Analysis
Glucose oxidase and dehydrogenase formulations feed from German and Japanese specialty chemical houses, while electrochemical biosensor assembly draws from Chinese and South Korean substrate suppliers. Russian domestic production rests on imported enzyme electrodes, PET substrate films, and precision lancet springs. Single-source vulnerability in enzyme formulation expertise exposes margins to supply disruption. Distribution runs through cold-chain logistics partnerships spanning the Baikal-Amur Mainline rail corridor to reach Siberian and Far East federal districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's self-monitoring blood glucose sector sits in early-cycle expansion as homecare protocol extensions from the Ministry of Health widen capillary glucose testing access to rural elderly populations previously dependent on clinic visits.
For Market Incumbents: Harden Roszdravnadzor registration pathways through Moscow clinical trial partnerships to accelerate 14-18 month approval windows that freeze out competitors. Deepen backward integration into test strip manufacturing via Kaluga import substitution grants to offset yuan-ruble volatility exposure from Chinese substrate suppliers. For New Entrants and Emerging Players: Build out replenishment service contracts for Siberian clinics beyond the Trans-Siberian rail corridor where 60-90 day stockout cycles create white-space demand. Target telemedicine-integrated subscription models linking regional patients to Moscow endocrinology centers as the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management infrastructure play because diabetes prevalence and elderly population growth sustain consumable demand regardless of device technology shifts. Acquisition targets should cluster around cold-chain logistics specialists with Baikal-Amur Mainline coverage. Watch federal district tender aggregation trends as the inflection signal for procurement power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Roszdravnadzor Registration Investment | Accelerates market entry through Moscow clinical trial partnerships and real-world accuracy study submissions. |
| Siberian Cold-Chain Logistics Partnership | Secures 45-day replenishment windows for Arkhangelsk and Murmansk clinics against 90-day stockout competitors. |
| Telemedicine Platform Integration | Enables subscription-based device-and-service bundling with Moscow endocrinology center data transmission. |
| Local Test Strip Manufacturing Scale-Up | Captures Kaluga and Ulyanovsk import substitution grants to offset EAEU tariff exposure on imported substrates. |
| CGM Sensor Subscription Development | Factory-calibrated sensor pods eliminate fingerstick routines and capture type 1 insulin pump user migration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Roszdravnadzor registration databases, Ministry of Health reimbursement list revisions, and EAEU technical regulation filings. Primary interviews engaged biomedical engineers at Moscow endocrinology centers, GPO contracts managers at federal district purchasing hubs, and procurement leads at regional state hospitals across Siberian and Far East networks. Secondary validation drew from hospital procurement databases, retail pharmacy inventory audits, and customs records tracking enzyme electrode substrate imports. Bottom-up patient population modeling triangulated against top-down manufacturer shipment data.
Forecast inputs span device type replacement cycles, regional reimbursement coverage expansion, and technology substitution rates between electrochemical and optical detection methods across the analysis window. Segmentation dimensions modeled include device type, end user archetype, usage frequency intensity, and technology platform. CAGRs derived from logistic adoption curve fitting calibrated to historical penetration data. Industry-specific inputs incorporate Ministry of Health chronic disease program enrollment trajectories and EAEU cross-border test strip flow volumes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese substrate suppliers to forward-integrate into finished glucometer assembly would shift outcomes substantially. Cross-checking against EAEU medical device trade flow statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Germany Continuous Glucose Monitoring Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
Global Non-Invasive Blood Glucose Monitoring Devices Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
Global Diabetes Pen Market