
 South Africa Continuous Glucose Monitoring Market | 2026-2036
South Africa Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Continuous Glucose Monitoring Market Insights
CE marking alignment under South Africa's updated medical device regulations is shifting the cost-of-entry calculus for CGM manufacturers seeking SAHPRA registration. Abbott Laboratories leverages its FreeStyle Libre manufacturing scale to anchor sensor supply across southern African distribution channels. Dexcom Inc. competes through real-time alert differentiation for intensive insulin therapy patients. Medtronic PLC sustains integrated pump-CGM system positioning within private diabetes clinic networks.
Continuous glucose monitoring comprises a wearable sensor measuring interstitial glucose via enzymatic electrochemical reaction, transmitting data to a receiver or smartphone for trend analysis and hypo/hyperglycemia alerting. Flash glucose monitoring leads product adoption in South Africa due to lower per-scan cost and reduced calibration burden versus real-time systems. Diabetes management applications dominate clinical deployment, while sports medicine represents an emerging segment where athletic performance programs trial glucose telemetry for metabolic optimization.
SAHPRA medical device registration requirements, coupled with ISO 15197 glucose meter accuracy standards and the National Department of Health's Essential Medicines List Committee reviews, shape product qualification timelines and public sector procurement eligibility. Private payer reimbursement policies from schemes like Discovery Health and Bonitas Medical Fund determine out-of-pocket exposure for home care users. Stakeholders must monitor NHI benefit design negotiations and SAHPRA's accelerated review pathway decisions to time market entry and channel investment.
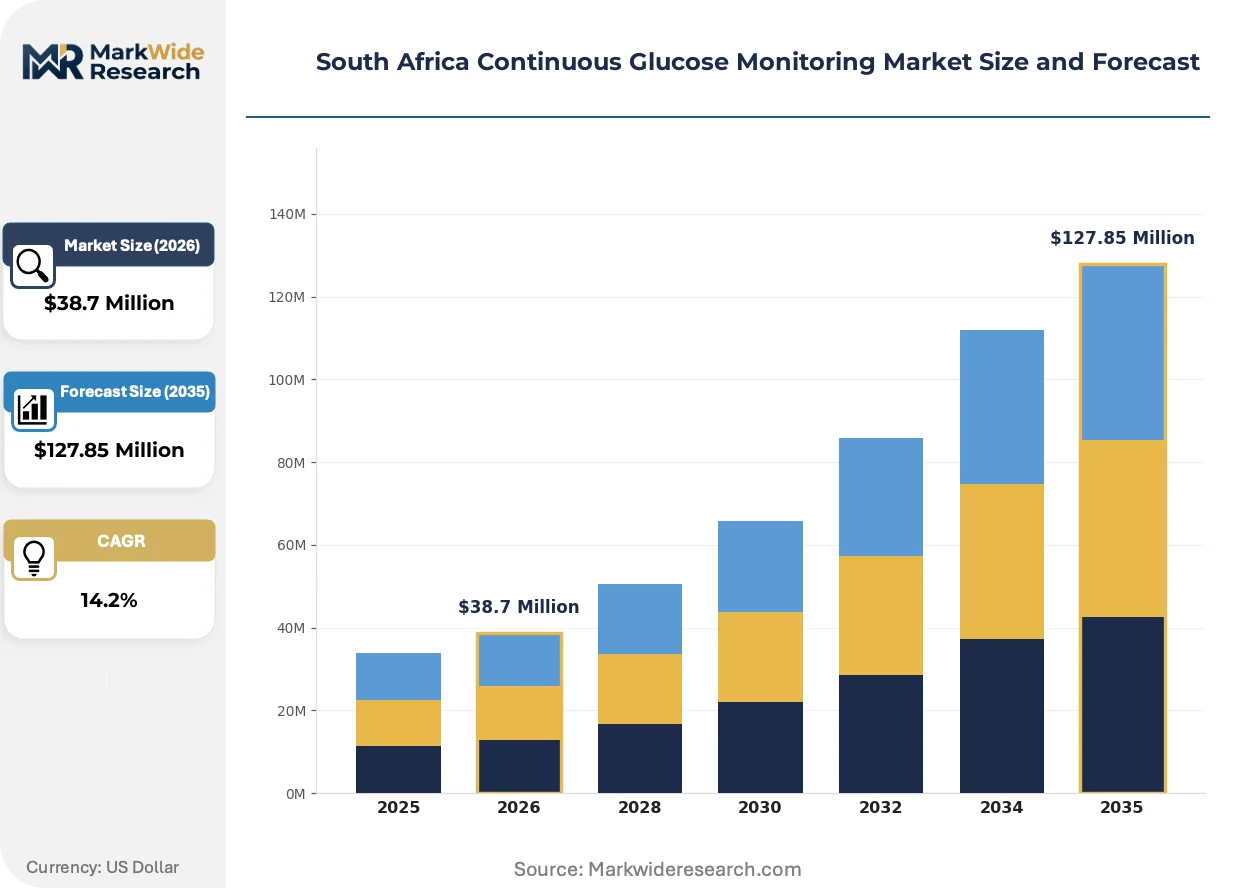
Market Dynamics
SAHPRA's updated medical device regulations are compressing registration timelines for CGM manufacturers while simultaneously elevating compliance costs, creating a structural filter that favors scaled suppliers with established southern African distribution infrastructure.
Growth Catalysts
- National Health Insurance framework:The NHI benefit design negotiations are creating reimbursement clarity for outpatient diabetes technology, expanding addressable patient pools beyond private scheme coverage.
- Urban specialist concentration:Endocrinology clinics in Gauteng and Western Cape are standardizing CGM protocols for type 1 diabetes management, generating referral network effects.
- Electrochemical sensor advances:Factory-calibrated enzymatic glucose detection is eliminating fingerstick calibration burdens, reducing clinical training requirements for device deployment.
Market Restraints
- Import-dependent supply chain:Sensor manufacturing concentration in European and North American facilities exposes distributors to currency volatility and shipping delays.
- SAHPRA registration friction:CE marking alignment requirements extend product qualification timelines by 12-18 months versus historical pathways, freezing capital in regulatory limbo.
- Flash glucose dominance:Real-time CGM systems face substitution pressure from lower-cost interstitial scanning alternatives in price-sensitive patient segments.
Strategic Opportunities
- Sports medicine telemetry:Athletic performance programs in Cape Town and Johannesburg are trialing glucose monitoring for metabolic optimization during endurance training protocols.
- Public sector procurement:Essential Medicines List Committee reviews may unlock hospital tender opportunities for inpatient glycemic control systems.
- Smartphone integration:Bluetooth-enabled transmitter-to-app connectivity is eliminating dedicated receiver hardware, opening direct-to-consumer channel possibilities.
Industry Challenges
- Diabetes educator scarcity:Certified training capacity for CGM onboarding lags device availability in secondary cities, constraining patient activation rates.
- Pump-CGM integration complexity:Closed-loop algorithm validation requires specialized biomedical engineering skills that cluster in academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Continuous Glucose Monitoring Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $127.85 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor, Transmitter, Receiver, Integrated System Technology: Flash Glucose Monitoring, Real-Time Continuous Monitoring, Non-Invasive, Invasive End User: Hospitals, Home Care, Diabetes Clinics, Healthcare Providers Application: Diabetes Management, Clinical Research, Sports Medicine, Preventive Healthcare |
| Companies Covered | Abbott Laboratories, Dexcom Inc., Medtronic PLC, Ascensia Diabetes Care, GlySens, F. Hoffmann-La Roche, Senseonics Holdings Inc, Thermo Fisher Scientific Inc, Aidex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Continuous Glucose Monitoring Market Trends and Innovations
Sensor miniaturization and algorithmic prediction capabilities are compressing the functional gap between flash and real-time systems, while reimbursement policy evolution is determining which patient segments access which technology tier.
Factory-calibrated electrochemical glucose sensing is consolidating market structure around three dominant form factors: implantable long-duration sensors, adhesive patch transmitters, and smartphone-integrated receivers. Private hospital networks in Gauteng are adopting the patch-transmitter configuration fastest, drawn by reduced nursing workload for inpatient glucose surveillance. This consolidation is compressing margins for distributors carrying multiple competing sensor brands.
SAHPRA's accelerated review pathway for devices with prior CE marking or FDA clearance is compressing registration timelines for established manufacturers while elevating documentation burdens for first-time entrants. The industrial consequence is a two-tier approval system where precedent holders access market entry faster. Real-time CGM systems with alert functionality are responding most aggressively, leveraging existing European regulatory dossiers.
Discovery Health and Bonitas Medical Fund are unbundling device procurement from specialist consultation fees, shifting financial risk to patients for sensor replacement cycles. Direct pharmacy distribution is displacing clinic-mediated fulfillment in metropolitan areas where retail pharmacy chains maintain cold-chain logistics. This channel rotation is most visible in Johannesburg's northern suburbs, where patients with established diabetes self-management skills prefer self-directed resupply.
South Africa Continuous Glucose Monitoring Market Segmentation
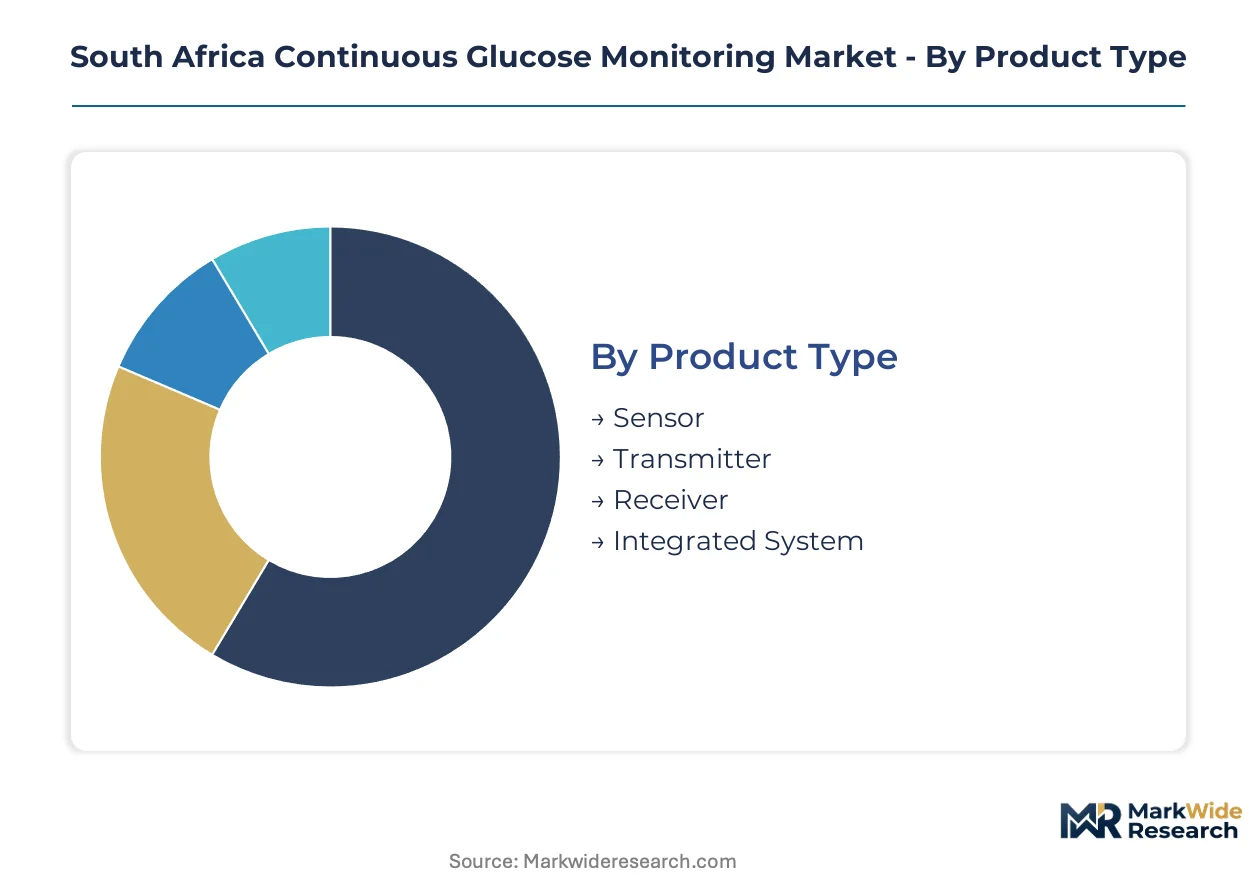
CGM market segmentation in South Africa reflects divergent reimbursement pathways, patient self-management capabilities, and clinical infrastructure density across provinces. Product form factors, transmission protocols, and care settings each create distinct commercial entry points for manufacturers navigating SAHPRA registration and private payer negotiations.
Product Type:
Disposable versus durable component economics differentiate procurement patterns across private hospital networks and retail pharmacy channels.
- Sensor:Enzymatic electrochemical strips with 10-14 day wear duration constitute the highest-volume consumable, with demand concentrating in Johannesburg and Cape Town retail pharmacies where Discovery Health members process recurring prescriptions. SAHPRA's cold-chain import requirements elevate landed costs for glucose oxidase formulations.
- Transmitter:Bluetooth-enabled adhesive patch devices attach to sensors for data relay, dominating inpatient deployments at Netcare hospitals in Gauteng where nursing staff monitor centralized glucose dashboards. Battery life limitations drive 90-day replacement cycles.
- Receiver:Dedicated handheld display units persist among elderly type 1 diabetes patients in Pretoria and Durban who lack smartphone proficiency. Declining shipments reflect direct-to-app connectivity adoption.
- Integrated System:Pump-sensor closed-loop configurations serve intensive insulin therapy patients at academic medical centers in Bloemfontein and Stellenbosch, requiring specialized endocrinology training for algorithm calibration.
Sensor volumes lead procurement today; integrated systems are gaining share fastest among newly diagnosed type 1 patients with private coverage.
Technology:
Calibration burden and alert sophistication separate patient segments by therapy intensity and price sensitivity.
- Flash Glucose Monitoring:Factory-calibrated interstitial scanning via handheld reader dominates home care in South Africa's middle-income segments, with Bonitas Medical Fund coverage driving adoption in Port Elizabeth and East London. Elimination of fingerstick confirmation reduces HbA1c testing frequency.
- Real-Time Continuous Monitoring:Automated hypo/hyperglycemia alerts with predictive algorithms command premium reimbursement at Mediclinic facilities in the Western Cape, where endocrinologists prioritize nocturnal glucose surveillance for pediatric patients.
- Non-Invasive:Optical and thermal glucose sensing technologies remain pre-commercial in South Africa, with local clinical trials at University of Cape Town evaluating spectroscopic accuracy against ISO 15197 standards.
- Invasive:Traditional fingerstick-reliant systems persist in public sector facilities awaiting Essential Medicines List Committee CGM inclusion, concentrated in rural KwaZulu-Natal clinics with intermittent electricity.
Flash glucose monitoring anchors volume today; real-time systems are expanding most quickly among urban specialist practices.
End User:
Care setting determines device complexity, training requirements, and reimbursement coding.
- Hospitals:Private hospital networks in Gauteng standardize patch-transmitter systems for perioperative glycemic control, with Life Healthcare facilities negotiating volume-based sensor procurement.
- Home Care:Self-directed patients in Johannesburg's northern suburbs favor pharmacy-direct resupply, bypassing clinic-mediated fulfillment.
- Diabetes Clinics:Endocrinology specialist practices in Cape Town generate referral network effects for CGM onboarding, though certified educator scarcity constrains activation in secondary cities.
- Healthcare Providers:General practitioner adoption lags due to SAHPRA device registration knowledge gaps and limited consultation fee structures for remote monitoring interpretation.
Hospital procurement leads volumes today; home care channels are climbing the fastest as smartphone integration eliminates receiver hardware.
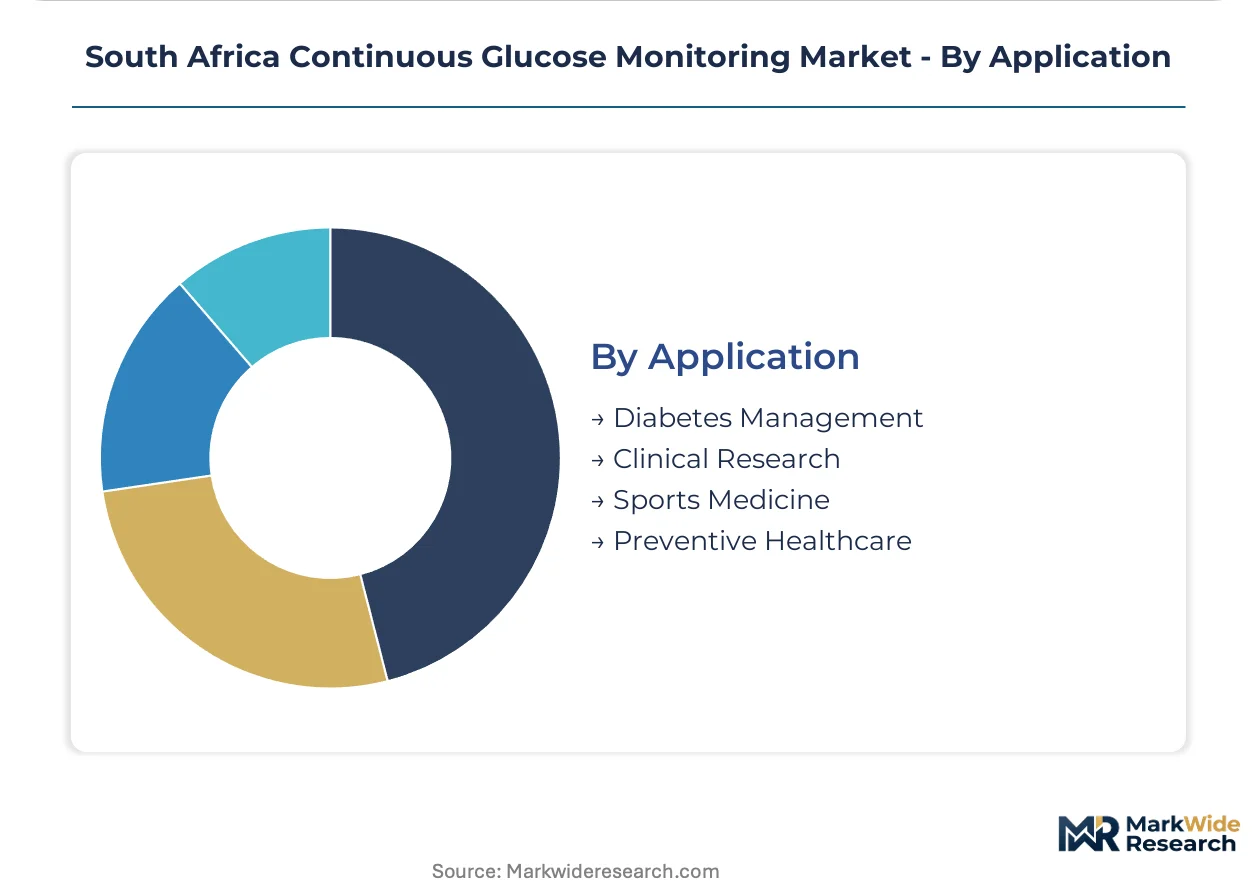
Application:
Clinical purpose shapes sensor accuracy requirements, data integration needs, and patient population targeting.
- Diabetes Management:Type 1 insulin dosing optimization drives the core installed base, with HbA1c reduction targets motivating private payer coverage at Discovery Health.
- Clinical Research:Pharmaceutical trials at South African Medical Research Council facilities employ CGM for glucose variability endpoints, requiring SAHPRA investigational device exemptions.
- Sports Medicine:Endurance training programs in Cape Town and Johannesburg trial metabolic telemetry, with performance coaches purchasing sensors outside medical reimbursement channels.
- Preventive Healthcare:Prediabetes screening applications remain nascent, concentrated in corporate wellness programs at mining sector employers in the North West province.
Diabetes management commands volume today; sports medicine shows the steepest expansion trajectory among non-reimbursed consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Endocrinology specialist concentration in Gauteng and the Western Cape anchors South Africa's CGM demand geography. Provincial health infrastructure disparities create divergent adoption trajectories across the country's nine provinces.
Gauteng
Private hospital networks in Johannesburg and Pretoria drive sensor procurement volumes for inpatient glycemic control. Discovery Health's headquarters proximity shapes reimbursement policy experimentation in the province. Netcare and Life Healthcare facilities in Sandton standardize patch-transmitter systems for perioperative monitoring.
Western Cape
Mediclinic facilities in Cape Town prioritize real-time CGM with predictive alerts for pediatric type 1 diabetes patients. The province's medical research cluster at Stellenbosch University generates clinical trial demand for glucose variability endpoints. Sports medicine programs in Cape Town trial metabolic telemetry for endurance athlete optimization.
KwaZulu-Natal
Public sector facilities in Durban and rural clinics await Essential Medicines List Committee CGM inclusion. Intermittent electricity infrastructure constrains cold-chain sensor storage in peripheral districts. Private scheme coverage through Bonitas Medical Fund drives adoption in Port Elizabeth referral networks.
Eastern Cape
Secondary city diabetes educator scarcity constrains patient activation rates in East London and Mthatha. Academic medical center partnerships with Stellenbosch extend training capacity for closed-loop algorithm calibration. Rural clinic networks rely on fingerstick systems pending SAHPRA registration of flash glucose alternatives.
South Africa Continuous Glucose Monitoring Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Africa's CGM procurement channels. The market structure concentrates around three scaled suppliers with established southern African distribution infrastructure. Strategic archetypes separate manufacturing-scale players from alert-differentiation specialists and integrated pump-system vendors. Competitive moves center on SAHPRA registration timeline acceleration and private payer reimbursement unbundling.
Within the manufacturing-scale tier, Abbott Laboratories leverages FreeStyle Libre production volume to anchor sensor supply across pharmacy and hospital channels. Dexcom Inc. occupies the alert-differentiation position for intensive insulin therapy patients requiring real-time hypo/hyperglycemia surveillance. Medtronic PLC exemplifies the integrated-system archetype through pump-CGM closed-loop positioning within private diabetes clinic networks.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom Inc. |
| Medtronic PLC |
| Ascensia Diabetes Care |
| GlySens |
| F. Hoffmann-La Roche |
| Senseonics Holdings Inc |
| Thermo Fisher Scientific Inc |
| Aidex |
| Others |
Pricing and Supply Chain Analysis
Certified diabetes educator concentration in Gauteng and the Western Cape creates labor-cost differentials that widen pricing-tier spreads between metropolitan specialist clinics and secondary city general practices, with remote training capacity constraints forcing premium markups for onboarding-intensive real-time CGM systems.
Pricing Analysis
Bundled device-plus-specialist consultation packages at Mediclinic and Netcare facilities command premium reimbursement rates, while unbundled sensor-only procurement through retail pharmacy channels exposes patients to full replacement-cycle costs. Price differentiation rests on alert sophistication and calibration burden, with factory-calibrated flash systems capturing price-sensitive Bonitas Medical Fund members and predictive real-time systems serving Discovery Health's intensive insulin therapy tier. Pricing pressure stems from Discovery Health and Bonitas unbundling procurement from consultation fees, shifting financial risk to patients. General practitioner clinics exhibit highest price sensitivity due to unfunded device interpretation workflows, while academic medical centers show lowest sensitivity given research grant offsets.
Supply Chain Analysis
Enzymatic glucose oxidase formulations for sensor manufacturing rest on European and North American specialty chemical producers, with final assembly concentrated in Ireland, Germany, and the United States. Raw material dependencies include glucose oxidase enzyme batches, biocompatible adhesive polymers, and Bluetooth transmitter chipsets. Supply chain risk centers on single-source vulnerability for cold-chain enzyme formulations subject to SAHPRA import documentation delays. Distribution runs through hospital procurement consortia in Gauteng and Western Cape, with pharmacy-direct fulfillment gaining share in Johannesburg's northern suburbs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's Continuous Glucose Monitoring Market functions as a regulatory compounder, where SAHPRA's CE marking alignment requirements and National Health Insurance benefit design negotiations create successive demand inflection points that reward precedent holders with accelerated market access.
For Market Incumbents: Anchor manufacturing-scale advantages through FreeStyle Libre production volume commitments to southern African distributors, insulating against currency volatility that squeezes import-dependent competitors. Defend against real-time CGM substitution by embedding flash glucose protocols within Netcare and Life Healthcare perioperative glycemic control standards. Prioritize SAHPRA accelerated review pathway maintenance to preserve 12-18 month registration timeline advantages over first-time entrants. For New Entrants and Emerging Players: Rural diabetes clinics in KwaZulu-Natal and Eastern Cape represent an underserved buyer archetype awaiting Essential Medicines List Committee CGM inclusion, with fingerstick-dependent workflows creating immediate upgrade demand upon public sector reimbursement unlocking. Sports medicine programs in Cape Town and Johannesburg offer consumer-funded entry outside medical reimbursement channels, with performance coaches purchasing direct for metabolic telemetry trials. Pursue smartphone-integrated transmitter-to-app connectivity to bypass dedicated receiver hardware costs and enable direct-to-consumer channel experimentation. For Investors and Strategic Acquirers: Diversified medical device conglomerates with established SAHPRA registration dossiers are the most active acquirer in this space, seeking bolt-on CGM capabilities to complement existing diabetes portfolios. Long-term viability hinges on NHI benefit design finalization and the pace of public sector procurement unlocking. Target acquisition archetypes include regional distributors with cold-chain logistics infrastructure and established relationships with Discovery Health and Bonitas Medical Fund. Watch SAHPRA investigational device exemption grants for sports medicine and clinical research applications as demand expansion signals.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Accelerated Review Pathway | CE marking alignment compresses registration timelines for precedent holders versus 12-18 month delays for new entrants. |
| NHI Benefit Design Negotiation | Reimbursement clarity for outpatient diabetes technology expands addressable patient pools beyond private scheme coverage. |
| Smartphone Integration Development | Bluetooth-enabled transmitter-to-app connectivity eliminates dedicated receiver hardware and opens direct-to-consumer channels. |
| Hospital System Partnership | Netcare and Life Healthcare volume-based sensor procurement standardizes patch-transmitter systems for inpatient glycemic control. |
| Diabetes Educator Training Scale-Up | Certified training capacity expansion in secondary cities unlocks patient activation rates currently constrained by workforce scarcity. |
Research Methodology
Coverage spans South Africa's nine provinces with primary inputs from each, combining structured interviews with endocrinologists, hospital procurement managers, biomedical engineers at academic medical centers, and pharmacy chain category buyers with secondary validation. Primary sources included SAHPRA registration databases, National Department of Health Essential Medicines List Committee review documentation, Discovery Health and Bonitas Medical Fund reimbursement policy filings, and private hospital network procurement contracts. Secondary sources encompassed hospital procurement databases, medical device import customs records, and GPO contract repositories. Bottom-up sensor volume modeling triangulated against top-down market value estimates derived from payer claims data.
Granularity-level framing applied province-level modeling for Gauteng, Western Cape, KwaZulu-Natal, and Eastern Cape, with product-type segmentation at sensor-transmitter-receiver-integrated system resolution and technology-tier differentiation between flash and real-time systems. CAGRs were derived from patient population growth projections, reimbursement policy evolution scenarios, and SAHPRA registration timeline assumptions across the analysis window. Forecast inputs incorporated type 1 diabetes prevalence trends, private medical scheme coverage rates, and endocrinology specialist concentration by metropolitan area.
Underlying measurement precision varies by segment; hospital procurement volumes carry tighter precision than home care channel estimates due to consolidated purchasing data availability. Forecasts reflect assumptions around NHI implementation pace, SAHPRA review pathway consistency, and currency stability for import-dependent supply chains. Regulatory delay risks, diabetes educator training bottlenecks, and public sector reimbursement timing uncertainty warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Global Needle Free Diabetes Care Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
France Diabetes Devices Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market