
 Global Non-Invasive Blood Glucose Monitoring Devices Market | 2026-2036
Global Non-Invasive Blood Glucose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Invasive Blood Glucose Monitoring Devices Market Foresight
The capital-intensity divergence between established diagnostic giants and emerging sensor startups is unwinding traditional competitive moats in non-invasive glucose monitoring. Abbott Laboratories leverages decades of electrochemical expertise to sustain regulatory credibility across multiple jurisdictions. Nemaura Medical competes through specialized focus on transdermal patch platforms that occupy a distinct price-performance tier. Know Labs positions its spectroscopy approach to navigate the gap between consumer wellness and clinical-grade accuracy requirements.
Non-invasive blood glucose monitoring devices employ optical, electromagnetic, or bioimpedance sensing modalities to estimate blood glucose levels without percutaneous blood sampling, typically achieving measurement frequencies from once per minute to continuous streaming via wearable form factors. These systems serve diabetes management, fitness tracking, and remote patient monitoring applications where patient compliance and real-time data transmission drive clinical and commercial value. Optical sensors dominate current deployment volumes due to mature photonics supply chains and established algorithm libraries for near-infrared spectroscopy. Transdermal sensors represent the fastest-expanding segment as microneedle-adjacent platforms close accuracy gaps with minimal skin breach. Patch sensors within the deployment dimension concentrate margin pools through recurring consumable revenue models and pharmacy channel integration.
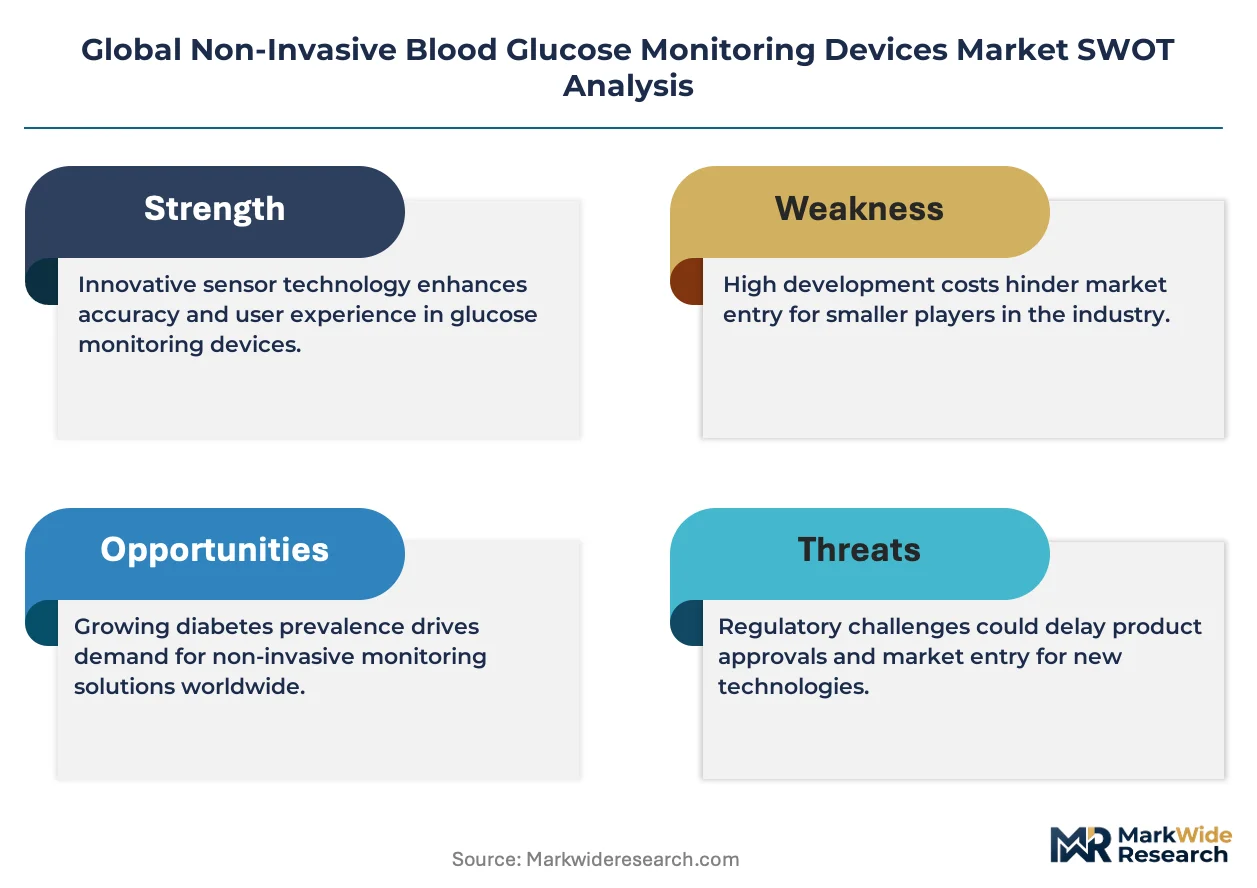
FDA breakthrough device pathways and the EU Medical Device Regulation shape market access timelines, with the former compressing premarket review for novel non-invasive platforms and the latter imposing post-market surveillance obligations that favor companies with established quality management systems. Japan's PMDA has introduced streamlined approval tracks for software-as-medical-device glucose analytics, creating additional geographic complexity for multi-regional launches. Stakeholders must monitor evolving reimbursement decisions by CMS and Germany's Federal Joint Committee, as these determinations will decide whether non-invasive devices displace fingerstick meters in standard-of-care protocols or remain confined to wellness-adjacent segments.
Market Dynamics
Reimbursement policy fragmentation across major healthcare systems is fragmenting commercialization pathways for non-invasive glucose monitoring platforms, forcing manufacturers to pursue parallel regulatory strategies rather than sequential market entry.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited premarket review timelines compress commercialization cycles for novel optical and bioimpedance platforms, reducing capital requirements for regulatory clearance.
- Home Care Provider Expansion:Post-acute care networks in the United States and Germany are procuring wearable patch sensors to reduce hospital readmission penalties and enable remote patient monitoring reimbursement.
- Microneedle-Adjacent Transdermal Platforms:Advances in minimally invasive interstitial fluid extraction are closing accuracy gaps with traditional continuous glucose monitors while eliminating calibration requirements.
Market Restraints
- Photonics Component Concentration:Near-infrared laser diode supply chains concentrate in East Asian foundries, exposing manufacturers to input volatility and geopolitical sourcing risk.
- Clinical Validation Burden:EU Medical Device Regulation post-market surveillance obligations impose recurring clinical evidence generation costs that favor established quality management systems over emerging entrants.
- Invasive CGM Substitution Pressure:Dexcom and Abbott FreeStyle Libre devices achieve sub-10% mean absolute relative difference in glucose readings, setting accuracy benchmarks that non-invasive alternatives struggle to match consistently.
Strategic Opportunities
- Japan PMDA Software-as-Medical-Device Pathway:Streamlined approval tracks for algorithm-based glucose analytics create first-mover advantages for spectroscopy platforms with cloud-connected processing architectures.
- Pharmacy Channel Integration:Patch sensor consumable models align with CVS Health and Walgreens distribution networks, enabling recurring revenue capture through prescription fulfillment workflows.
- Fitness-Wellness Hybrid Positioning:Optical sensors with glucose trend indication (non-diagnostic) access consumer electronics retail channels without full medical device regulatory burden.
Industry Challenges
- Algorithm Training Data Scarcity:Diverse skin tone and tissue composition variations require expanded clinical trial cohorts, extending development timelines and raising recruitment costs for spectroscopy-based systems.
- Legacy EHR Integration Complexity:Hospital procurement committees demand HL7 FHIR compatibility and Epic Systems interoperability, forcing middleware development expenditures that strain early-stage sensor startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Invasive Blood Glucose Monitoring Devices Market |
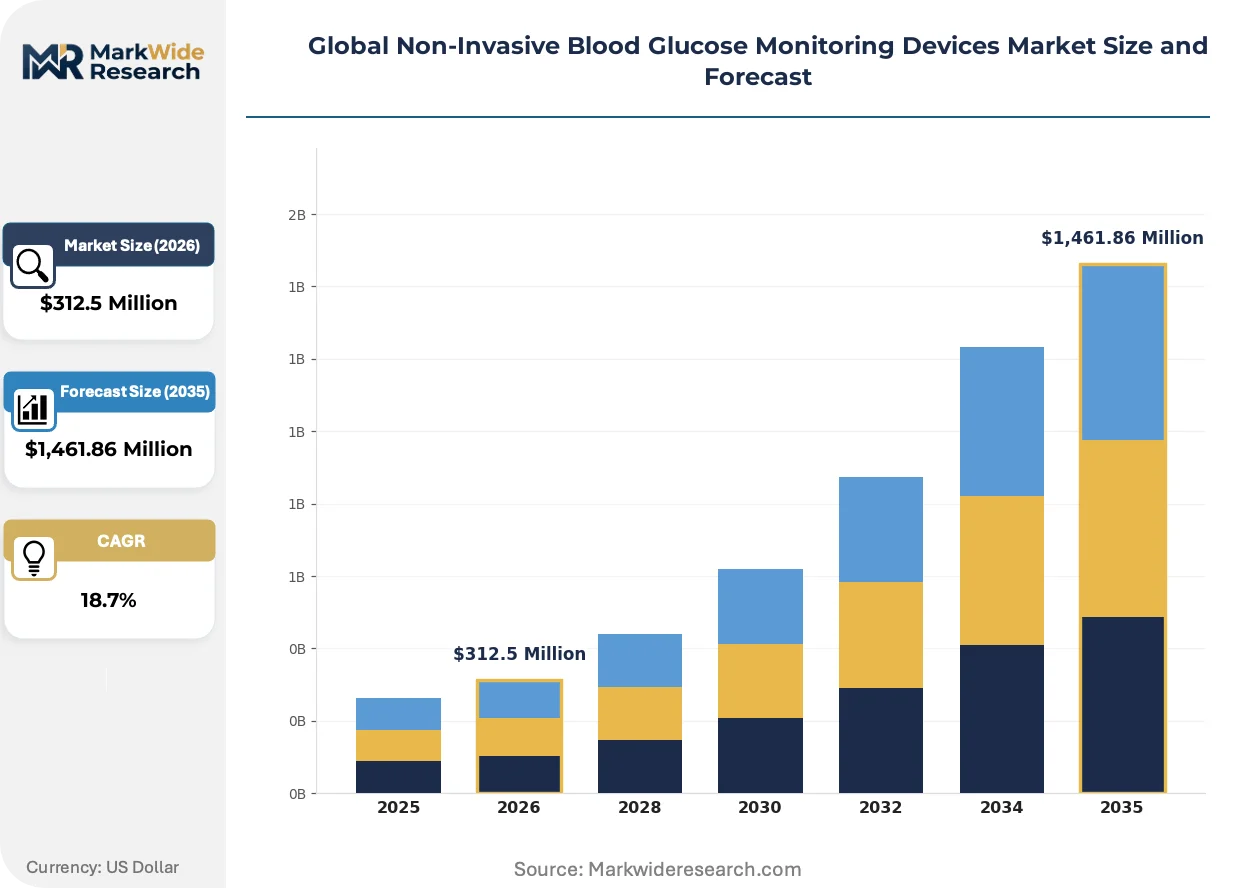
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sensors, Electromagnetic Sensors, Transdermal Sensors, Ultrasound Sensors, Bioimpedance Sensors Application: Diabetes Management, Fitness Tracking, Preventive Screening, Remote Patient Monitoring, Research Studies End User: Hospitals, Diagnostic Laboratories, Home Care Providers, Specialized Clinics, Wellness Centers Deployment: Wearable Devices, Handheld Devices, Patch Sensors, Embedded Systems, Mobile-Compatible Devices |
| Companies Covered | Abbott Laboratories, Medtronic, DexCom, Nemaura Medical, Senseonics, Afon Technology, Cnoga Digital Care, DiaMon Tech, Know Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Invasive Blood Glucose Monitoring Devices Market Shifts & Advancements
Multi-modal sensor fusion is eroding single-technology dominance in glucose estimation, as manufacturers combine optical, thermal, and bioimpedance signals to compensate for individual modality limitations in real-world use conditions.
Spectroscopy-based glucose estimation is decomposing the traditional accuracy-versus-comfort tradeoff in diabetes management. Home care providers in Germany are piloting combined near-infrared and Raman scattering devices for nocturnal hypoglycemia detection. This convergence is decomposing established procurement categories that previously separated consumer wellness from clinical-grade monitoring tiers.
EU Medical Device Regulation Class IIa reclassification for continuous glucose monitoring accessories is tightening post-market clinical follow-up requirements for algorithm updates. Manufacturers must submit periodic safety reports to notified bodies for software revisions that previously qualified as routine maintenance. Transdermal patch platforms with disposable microneedle arrays face the steepest compliance cost escalation, accelerating consolidation toward vertically integrated production models.
Patient self-monitoring behaviors are fragmenting across diagnostic and wellness use cases, with younger diabetes cohorts in the United States adopting glucose trend data for metabolic fitness optimization beyond glycemic control. Pharmacy benefit managers are responding with tiered formulary placement that distinguishes therapeutic continuous monitors from lifestyle-oriented sensors. This behavioral bifurcation is most pronounced in employer-sponsored health plans, where wellness program subsidies increasingly cover non-diagnostic glucose tracking devices.
Global Non-Invasive Blood Glucose Monitoring Devices Market Segmentation
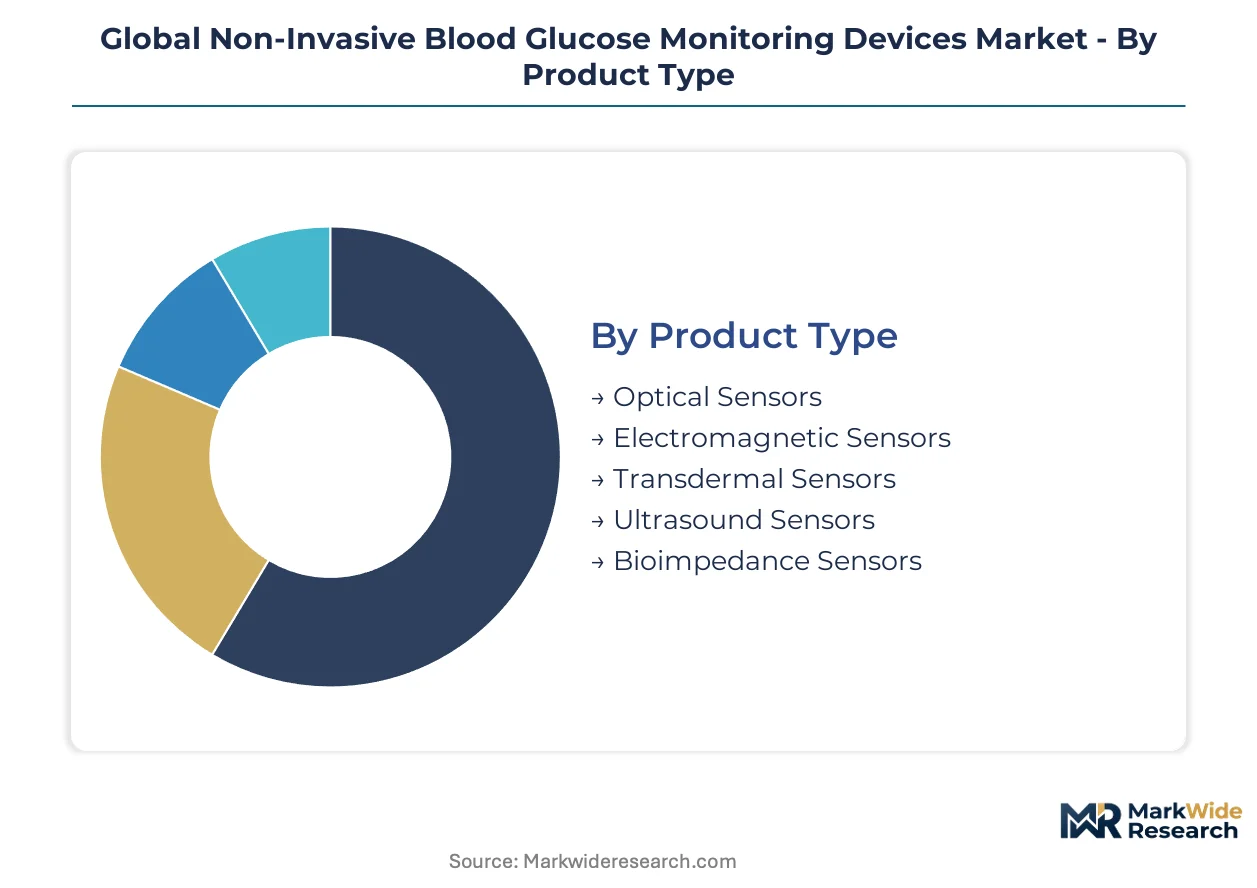
Technology modality and deployment form factor determine reimbursement eligibility and regulatory pathway complexity for non-invasive glucose monitoring. Manufacturers must align segment-specific value propositions with distinct clinical validation requirements across diabetes management and wellness applications.
Product Type:
Substitution pressure from invasive continuous glucose monitors varies sharply by sensing modality, with optical platforms facing the steepest accuracy benchmarks from Dexcom and Abbott FreeStyle Libre systems.
- Optical Sensors:Near-infrared and Raman spectroscopy devices leverage mature photonics supply chains from East Asian foundries. Demand concentrates in United States home care networks where FDA breakthrough designation accelerates premarket review timelines.
- Transdermal Sensors:Microneedle-adjacent interstitial fluid extraction platforms achieve measurement frequencies competitive with invasive alternatives. Germany's Federal Joint Committee reimbursement evaluations are driving procurement expansion in post-acute care settings.
- Electromagnetic Sensors:Dielectric spectroscopy approaches target wellness applications with reduced regulatory burden.
- Ultrasound Sensors:Acoustic-based glucose estimation remains confined to research validation phases.
- Bioimpedance Sensors:Electrical tissue property measurement appeals to fitness tracker integration.
Optical sensors retain volume leadership; transdermal sensors hold the steepest expansion curve.
Application:
Cost tier stratification separates therapeutic-grade devices eligible for pharmacy reimbursement from consumer wellness products distributed through electronics retail.
- Diabetes Management:Clinical-grade glycemic control applications require ISO 15197 accuracy compliance and EHR interoperability. Japan's PMDA software-as-medical-device pathway is streamlining algorithm-based analytics approval for cloud-connected architectures.
- Remote Patient Monitoring:Real-time data transmission to care teams reduces hospital readmission penalties under United States CMS reimbursement frameworks. Home care providers in Germany are piloting combined sensor platforms for nocturnal hypoglycemia detection.
- Fitness Tracking:Metabolic optimization for non-diabetic users accesses consumer channels without full medical device regulatory burden.
- Preventive Screening:Prediabetes population monitoring faces uncertain reimbursement classification.
- Research Studies:Academic validation cohorts drive algorithm training data generation.
Diabetes management commands margin concentration; remote patient monitoring is gaining share fastest.
End User:
Customer type determines procurement authority and purchasing cycle length, with hospital committees demanding middleware interoperability that strains early-stage sensor startups.
- Home Care Providers:Post-acute care networks procure wearable patch sensors to enable remote monitoring reimbursement. United States hospital readmission penalty structures are accelerating procurement timelines for wireless glucose transmission platforms.
- Specialized Clinics:Endocrinology practices integrate non-invasive devices into diabetes education programs. Germany's ambulatory care reimbursement evolution is expanding prescribing authority for transdermal platforms.
- Hospitals:Inpatient glycemic management requires HL7 FHIR compatibility and Epic Systems integration.
- Diagnostic Laboratories:Centralized reference testing competes with point-of-care alternatives.
- Wellness Centers:Employer-sponsored health plan subsidies increasingly cover lifestyle-oriented glucose tracking.
Home care providers anchor current demand; specialized clinics are expanding most quickly.
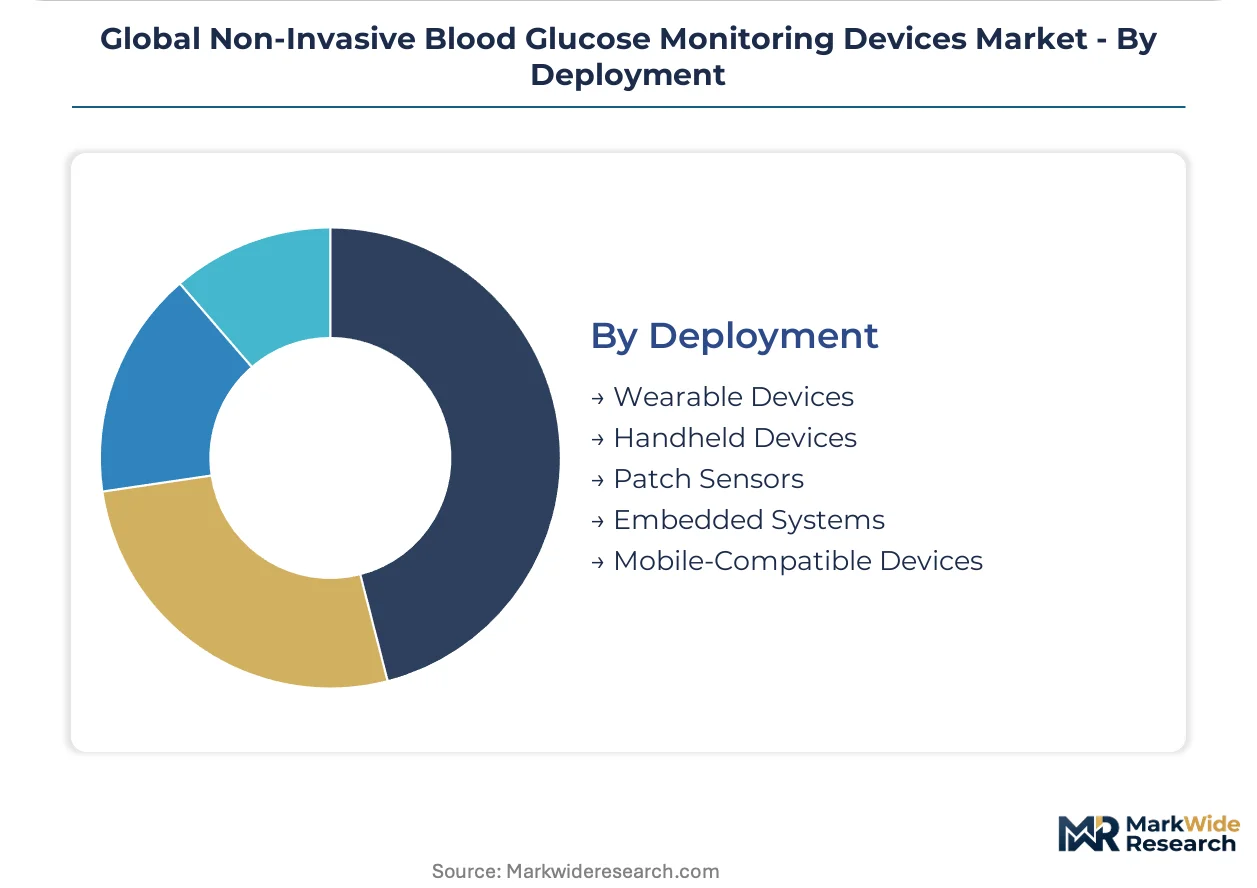
Deployment:
Supply concentration in consumable manufacturing favors vertically integrated production models for patch sensor platforms facing EU MDR Class IIa reclassification.
- Patch Sensors:Disposable microneedle arrays with recurring consumable revenue align with CVS Health and Walgreens pharmacy distribution networks. EU Medical Device Regulation post-market surveillance obligations favor established quality management systems.
- Wearable Devices:Continuous streaming form factors integrate with Apple Watch and Fitbit ecosystems. Japan's PMDA has introduced streamlined approval tracks specifically for wearable glucose analytics.
- Handheld Devices:Periodic measurement units compete with legacy fingerstick meters on price.
- Mobile-Compatible Devices:Smartphone-connected sensors leverage consumer electronics supply chains.
- Embedded Systems:Integration into insulin delivery pumps requires closed-loop validation.
Patch sensors dominate recurring revenue capture; wearable devices are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of optical sensor components from East Asian foundries dominate supply-side trade balances, while import demand concentrates in markets with evolving reimbursement frameworks for continuous glucose monitoring systems.
United States
Hospital readmission penalty structures and CMS reimbursement evolution are accelerating procurement of wearable patch sensors by post-acute care networks. FDA breakthrough device designation pathways compress premarket review timelines for novel optical and bioimpedance platforms. The Greater Boston corridor hosts concentrated algorithm development activity for spectroscopy-based glucose analytics.
Germany
Ambulatory care networks and home care providers are expanding transdermal sensor procurement to reduce hospital readmission penalties under Federal Joint Committee frameworks. EU Medical Device Regulation Class IIa reclassification tightens post-market surveillance obligations for continuous monitoring accessories. The Baden-Württemberg industrial cluster concentrates photonics component manufacturing for near-infrared laser diode supply chains.
Japan
Endocrinology practices and specialized diabetes clinics are integrating non-invasive devices into patient education programs under evolving PMDA software-as-medical-device pathways. METI streamlines approval tracks specifically for wearable glucose analytics with cloud-connected processing architectures. The Kanto region around Tokyo anchors domestic demand for spectroscopy platforms targeting nocturnal hypoglycemia detection.
China
Domestic manufacturing of electromagnetic and bioimpedance sensors is scaling to serve fitness tracker integration demand without full medical device regulatory burden. NMPA oversight of software-as-medical-device glucose analytics creates parallel approval tracks for algorithm-based platforms. The Yangtze River Delta concentrates optical sensor assembly capacity serving both domestic consumption and re-export markets.
India
Diagnostic laboratories and wellness centers are piloting handheld non-invasive devices for prediabetes population screening amid uncertain reimbursement classification. CDSCO regulatory frameworks for point-of-care glucose monitoring are evolving to accommodate optical sensor platforms. The Maharashtra-Gujarat pharmaceutical corridor is emerging as a distribution hub for patch sensor consumables targeting pharmacy channel integration.
Global Non-Invasive Blood Glucose Monitoring Devices Market Competitive Landscape
Concentration sits with diversified diagnostic conglomerates that leverage decades of electrochemical expertise to sustain regulatory credibility across multiple jurisdictions. Market structure exhibits tiered competition between established medical device manufacturers with integrated quality management systems and emerging sensor specialists pursuing focused platform strategies. Three archetypes dominate: legacy CGM incumbents extending into non-invasive adjacencies, transdermal patch specialists capturing recurring consumable revenue, and spectroscopy newcomers navigating wellness-clinical boundary positioning. Competitive moves center on regulatory pathway acceleration through breakthrough designations and backward integration into photonics component supply.
Within the diversified diagnostic tier, Abbott Laboratories and Medtronic occupy positions anchored by established electrochemical portfolios and multi-jurisdictional regulatory infrastructure. DexCom exemplifies the invasive-to-non-invasive extension archetype through continuous glucose monitoring platforms that set accuracy benchmarks non-invasive alternatives must match. Nemaura Medical and Know Labs represent specialized entrants: the former occupies transdermal patch positioning with pharmacy channel alignment, while the latter sits within spectroscopy-based approaches targeting algorithm-driven glucose estimation. Senseonics anchors implantable sensor positioning with long-duration monitoring capabilities. These five entities collectively illustrate competitive fragmentation between scale-driven regulatory navigation and focused technology platform bets.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| DexCom |
| Nemaura Medical |
| Senseonics |
| Afon Technology |
| Cnoga Digital Care |
| DiaMon Tech |
| Know Labs |
| Others |
Supply & Pricing Matrix
East Asian photonics foundry capacity utilization above 85 percent concentrates near-infrared laser diode supply among three dominant suppliers, creating asymmetric pricing power that elevates input cost floors for spectroscopy-based glucose monitors while squeezing margin recovery for downstream device assemblers lacking captive wafer supply.
Pricing Analysis
Home care providers and hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers, with FDA breakthrough designation and ISO 15197 certification grade serving as the primary price differentiation drivers. Cost compression in the standard tier is intensifying because transdermal patch manufacturers compete for pharmacy channel placement against established fingerstick meter bundles. Specialized clinics demonstrate the least price sensitivity due to reimbursement pass-through mechanisms, while wellness-oriented fitness tracker integrations face the greatest buyer resistance at premium price points.
Supply Chain Analysis
Strait of Malacca transit routes underpin photonics component flows from Taiwan, South Korea, and Japan to device assembly facilities in Germany and the United States. Near-infrared laser diodes, MEMS microneedle arrays, and bioimpedance electrode substrates constitute critical input dependencies. Single-source vulnerability concentrates in East Asian foundry capacity for custom wavelength emitters. Distribution runs through pharmacy benefit manager formularies and hospital GPO contracts for clinical-grade devices, with consumer electronics retail channels serving wellness-tier products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-invasive glucose monitoring sits in early-cycle expansion as home care reimbursement frameworks in the United States and Germany mature to cover wearable patch platforms beyond traditional fingerstick alternatives.
For Market Incumbents: Shield electrochemical portfolio margins by accelerating FDA breakthrough pathway submissions for spectroscopy adjacencies before transdermal specialists achieve parity accuracy benchmarks. Secure backward integration into photonics wafer supply through foundry partnerships or captive capacity in Taiwan. Channel control through pharmacy benefit manager exclusivity agreements represents the critical defensive lever against patch sensor entrants. For New Entrants and Emerging Players: Differentiate on algorithm training data diversity across skin tone and tissue composition variations, where incumbent spectroscopy platforms exhibit validation gaps. Target employer-sponsored wellness program subsidies in the United States as the most penetrable revenue pool, bypassing clinical reimbursement complexity. Direct-to-consumer positioning through fitness tracker ecosystem partnerships offers the clearest go-to-market angle for bioimpedance and electromagnetic sensor architectures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among transdermal patch platforms with disposable microneedle consumables and pharmacy channel integration. Five-to-ten year viability favors manufacturers with vertically integrated production models capable of absorbing EU MDR Class IIa compliance cost escalation. Watch FDA breakthrough designation awards to spectroscopy newcomers as the signal indicating inflection toward clinical-grade accuracy validation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Expedited premarket review compresses commercialization timelines for novel optical platforms against invasive CGM benchmarks. |
| Pharmacy Channel Integration | CVS Health and Walgreens distribution alignment enables recurring consumable revenue capture through prescription fulfillment workflows. |
| Photonics Foundry Partnership | Captive wafer supply from Taiwan and South Korea mitigates single-source vulnerability for near-infrared laser diode inputs. |
| Software-as-Medical-Device Pathway | Japan PMDA streamlined approval creates first-mover positioning for cloud-connected algorithm analytics architectures. |
| EU MDR Quality System Investment | Class IIa post-market surveillance compliance favors established manufacturers over early-stage sensor startups. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, biomedical engineers at diabetes device manufacturers, regulatory affairs leads specializing in FDA breakthrough pathways, and pharmacy benefit manager formulary directors, then refined through secondary validation against FDA 510(k) filings, EU MDR notified body documentation, CMS reimbursement decision records, and hospital GPO contract databases. Bottom-up patient population modeling and top-down healthcare expenditure triangulation anchored volume and value estimates.
Variance decomposition across technology modality, deployment form factor, and application tier shaped the analytical framework over the projection horizon. Modeled segmentation encompassed sensing approach, device wearability class, end-user procurement authority, and regional regulatory cluster. CAGRs derived from fitted adoption curves incorporating reimbursement policy evolution and accuracy benchmark convergence against invasive alternatives. Algorithm training data requirements and photonics component supply constraints served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement expansion for non-invasive alternatives would require recalibration. Forecasts reflect documented assumptions regarding FDA breakthrough pathway throughput, EU MDR notified body capacity, and East Asian foundry utilization stability. Practitioners should keep alternative scenarios live as Federal Joint Committee reimbursement evaluations and PMDA software-as-medical-device precedent evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
United States Self-Monitoring Blood Glucose Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
North America Continuous Glucose Monitoring Market