
 Indonesia Diabetes Care Devices Market | 2026-2036
Indonesia Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Diabetes Care Devices Market Foresight
ISO 13485 certification is reorganizing competitive access for foreign manufacturers seeking entry into Indonesia's diabetes device sector. Abbott leverages its vertically integrated sensor manufacturing to sustain cost advantages across continuous glucose monitor shipments. PT Kalbe Farma anchors its position through domestic distribution networks that reach provincial hospitals outside Java. Roche competes on diagnostic accuracy standards that align with Ministry of Health laboratory requirements.
Diabetes care devices encompass instruments for glucose measurement, insulin administration, and metabolic monitoring, typically operating through electrochemical sensor reactions or precision piston-driven fluid delivery with calibration tolerances within fifteen percent variance. These tools serve to prevent hyperglycemic crises, optimize therapeutic dosing, and reduce long-term complication burdens in diabetic populations. Blood glucose meters and test strips still occupy the largest revenue pool due to universal screening protocols, though continuous glucose monitors and smart wireless devices are capturing the fastest expansion as endocrinology practices in Jakarta and Surabaya adopt real-time data protocols. Insulin delivery devices concentrate margin in premium pump systems while patch-based alternatives penetrate price-sensitive home care segments.
Indonesia's Ministry of Health regulates device registration under the ASEAN Medical Device Directive framework, with BPOM conducting pre-market assessments that delay entry for uncertified applicants. BIS-equivalent national standards and forthcoming local content requirements are forcing manufacturers to establish domestic assembly or partner with licensed Indonesian distributors. Stakeholders must monitor BPOM's evolving risk classification rules and the Ministry of Health's hospital procurement centralization to anticipate which device categories will face accelerated approval or exclusion.
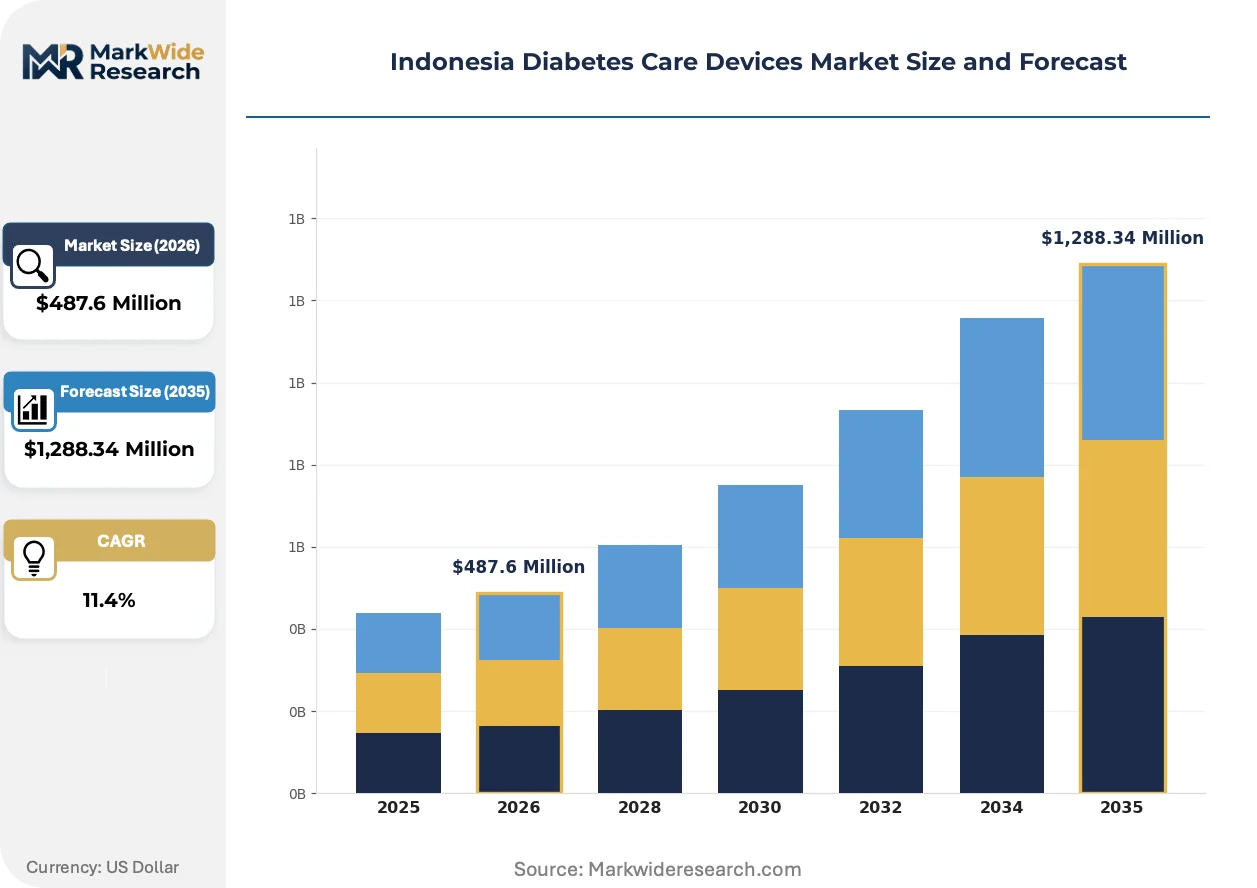
Market Dynamics
BPOM's enforcement of ASEAN Medical Device Directive risk classifications is compressing approval timelines for glucose monitoring systems while elevating compliance costs for unregistered manufacturers. This regulatory tightening concentrates procurement authority within Jakarta's centralized hospital purchasing pools.
Growth Catalysts
- ASEAN Medical Device Directive harmonization:BPOM's alignment with regional standards accelerates cross-border device recognition for insulin delivery systems. Foreign manufacturers gain pathway equivalence across Southeast Asian markets.
- Endocrinology practice consolidation:Jakarta and Surabaya specialty clinics are standardizing continuous glucose monitor protocols. Real-time data integration drives replacement cycles for legacy blood glucose meters.
- Provincial hospital network expansion:Ministry of Health infrastructure programs extend diabetes screening to Eastern Indonesia. Test strip volumes rise with universal screening mandates outside Java.
Market Restraints
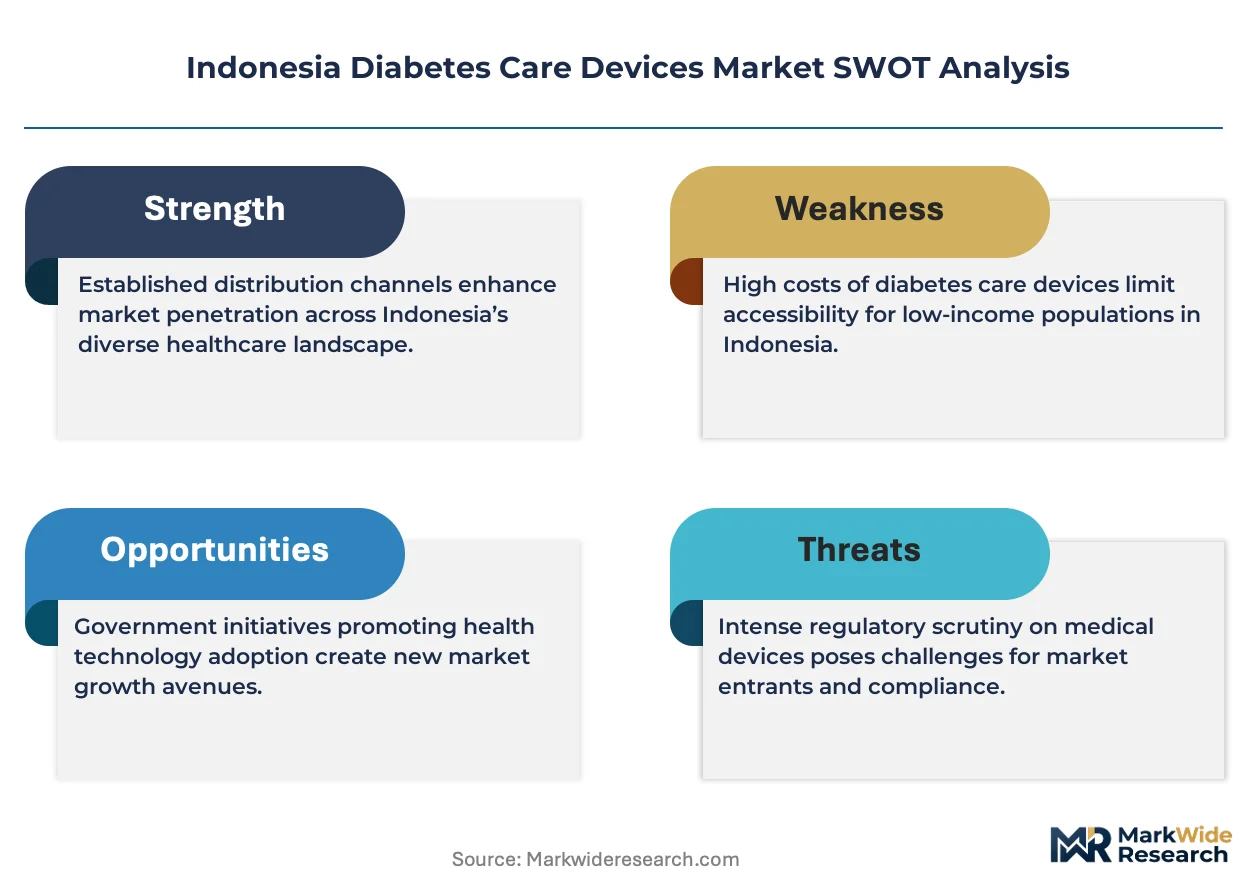
- Sensor substrate cost volatility:Electrochemical sensor membranes depend on palladium and silver paste imports. Currency fluctuation against the rupiah compresses margins for domestic distributors.
- Single-source pump motor supply:Precision insulin pump actuators concentrate with Swiss and German component suppliers. Geopolitical friction risks intermittent delivery delays.
- BPOM risk-classification elevation:Reclassification of continuous glucose monitors to higher-risk tiers extends pre-market assessment timelines. Uncertified applicants face 18-24 month entry delays.
Strategic Opportunities
- Eastern Indonesia underpenetration:Papua and Maluku provinces operate below 15% diabetes diagnostic coverage. Mobile screening units paired with telemedicine infrastructure create first-mover positioning.
- Local content requirement preparation:Ministry of Health draft rules mandate domestic assembly thresholds for hospital procurement eligibility. Early manufacturing joint ventures secure preferential tender access.
- Patch pump-home care convergence:Disposable insulin patch devices align with JKN reimbursement expansion for home-based chronic disease management. Price-sensitive segments shift from syringe-based delivery.
Industry Challenges
- ISO 13485 auditor scarcity:BPOM-recognized certification bodies operate limited Indonesian assessment capacity. Manufacturer queue times extend six to nine months.
- Legacy hospital information system integration:Provincial facilities run incompatible data protocols for continuous glucose monitor feeds. Middleware development consumes implementation budgets.
- Biocompatibility testing infrastructure gaps:Domestic ISO 10993 evaluation capacity concentrates in Jakarta. Peripheral manufacturers face sample transport costs and timeline extension.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Diabetes Care Devices Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Continuous Glucose Monitors, Insulin Delivery Devices, Test Strips End User: Home Care, Hospitals, Clinics, Laboratories Delivery Mode: Injectable, Patch, Sensor, Oral Technology: Smart Devices, Traditional Devices, Wireless Devices, Non-Invasive Devices |
| Companies Covered | Abbott, Sanofi, Medtronic, Ypsomed, PT Kalbe Farma, Roche, Dexcom, PT PHC Indonesia, Novo Nordisk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Diabetes Care Devices Market Shifts & Advancements
Wireless connectivity protocols and disposable form factors are compressing device replacement cycles while shifting value capture toward sensor consumables. Regulatory data requirements and procurement centralization simultaneously reshape competitive entry pathways.
Continuous glucose monitor sensor architecture is miniaturizing through MEMS fabrication advances that reduce filament diameter below 0.4 millimeters. Endocrinology practices in Jakarta's tertiary hospitals are adopting these systems at replacement rates exceeding 35% annually for legacy fingerstick protocols. The technology is miniaturizing patient burden sufficiently to expand addressable populations into pediatric and geriatric segments previously excluded by insertion trauma concerns.
Indonesia's Ministry of Health is tightening local content thresholds for medical device procurement under forthcoming domestic assembly mandates. Industrial consequence falls heaviest on foreign manufacturers lacking licensed Indonesian distribution partners or captive manufacturing facilities. Continuous glucose monitor and insulin pump categories face accelerated compliance timelines as hospital purchasing centralization prioritizes vendors with established in-country presence.
Hospital procurement committees are consolidating supplier rosters through framework agreements that bundle device supply with maintenance and calibration services. Provincial referral hospitals outside Java increasingly select single-source vendors for glucose monitoring infrastructure rather than maintaining multi-brand device pools. Eastern Indonesia's expanding hospital networks exhibit this concentration most visibly as purchasing authority shifts from individual departments to centralized ministry-aligned procurement units.
Indonesia Diabetes Care Devices Market Segmentation
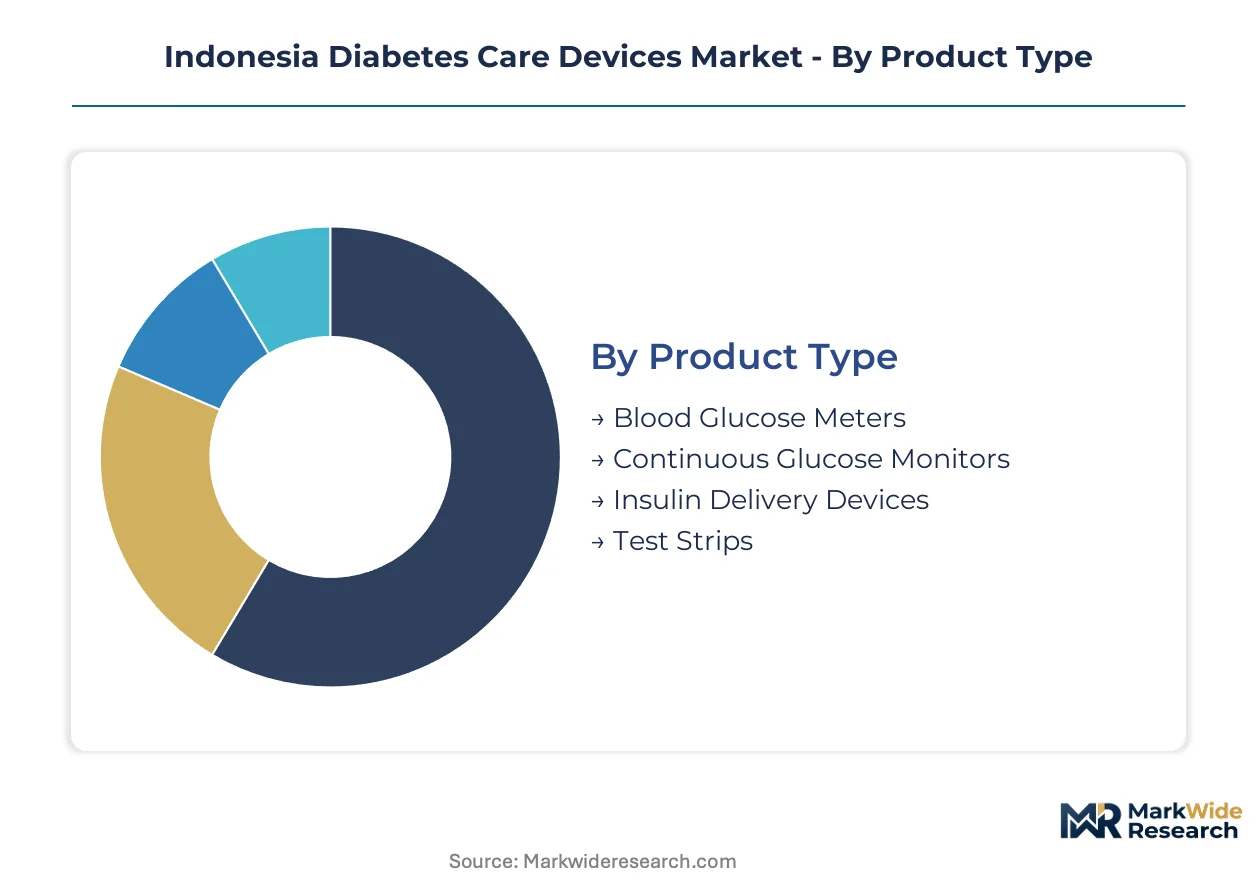
Segmentation reveals how procurement centralization and reimbursement tiers fragment Indonesia's diabetes device landscape. Jakarta's hospital purchasing pools concentrate volume in specific product categories while provincial networks drive demand in others.
Product Type:
Margin pools concentrate in consumable sensor platforms and premium pump systems that lock in recurring revenue through proprietary cartridge formats.
- Blood Glucose Meters:Electrochemical strip readers with 5-second measurement cycles dominate universal screening protocols. Provincial hospitals outside Java absorb bulk procurement volumes as Ministry of Health infrastructure programs extend diagnostic coverage.
- Continuous Glucose Monitors:MEMS-fabricated filament sensors below 0.4 millimeter diameter enable real-time glucose tracking with 14-day wear cycles. Jakarta's tertiary endocrinology practices are rotating out legacy fingerstick protocols at replacement rates exceeding one-third annually.
- Insulin Delivery Devices:Precision piston-driven pumps and disposable patch systems serve divergent patient segments. JKN reimbursement expansion favors home-care pump adoption among managed chronic populations.
- Test Strips:Single-use electrochemical substrates with enzymatic glucose oxidase coatings generate volume through screening mandates. Eastern Indonesia's diagnostic coverage gaps below 15 percent create latent demand pools.
Test strips hold installed capacity. Continuous glucose monitors are rotating up the share rankings.
End User:
Revenue concentration tracks reimbursement authorization tiers, with hospital procurement pools commanding price premiums over retail channels.
- Home Care:Patient-managed glucose monitoring and insulin administration devices. JKN chronic disease management benefits are expanding patch pump eligibility for price-sensitive households.
- Hospitals:Centralized purchasing committees in Jakarta's tertiary facilities bundle device supply with calibration services. Framework agreements are consolidating supplier rosters into single-source vendor relationships.
- Clinics:Specialty endocrinology practices in Surabaya standardize continuous glucose monitor protocols. Real-time data integration drives device replacement cycles.
- Laboratories:Diagnostic accuracy standards align with Ministry of Health reference methods. Centralized lab networks concentrate high-volume test strip consumption.
Hospitals anchor procurement volume. Home care is climbing the fastest as reimbursement shifts toward chronic disease management.
Delivery Mode:
Technology substitution patterns favor less invasive formats where patient compliance and reimbursement coverage converge.
- Injectable:Syringe and pen-based insulin delivery retains volume in price-sensitive segments. Traditional delivery dominates where patch pump reimbursement remains limited.
- Patch:Disposable adhesive pump systems with pre-filled insulin reservoirs align with home-care chronic disease protocols. JKN expansion is accelerating format substitution among managed populations.
- Sensor:Subcutaneous glucose detection platforms generate recurring revenue through proprietary transmitter-sensor pairings. BPOM risk-classification elevation to higher tiers extends pre-market timelines for new entrants.
- Oral:Non-invasive glucose monitoring through tear fluid or saliva analysis remains developmental. Clinical validation gaps limit current commercial penetration.
Injectable formats retain installed base. Patch delivery is gaining share fastest on reimbursement tailwinds.
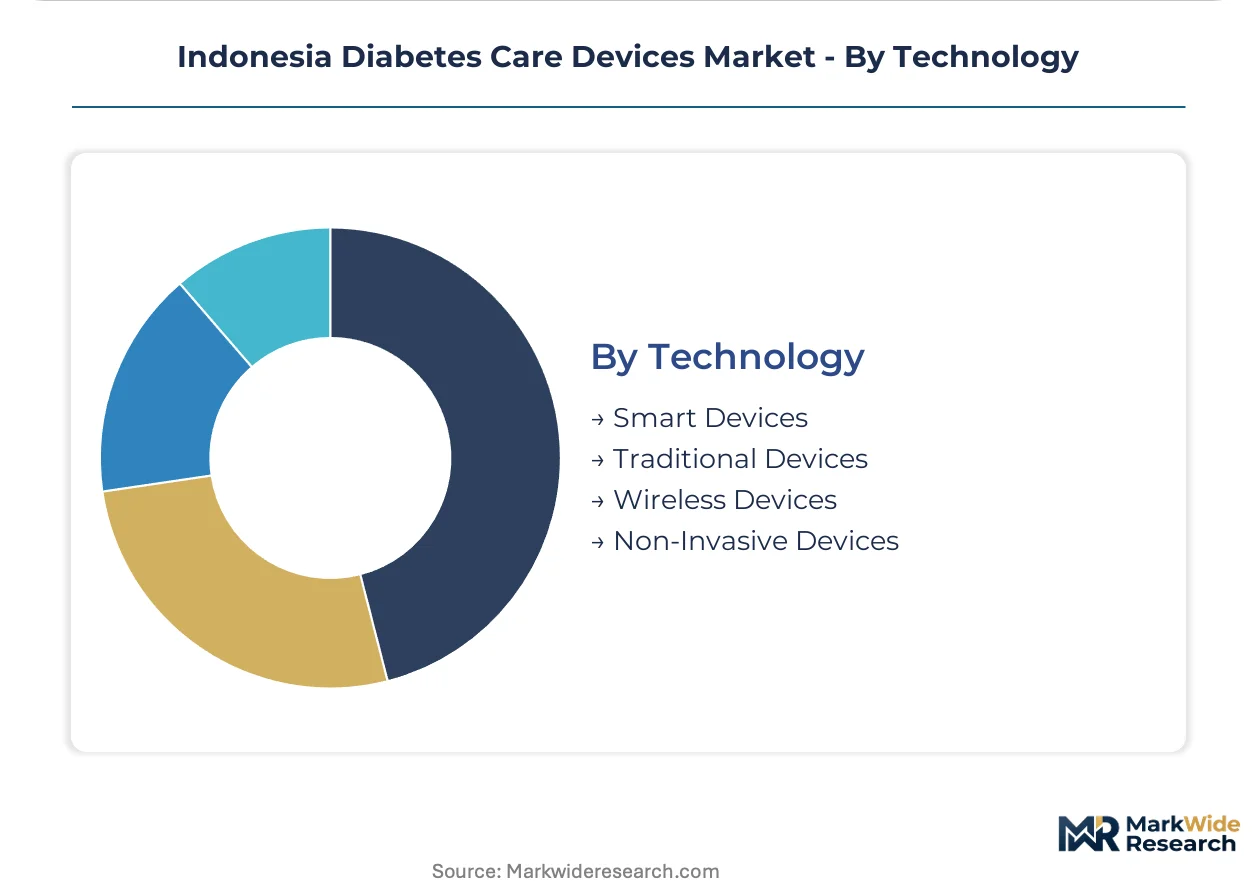
Technology:
Value capture shifts toward data-integrated platforms as Jakarta's hospital networks consolidate around interoperable health information systems.
- Smart Devices:Algorithm-enabled glucose prediction and automated insulin dosing adjustment. Integration with hospital information systems drives procurement preference in centralized purchasing pools.
- Traditional Devices:Non-connected blood glucose meters and manual insulin syringes. Provincial facilities with incompatible data protocols maintain legacy device pools.
- Wireless Devices:Bluetooth-enabled continuous glucose monitors transmitting to smartphone applications. Real-time data sharing with clinicians supports remote patient management.
- Non-Invasive Devices:Optical and thermal glucose sensing technologies eliminate fingerstick requirements. Regulatory validation requirements under BPOM's ASEAN Medical Device Directive framework delay market entry.
Traditional devices hold installed capacity. Smart devices are rotating up the share rankings on integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Ministry of Health procurement centralization under Jaminan Kesehatan Nasional expansion is redistributing diabetes device demand across the archipelago's uneven hospital infrastructure. Provincial equity mandates now channel continuous glucose monitors and insulin delivery systems toward Eastern Indonesia's diagnostic coverage gaps.
Java
Jakarta's tertiary hospital purchasing pools absorb the majority of premium continuous glucose monitor deployments as endocrinology practices consolidate. BPOM's centralized device registration processing concentrates manufacturer compliance activity in the capital region. Surabaya's specialty clinics in East Java drive replacement cycles for legacy blood glucose meters through real-time data protocol adoption.
Sumatra
Medan's hospital procurement committees leverage framework agreements to bundle diabetes device supply with calibration services across North Sumatra's referral network. Ministry of Health infrastructure programs extend test strip volumes through universal screening mandates in previously underserved districts. Palembang's centralized purchasing units in South Sumatra increasingly select single-source vendors for glucose monitoring infrastructure.
Sulawesi
Makassar's provincial hospital networks exhibit rapid supplier roster consolidation as purchasing authority shifts from individual departments to ministry-aligned procurement units. Eastern Indonesia's expanding diagnostic infrastructure creates latent demand pools for electrochemical strip readers. BPOM's risk-classification enforcement delays entry for uncertified continuous glucose monitor applicants seeking access to Sulawesi's growing hospital market.
Kalimantan
Balikpapan's oil and gas industry concentration generates employer-sponsored diabetes screening programs that sustain blood glucose meter procurement outside Java. Provincial hospitals in East Kalimantan run incompatible data protocols for continuous glucose monitor feeds, consuming middleware implementation budgets. Ministry of Health draft local content rules mandate domestic assembly thresholds that foreign manufacturers must satisfy for hospital procurement eligibility.
Papua and Maluku
Mobile screening units paired with telemedicine infrastructure create first-mover positioning opportunities in provinces operating below fifteen percent diabetes diagnostic coverage. Jayapura's referral hospitals face biocompatibility testing infrastructure gaps that concentrate ISO 10993 evaluation sample transport costs to Jakarta. JKN reimbursement expansion for home-based chronic disease management accelerates patch pump eligibility among managed populations in remote island communities.
Indonesia Diabetes Care Devices Market Competitive Landscape
Player mix skews toward multinational medical technology conglomerates with vertically integrated sensor manufacturing and domestic pharmaceutical distributors with established provincial hospital networks. Market structure concentrates procurement influence within Jakarta's centralized purchasing pools, creating tiered access between ISO 13485-certified applicants and uncertified entrants facing extended BPOM assessment timelines. Strategic archetypes include sensor-integrated platform specialists, disposable delivery device manufacturers, and licensed Indonesian distribution partners. Dominant competitive moves encompass manufacturing joint ventures to satisfy forthcoming local content requirements and framework agreements bundling device supply with maintenance services.
Among multinational technology conglomerates, Abbott and Roche exemplify archetypes competing on diagnostic accuracy standards and vertically integrated production control. PT Kalbe Farma anchors the domestic distributor tier through licensed distribution networks reaching provincial hospitals outside Java. Medtronic occupies a position representing precision insulin pump system concentration dependent on Swiss and German component suppliers for actuator sourcing.
| Leading Market Players |
|---|
| Abbott |
| Sanofi |
| Medtronic |
| Ypsomed |
| PT Kalbe Farma |
| Roche |
| Dexcom |
| PT PHC Indonesia |
| Novo Nordisk |
| Others |
Supply & Pricing Matrix
MEMS-fabricated sensor substrates replacing legacy electrochemical membranes are redrawing procurement geography toward Swiss and German precision component suppliers while compressing margin structures for Jakarta-based distributors absorbing rupiah volatility against palladium and silver paste import costs.
Pricing Analysis
Certification level (ISO 13485/BPOM-registered versus uncertified) creates the primary spread between premium continuous glucose monitors and economy blood glucose meters. Three-tier pricing structure across premium, standard, and economy levels bundles device supply with calibration services in Jakarta's centralized hospital purchasing pools. Price erosion runs through test strip categories as provincial screening mandates expand volume without proportional reimbursement expansion. Home care segments exhibit highest price sensitivity, while tertiary hospital procurement committees prioritize diagnostic accuracy standards over unit cost.
Supply Chain Analysis
Tanjung Priok port congestion on the Singapore-Jakarta trade lane elevates inbound logistics costs for electrochemical sensor substrates and precision insulin pump actuators. Component manufacturing concentrates in Switzerland, Germany, and Japan for MEMS fabrication and precision motor assemblies. Domestic distributors draw from single-source pump motor suppliers, creating vulnerability to geopolitical friction. Distribution runs through PT Kalbe Farma's licensed provincial networks reaching hospitals outside Java.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patch-based insulin delivery systems represent a credible substitution threat to legacy pump architectures, requiring incumbents to defend installed base through reimbursement-aligned format innovation.
For Market Incumbents: Shield market position by deepening backward integration into MEMS sensor manufacturing to offset palladium cost volatility, while accelerating ISO 13485 certification for BPOM risk-classification elevation. Secure framework agreements with Jakarta's centralized purchasing committees before local content mandates crystallize. Priority lever rests on manufacturing joint ventures satisfying forthcoming domestic assembly thresholds. For New Entrants and Emerging Players: Anchor in Papua and Maluku provinces where diagnostic coverage sits below fifteen percent, deploying mobile screening units paired with telemedicine infrastructure. Target price-sensitive home care segments through JKN-reimbursable patch pump formats. Go-to-market angle emphasizes disposable form factors bypassing legacy hospital information system integration barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision component manufacturers holding captive supply relationships with Swiss and German actuator producers. Long-term viability hinges on local content compliance capability across the analysis window. Acquisition target archetype: licensed Indonesian distributors with established provincial hospital networks. Signal to watch: BPOM's final local content rule publication triggering consolidation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | BPOM registration acceleration compresses 18-24 month entry delays for glucose monitoring systems. |
| Manufacturing Joint Venture | Domestic assembly thresholds secure preferential access to Ministry of Health hospital procurement tenders. |
| Hospital System Partnership | Framework agreements bundling device supply with calibration services consolidate supplier rosters in Jakarta. |
| Software Companion Development | Real-time data integration with hospital information systems drives procurement preference in centralized purchasing pools. |
| Reimbursement Strategy | JKN expansion for home-based chronic disease management accelerates patch pump eligibility among managed populations. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineers at tertiary facilities, BPOM regulatory affairs specialists, and provincial distribution network managers, then refined against secondary sources including BPOM device registration databases, Ministry of Health procurement records, ASEAN Medical Device Directive harmonization documents, and GPO contract filings. Bottom-up test strip volume estimates triangulated with top-down market sizing across product categories.
Variance decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end user tier, delivery mode, and technology integration level. CAGRs derived from installed base rotation rates for legacy fingerstick protocols and replacement cycle acceleration for continuous glucose monitors. Industry-specific inputs incorporated JKN reimbursement expansion trajectories and BPOM risk-classification timeline assumptions.
Underlying assumptions cover JKN chronic disease management benefit continuity and palladium price band stability, with deviation risk concentrated in BPOM local content rule finalization and rupiah volatility against component import currencies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Insulin Patch Pumps Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Global Continuous Glucose Monitoring Systems Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
Latin America Insulin Infusion Pump Market