
 Asia-Pacific Oral Anti-Diabetic Drug Market | 2026-2036
Asia-Pacific Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oral Anti-Diabetic Drug Market Analysis
India's PLI scheme for active pharmaceutical ingredients is broadening the regional manufacturing base for oral anti-diabetic drugs. Sanofi leverages its established insulin portfolio to extend into complementary oral therapies across Southeast Asian markets. Takeda Pharmaceutical Company Limited anchors its position through deep specialization in DPP-4 inhibitor chemistry and Japanese regulatory expertise.
Oral anti-diabetic drugs comprise small-molecule pharmaceuticals administered perorally to lower blood glucose through mechanisms including hepatic glucose suppression, insulin sensitization, and renal glucose excretion, with formulations typically containing 500-1000 mg of active compound in immediate-release or extended-release matrices. These agents serve as first-line pharmacotherapy for type 2 diabetes management in outpatient and homecare settings where patient self-administration is required. SGLT2 inhibitors represent the fastest-expanding product category as cardiorenal outcome data drives prescribing shifts beyond glycemic control alone. Tablet delivery mode dominates volume due to manufacturing economies and patient familiarity, though liquid formulations occupy a meaningful niche in geriatric and pediatric populations.
India's CDSCO, China's NMPA, and Japan's PMDA collectively govern market access through bioequivalence requirements, GMP inspections, and post-market surveillance protocols that elevate barriers for non-compliant manufacturers. Australia's TGA and South Korea's MFDS further shape standards through mutual recognition agreements and regional harmonization initiatives. Stakeholders must monitor evolving pharmacovigilance mandates and local clinical trial requirements as each regulator tightens evidence standards for new molecular entities.
Market Dynamics
SGLT2 inhibitors are capturing prescribing share from older drug classes as cardiorenal outcome data reshapes treatment algorithms across Asia-Pacific outpatient clinics. This molecular transition concentrates investment in specialized manufacturing capacity while compressing margins for commoditized sulfonylurea production.
Growth Catalysts
- China's NMPA accelerated review pathways:Priority review designations for innovative diabetes therapies compress regulatory timelines from 200 days to 130 days, enabling faster patient access to novel DPP-4 and SGLT2 molecules.
- Hospital-based diabetes management programs:Southeast Asian health systems in Thailand, Vietnam, and Indonesia are embedding pharmacists into multidisciplinary diabetes teams, institutionalizing oral therapy protocols and driving formulary standardization.
- Renal glucose excretion mechanisms:SGLT2 inhibitor chemistry platforms now command dedicated manufacturing investment as prescribers prioritize glucose-independent cardiovascular protection in type 2 diabetes patients with comorbid heart failure.
Market Restraints
- API import dependence:Indian formulation manufacturers rely on Chinese suppliers for 65-70% of key oral anti-diabetic active pharmaceutical ingredients, exposing production schedules to geopolitical friction and customs delays.
- Bioequivalence study costs:CDSCO mandates for local clinical trial data in India add 18-24 months to generic market entry timelines, elevating capital requirements for mid-tier manufacturers without established trial infrastructure.
- Fixed-dose combination complexity:Multi-mechanism tablets combining metformin with DPP-4 inhibitors require specialized dissolution profiles that strain conventional immediate-release manufacturing lines, limiting supplier flexibility.
Strategic Opportunities
- India's PLI scheme for APIs:Production-linked incentives covering 41 fermentation-based and chemical synthesis products enable domestic backward integration, reducing import exposure for metformin and glimepiride precursors.
- Extended-release formulation platforms:Matrix-controlled release technologies for once-daily dosing align with geriatric adherence patterns in Japan's aging population, creating premium positioning beyond commodity tablet supply.
- Tier-2 city outpatient clinics:China's provincial hospital expansion into secondary cities concentrates new prescription volume in markets with lower brand loyalty and higher generic substitution rates.
Industry Challenges
- Pharmacovigilance infrastructure gaps:Post-market adverse event reporting systems in Indonesia, Philippines, and Vietnam lack integration with manufacturing quality systems, complicating signal detection for rare drug reactions.
- Multinational trial coordination:Divergent PMDA, NMPA, and CDSCO requirements for ethnic bridging data force redundant patient recruitment across Japanese, Chinese, and Indian sites, inflating development costs for novel molecules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oral Anti-Diabetic Drug Market |
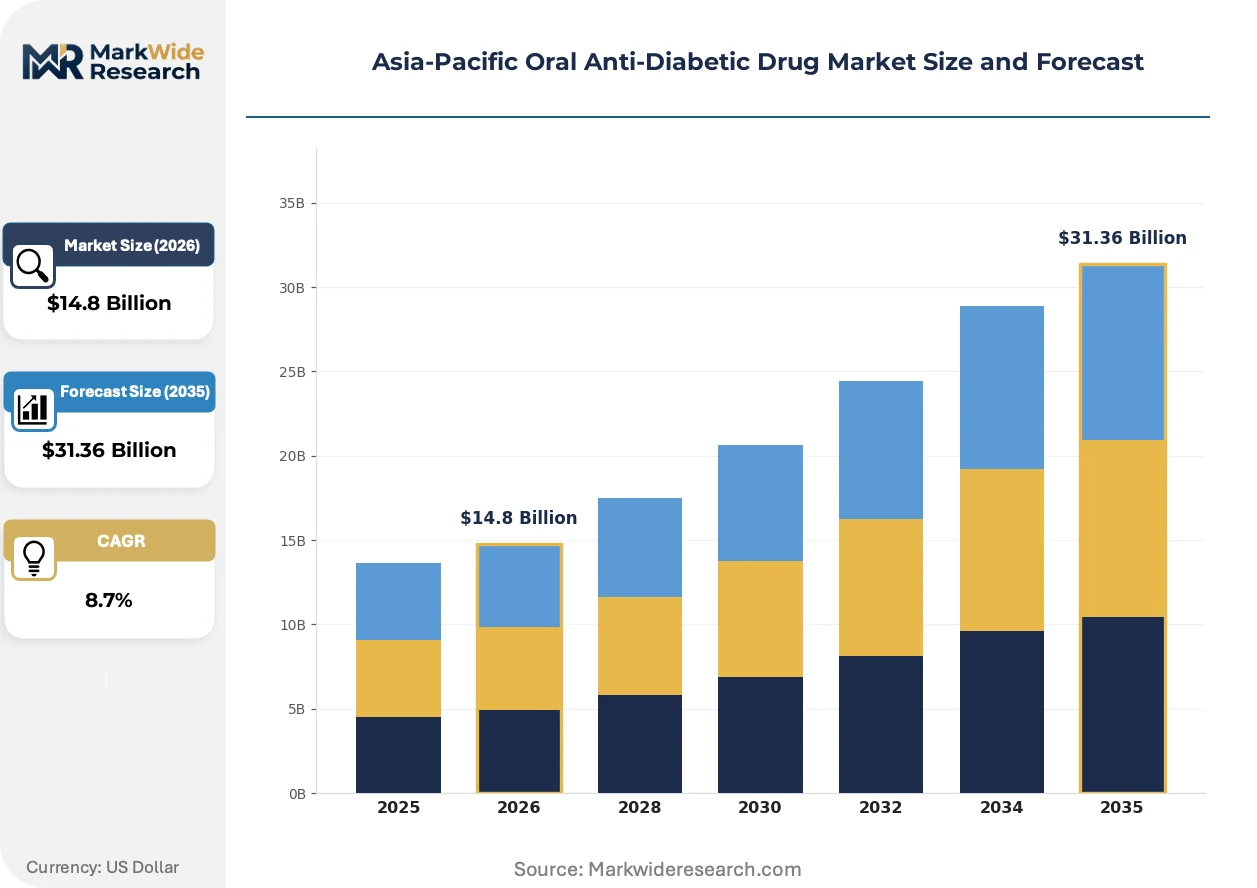
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Delivery Mode: Tablet, Capsule, Liquid, Powder End User: Hospitals, Homecare, Clinics, Pharmacies Therapy Area: Type 2 Diabetes, Pre-diabetes, Gestational Diabetes, Others |
| Companies Covered | Sanofi, Novo Nordisk A/S, Takeda Pharmaceutical Company Limited, Astellas Pharma Inc., AstraZeneca, Eli Lilly and Company, Merck & Co Inc, Boehringer Ingelheim, Janssen Pharmaceuticals, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oral Anti-Diabetic Drug Market Emerging Trajectories
Continuous glucose monitoring integration with oral therapy management is restructuring how prescribers titrate drug doses, creating data-linked prescribing ecosystems that favor manufacturers with digital health partnerships over pure pharmaceutical suppliers.
Fixed-dose combinations of SGLT2 inhibitors with metformin are absorbing manufacturing capacity from standalone sulfonylurea production across Indian and Chinese contract manufacturing organizations. Hospital formularies in South Korea and Australia are prioritizing these dual-mechanism tablets for treatment-naïve patients, compressing demand for single-agent thiazolidinediones and accelerating line conversions at formulation facilities.
Japan's PMDA has implemented conditional early approval pathways for diabetes therapies demonstrating cardiovascular outcome benefits, compressing the evidence threshold for market entry against standard glycemic endpoints alone. This regulatory architecture advantages sponsors with pre-existing cardiorenal trial infrastructure, while generic manufacturers face elevated bioequivalence study design complexity for molecules with outcome-based labeling claims.
Pharmacy benefit managers in Australia's PBS and South Korea's HIRA are tightening reimbursement controls around oral anti-diabetic switching, replacing physician discretion with protocol-driven step-therapy requirements. Community pharmacies in both markets now process prior authorization for second-line SGLT2 initiation, shifting prescribing influence from endocrinology clinics to centralized formulary committees and compressing brand loyalty windows.
Asia-Pacific Oral Anti-Diabetic Drug Market Segmentation
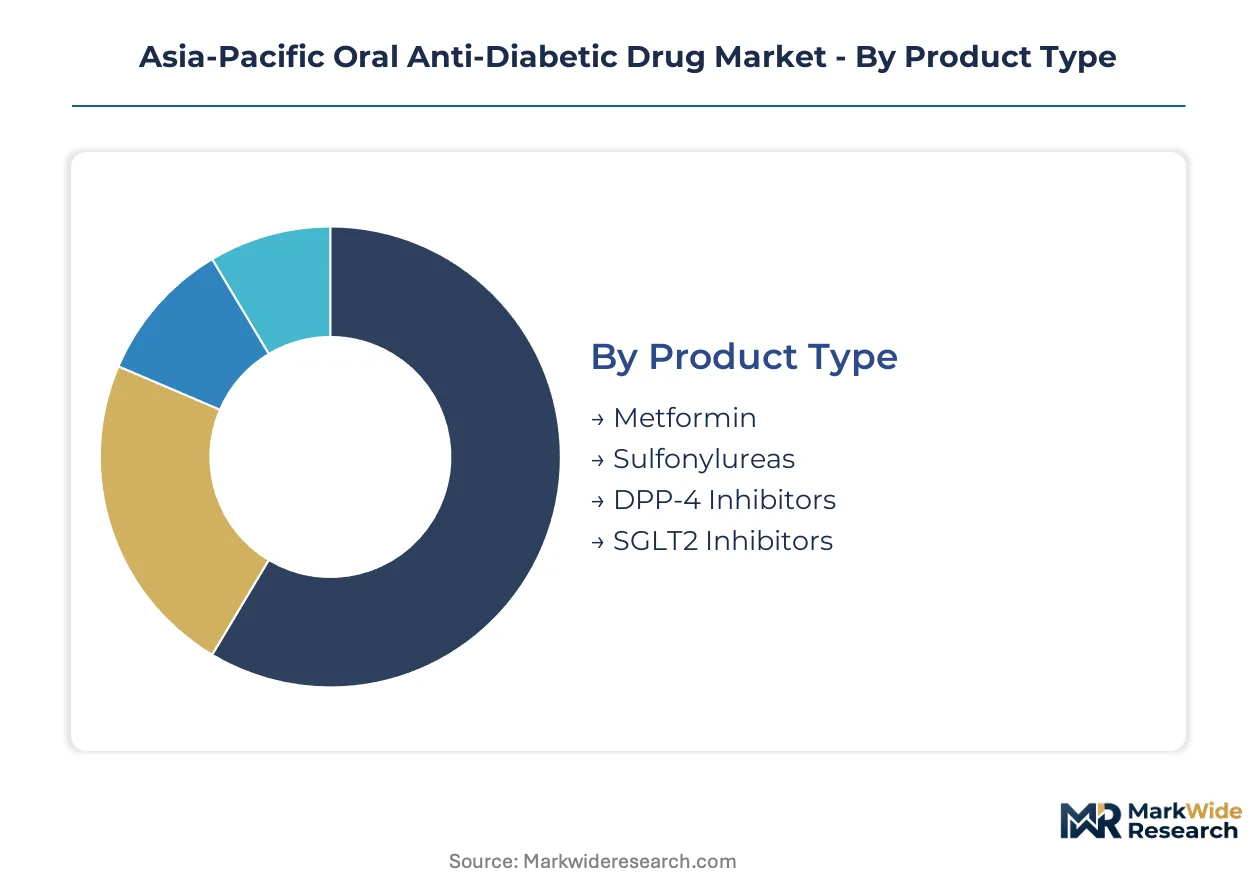
Oral anti-diabetic drug manufacturers configure production lines around molecular complexity and dosage form requirements. Segment-specific capital commitments determine which players can compete across the full product spectrum versus specializing in narrow niches.
Product Type:
Capital intensity varies sharply across molecular platforms, with fermentation-based and complex synthesis routes demanding dedicated multi-year investment cycles.
- SGLT2 Inhibitors:These molecules require sophisticated stereoselective synthesis and specialized crystallization infrastructure. China's NMPA priority review pathways and Japan's PMDA conditional approvals are concentrating demand in East Asian markets where cardiorenal outcome data drives formulary placement.
- DPP-4 Inhibitors:Peptidomimetic chemistry platforms demand cleanroom manufacturing suites and precise humidity-controlled environments. Japanese regulatory expertise and domestic clinical trial infrastructure anchor production investment decisions for sponsors targeting PMDA submissions.
- Metformin:Commodity chemical synthesis with established API supply chains across India and China.
- Sulfonylureas:Mature manufacturing processes facing margin compression from generic competition.
Metformin absorbs the bulk of installed capacity; SGLT2 inhibitors are expanding most quickly.
Delivery Mode:
Formulation technology selection shapes facility investment, with controlled-release matrices requiring distinct equipment from immediate-release lines.
- Tablet:Direct compression and wet granulation lines dominate capital deployment across Indian and Chinese contract manufacturing organizations. Australia's TGA bioequivalence requirements and South Korea's MFDS dissolution specifications are standardizing quality thresholds for regional export supply.
- Liquid:Pediatric and geriatric populations in Japan's aging demographic drive demand for oral solutions with precise dosing flexibility. Bottling lines and preservative validation protocols require specialized cleanroom configurations distinct from solid dose facilities.
- Capsule:Gelatin and HPMC shell encapsulation for combination therapies with incompatible active ingredients.
- Powder:Sachet formulations for patients with swallowing difficulties in Southeast Asian homecare settings.
Tablets command the majority of production volume; liquid formulations are climbing the fastest on geriatric demand.
End User:
Channel-specific packaging and distribution requirements segment logistics investment across institutional and retail supply chains.
- Hospitals:Bulk procurement contracts and unit-dose packaging specifications dominate volume in Thailand and Vietnam where diabetes management programs are embedding pharmacists into multidisciplinary care teams. Cold chain requirements for certain formulations concentrate distribution investment near major metropolitan hospital clusters.
- Homecare:Patient-administered therapy demand is restructuring packaging toward adherence-supporting blister configurations and multilingual labeling for Australia's PBS-subsidized supply.
- Clinics:Outpatient prescription volume in China's tier-2 cities concentrates demand for 30-day supply configurations.
- Pharmacies:Community dispensing in Indonesia and Philippines shapes over-the-counter accessibility for certain drug classes.
Hospitals absorb the bulk of procurement volume; homecare channels are gaining share fastest on self-administration trends.
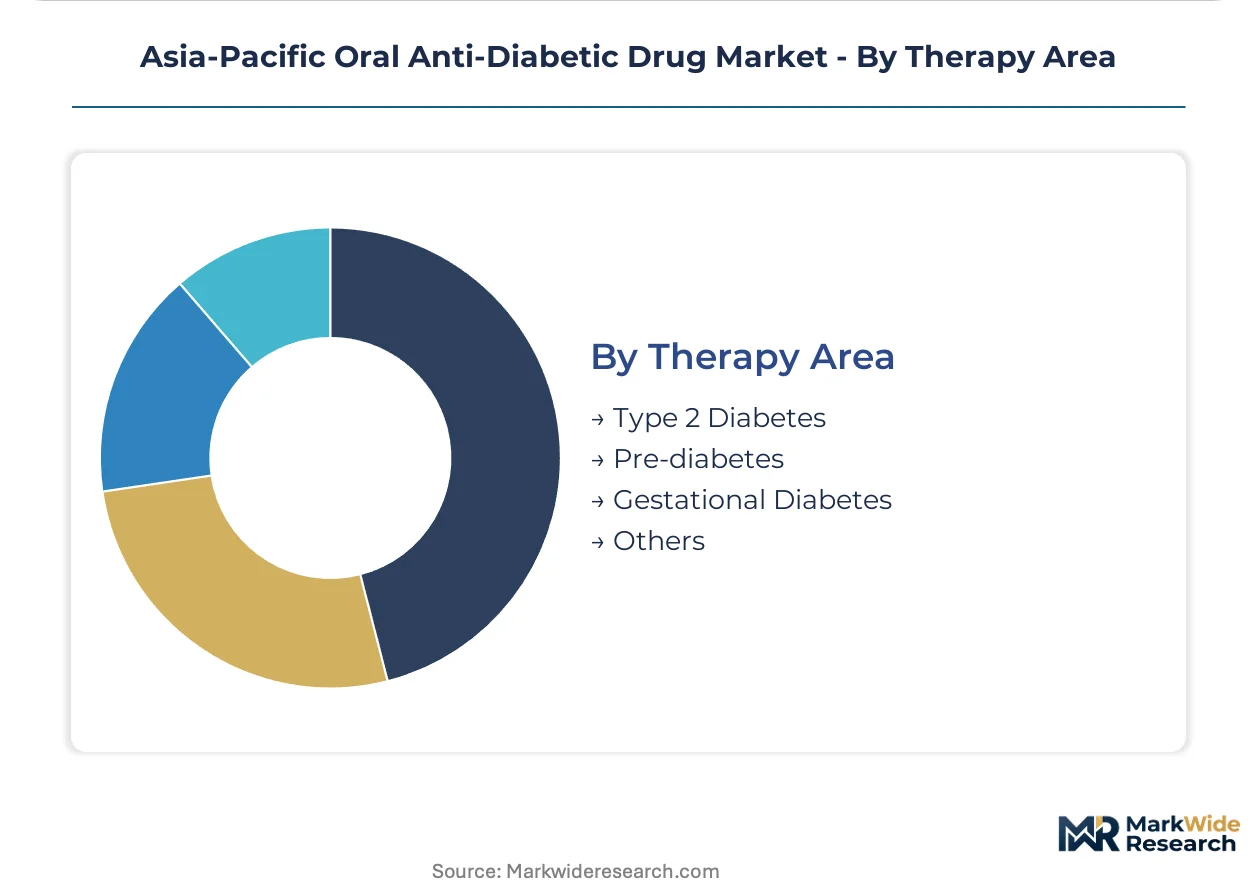
Therapy Area:
Clinical indication determines trial infrastructure requirements and regulatory evidence thresholds for market authorization.
- Type 2 Diabetes:The core indication drives cardiovascular outcome trial investment and post-market surveillance commitments across CDSCO, NMPA, and PMDA jurisdictions. India's hospital-based diabetes programs and China's tier-2 clinic expansion are concentrating prescription volume in markets with protocol-driven therapy selection.
- Pre-diabetes:Lifestyle intervention adjuvant therapy positioning requires distinct pharmacoeconomic evidence for payer acceptance in Australia's PBS and South Korea's HIRA frameworks.
- Gestational Diabetes:Pregnancy safety databases and teratogenicity studies constrain sponsor participation in this niche indication.
- Others:Off-label and emerging indications with limited formal trial infrastructure.
Type 2 diabetes commands the bulk of clinical development investment; pre-diabetes is expanding most quickly on prevention-focused healthcare policy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates API production for oral anti-diabetic drugs while India and Southeast Asian markets absorb the bulk of finished formulation consumption. Japan anchors premium-priced innovative therapy demand. Australia's reimbursement frameworks shape pricing benchmarks for regional exports.
China
Tier-2 cities including Chengdu, Wuhan, and Xi'an are driving outpatient prescription volume as provincial hospitals expand diabetes clinics. NMPA accelerated review pathways compress regulatory timelines for novel SGLT2 and DPP-4 molecules. The Yangtze River Delta concentration of fermentation-based API facilities supplies precursors for metformin and glimepiride across Asia-Pacific formulation plants.
India
Hospital-based diabetes management programs in Maharashtra and Karnataka are embedding clinical pharmacists into multidisciplinary care teams. CDSCO mandates for local bioequivalence data extend generic market entry timelines. Gujarat's Ahmedabad-Vadodara industrial corridor hosts contract manufacturing organizations specializing in immediate-release tablet lines for sulfonylurea production.
Japan
Kanto region endocrinology clinics prioritize cardiorenal outcome data in prescribing decisions for aging type 2 diabetes patients. PMDA conditional early approval pathways reward sponsors with pre-existing cardiovascular trial infrastructure. Osaka-based formulation specialists command premium positioning for extended-release matrix technologies aligned with geriatric adherence patterns.
Australia
Pharmacy benefit managers through PBS are tightening step-therapy protocols that shift prescribing influence from clinicians to centralized formulary committees. TGA bioequivalence requirements and mutual recognition agreements with MFDS standardize quality thresholds for regional export supply. Sydney and Melbourne hospital networks concentrate bulk procurement contracts for SGLT2 inhibitor formularies.
South Korea
Seoul Capital Area endocrinology practices are integrating continuous glucose monitoring data with oral therapy titration protocols. MFDS dissolution specifications and HIRA reimbursement controls are compressing brand loyalty windows for second-line therapy initiation. Busan-Ulsan manufacturing clusters supply extended-release formulations for export to Southeast Asian markets.
Asia-Pacific Oral Anti-Diabetic Drug Market Vendor Landscape
The competitive structure tilts toward multinational pharmaceutical conglomerates with established cardiorenal trial infrastructure. Japanese and European sponsors leverage PMDA conditional pathways and NMPA accelerated reviews to secure premium positioning, while Indian and Chinese manufacturers compete on API cost and generic formulation scale. Two archetypes dominate: innovation-focused developers with outcome-based labeling capabilities, and volume-driven generic houses with backward-integrated API supply. Capacity expansion in extended-release platforms and strategic partnerships for digital health integration represent the primary competitive vectors.
Among the innovation-focused tier, Sanofi and Takeda Pharmaceutical Company Limited exemplify archetypes built on regulatory expertise and specialized chemistry platforms. Sanofi occupies a position bridging insulin portfolio depth into complementary oral therapies across Southeast Asian hospital systems. Takeda anchors Japanese market presence through DPP-4 inhibitor specialization and PMDA relationship infrastructure. Novo Nordisk A/S sits within the diabetes-dedicated conglomerate archetype, representing the concentrated therapeutic focus that enables integrated care pathway positioning.
| Leading Market Players |
|---|
| Sanofi |
| Novo Nordisk A/S |
| Takeda Pharmaceutical Company Limited |
| Astellas Pharma Inc. |
| AstraZeneca |
| Eli Lilly and Company |
| Merck & Co Inc |
| Boehringer Ingelheim |
| Janssen Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Captive API production in Gujarat's Ahmedabad-Vadodara corridor anchors pricing power for Indian formulation manufacturers while exposing non-integrated competitors to Chinese import volatility. This backward integration choice separates margin-sustainable players from those tethered to spot-market precursor pricing.
Pricing Analysis
Margin tightening in generic sulfonylurea production reflects India's PLI scheme accelerating domestic metformin precursor supply. Three-tier pricing structure across originator SGLT2 inhibitors, licensed DPP-4 molecules, and commodity sulfonylureas stratifies by cardiovascular outcome labeling and CDSCO bioequivalence certification. Cost-down pressure on immediate-release tablets intensifies as China's tier-2 clinics drive volume procurement with formulary standardization. Hospital procurement committees exhibit highest price sensitivity; originator sponsors with PMDA conditional approvals command lowest sensitivity.
Supply Chain Analysis
Batch recall logistics for extended-release matrix failures flow through Osaka-based formulation specialists with validated temperature-controlled distribution. API supply concentrates in China's Yangtze River Delta fermentation clusters and India's Gujarat chemical synthesis corridor. Key inputs span stereoselective catalysts for SGLT2 chemistry, HPMC matrices for geriatric formulations, and gelatin shells for combination capsules. Single-source vulnerability in Chinese KSM supply for DPP-4 inhibitors threatens production schedules. Distribution runs through hospital procurement hubs in Bangkok, Jakarta, and Ho Chi Minh City with cold chain requirements for certain formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into fermentation-based API production represents the decisive upstream lever as India's PLI scheme reshapes competitive positioning around captive precursor supply.
For Market Incumbents: Deploy extended-release formulation platforms to defend premium positioning against generic erosion in Japan's aging demographic. Anchor manufacturing capacity in Busan-Ulsan clusters to capture Southeast Asian export demand while insulating against CDSCO import dependency scrutiny. Counter emerging Chinese CMO competition with PMDA relationship infrastructure and cardiovascular trial databases. For New Entrants and Emerging Players: Enter via liquid formulation specialization for pediatric and geriatric populations in Japan and Australia's PBS channels. Target tier-2 Chinese outpatient clinics with 30-day supply configurations where brand loyalty remains undeveloped. Pursue pharmacist-embedded diabetes management programs in Thailand and Vietnam as institutional formulary entry points. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier Indian manufacturers with CDSCO trial infrastructure and dormant API synthesis licenses. Long-term viability hinges on cardiorenal outcome trial capabilities and NMPA priority review access. Monitor PMDA conditional approval grant velocity as inflection indicator for innovative therapy premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | India's PLI scheme reduces Chinese KSM dependency for metformin and glimepiride precursors. |
| Extended-Release Platform Investment | Osaka formulation specialists capture geriatric adherence premiums in Japan's aging market. |
| NMPA Priority Review Pathway Access | Accelerated 130-day timelines enable faster SGLT2 market entry in China's tier-2 cities. |
| Continuous Glucose Monitoring Partnership | Data-linked prescribing ecosystems favor digital health-integrated manufacturers over pure suppliers. |
| Hospital Pharmacist Embedding Program | Thailand and Vietnam diabetes management protocols institutionalize oral therapy formulary placement. |
Methodological Framework
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings. Primary interviews with CDSCO compliance officers and PMDA submission specialists combined with secondary validation from FDA Orange Book filings, NMPA approval databases, ClinicalTrials.gov cardiovascular outcome studies, and hospital procurement contract records. Bottom-up prescription volume modeling and top-down API production capacity estimates triangulate market sizing.
Comparable-period anchoring to historical NMPA approval timelines and CDSCO bioequivalence study completion rates structures the forecast window across the analysis window. Segmentation dimensions span molecular platform, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derive from prescription volume growth trajectories in China's tier-2 cities, India's hospital program expansion, and Japan's geriatric demand shift. Forecast inputs incorporate SGLT2 cardiorenal outcome trial publication schedules and PLI scheme API capacity buildout curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA regulatory delay scenarios or Chinese API export restriction events. Practitioners should monitor PMDA conditional approval grant rates and India's PLI scheme disbursement velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Germany Continuous Glucose Monitoring Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
Next Generation Diabetes Therapy and Drug Delivery Market
Diabetes Care
Japan Insulin Infusion Pump Market