
 Japan Battery Market | 2026-2036
Japan Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Battery Market Foresight
The capability gap between vertically integrated cell producers and module assemblers is redrawing competitive boundaries in Japan. Panasonic Corporation leverages its in-house cathode material production to sustain cost advantages across cylindrical formats. GS Yuasa International Ltd anchors its position in lead-acid replacements for industrial backup systems while competing in next-generation sodium-ion development.
A battery electrochemically stores and releases energy through reversible redox reactions between anode and cathode materials separated by an electrolyte, with lithium-ion variants achieving energy densities exceeding 250 Wh/kg for automotive traction applications. Solid-state configurations replace flammable liquid electrolytes with ceramic or sulfide conductors to eliminate thermal runaway risks and enable higher voltage operation. Lithium-ion products dominate current manufacturing scale while solid-state technology attracts the fastest-growing R&D allocation. Automotive applications command the largest revenue pool, though renewable energy storage segments show expanding margin contribution from utility-scale deployments.
METI enforces domestic content requirements under the Battery Supply Chain Policy, while JIS standards govern cell safety testing protocols and the PMDA oversees medical device battery certifications. These frameworks compel manufacturers to localize production and upgrade quality systems. Stakeholders must track METI subsidy thresholds for gigafactory investments and anticipate how revised JIS thermal propagation tests will reshape product qualification timelines.
Market Dynamics
METI's Battery Supply Chain Policy is forcing domestic gigafactory localization while solid-state electrolyte research redirects R&D flows away from incumbent liquid-electrolyte formats. This dual pressure compresses legacy capacity planning horizons.
Growth Catalysts
- Automotive traction demand:Electric vehicle OEMs in the Kanto corridor are accelerating procurement of high-capacity cylindrical cells for next-generation platforms.
- METI subsidy thresholds:Domestic content requirements under the Battery Supply Chain Policy compel manufacturers to localize cathode material production and cell assembly.
- Solid-state electrolyte breakthroughs:Osaka-based research institutes are achieving ceramic conductor stability milestones that enable higher voltage operation.
Market Restraints
- Lithium carbonate volatility:Input cost swings from Chilean and Australian spodumene concentrate contracts compress margin predictability for cathode producers.
- Single-source sulfide supply:Solid-state electrolyte manufacturing depends on concentrated Japanese specialty chemical suppliers for lithium sulfide precursors.
- JIS thermal propagation timeline:Revised cell safety testing protocols extend product qualification cycles by six to nine months.
Strategic Opportunities
- Chiba prefecture industrial zones:Underutilized port infrastructure offers brownfield gigafactory sites with direct cathode material import access.
- Grid-scale storage integration:Utility operators in Tokyo and Kanagawa are procuring containerized battery systems for frequency regulation services.
- Sodium-ion chemistry convergence:Abundant domestic salt deposits enable cost-competitive alternatives for industrial backup applications.
Industry Challenges
- Solid-state manufacturing scale-up:Thin-film ceramic deposition requires vacuum equipment and cleanroom infrastructure absent from existing lithium-ion lines.
- Electrolyte chemist scarcity:Domestic universities produce insufficient sulfide conductor specialists to staff expanding R&D programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Battery Market |
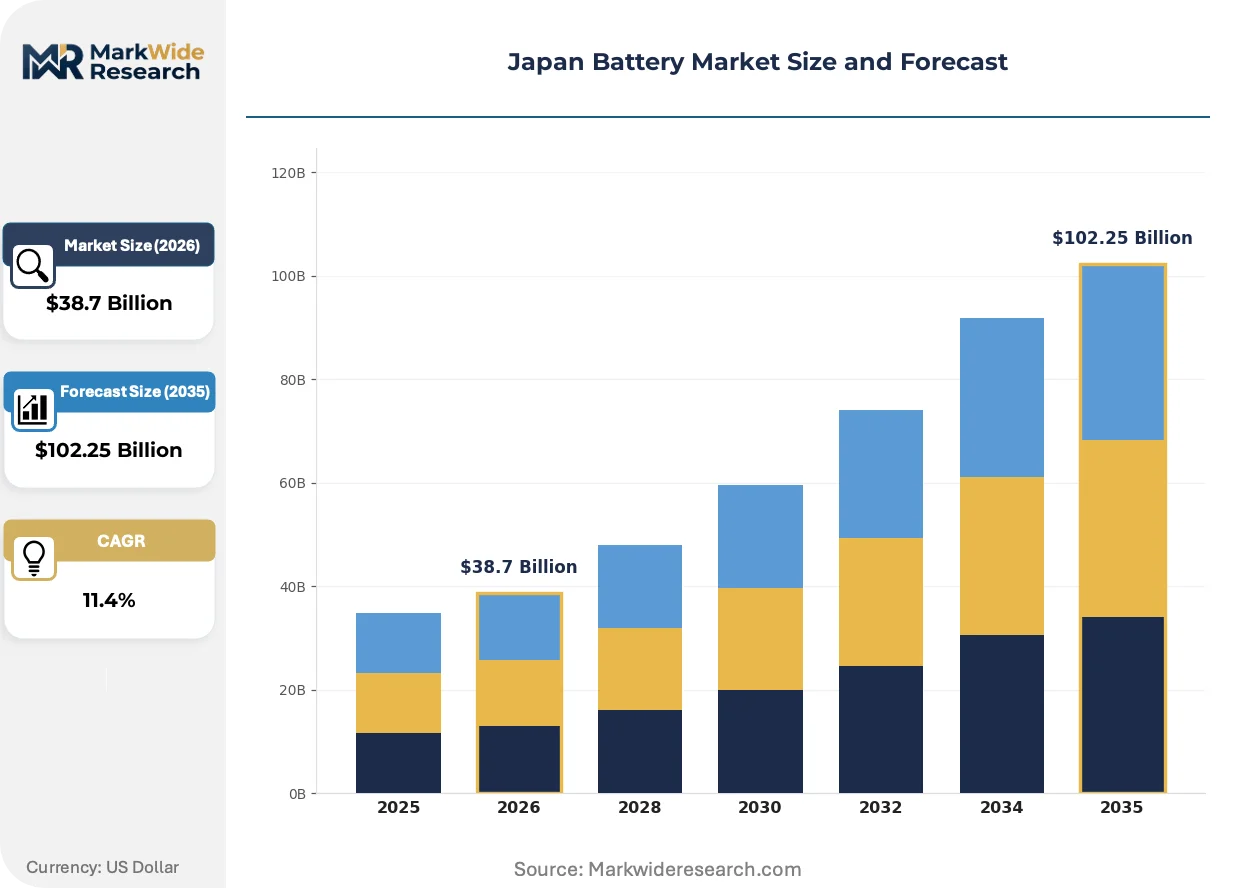
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state Application: Automotive, Consumer Electronics, Renewable Energy, Industrial Equipment End User: OEMs, Retailers, Utilities, Manufacturers Technology: Energy Storage, Fast Charging, Recycling, Smart Grids |
| Companies Covered | Panasonic Corporation, GS Yuasa International Ltd, NGK Insulators Ltd, Toshiba Corporation, Maxell Ltd, Sony Corporation, Hitachi Chemical Co., Ltd, Mitsubishi Electric Corporation, NEC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Battery Market Shifts & Advancements
Solid-state configurations are decomposing the liquid-electrolyte value chain while METI policy accelerates domestic manufacturing investment. Three forces are compressing legacy competitive positions.
Sulfide-based solid-state electrolytes are decomposing the flammable liquid electrolyte segment by eliminating thermal runaway risks. Automotive OEMs in Kanagawa and Tokyo prefectures are qualifying ceramic conductor cells for premium electric vehicle platforms. This chemistry shift is decomposing incumbent cylindrical format advantages by enabling prismatic and pouch geometries with higher packing density.
METI's Battery Supply Chain Policy mandates domestic content thresholds for gigafactory subsidy eligibility. Manufacturers must localize cathode active material production and cell assembly to qualify for investment support. The Kanto industrial corridor is capturing the majority of qualified projects as firms reconfigure supply chains to meet certification requirements.
Utility procurement is consolidating around long-term service agreements rather than equipment-only transactions. Tokyo-area grid operators are bundling battery hardware with fifteen-year performance guarantees and remote monitoring services. This contracting evolution is visible across Kanagawa and Chiba prefectures where regional utilities prioritize total cost of ownership over capital expenditure minimization.
Japan Battery Market Segmentation
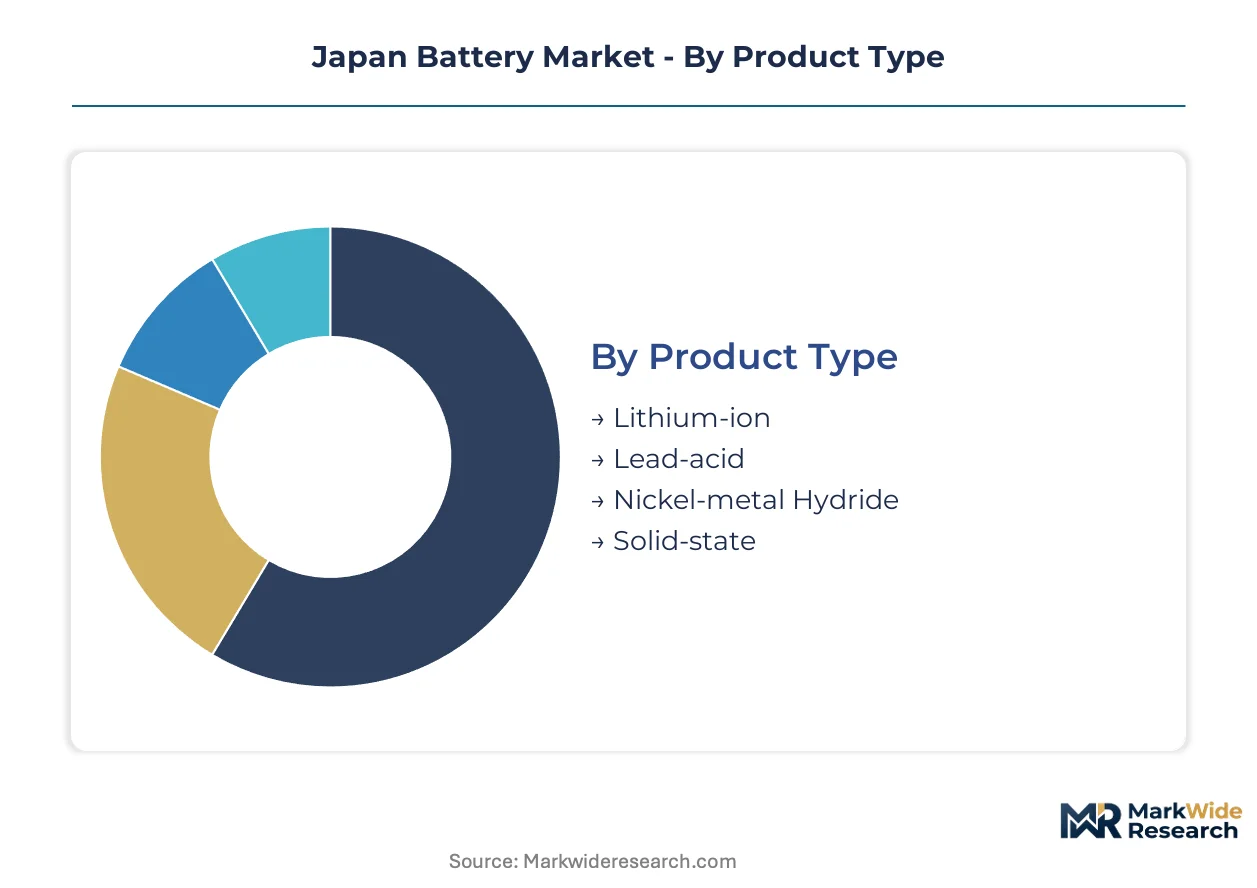
Segmentation in Japan's battery market reveals how chemistry transitions and application-specific performance requirements are fragmenting procurement patterns. Understanding these divides clarifies where substitution pressures and margin compression concentrate across the value chain.
Product Type:
Solid-state electrolytes are displacing liquid-electrolyte formats fastest in premium automotive applications, while lead-acid faces sodium-ion substitution in industrial backup systems.
- Lithium-ion:Dominant chemistry for automotive traction and consumer electronics, utilizing layered oxide cathodes and graphite anodes with energy densities exceeding 250 Wh/kg. Demand concentrates in Kanagawa and Tokyo prefectures where electric vehicle OEMs qualify cylindrical cells for next-generation platforms; METI domestic content requirements compel localized cathode production.
- Solid-state:Ceramic and sulfide electrolyte configurations eliminate thermal runaway risks while enabling higher voltage operation. Osaka-based research institutes are achieving stability milestones that attract R&D investment from automotive manufacturers in the Kanto corridor; thin-film deposition requirements constrain manufacturing scale-up.
- Lead-acid:Mature technology for starter batteries and uninterruptible power supplies with established recycling infrastructure.
- Nickel-metal Hydride:Hybrid electric vehicle applications and specialty industrial uses where proven safety records outweigh energy density requirements.
Lithium-ion retains volume leadership; solid-state holds the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive automotive qualification cycles from margin-thinner industrial equipment replacement markets.
- Automotive:Traction batteries for battery electric and hybrid electric vehicles, with cell formats optimized for pack integration and thermal management. Procurement concentrates among Kanto corridor OEMs accelerating high-capacity cylindrical cell sourcing; solid-state qualification timelines extend product development cycles.
- Renewable Energy:Grid-scale storage and residential solar-plus-battery systems requiring long cycle life and degradation warranties. Tokyo and Kanagawa utility operators are procuring containerized systems with fifteen-year performance guarantees; service bundling shifts contracting toward total cost of ownership metrics.
- Consumer Electronics:Smartphones, laptops, and portable devices demanding high energy density in compact form factors.
- Industrial Equipment:Forklifts, backup power systems, and material handling equipment where operational uptime priorities dominate procurement.
Automotive commands premium pricing tiers; renewable energy is gaining share fastest in utility procurement portfolios.
End User:
Customer type determines contracting structure, with utilities demanding long-term service agreements and OEMs prioritizing cell qualification speed.
- OEMs:Automotive and electronics manufacturers integrating cells into finished products, requiring JIS certification and METI subsidy compliance for supply chain localization.
- Utilities:Grid operators in Tokyo, Kanagawa, and Chiba prefectures procuring frequency regulation and peak shaving capacity through performance-based contracts.
- Retailers:Consumer-facing channels for replacement batteries and aftermarket products.
- Manufacturers:Industrial firms sourcing backup power systems and motive power equipment.
OEMs drive chemistry innovation requirements; utilities are expanding procurement fastest through bundled service models.
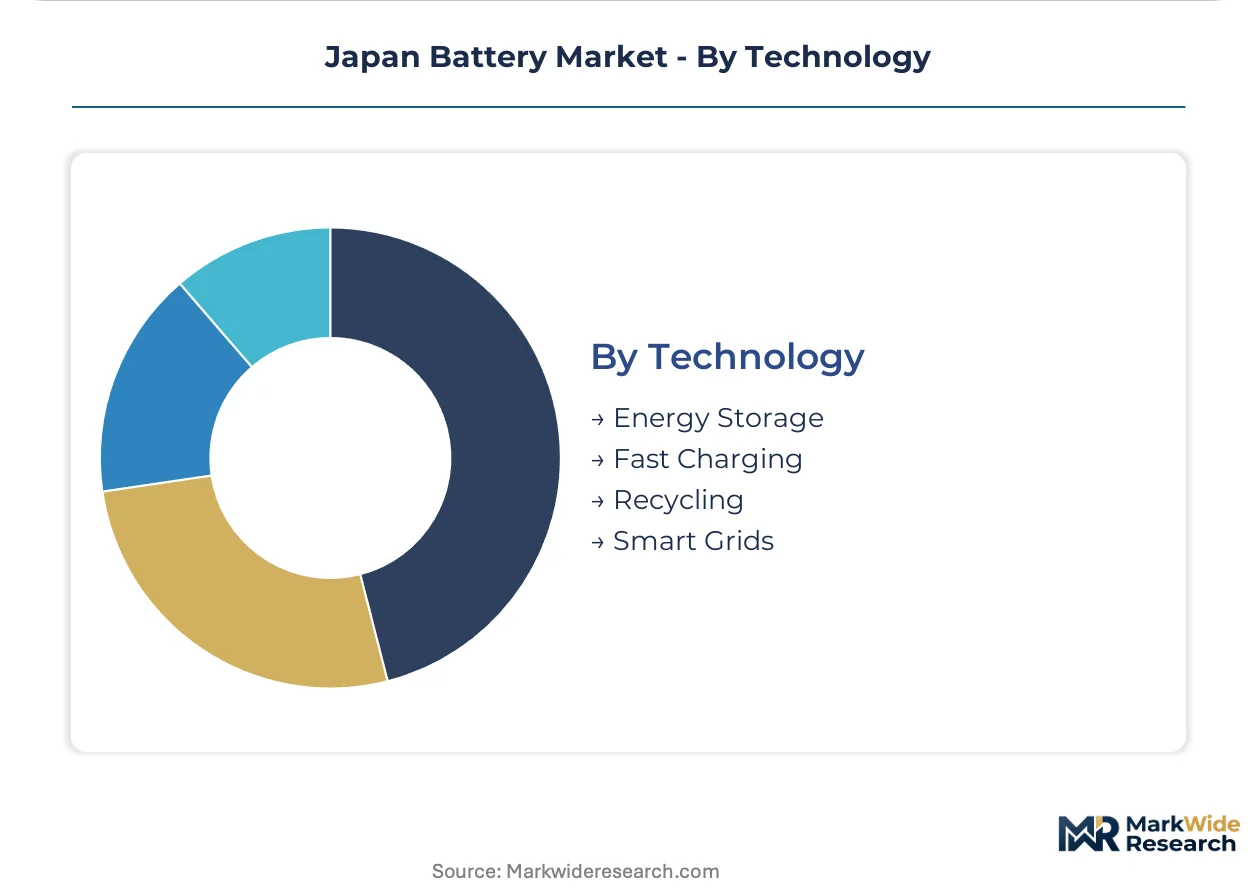
Technology:
Maturity gradients separate commercialized energy storage systems from emerging fast charging and smart grid integration capabilities.
- Energy Storage:Core electrochemical systems for stationary and mobile applications, with lithium-ion dominating current manufacturing scale.
- Fast Charging:Cell architectures and thermal management enabling rapid energy replenishment without accelerated degradation.
- Recycling:Hydrometallurgical and pyrometallurgical recovery of lithium, cobalt, and nickel from end-of-life batteries.
- Smart Grids:Battery management systems and communication protocols enabling demand response and grid stabilization services.
Energy storage anchors current revenue; smart grids are climbing the fastest as utility digitalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility buyers in Tokyo and Kanagawa prefectures exhibit low price elasticity for grid-scale storage, while industrial equipment purchasers in peripheral prefectures remain highly sensitive to upfront capital costs. This demand-elasticity contrast shapes regional investment flows and subsidy allocation priorities across Japan's battery market.
Kanto (Tokyo, Kanagawa, Chiba)
Automotive OEMs in this corridor are accelerating procurement of high-capacity cylindrical cells for next-generation electric vehicle platforms. METI's Battery Supply Chain Policy mandates domestic content thresholds that compel manufacturers to localize cathode material production and cell assembly. The Keihin industrial zone spanning Kawasaki and Yokohama is capturing qualified gigafactory projects as firms reconfigure supply chains to meet certification requirements.
Kansai (Osaka, Kyoto, Hyogo)
Research institutes in Osaka are achieving ceramic conductor stability milestones that enable higher voltage operation for solid-state configurations. JIS standards govern cell safety testing protocols for manufacturers qualifying products through regional certification bodies. The Osaka Science and Technology Center is redirecting R&D flows away from incumbent liquid-electrolyte formats toward sulfide-based electrolyte development.
Chubu (Aichi, Gifu, Shizuoka)
Automotive component suppliers in Aichi prefecture are integrating battery management systems for hybrid electric vehicle applications. The region's manufacturing base benefits from proximity to Toyota City and Nagoya's industrial infrastructure. Suppliers here face compressed legacy capacity planning horizons as solid-state qualification timelines extend product development cycles.
Kyushu (Fukuoka, Saga, Nagasaki)
Industrial backup system demand concentrates in Fukuoka prefecture where manufacturing facilities require uninterruptible power supply reliability. Regional utilities are procuring containerized battery systems for frequency regulation services under long-term service agreements. The Ariake Sea coastal industrial zone offers underutilized port infrastructure with direct cathode material import access.
Tohoku (Miyagi, Fukushima, Iwate)
Renewable energy storage deployments are expanding across Fukushima prefecture following grid reconstruction investments. Utility operators are bundling battery hardware with fifteen-year performance guarantees and remote monitoring services. The Sendai coastal industrial corridor is attracting brownfield gigafactory sites seeking lower land costs than Kanto alternatives.
Japan Battery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japan's battery market structure. Vertically integrated cell producers with in-house cathode material production command cost advantages across cylindrical formats, while module assemblers without upstream chemical capabilities face margin compression. Three archetypes dominate: integrated materials-to-cells conglomerates, specialty chemical suppliers for solid-state electrolytes, and industrial backup system providers. Competitive moves center on backward integration into cathode active material production and strategic partnerships with automotive OEMs for platform qualification.
Among Japan-based integrated manufacturers, Panasonic Corporation, GS Yuasa International Ltd, and Toshiba Corporation occupy positions across different chemistry and application tiers. Panasonic exemplifies the vertically integrated archetype with captive cathode production capabilities. GS Yuasa represents the diversified industrial specialist segment spanning lead-acid replacements and next-generation chemistry development. Toshiba sits within the technology licensing tier, leveraging legacy electronics manufacturing expertise for energy storage system integration. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Panasonic Corporation |
| GS Yuasa International Ltd |
| NGK Insulators Ltd |
| Toshiba Corporation |
| Maxell Ltd |
| Sony Corporation |
| Hitachi Chemical Co., Ltd |
| Mitsubishi Electric Corporation |
| NEC Corporation |
| Others |
Supply & Pricing Matrix
Solid-state electrolyte substitution for liquid-electrolyte formats is simultaneously redrawing cathode material sourcing geography and compressing legacy pricing economics across cylindrical cell tiers. Lithium sulfide precursor procurement from Osaka-based specialty chemical suppliers now commands premium positioning as automotive OEMs in Kanagawa and Tokyo prefectures qualify next-generation platforms.
Pricing Analysis
After-sales service bundling with fifteen-year performance guarantees drives lifetime value differentiation for utility-scale deployments. Three-tier pricing structure across premium automotive traction, standard industrial backup, and economy consumer electronics segments reflects JIS certification tiers and cathode material localization status. Cost compression in cylindrical formats intensifies as METI domestic content requirements force cathode active material production shifts. Industrial equipment purchasers in peripheral prefectures exhibit highest price sensitivity, while Tokyo-area grid operators prioritize total cost of ownership over capital expenditure minimization.
Supply Chain Analysis
Container availability constraints on Australia-Japan and Chile-Japan trade lanes elevate inbound logistics costs for spodumene concentrate and lithium carbonate feedstocks. Manufacturing scale draws from Australia, Chile, and domestic Japanese specialty chemical producers for lithium compounds, nickel sulfate, and cobalt precursors. Single-source sulfide supply from concentrated Japanese lithium sulfide producers creates vulnerability exposure for solid-state electrolyte manufacturing. Distribution runs through qualified gigafactory sites in the Kanto industrial corridor with direct port access for cathode material imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sulfide conductor specialist shortage constrains R&D program staffing and manufacturing scale-up velocity across solid-state electrolyte development pipelines. This capability gap separates integrated materials-to-cells conglomerates from module assemblers facing margin compression.
For Market Incumbents: Shield cylindrical format advantages by accelerating captive cathode active material production in Chiba prefecture industrial zones. Secure JIS thermal propagation certification ahead of revised protocol timelines to compress competitor qualification cycles. Solid-state electrolyte breakthroughs from Osaka-based research institutes threaten legacy liquid-electrolyte positioning.
For New Entrants and Emerging Players: Anchor in sodium-ion chemistry convergence for industrial backup applications where abundant domestic salt deposits enable cost-competitive positioning against lead-acid incumbents. Target underpenetrated grid-scale storage procurement in Tohoku region utility operators bundling long-term service agreements. Qualify through regional certification bodies with accelerated JIS compliance pathways.
For Investors and Strategic Acquirers: METI Battery Supply Chain Policy subsidy threshold revisions reshape the acquisition landscape toward gigafactory assets with domestic content qualification. Five-to-ten year viability hinges on backward integration into cathode material production rather than pure cell assembly exposure. Monitor Osaka-based ceramic conductor stability milestones as inflection signal for solid-state manufacturing scale-up feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Localization | METI subsidy eligibility compels domestic production shifts in Kanto corridor zones. |
| Solid-State Electrolyte Scale-Up | Thin-film ceramic deposition requires vacuum equipment absent from existing lithium-ion lines. |
| Utility Service Contract Bundling | Tokyo-area grid operators prioritize fifteen-year performance guarantees over equipment-only transactions. |
| Sodium-Ion Chemistry Development | Domestic salt deposits enable cost-competitive industrial backup system substitution. |
| JIS Certification Pre-Positioning | Revised thermal propagation protocols extend qualification cycles by six to nine months. |
Research Methodology
A spread of perspectives from battery platform engineers at Kanto corridor OEMs, cathode material procurement leads, utility planning officers in Tokyo and Kanagawa, and solid-state electrolyte R&D directors converged on the working assumptions. Primary fieldwork combined with secondary validation from METI policy filings, JIS standard revision notices, customs trade data for lithium compound imports, and Osaka Science and Technology Center research disclosures. Bottom-up cell demand modeling and top-down gigafactory investment tracking provided triangulation anchors.
Segmentation dimensions modeled include chemistry type, application tier, end-user contracting structure, and regional regulatory cluster across the projection horizon. CAGRs derived from installed capacity buildout trajectories and cathode material localization timelines. Forecast inputs incorporated METI subsidy threshold compliance rates and solid-state electrolyte manufacturing yield assumptions.
Material uncertainties — lithium carbonate spot price volatility, JIS protocol revision timing, and sulfide conductor specialist labor availability — sit outside the modeled envelope. Forecasts reflect documented assumptions about ceramic deposition equipment delivery schedules and utility procurement contract conversion rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Semi-Solid Flow Battery Market
Batteries
Battery Cases Market
Batteries
Automotive AGM Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
East Europe Battery Market
Batteries
Proton Battery Market
Batteries
USA Forklift Battery Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Portable Battery Station Market
Batteries
Battery Pack Balancer Market
Batteries
North America NMC Battery Pack Market
Batteries
United Kingdom SLI Battery Market
Batteries
Drone Power Sources Market
Batteries
Military Battery Packs Market
Batteries
Secondary Battery Market
Batteries
Printable Battery Market