
 North America Glass Packaging Market | 2026-2036
North America Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Glass Packaging Market Analytics
The premium-commodity divide in North American glass packaging is hardening around aesthetic complexity, batch minimums, and decoration tolerance. O-I Glass Inc. dominates furnace-scale production across multiple US states, sustaining cost leadership through backward integration into cullet processing. Ardagh Group competes through lightweighting technology leadership, while Gerresheimer AG anchors pharmaceutical-grade borosilicate demand with exacting dimensional certification.
North America glass packaging comprises silica-soda-lime formulations, typically containing 60-75% silicon dioxide, manufactured through continuous float or batch furnace processes and valued for inertness, impermeability, and infinite recyclability. Bottles lead volume across food and beverage applications, though pharmaceutical vials command superior margin pools due to USP Type I/III compliance requirements. Jars occupy mature positions in preserves and sauces, while custom shapes in personal care extract pricing premiums through proprietary mold investments.
The FDA governs food-contact glass under 21 CFR 175.300, while EPA recycling mandates under the Resource Conservation and Recovery Act shape post-consumer cullet availability; Canada aligns through Health Canada and PMRA frameworks with cross-border harmonization pressure. OSHA silica exposure rules tighten furnace operations economics, particularly for smaller independent producers. Stakeholders must monitor state-level extended producer responsibility legislation spreading from Maine and California toward mid-Atlantic jurisdictions, as these programs will restructure collection cost allocation between brand owners and converters.
Market Dynamics
The North America glass packaging market is being reshaped by the collision of extended producer responsibility mandates spreading from Maine and California against furnace-scale consolidation around the Great Lakes and Ohio River Valley cullet corridors.
Growth Catalysts
- FDA recycled content mandates:The FDA's enforcement of 21 CFR 175.300 for food-contact glass is compelling brand owners to certify post-consumer cullet streams, expanding demand for pharmaceutical-grade amber and flint containers.
- Craft beverage cluster density:Microdistilleries and craft breweries in the Northeast corridor are specifying custom mold shapes and embossed decoration to differentiate shelf presence, pulling premium glass volumes.
- Lightweighting process advances:NNPB (narrow-neck press-and-blow) technology adoption is reducing per-unit silica consumption by 25-30% while maintaining dimensional tolerance for carbonated applications.
Market Restraints
- Natural gas price volatility:Furnace operations in Ontario and Pennsylvania face margin compression from input energy cost swings, with gas representing 35-40% of melt economics.
- Silica sand supply concentration:High-purity silica deposits in Wisconsin and Illinois are controlled by limited mining permits, creating geographic chokepoints for container-grade feedstock.
- Aluminum can substitution:Beverage brands are migrating single-serve formats to aluminum for logistics efficiency, compressing glass demand in sub-12-ounce categories.
Strategic Opportunities
- Canadian EPR expansion:Ontario and British Columbia are implementing producer-funded collection systems that will restructure cullet economics and create captive supply advantages for integrated converters.
- Pharmaceutical serialization convergence:Track-and-trace mandates for USP Type I borosilicate vials are creating demand for laser-etched 2D codes and unit-level authentication.
- Direct-to-consumer wine channels:Winery subscription models are specifying lightweight, breakage-resistant bottles with premium aesthetic finishes, bypassing traditional distributor specifications.
Industry Challenges
- Silica exposure compliance:OSHA respirable crystalline silica rules are forcing furnace rebuilds and ventilation upgrades, extending capex cycles for independent producers.
- USP dimensional certification timelines:Pharmaceutical customers require 18-24 month validation periods for new mold sets, compressing product development windows.
- Legacy furnace reconfiguration:Converting soda-lime lines to borosilicate or amber production requires 8-12 week changeover periods, constraining operational flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Glass Packaging Market |
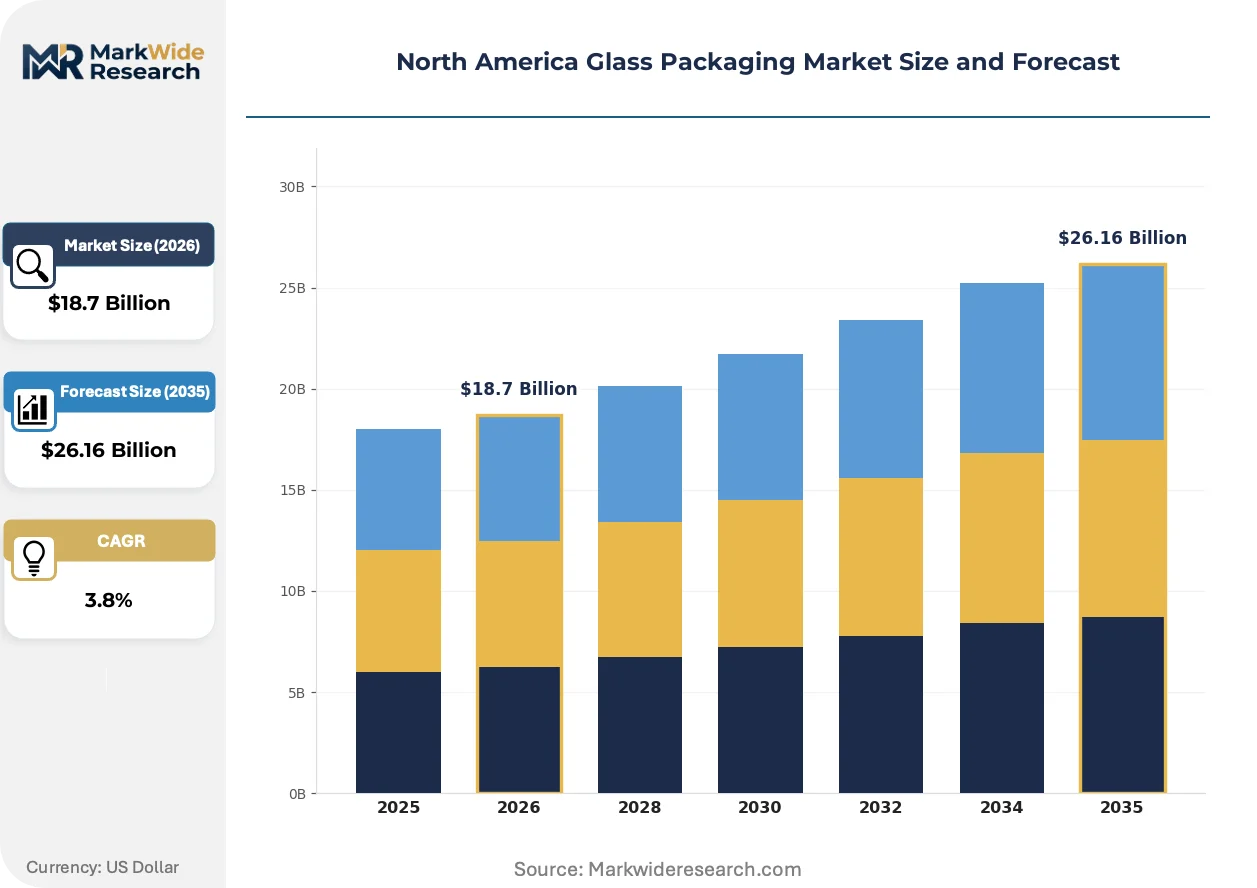
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tumblers End User: Food & Beverage, Personal Care, Pharmaceuticals, Chemicals Shape: Round, Square, Rectangular, Custom Capacity: Below 200ml, 200ml-1L, 1L-5L, Above 5L |
| Companies Covered | O-I Glass Inc., Ardagh Group, Gerresheimer AG, Amcor Plc, AptarGroup, BA Glass BV, Berlin Packaging LLC, Kaufman Container, WestPack LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Glass Packaging Market Evolving Landscape
Electrification of melt operations, regulatory tightening on chemical leaching, and procurement centralization by multinational beverage brands are converging to transform competitive requirements across the value chain.
Plasma-assisted melting technology is decentralizing furnace economics by enabling smaller-batch production with 40% lower energy intensity than conventional regenerative furnaces. Premium spirits brands in Kentucky and Tennessee are piloting these systems for limited-release expressions. The technology is decentralizing geographic production constraints that previously favored Ohio River Valley concentration.
The EPA's Resource Conservation and Recovery Act enforcement is tightening post-consumer cullet specifications for food-contact applications. Melt facilities in Pennsylvania and New York must now document chain-of-custody for 70%+ recycled content claims. Pharmaceutical vial manufacturers are responding by qualifying dedicated flint streams separate from commingled municipal collection.
Centralized procurement by multinational beverage conglomerates is compressing supplier rosters and mandating lightweighting roadmaps with annual gram-reduction targets. These buyers are consolidating mold ownership and specification control, displacing regional converter autonomy. The shift is most visible in California and Texas, where two-brand concentration exceeds 60% of volume.
North America Glass Packaging Market Segmentation
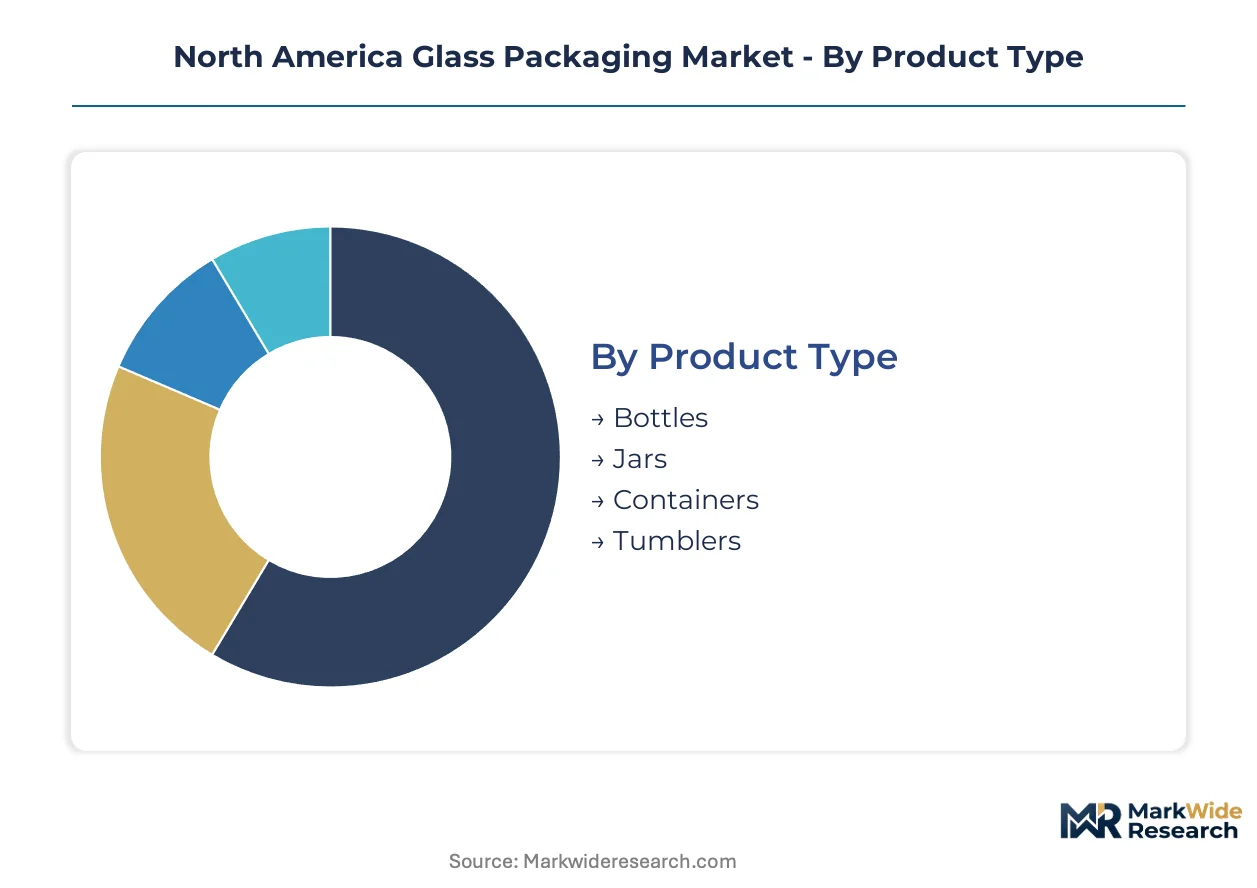
Glass packaging segmentation in North America reflects divergent technical requirements across furnace-scale production and specialized pharmaceutical certification. Specification tiers separate commodity soda-lime containers from borosilicate vials demanding USP Type I/III compliance, with each tier commanding distinct margin pools and validation timelines.
Product Type:
Silica-soda-lime formulations dominate furnace output, though dimensional tolerance and decoration complexity stratify commercial positioning across the four primary formats.
- Bottles:Continuous neck finish designs with NNPB lightweighting capability support carbonated beverage pressure requirements. Demand concentrates in Kentucky and Tennessee distilleries specifying embossed shoulders and proprietary punt designs for shelf differentiation.
- Jars:Wide-mouth configurations with lug or continuous thread finishes accommodate viscous food products. Mature demand sits with preserves and sauce processors in Pennsylvania and Ohio seeking 63mm and 70mm standard finishes.
- Containers:Rectangular and oblong profiles optimize pallet density for logistics-intensive categories. Chemical and pharmaceutical end-users in New Jersey and Massachusetts drive specification for amber and cobalt UV-blocking variants.
- Tumblers:Straight-wall cylindrical forms with fire-polished rims serve candle and personal care applications. Premium cosmetic brands in California specify heavy-base designs with silk-screen decoration.
Mature deployment sits with bottles. Newer deployment is concentrated in custom-profile containers for pharmaceutical serialization.
End User:
Regulatory intensity and procurement scale separate the four demand verticals, with FDA 21 CFR 175.300 compliance creating distinct entry barriers.
- Food & Beverage:The largest volume vertical spanning craft breweries, wineries, and sauce processors. Massachusetts and New York clusters specify flint and amber glass with 70%+ post-consumer cullet content under EPA RCRA mandates.
- Personal Care:Premium fragrance and skincare brands commission proprietary mold shapes with applied ceramic labeling. California and Texas house the densest brand-owner concentration.
- Pharmaceuticals:USP Type I borosilicate and Type III soda-lime vials demand 18-24 month mold validation cycles. New Jersey and North Carolina pharmaceutical corridors anchor this highest-margin segment.
- Chemicals:Industrial reagent and solvent packaging requires chemical resistance certification and UN-rated closures. Texas and Louisiana petrochemical proximity shapes regional demand.
Volume leadership belongs to food and beverage. Margin expansion is climbing the fastest in pharmaceutical-grade borosilicate.
Shape:
Mold investment requirements and decoration feasibility stratify the four geometric categories, with custom tooling amortization determining minimum viable batch sizes.
- Round:Rotationally symmetric profiles minimize mold complexity and maximize furnace output efficiency. Standard wine and spirits bottles across California and Washington utilize this lowest-cost geometry.
- Square:Quadrilateral profiles improve pallet cube utilization for logistics-intensive categories. Olive oil and specialty food processors in California specify these for retail shelf efficiency.
- Rectangular:Elongated profiles with rounded corners accommodate label expansion and handling ergonomics. Personal care brands in New York and New Jersey favor this for premium cosmetic lines.
- Custom:Proprietary contours requiring dedicated mold sets and extended validation timelines. Kentucky bourbon distilleries and Texas craft spirits producers commission these for trademark silhouette protection.
Round shapes capture standard-volume deployment. Custom geometries are gaining share fastest among premium spirits differentiation strategies.
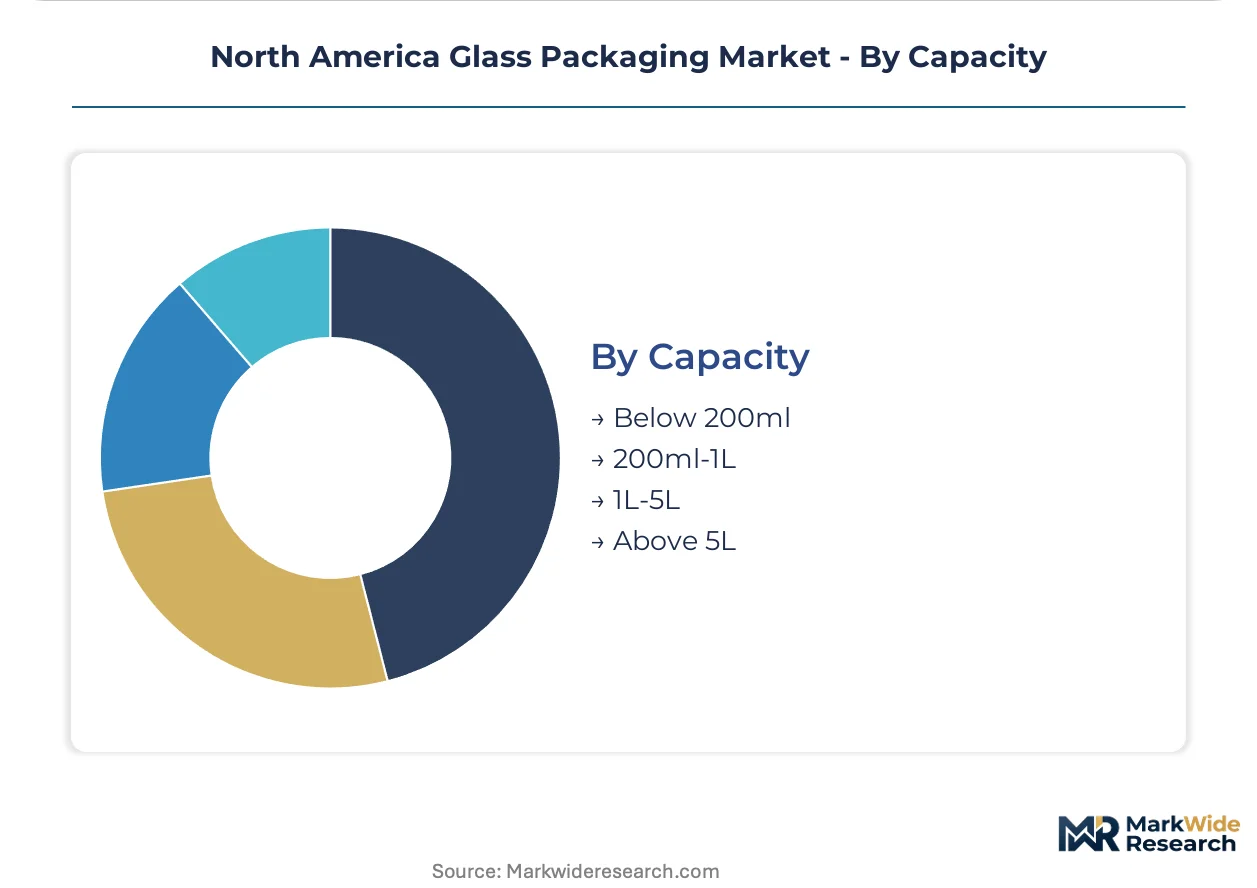
Capacity:
Fill-line compatibility and distribution economics segment the four volume tiers, with lightweighting roadmaps targeting specific gram-per-ml targets within each band.
- Below 200ml:Miniature formats for spirits samples, pharmaceutical vials, and cosmetic ampoules. New Jersey pharmaceutical serialization mandates drive 2D code integration in this tier.
- 200ml-1L:The core beverage and food range spanning standard wine bottles, sauce jars, and condiment containers. California and Oregon wineries dominate specification authority.
- 1L-5L:Family-size and foodservice formats with reinforced shoulders and heavier gram weights. Institutional food processors in Illinois and Ohio specify these for commercial kitchen durability.
- Above 5L:Bulk chemical and industrial formats with handle integration and UN certification requirements. Texas chemical corridor and California wine bulk storage anchor this niche tier.
Standard deployment centers on 200ml-1L formats. Above-5L industrial containers are expanding most quickly in chemical logistics optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ohio River Valley corridor spanning Kentucky, Ohio, and Pennsylvania anchors North American glass packaging production, with furnace-scale capacity clustering near recycled cullet processing infrastructure and natural gas pipeline networks.
United States
Kentucky bourbon distilleries and Tennessee craft spirits producers are commissioning custom mold shapes with embossed shoulders for shelf differentiation. The FDA enforces 21 CFR 175.300 for food-contact glass certification, compelling brand owners to document post-consumer cullet streams. Pennsylvania and New York melt facilities must now verify chain-of-custody for recycled content claims under EPA Resource Conservation and Recovery Act mandates.
Canada
Ontario and British Columbia are implementing producer-funded collection systems that will restructure cullet economics for integrated converters. Health Canada aligns pharmaceutical glass standards with FDA frameworks, creating cross-border harmonization pressure for USP Type I borosilicate certification. The Quebec-Ontario corridor houses pharmaceutical vial demand clusters serving Montreal and Toronto biopharma manufacturing.
Mexico
Baja California and central Mexico beverage bottlers are expanding flint and amber glass capacity to serve US export markets. The country's national environmental regulator is tightening post-consumer collection targets for glass packaging waste streams. Monterrey industrial parks attract furnace investments from multinational converters seeking NAFTA-advantaged supply positioning.
North America Glass Packaging Market Competitive Landscape
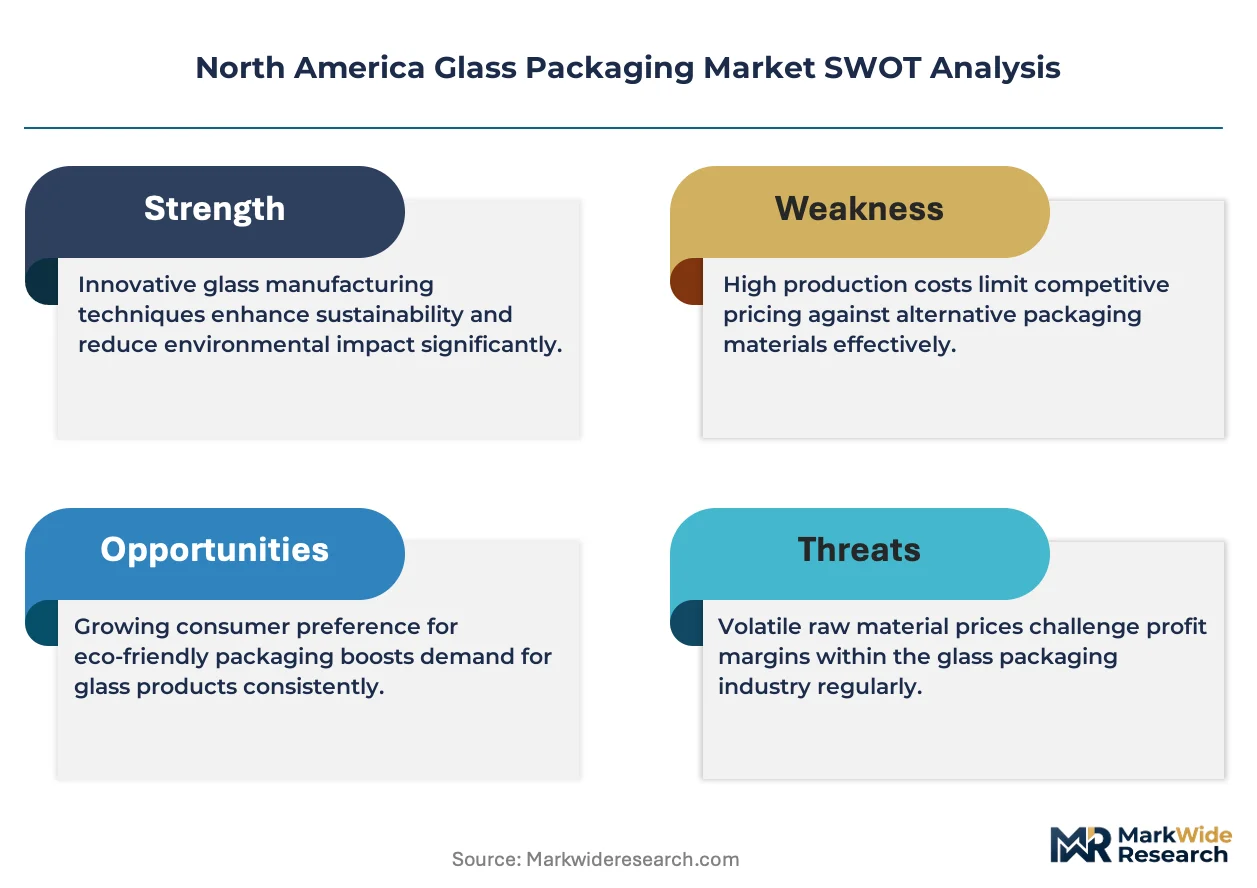
Premium-margin players sit above commodity-margin players across certification complexity, with pharmaceutical-grade borosilicate commanding superior returns against standard soda-lime container formats. The market structure consolidates around furnace-scale producers with backward integration into cullet processing, while independent converters face margin compression from energy cost volatility and silica exposure compliance burdens. Three archetypes dominate: integrated furnace operators with captive recycled feedstock, lightweighting technology specialists, and pharmaceutical certification leaders with exacting dimensional validation capabilities. Competitive moves center on strategic partnerships for EPR program participation and capacity reconfiguration toward amber and borosilicate production lines.
Within the integrated furnace tier, O-I Glass Inc. and Ardagh Group exemplify scale-driven operators with multi-state production footprints. Gerresheimer AG occupies a position among pharmaceutical certification leaders, anchoring USP Type I/III compliance demand with borosilicate specialization. These three entities represent the dominant competitive archetypes shaping procurement consolidation and lightweighting roadmap mandates from multinational beverage brand owners.
| Leading Market Players |
|---|
| O-I Glass Inc. |
| Ardagh Group |
| Gerresheimer AG |
| Amcor Plc |
| AptarGroup |
| BA Glass BV |
| Berlin Packaging LLC |
| Kaufman Container |
| WestPack LLC |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade borosilicate certification creates a steep value ladder that separates USP Type I/III compliant producers from commodity soda-lime converters, with each rung demanding distinct furnace investments, validation timelines, and captive cullet streams that reshape both margin capture and geographic sourcing decisions across the United States and Canada.
Pricing Analysis
USP Type I dimensional certification anchors value-based pricing for pharmaceutical vial manufacturers serving New Jersey and North Carolina biopharma corridors. Three-tier pricing structure across premium borosilicate, standard amber, and economy flint soda-lime separates margin pools by validation burden and chemical leaching tolerance. Cost compression in commodity flint bottles is intensifying because natural gas volatility erodes melt economics for independent Pennsylvania and Ontario producers. Mass-market beverage brand owners exhibit highest price sensitivity, while pharmaceutical procurement committees prioritize batch consistency over unit cost.
Supply Chain Analysis
Skilled furnace operators and mold technicians concentrate in the Ohio River Valley corridor spanning Kentucky, Ohio, and Pennsylvania, where generational glassmaking expertise anchors production quality. High-purity silica sand from Wisconsin and Illinois, natural gas from Appalachian pipeline networks, and post-consumer cullet from Northeast municipal collection systems feed furnace operations. Single-source vulnerability sits with limited silica mining permits controlled by state environmental regulators. Distribution runs through rail-served converter warehouses positioned within 500 miles of major beverage and pharmaceutical demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American glass packaging functions as a cost-of-compliance market where FDA 21 CFR 175.300 enforcement and EPA RCRA mandates erect regulatory moats that favor incumbents with validated cullet streams and certified furnace operations.
For Market Incumbents: Anticipate aluminum can substitution pressure in sub-12-ounce beverage formats by accelerating lightweighting roadmaps and securing exclusive mold ownership contracts with Kentucky and Tennessee distilleries. Backward integration into Ontario and British Columbia EPR-funded collection systems will lock in captive cullet supply before producer-funded programs reshape feedstock economics.
For New Entrants and Emerging Players: Enter via plasma-assisted melting technology pilots serving premium spirits limited-release expressions, where smaller-batch production bypasses Ohio River Valley furnace-scale concentration. Pharmaceutical serialization infrastructure for USP Type I borosilicate vials offers the most penetrable white-space, given 18-24 month validation timelines that deter rapid incumbent response. A direct-to-customer winery channel go-to-market angle bypasses consolidated distributor gatekeepers.
For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical certification specialists with USP Type I/III validation capabilities and established New Jersey biopharma customer relationships. Long-term viability favors converters with operational flexibility to reconfigure soda-lime lines toward amber and borosilicate production. Watch OSHA silica exposure rule enforcement timelines as a signal for forced furnace upgrade cycles that will compress independent producer margins and accelerate consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Roadmap | NNPB process adoption reduces per-unit silica consumption while maintaining carbonated beverage pressure tolerance for Kentucky distilleries. |
| EPR Program Participation | Ontario and British Columbia producer-funded collection systems restructure cullet economics toward integrated converters with captive supply. |
| Pharmaceutical Serialization Investment | Laser-etched 2D code integration for USP Type I borosilicate vials meets New Jersey track-and-trace mandates for unit-level authentication. |
| Plasma-Assisted Melting Pilot | Decentralized furnace technology enables premium spirits limited-release production with lower energy intensity outside Ohio River Valley concentration. |
| Borosilicate Line Reconfiguration | Furnace conversion from soda-lime to amber or borosilicate production captures pharmaceutical margin pools despite 8-12 week changeover constraints. |
Research Methodology
Independent corroboration across furnace operator interviews, pharmaceutical procurement manager discussions, and regulatory affairs director consultations underwrites the qualitative findings. Primary fieldwork captured perspectives from plant engineers at Ohio River Valley melt facilities, category buyers at Massachusetts craft beverage clusters, and Health Canada compliance officers. Secondary validation drew from EPA RCRA enforcement documentation, FDA 21 CFR 175.300 guidance filings, and state-level extended producer responsibility legislative tracking. Bottom-up volume modeling triangulated against top-down value estimates from customs and trade data.
Comparable-period anchoring to historical production and demand patterns established baseline trajectories across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, geometric shape, and capacity tier alongside furnace technology generation and cullet source certification status. CAGRs derived from regression analysis of volume and value outputs, with natural gas price volatility and silica sand permit availability as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EPR program rollout or unplanned OSHA silica rule enforcement. Forecasts reflect assumptions documented in furnace capacity utilization rates, pharmaceutical validation timeline distributions, and craft beverage cluster expansion plans. A small set of triggers—including Canadian EPR implementation speed, lightweighting technology adoption curves, and aluminum substitution thresholds in single-serve formats—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Israel Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
India Container Glass Market
Glass Packaging
Portugal Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Philippines Container Glass Market